
 Global Fresh Compressed Yeast Market | 2026-2036
Global Fresh Compressed Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fresh Compressed Yeast Market Analysis
Multi-source procurement among industrial bakeries is realigning how yeast suppliers secure raw molasses and sugar beet feedstock. Lesaffre leverages its vertically integrated fermentation network across multiple continents. Lallemand Inc. competes through specialized strain development for cold-weather dough performance. Angel Yeast Co., Ltd. anchors volume supply to Asia-Pacific food manufacturers through distributed production facilities.
Fresh compressed yeast consists of living Saccharomyces cerevisiae cells packed at approximately 30% solids content in moist cake or block form, requiring refrigeration at 0-4°C to maintain viability over 2-4 week shelf periods. Its primary purpose is to generate carbon dioxide through anaerobic fermentation, causing dough leavening in commercial bread production. Block yeast dominates industrial bakery procurement due to standardized dosing and extended handling tolerance. Cake yeast retains niche demand among artisanal bakers seeking manual crumble dispersion. Instant yeast segments capture growth in home baking channels where storage convenience outweighs traditionalist preference.
FDA food safety standards and the EU's General Food Law Regulation govern pathogen limits and labeling requirements for live yeast products crossing into US and European commercial channels. China's SAMR enforces GB standards for microbial purity that constrain import eligibility. India's FSSAI mandates cold-chain documentation for perishable biologics entering food processing. Stakeholders must monitor evolving strain registration protocols and refrigeration infrastructure gaps before committing capital to emerging market expansion.
Market Dynamics
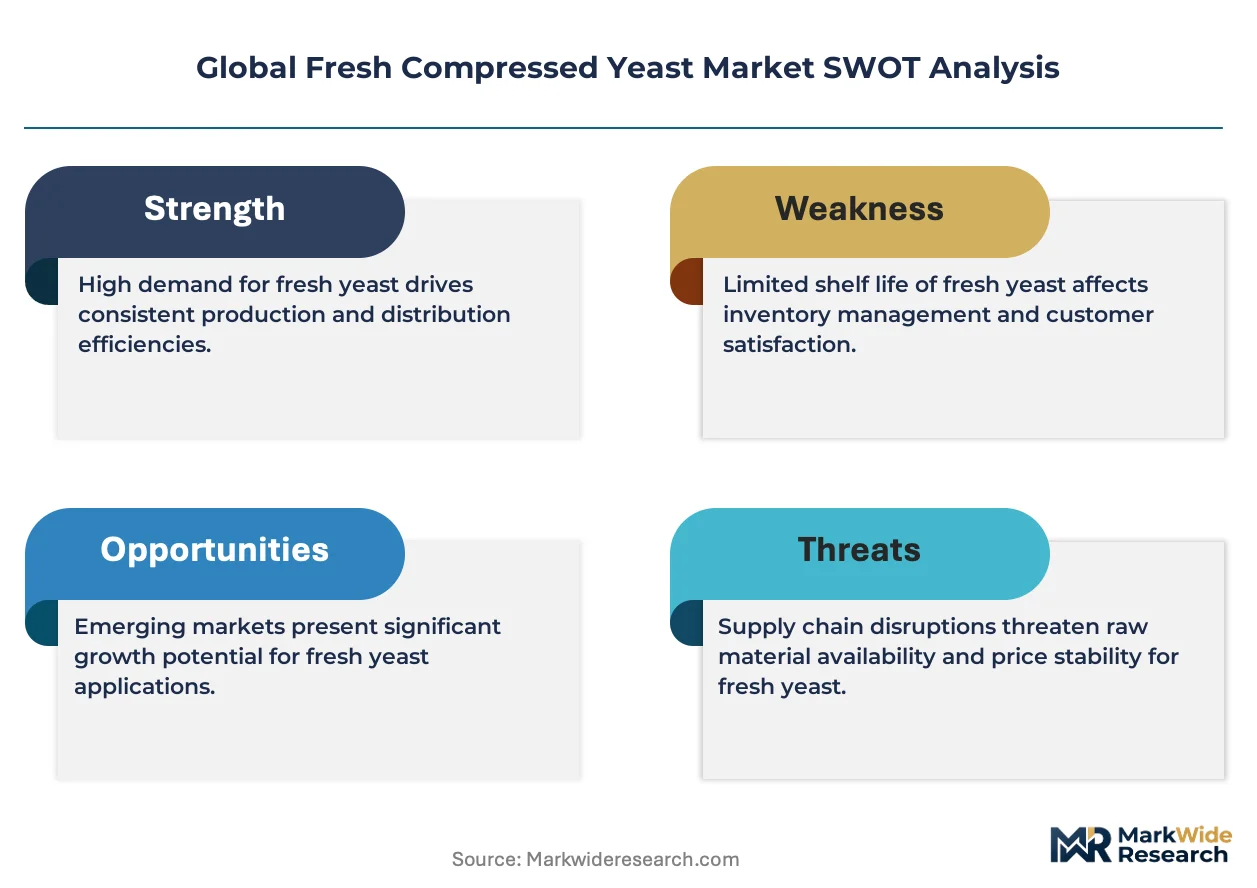
The EU Green Deal's sustainability mandates are forcing yeast suppliers to restructure raw material sourcing protocols across fermentation networks. Cold-chain infrastructure gaps in emerging markets compound operational complexity for perishable biologics distribution.
Growth Catalysts
- Clean-label fermentation:Artisanal bakeries across Western Europe favor fresh compressed yeast for traditional bread cultures over dried alternatives.
- EU Green Deal mandates:Sustainability requirements reshape molasses and sugar beet feedstock procurement protocols for industrial suppliers.
- Asia-Pacific food manufacturing:Distributed production facilities anchor volume supply to regional manufacturers expanding bakery output.
Market Restraints
- Refrigeration dependency:Fresh compressed yeast requires 0-4°C cold chain maintenance, limiting shelf life to 2-4 weeks and constraining distribution radius.
- Input cost volatility:Molasses prices fluctuate with sugar beet harvest cycles and biofuel diversion demand.
- Substitution threat:Instant yeast segments capture home baking channels where storage convenience outweighs traditionalist preference.
Strategic Opportunities
- India cold-chain expansion:FSSAI mandates for perishable biologics documentation create structured entry pathways for compliant suppliers.
- Strain specialization:Cold-weather dough performance variants address Nordic and Alpine bakery requirements.
- Block yeast standardization:Industrial bakeries favor standardized dosing formats for automated production lines.
Industry Challenges
- Refrigeration infrastructure gaps:Last-mile cold chain deficiencies in emerging markets threaten viability during transport.
- Strain registration complexity:Evolving microbial purity protocols across FDA, EFSA, and SAMR jurisdictions extend product approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fresh Compressed Yeast Market |
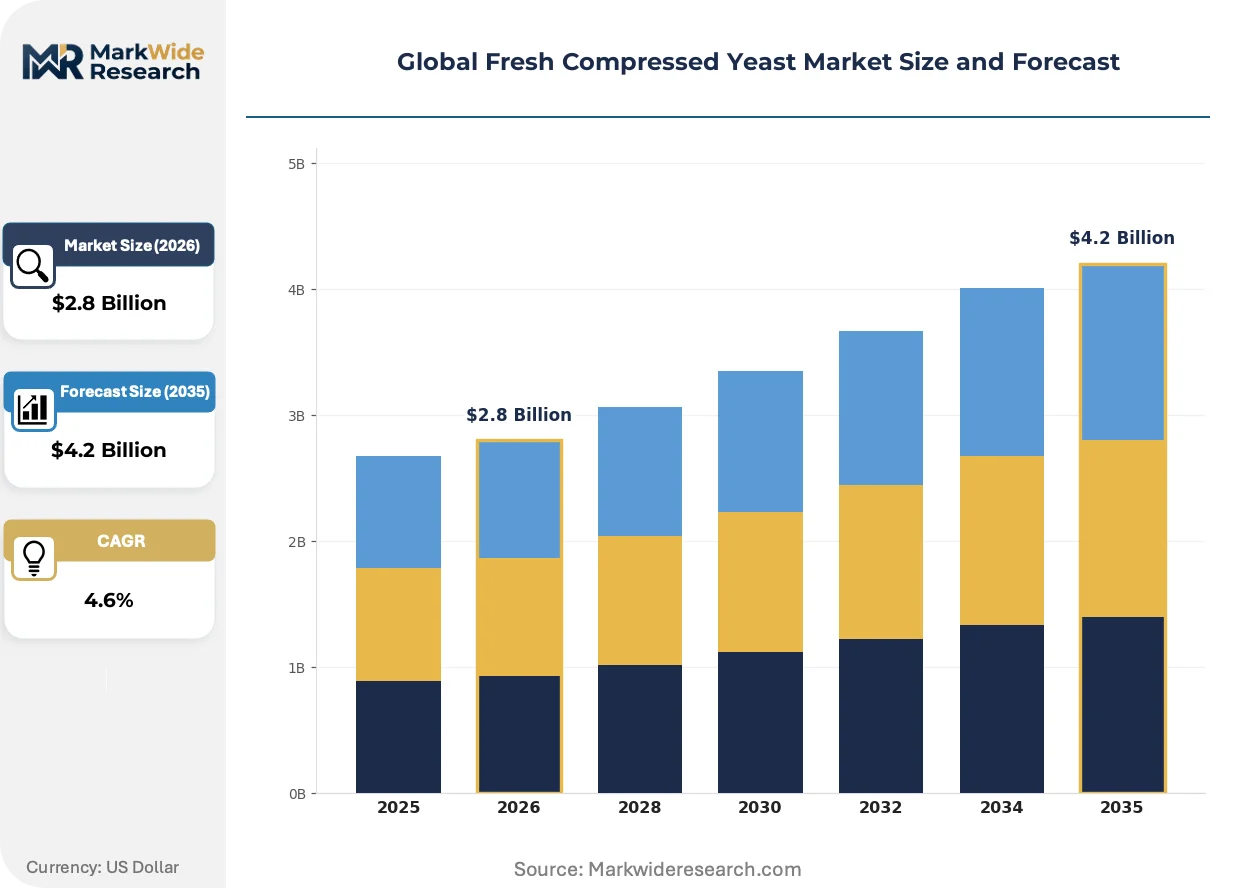
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Yeast, Cake Yeast, Active Dry Yeast, Instant Yeast End User: Bakeries, Confectioneries, Home Baking, Food Service Application: Bread Production, Pastry Making, Pizza Dough, Fermentation Processes Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Angel Yeast Co., Ltd., Lesaffre, Lallemand Inc., Associated British Foods, Oriental Yeast Co., Ltd., Kerry Group plc, Chr. Hansen, Koninklijke DSM N.V., AB Mauri Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fresh Compressed Yeast Market Emerging Trajectories
Bioprocessing automation and regulatory harmonization are compressing production economics while reshaping competitive requirements for live yeast suppliers.
Single-use bioreactor systems for yeast propagation are consolidating fermentation capacity into modular, scalable units. Mid-scale industrial bakeries adopt these systems to reduce cross-contamination risks and accelerate batch turnaround. The technology is consolidating regional production networks by enabling distributed manufacturing without centralized capital intensity.
REACH and EU F-Gas Regulation compliance requirements are tightening emissions controls across refrigeration-dependent supply chains. Industrial yeast suppliers retrofit cold storage facilities with lower-GWP refrigerants to maintain market access. Block yeast distribution networks in Germany and France face accelerated equipment upgrade cycles.
Direct procurement relationships between artisanal bakeries and specialized strain developers are displacing traditional distributor intermediaries. Small-batch bakers in Italy and Spain source heritage fermentation cultures through digital platforms connecting regional suppliers. This channel shift concentrates in Mediterranean markets where provenance certification commands premium positioning.
Global Fresh Compressed Yeast Market Segmentation
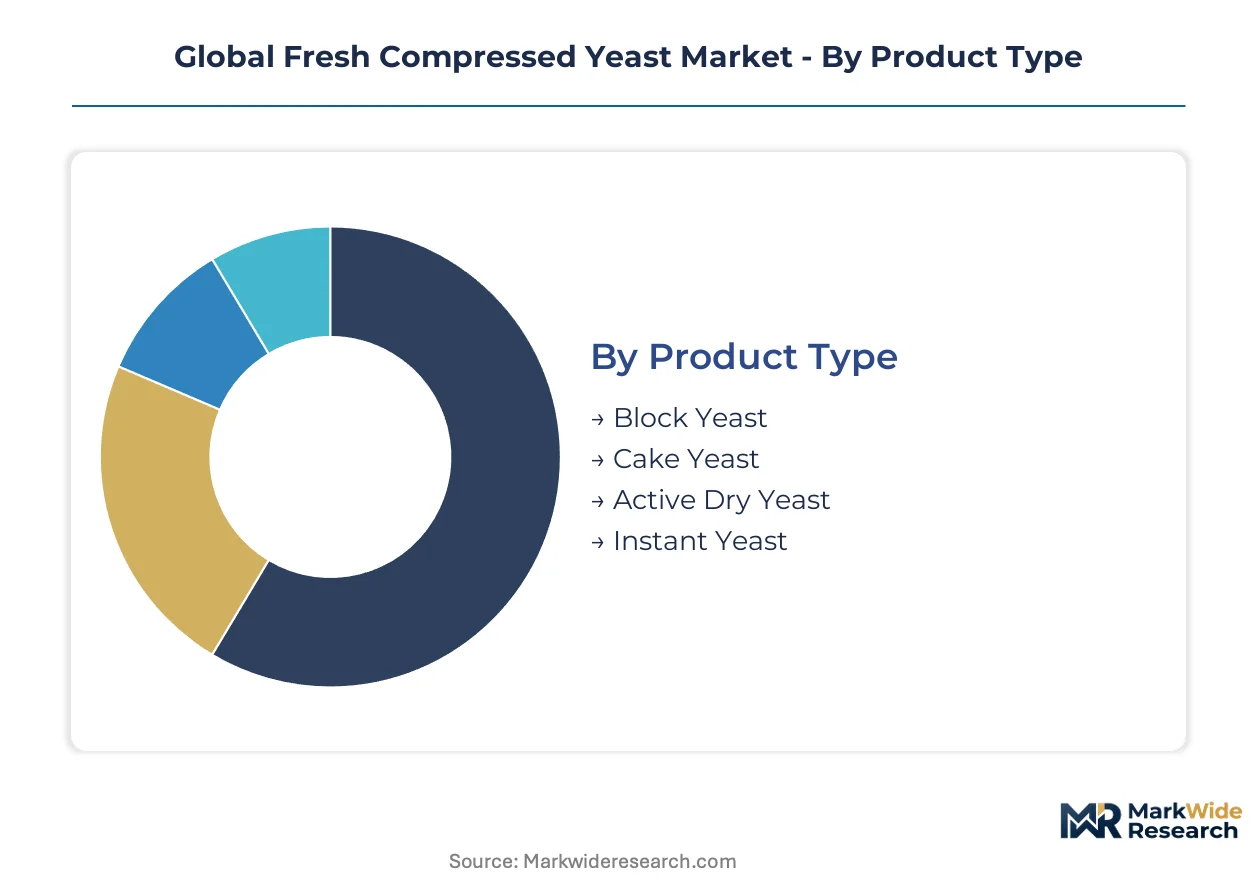
Fresh compressed yeast markets fragment across product formats, end-user scale, and channel infrastructure. Each dimension carries distinct refrigeration requirements, pricing tolerance, and strain specification needs that reshape supplier priorities.
Product Type:
Industrial buyers prioritize handling tolerance and dosing precision; artisanal segments trade standardization for manual control and heritage provenance.
- Block Yeast:Dense rectangular blocks at 30% solids content withstand extended ambient exposure during industrial handling. Automated production lines in Germany and France favor this format for consistent gram-scale dosing. Cold-chain reliability limits expansion into markets with refrigeration gaps.
- Cake Yeast:Crumbly moist cakes enable manual dispersion into small-batch doughs. Artisanal bakers in Italy and Spain source heritage strains through direct procurement relationships. Shelf life constraints of 2-3 weeks restrict geographic distribution radius.
- Active Dry Yeast:Dehydrated granules with extended ambient stability serve backup supply roles for industrial bakeries managing cold-chain risk.
- Instant Yeast:Rapid-hydration formulations capture home baking channels where refrigerator space is limited.
Volume sits with Block Yeast; growth tilts toward Instant Yeast.
End User:
Scale determines procurement sophistication — from commodity contracts to heritage strain curation.
- Bakeries:Industrial facilities in Germany negotiate multi-year supply agreements with strain performance guarantees. Lesaffre and Lallemand compete on fermentation speed consistency under variable flour protein conditions.
- Confectioneries:Patisserie chains in France require low-odor strains that preserve delicate flavor profiles in laminated doughs. Cold-chain documentation under EU General Food Law Regulation governs supplier eligibility.
- Home Baking:Convenience preferences drive instant yeast substitution despite traditionalist advocacy for compressed formats.
- Food Service:Pizza chains in the US specify cold-weather performance variants for dough retarding systems.
Revenue concentrates in Bakeries; margin expansion favors Confectioneries.
Application:
Fermentation kinetics and dough rheology requirements segment demand by end-product specifications.
- Bread Production:Pan bread factories demand high-activity strains with rapid gas production for short proofing cycles. Block yeast dominates high-throughput lines in industrial facilities.
- Pastry Making:Laminated dough applications in French patisserie require strains with controlled fermentation rates to prevent butter layer rupture during folding.
- Pizza Dough:Cold-fermentation protocols favor strains with extended viability at refrigerated temperatures.
- Fermentation Processes:Non-baking applications in bioethanol and brewing divert yeast supply during surplus periods.
Throughput leadership belongs to Bread Production; technical differentiation concentrates in Pastry Making.
Distribution Channel:
Cold-chain integrity requirements filter channel viability by segment and geography.
- Wholesale:Temperature-controlled distribution networks serve industrial bakeries with scheduled just-in-time delivery. Germany's KBA-regulated transport standards enforce compliance documentation.
- Supermarkets:Refrigerated retail cases in France and Italy stock cake yeast for home bakers, though shelf space competes with dried alternatives.
- Online Retail:Insulated packaging and expedited shipping expand access to specialty strains for artisanal buyers in remote locations.
- Convenience Stores:Limited refrigeration capacity restricts assortment to dried yeast formats in most markets.
Volume flows through Wholesale; channel innovation centers on Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molasses supply corridors from Brazilian sugarcane fields and European sugar beet belts anchor production geography for fresh compressed yeast manufacturing networks.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia sustain block yeast demand for automated production lines. The KBA enforces temperature-controlled transport standards under EU General Food Law Regulation. Cologne-Düsseldorf corridor hosts Lesaffre's vertically integrated fermentation facilities serving pan bread factories across the Benelux region.
France
Patisserie chains in Île-de-France require low-odor strains for laminated dough applications. REACH compliance mandates govern emissions from cold storage facilities using lower-GWP refrigerants. Lyon and Paris industrial zones concentrate heritage strain development for artisanal bakery direct procurement.
United States
Pizza chains specify cold-weather performance variants for dough retarding systems in Midwest and Northeast operations. FDA food safety standards govern pathogen limits for live yeast products entering commercial channels. Chicago and New York Metro areas anchor wholesale distribution networks for temperature-controlled just-in-time delivery.
China
Asia-Pacific food manufacturers expand bakery output through distributed production facilities in Yangtze River Delta and Pearl River Delta. SAMR enforces GB standards for microbial purity that constrain import eligibility. Zhengzhou and Shanghai industrial clusters host Angel Yeast Co., Ltd. volume supply operations.
India
FSSAI mandates for perishable biologics documentation create structured entry pathways for compliant suppliers in Maharashtra and Gujarat. Cold-chain infrastructure gaps in last-mile distribution threaten viability during transport. Mumbai-Pune corridor concentrates emerging demand from organized retail bakery chains.
Global Fresh Compressed Yeast Market Vendor Landscape
Capacity expansion dominates the current landscape as fermentation networks consolidate into modular, scalable units. The vendor base organizes around three tiers: multinational biotech conglomerates with diversified life science portfolios, specialized yeast propagators with regional fermentation expertise, and heritage strain curators serving artisanal channels. Strategic archetypes include backward-integrated feedstock controllers, distributed manufacturing specialists, and provenance-certified niche suppliers. M&A activity and geographic licensing agreements represent the dominant competitive moves reshaping market structure.
Among the specialized yeast propagators, Angel Yeast Co., Ltd. and Lallemand Inc. exemplify the distributed manufacturing archetype through continental production footprints. Lesaffre occupies a position representing backward-integrated feedstock control with multi-continent fermentation network coverage. Associated British Foods and Oriental Yeast Co., Ltd. sit within the diversified food ingredient conglomerate tier, leveraging cross-category distribution infrastructure. Kerry Group plc and Chr. Hansen anchor the life science application extension archetype, connecting yeast capabilities to broader bioprocessing portfolios.
| Leading Market Players |
|---|
| Angel Yeast Co., Ltd. |
| Lesaffre |
| Lallemand Inc. |
| Associated British Foods |
| Oriental Yeast Co., Ltd. |
| Kerry Group plc |
| Chr. Hansen |
| Koninklijke DSM N.V. |
| AB Mauri Foods |
| Others |
Supply Flow & Price Mechanics
Family-owned fermentation specialists across Western Europe and Asia-Pacific anchor supply discipline through multi-generational ownership structures that resist short-term pricing volatility. Their captive control over molasses sourcing networks insulates block yeast contracts from spot market swings while sustaining premium positioning for heritage cake yeast strains in artisanal channels.
Pricing Analysis
Strain performance guarantees bundled with multi-year supply agreements command premium positioning against unbundled commodity spot transactions. Three-tier pricing structure across premium, standard, and economy levels separates certified organic strains from industrial-grade block formats and generic cake yeast alternatives. Cost compression in standard tiers is intensifying because Brazilian molasses diversion to bioethanol feedstock tightens input availability. Industrial bakeries in Germany exhibit highest price sensitivity through volume-negotiated contracts, while French patisserie chains tolerate premium positioning for low-odor specialized strains.
Supply Chain Analysis
Skilled fermentation technicians in Germany's Cologne-Düsseldorf corridor, France's Lyon industrial zone, and China's Zhengzhou cluster constrain capacity expansion despite automation investments. Raw material flows draw from Brazilian sugarcane molasses, European sugar beet processing byproducts, and Thai cassava-derived feedstocks. Single-source vulnerability in Brazilian molasses corridors threatens batch consistency during harvest cycle disruptions. Distribution runs through temperature-controlled wholesale networks with KBA-regulated transport documentation serving industrial bakeries on just-in-time schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity expansion lags demand growth across all major producing regions, with skilled technician shortages and cold-chain infrastructure gaps propping pricing discipline for compliant suppliers.
For Market Incumbents: Hedge against instant yeast substitution in home baking channels by securing exclusive strain development partnerships with industrial bakery automation vendors. Prioritize backward integration into sugar beet processing in France and Germany to lock in molasses supply during biofuel diversion peaks. Channel control through direct procurement platforms for artisanal bakers in Italy and Spain defends margin position against distributor disintermediation.
For New Entrants and Emerging Players: Begin with modular single-use bioreactor deployments in India's Maharashtra and Gujarat corridors where FSSAI compliance documentation creates structured entry barriers against informal competitors. The most penetrable white-space sits in cold-weather performance variants for Nordic bakery chains currently sourcing from distant European suppliers. A heritage strain curation go-to-market angle through digital direct procurement platforms captures premium positioning in Mediterranean artisanal markets.
For Investors and Strategic Acquirers: REACH and EU F-Gas Regulation compliance retrofit announcements by incumbent cold storage operators are the leading indicator that consolidation pressure is accelerating for sub-scale fermentation facilities. Long-term viability favors acquisition targets with distributed manufacturing footprints spanning three or more regulatory jurisdictions and captive feedstock arrangements. Watch for strain registration protocol harmonization discussions between FDA, EFSA, and SAMR as the inflection signal for cross-border capacity rationalization plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive molasses supply from German sugar beet processors insulates margin from biofuel diversion volatility. |
| Modular Bioreactor Deployment | Single-use fermentation systems in India's Gujarat corridor bypass centralized capital intensity for regional supply. |
| Cold-Chain Infrastructure Partnership | Refrigerated transport alliances with KBA-certified operators secure last-mile viability for perishable block yeast. |
| Heritage Strain Certification | Provenance documentation through Lyon-based laboratories commands premium positioning in Italian artisanal channels. |
| Regulatory Compliance Retrofit | Lower-GWP refrigerant upgrades under EU F-Gas Regulation maintain market access for German cold storage networks. |
Methodological Framework
Trade flow databases, customs records from major molasses-exporting jurisdictions, and fermentation industry association publications formed the secondary backbone of this analysis. Primary fieldwork encompassed interviews with plant managers at industrial bakery facilities, procurement leads at European sugar beet processing cooperatives, cold-chain logistics operators under KBA transport standards, and regulatory affairs specialists navigating FDA, EFSA, and SAMR strain registration protocols. Bottom-up volume estimates from facility-level production data triangulated against top-down demand aggregation across bread production, pastry making, and pizza dough application segments.
Bottom-up modeling anchored projections in named production cluster capacities, strain-specific activity rates, and cold-chain infrastructure development timelines across the analysis window. Segmentation dimensions encompassed product format, end-user scale, application fermentation kinetics, and distribution channel infrastructure. CAGRs were derived from elasticity-adjusted demand curves incorporating flour protein variability, proofing cycle compression trends, and substitution dynamics between compressed and instant yeast formats. Industry-specific inputs included molasses price correlation models with sugar beet harvest cycles and bioethanol policy diversion coefficients.
Underlying measurement precision varies by segment; block yeast industrial contracts carry tighter precision than artisanal cake yeast spot markets due to standardized reporting requirements. Forecasts reflect documented assumptions regarding cold-chain infrastructure buildout rates, strain registration protocol evolution, and feedstock availability under EU Green Deal sustainability mandates. Material deviation in Brazilian molasses export policy, REACH refrigerant phase-down acceleration, or FSSAI enforcement intensity in India warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Edible Oil Market
Ingredients
Industrial Starch Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Animal-Derived Ingredients Market
Ingredients
Refined Coconut Oil Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Canada Soy Protein Market
Ingredients
Potato Protein Market
Ingredients
Barley Malt Extract Market
Ingredients
North America Gums Market
Ingredients
Desiccated Coconut Market
Ingredients
Glucuronolactone Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Salt Content Reduction Ingredients Market
Ingredients
Global Personal Care Active Ingredients Market