
 Liquid Sugar Market | 2026-2036
Liquid Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Sugar Market Analysis
FDA nutrition-labeling revisions is pivoting formulation economics for U.S. liquid sugar suppliers. Cargill Incorporated leverages its corn wet-milling infrastructure to sustain cost advantages in high-fructose syrup production. Südzucker AG anchors European beet-derived liquid sugar supply through integrated agricultural processing networks. Tate & Lyle PLC differentiates with specialty fiber-syrup blends that navigate reduced-sugar regulatory thresholds.
Liquid sugar comprises concentrated aqueous solutions of sucrose, glucose, fructose, or blended saccharides, typically standardized to 67-69 degrees Brix for industrial handling and microbial stability. Food & Beverage end users consume the dominant volume share, though Pharmaceuticals-grade specifications command premium positioning due to USP-grade purity requirements and endotoxin controls. Corn Syrup retains mature volume leadership in North American processed foods, while Agave Syrup captures expanding shelf space in natural-channel distribution as specialty-store buyers prioritize low-glycemic index claims.
FDA, EPA, and EU Green Deal frameworks collectively govern liquid sugar quality, environmental discharge from refineries, and carbon-intensity disclosure across supply chains. The EU Green Deal's deforestation-free sourcing rules will restrict market access for suppliers lacking traceable agricultural provenance. Stakeholders must monitor evolving sweetener-tax legislation and biotechnology-derived alternatives that could displace conventional liquid sugar in formulated products.
Market Dynamics
The EU Green Deal's deforestation-free sourcing rules are compressing supply chain timelines for liquid sugar processors, forcing rapid traceability system deployment across cane and beet agricultural networks.
Growth Catalysts
- Clean-label beverage mandates:Major soft drink and ready-to-drink coffee manufacturers are reformulating with liquid cane and agave syrups to eliminate artificial sweeteners from ingredient decks.
- FDA nutrition-labeling revisions:Updated serving-size declarations and added-sugar callouts are driving food manufacturers toward concentrated liquid formats that reduce per-serving sweetener volume.
- Brazilian cane processing expansion:New crushing capacity in São Paulo and Minas Gerais states is lowering export unit costs for North American and Asian food processors.
Market Restraints
- Corn feedstock volatility:Drought-induced price swings in U.S. Midwest grain markets destabilize high-fructose corn syrup production economics.
- Beet supply concentration:European liquid sugar output depends on weather-sensitive harvests concentrated in France, Germany, and Poland.
- Biotechnology substitution:Precision-fermented sweeteners and enzymatically modified stevia extracts threaten conventional liquid sugar volumes in reduced-sugar applications.
Strategic Opportunities
- Pharmaceutical-grade specifications:USP-grade liquid sucrose for parenteral nutrition and vaccine stabilization commands price multiples over food-grade equivalents.
- EU carbon-border adjustment mechanisms:Early certification of low-carbon-intensity cane sourcing creates preferential access to European industrial buyers.
- Direct-to-bakery distribution:Bulk tanker delivery systems bypass traditional ingredient distributors for artisan and commercial bakery segments.
Industry Challenges
- Microbiological control expertise:Maintaining 67-69 Brix stability without crystallization or fermentation requires specialized process engineering talent in short supply.
- Endotoxin testing infrastructure:Pharmaceutical customers demand validated rapid-testing capabilities that smaller refiners lack capital to install.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Sugar Market |
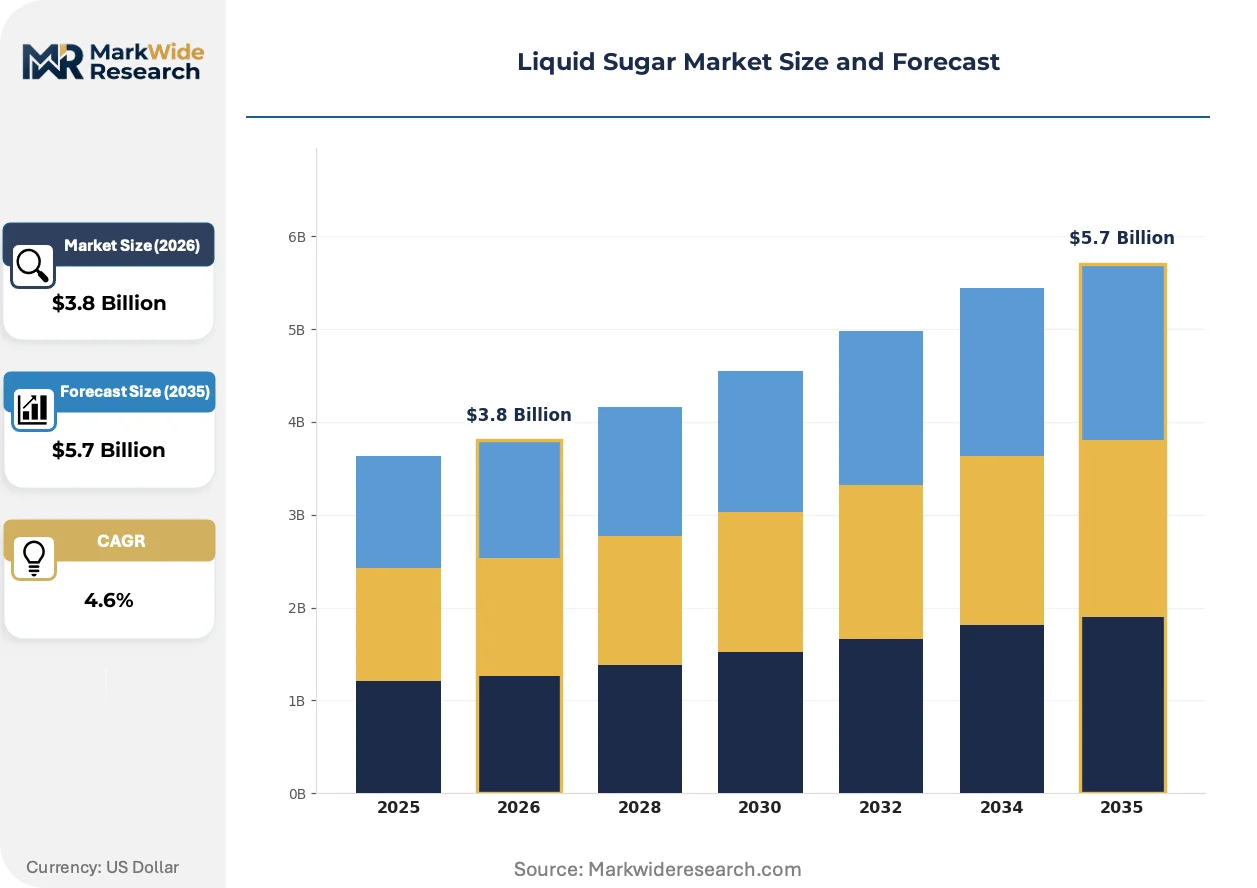
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simple Syrup, Corn Syrup, Agave Syrup, Maple Syrup End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Form: Liquid Concentrate, Ready-to-Use, Powdered, Specialty Blend Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Südzucker AG, ASR Group, Wilmar International Limited, American Crystal Sugar Company, Nordzucker AG, Tereos S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Sugar Market Emerging Trajectories
Digital traceability platforms and enzymatic processing advances are compressing the gap between agricultural provenance and finished specification compliance.
Membrane filtration technology for color and impurity removal is modularizing refinery operations, allowing mid-scale processors to match large-plant output quality without continuous thermal processing. Beverage concentrate manufacturers in Mexico and Thailand are adopting skid-mounted units for flexible campaign-based production. This modularizing approach is fragmenting equipment vendor relationships and shortening technology refresh cycles.
EU Green Deal deforestation-free sourcing rules are mandating geolocation-verified farm boundaries and mass-balance documentation for all imported cane-derived sweeteners. European confectionery and dairy processors must requalify suppliers by the compliance deadline or face exclusion from public procurement channels. Brazilian and Indian exporters are deploying satellite-monitoring partnerships to retain market access.
Ingredient specification unbundling is separating liquid sugar procurement from traditional broadline distributor relationships. Large food manufacturers in the United States are negotiating direct supply agreements with refiners, bypassing regional ingredient houses. This disintermediation concentrates volume with integrated agricultural processors and compresses margins for independent distributors serving mid-tier bakeries and beverage startups.
Liquid Sugar Market Segmentation
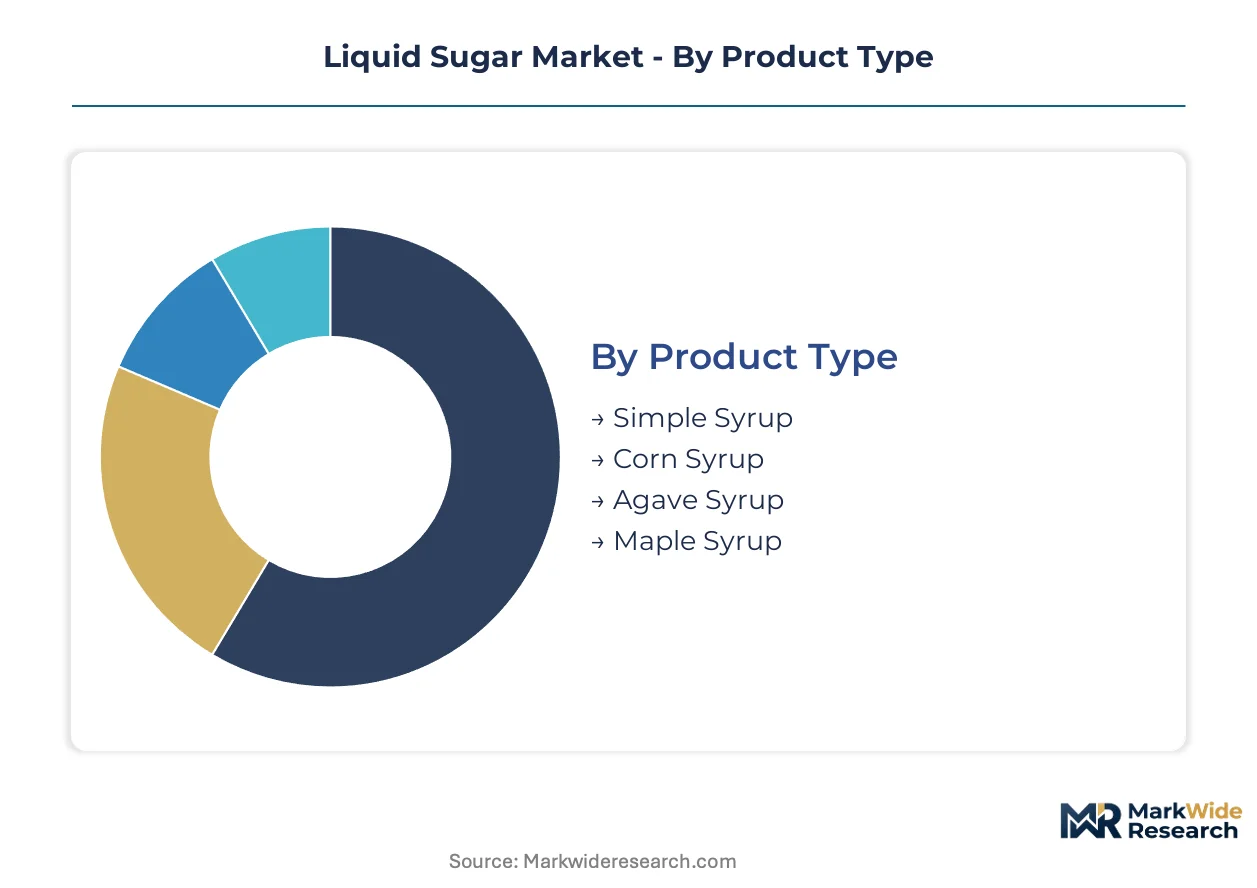
Liquid sugar procurement patterns diverge sharply across product specifications, end-use purity requirements, and handling formats. Manufacturers configure production assets around these segment boundaries to capture volume efficiencies or premium positioning.
Product Type:
Supply concentration varies dramatically by feedstock origin, with cane and corn processing infrastructure anchoring regional cost structures.
- Simple Syrup:Standardized aqueous sucrose solutions at 67 Brix serve as the baseline industrial sweetener for beverage bottlers and bakery formulators. U.S. and Brazilian cane refiners dominate bulk supply contracts with North American soft drink manufacturers seeking clean-label alternatives to corn-derived options.
- Corn Syrup:Glucose-fructose blends from wet-milled corn starch retain mature volume leadership in processed foods. Midwest grain belt proximity to Cargill and ADM processing facilities sustains cost advantages for U.S. confectionery and cereal producers despite feedstock price volatility.
- Agave Syrup:Low-glycemic index positioning drives natural-channel expansion; Mexican Jalisco processors supply U.S. specialty retailers.
- Maple Syrup:Quebec and Vermont tapping operations constrain supply; premium pricing limits penetration beyond artisan bakery and confectionery niches.
Simple syrup absorbs the bulk of installed capacity; agave syrup is expanding most quickly.
End User:
Application-specific purity standards create tiered margin structures that reshape refinery investment priorities.
- Food & Beverage:Industrial-scale users consume dominant volume through tanker-delivered bulk contracts. FDA nutrition-labeling revisions are driving reformulation toward concentrated liquid formats that reduce per-serving sweetener declarations.
- Pharmaceuticals:USP-grade liquid sucrose for parenteral nutrition and vaccine stabilization commands price multiples over food-grade equivalents. Endotoxin testing requirements and batch documentation create qualification barriers that concentrate supply among integrated refiners with dedicated pharmaceutical suites.
- Personal Care:Humectant and exfoliant applications in skincare formulations favor low-color liquid glucose; Brazilian suppliers are gaining share.
- Household:Retail-packaged table syrups face private-label compression; direct-to-consumer channels are fragmenting brand loyalty.
Food & Beverage commands the majority of refinery output; Pharmaceuticals delivers the steepest margin expansion trajectory.
Form:
Handling economics and microbiological stability requirements segment production capabilities across the supplier base.
- Liquid Concentrate:High-Brix solutions minimize transportation costs for industrial buyers with on-site dilution equipment. Brazilian and Thai exporters prioritize this format for intercontinental shipment to North American and Asian processors.
- Ready-to-Use:Standardized dilutions target mid-tier bakeries and beverage startups lacking process engineering staff. Direct-to-bakery distribution systems are bypassing traditional ingredient distributors for this segment.
- Powdered:Spray-dried and crystallized options address shelf-stable formulation needs; limited liquid sugar market overlap.
- Specialty Blend:Fiber-syrup combinations and reduced-sugar formulations navigate regulatory thresholds; Tate & Lyle PLC differentiation focus.
Liquid concentrate captures the greatest production asset deployment; specialty blends are climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and traceability documentation needs.
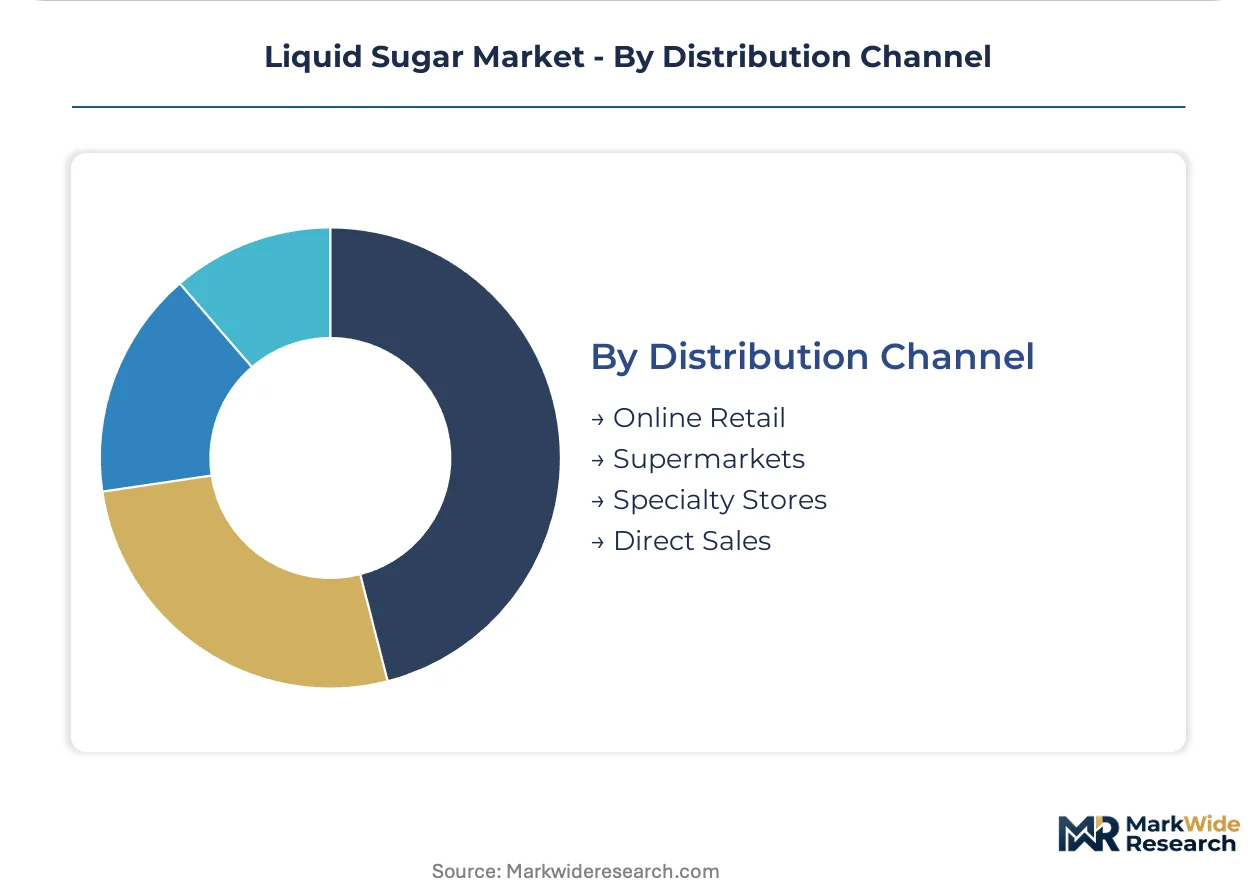
- Direct Sales:Large food manufacturers negotiate supply agreements directly with integrated agricultural processors, disintermediating regional ingredient houses. EU Green Deal deforestation-free documentation requirements favor direct relationships with traceable cane suppliers.
- Supermarkets:Retail-packaged liquid sugar for household consumption faces private-label margin compression.
- Specialty Stores:Natural-channel buyers prioritize agave and maple provenance claims; Mexican and Vermont suppliers concentrate here.
- Online Retail:E-commerce penetration remains limited for bulk industrial formats; artisan bakery ingredient kits drive niche growth.
Direct sales channels concentrate the highest volume flows; specialty stores are gaining share fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's Zona Franca de Manaus and Thailand's Eastern Economic Corridor concentrate cane-processing infrastructure through tax-advantaged zones that subsidize export-oriented refining capacity.
United States
Midwest corn wet-milling clusters around Cedar Rapids and Decatur supply high-fructose corn syrup to domestic beverage bottlers. FDA nutrition-labeling revisions are forcing reformulation toward lower-declared sugar formats. Corn belt drought cycles destabilize feedstock economics for processors in Iowa and Illinois.
Brazil
São Paulo and Minas Gerais crushing expansion is lowering unit costs for North American and Asian export markets. ANVISA alignment with international food-grade standards facilitates pharmaceutical-grade sucrose qualification. Santos port infrastructure upgrades are reducing intercontinental shipment dwell times for liquid concentrate tankers.
Germany
Magdeburg and Anklam beet-processing corridors anchor European liquid sugar supply through integrated agricultural networks. EU Green Deal deforestation-free sourcing rules are compressing supplier requalification timelines. Nordzucker AG facilities in Saxony-Anhalt are deploying satellite-verified farm boundary tracing for cane-derived inputs.
India
Uttar Pradesh and Maharashtra cane cooperatives are expanding crushing capacity for domestic beverage and pharmaceutical demand. FSSAI enforcement of added-sugar disclosure rules is accelerating industrial adoption of concentrated liquid formats. Muzaffarnagar and Kolhapur refining clusters are upgrading membrane filtration capabilities for color removal.
Thailand
Kanchanaburi and Suphan Buri cane belts supply ASEAN processors and Chinese importers with liquid concentrate shipments. Eastern Economic Corridor tax incentives are attracting Japanese beverage manufacturers to co-locate formulation facilities. Rayong port liquid bulk terminals are expanding tanker loading capacity for intercontinental routes.
Liquid Sugar Market Vendor Landscape
North American corn processors anchor one tier; European beet specialists and Asian cane traders hold differentiated positions. The vendor base clusters around three strategic archetypes: integrated agricultural conglomerates with captive feedstock, regional refiners with geographic sourcing advantages, and specialty blenders targeting reduced-sugar formulations. Capacity expansion and direct-to-manufacturer distribution partnerships constitute the dominant competitive moves.
Among integrated agricultural processors, Cargill Incorporated and Archer Daniels Midland Company occupy positions exemplifying scale-driven corn wet-milling dominance. Südzucker AG represents the European beet-derived archetype through integrated agricultural processing networks. Tate & Lyle PLC sits within the specialty formulation tier, differentiating through fiber-syrup blends that navigate regulatory thresholds.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Südzucker AG |
| ASR Group |
| Wilmar International Limited |
| American Crystal Sugar Company |
| Nordzucker AG |
| Tereos S.A. |
| Others |
Supply Flow & Price Mechanics
Captive cane-milling infrastructure in São Paulo and Minas Gerais anchors both supply security and pricing power for Brazilian exporters serving North American beverage processors. This backward integration into agricultural feedstock insulates integrated refiners from spot-market volatility while concentrating volume-based negotiating leverage with multinational soft drink manufacturers.
Pricing Analysis
Short lead-time premiums apply to pharmaceutical-grade liquid sucrose batches requiring validated endotoxin documentation and expedited USP certification. Contract-based long-term offtake dominates industrial procurement, with price differentiation hinging on certification grade and volume scale. Cost compression in food-grade simple syrup is intensifying because Brazilian export capacity expansion floods spot markets. Mid-tier bakeries exhibit highest price sensitivity; pharmaceutical formulators show least sensitivity due to qualification switching costs.
Supply Chain Analysis
EU Green Deal domestic-content mandates are reshaping sourcing toward traceable European beet supply and certified low-carbon-intensity cane imports. Production gravity centers on Brazil, Germany, and Thailand, with raw material dependencies drawing from cane harvests, beet agricultural networks, and corn wet-milling output. Single-source vulnerability concentrates in São Paulo's Zona Franca de Manaus export corridor. Distribution runs through direct tanker delivery to large manufacturers and regional ingredient distributors serving smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology is displacing continuous thermal processing as the dominant refinery upgrade path, compressing capital requirements for mid-scale processors and fragmenting equipment vendor relationships.
For Market Incumbents: Anchor pharmaceutical-grade capacity expansion in ANVISA-aligned Brazilian facilities to capture vaccine stabilization and parenteral nutrition demand. Deepen backward integration into satellite-verified cane sourcing to satisfy EU Green Deal deforestation-free documentation requirements and lock in European confectionery contracts. For New Entrants and Emerging Players: Capture direct-to-bakery distribution white space in North American artisan and commercial bakery segments lacking on-site process engineering staff. Specialty fiber-syrup blends targeting reduced-sugar regulatory thresholds offer the most penetrable entry point; pursue co-development partnerships with beverage concentrate manufacturers seeking clean-label reformulation. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty formulation acquisitions by diversified ingredient houses seeking reduced-sugar capabilities. Long-term viability favors integrated processors with captive agricultural supply and pharmaceutical-suite certifications. Watch biotechnology-derived sweetener cost curves as the inflection indicator threatening conventional liquid sugar volumes in reduced-sugar applications.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Deployment | Modular skid-mounted units allow Thai and Mexican processors to match large-plant quality without continuous thermal processing. |
| Pharmaceutical-Grade Capacity Addition | USP-grade liquid sucrose for vaccine stabilization commands price multiples and creates qualification barriers for smaller refiners. |
| Satellite-Verified Sourcing Certification | Brazilian and Indian exporters deploy geolocation monitoring to retain European market access under EU Green Deal rules. |
| Direct-to-Bakery Distribution Systems | Bulk tanker delivery bypasses traditional ingredient distributors for mid-tier bakeries and beverage startups. |
| Fiber-Syrup Blend Development | Tate & Lyle PLC differentiation focus navigates FDA added-sugar disclosure thresholds for reduced-sugar formulations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with refinery operations directors, beverage formulation scientists, pharmaceutical procurement managers, and bakery supply chain planners combined with FDA nutrition-labeling guidance documents, ANVISA pharmaceutical-grade standards, EU Green Deal implementation texts, and Brazilian agricultural export statistics. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Production volume databases, refinery capacity utilization surveys, and sweetener consumption audits from food and beverage trade associations reconciled with customs import records and pharmaceutical-grade batch documentation requirements across the analysis window. Segmentation dimensions modeled include product type, end-use purity tier, handling format, and distribution channel. CAGRs derived from trend extrapolation of historical volume flows adjusted for regulatory reformulation mandates and biotechnology substitution threats.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to precision-fermented sweetener cost reduction, EU carbon-border adjustment implementation, and drought-induced corn feedstock volatility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Erythritol Market
Sweeteners
Corn Sweeteners Market
Sweeteners
Compressible Sugar Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
White Sugar Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Isomaltulose Market
Sweeteners
Stevia Mints Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
China Allulose Market