
 White Mulberry Leaves Extract Market | 2026-2036
White Mulberry Leaves Extract Market Size, Share, and Industry Trends Forecast 2026-2036
White Mulberry Leaves Extract Market Analytics
Buyer concentration among nutraceutical contract manufacturers is restructuring upstream sourcing dynamics for white mulberry leaf extracts. Xi'an Greena Biotech anchors bulk powder supply to Asian encapsulators through backward integration into raw leaf cultivation. Shaanxi SCIGROUND Biotechnology Co., Ltd. differentiates via DNJ standardization protocols that meet pharmaceutical-grade specifications. Swanson Health Products competes in direct-to-consumer channels with vertically controlled tincture and capsule lines.
White mulberry leaves extract derives from Morus alba foliage, typically standardized to 1-deoxynojirimycin content ranging from one percent to five percent by weight through aqueous or ethanol extraction methods, and serves primarily as a glycemic management agent in dietary supplements and functional foods. Powder formats dominate industrial procurement due to blending flexibility in beverage and bakery applications, while liquid extracts capture premium positioning in apothecary and practitioner channels. Capsule segments sustain margin pools through clinical-dose positioning, whereas tincture formulations occupy niche naturopathic markets with lower volume throughput.
FDA Current Good Manufacturing Practice enforcement for dietary supplements and EFSA novel food assessment pathways jointly elevate analytical burden for new market entrants. USDA organic certification and ISO 17025 laboratory accreditation increasingly function as non-negotiable qualifiers for pharmacy and supermarket listings. Stakeholders must monitor regulatory divergence between pharmacopeial-grade and food-grade extract standards when configuring regional compliance strategies.
Market Dynamics
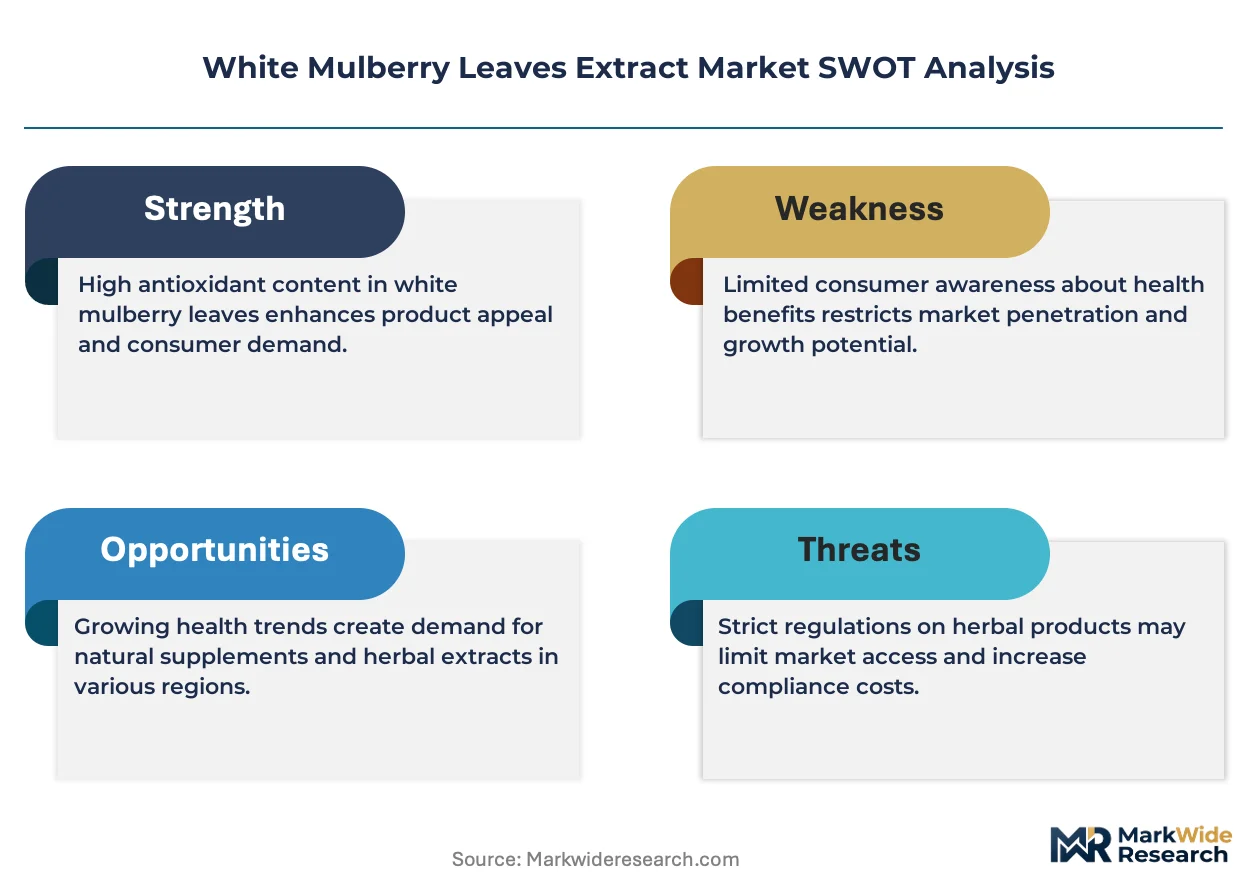
Standardization pressure from FDA dietary supplement guidance and EFSA novel food procedures is compressing supplier margins while elevating analytical compliance costs for DNJ-rich extract batches entering functional food channels.
Growth Catalysts
- Metabolic health positioning:Functional beverage brands in the United States are reformulating with glycemic management claims, pulling standardized 1-deoxynojirimycin extracts into ready-to-drink applications.
- Clean-label procurement mandates:German pharmacy chains now require ISO 17025 laboratory accreditation and USDA organic certification as baseline qualifiers for shelf placement.
- South Korean MFDS regulatory clarity:The Ministry of Food and Drug Safety's explicit health claim pathways for blood glucose modulation are accelerating premium extract uptake in Seoul's direct-to-consumer channels.
Market Restraints
- Leaf supply concentration:Raw Morus alba cultivation clusters in Shaanxi Province create geographic single-point vulnerability for aqueous extraction capacity.
- Pharmaceutical-grade DNJ scarcity:Ethanol purification infrastructure capable of achieving five percent standardization requires capex intensity that excludes mid-tier processors.
- EFSA novel food assessment timelines:Eighteen-to-twenty-four month evaluation windows for new extract formats delay European market entry and tie up working capital.
Strategic Opportunities
- Practitioner channel expansion:Naturopathic clinics in Australia represent underpenetrated demand for liquid tincture formats with clinical-dose positioning.
- Bakery application white space:Clean-label bread and pastry manufacturers seek heat-stable glycemic modulators to replace synthetic additives in dough conditioning.
- Dual carbon policy alignment:China's SAMR green manufacturing incentives favor processors deploying closed-loop ethanol recovery systems for extraction operations.
Industry Challenges
- Phytochemical standardization expertise:Analytical chemists capable of validating DNJ content via HPLC-ELSD methods command premium compensation and remain scarce outside established botanical hubs.
- Multi-jurisdictional dossier preparation:Simultaneous FDA cGMP, EFSA novel food, and MFDS health claim submissions require parallel regulatory affairs teams with divergent documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Mulberry Leaves Extract Market |
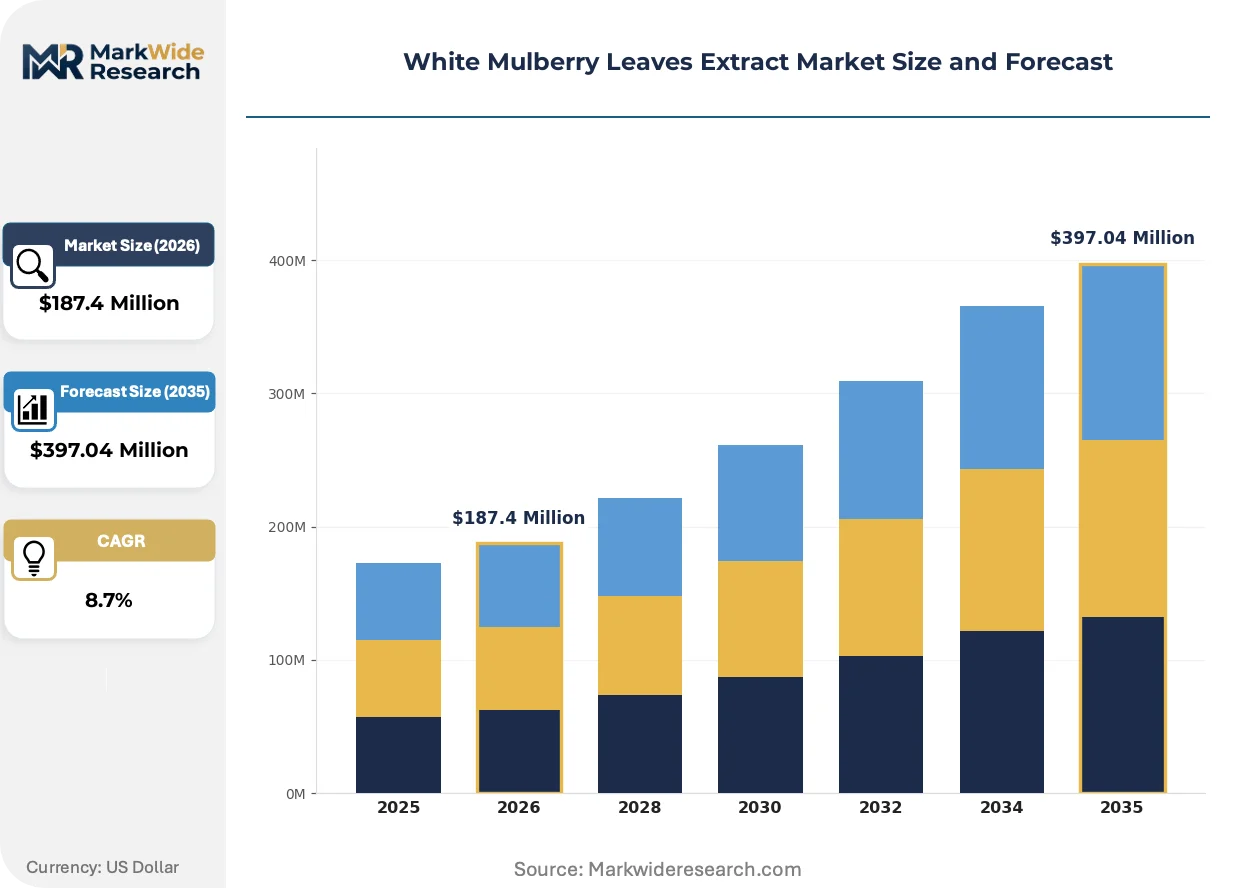
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid Extract, Tincture End User: Food Industry, Nutraceuticals, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets Pack Size: Small, Medium, Large, Bulk |
| Companies Covered | Undersun Biomedtech Corp, Kordel's, Swanson Health Products, Nutra Business, Xi'an Greena Biotech, Nutra Green, Shaanxi SCIGROUND Biotechnology Co., Ltd., Bio Nutrition, NuVitality, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Mulberry Leaves Extract Market Evolving Landscape
Extraction technology maturation and procurement model evolution are converging to reshape competitive positioning across powder, liquid, and encapsulated delivery formats.
Supercritical CO2 extraction is decentralizing capacity deployment for heat-sensitive alkaloid recovery. Mid-scale processors in Germany and South Korea are adopting modular skid-mounted units to bypass centralized toll manufacturing. This technology is decentralizing geographic production gravity away from Shaanxi's aqueous extraction strongholds toward regional pharmaceutical clusters.
EFSA's evolving health claim substantiation requirements for botanical glycemic agents are tightening clinical evidence thresholds. Supplement brands must now commission human intervention studies rather than relying on compositional data alone. Capsule and tablet segments face the steepest compliance burden, driving consolidation toward vertically integrated firms with captive clinical research capabilities.
Direct-procurement relationships between functional food brands and cultivator-extractors are displacing traditional distributor intermediaries. Bakery and beverage manufacturers now negotiate backward integration contracts specifying leaf provenance and DNJ standardization tiers. This pattern concentrates in the United States where clean-label supply chain transparency commands shelf price premiums.
White Mulberry Leaves Extract Market Segmentation
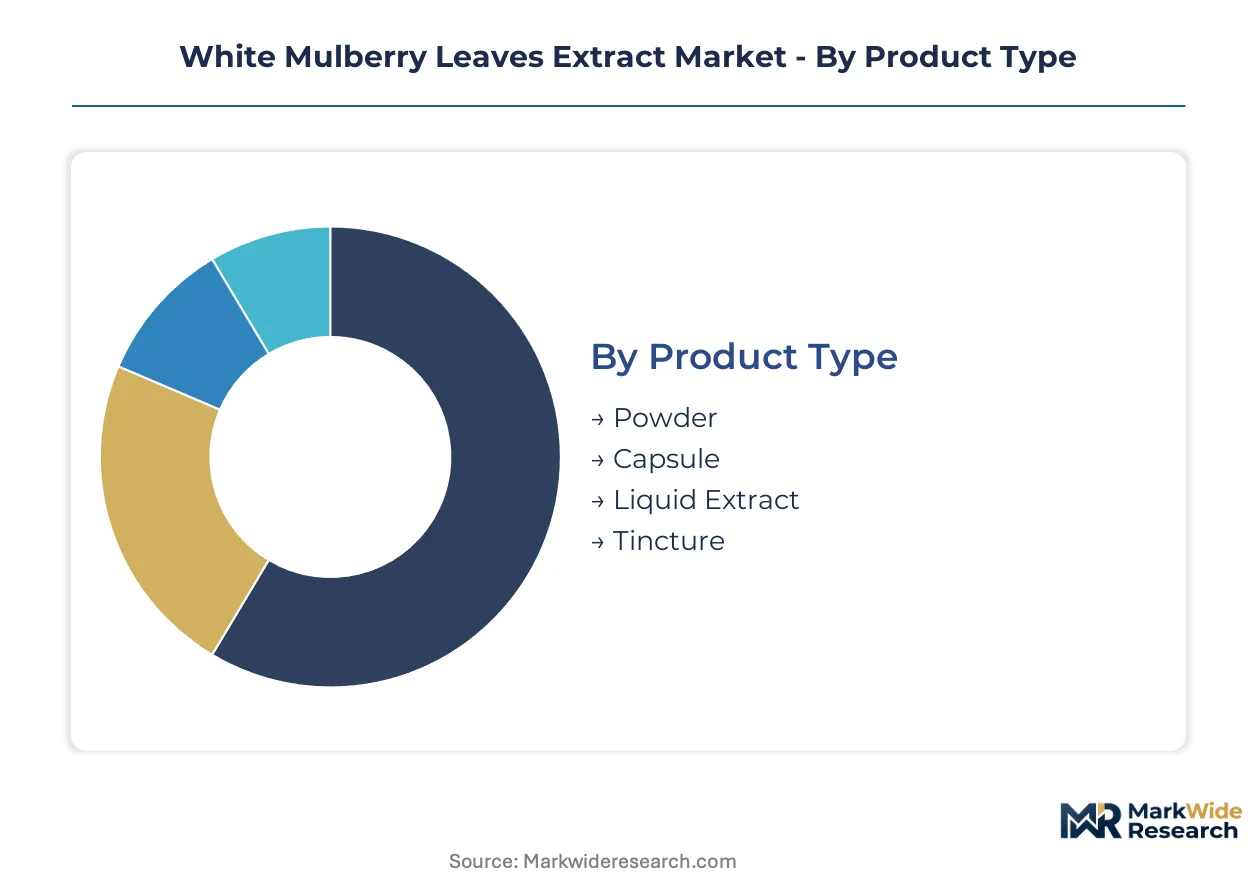
Segmentation in white mulberry leaf extracts determines which procurement pathways extractors must navigate. FDA cGMP, EFSA novel food, and MFDS health claim requirements apply unevenly across delivery formats and end-use channels, creating divergent compliance economics for suppliers.
Product Type:
Powder formats face the lightest regulatory burden for food-grade applications, while pharmaceutical-grade capsules and tinctures trigger multi-jurisdictional pharmacopeial standards that extend approval timelines.
- Powder:Dominates industrial procurement due to blending flexibility in beverage and bakery formulations. Demand concentrates in United States functional food brands seeking heat-stable glycemic modulators for clean-label reformulation.
- Capsule:Requires clinical-dose positioning and substantiation through human intervention studies under EFSA's tightened botanical health claim pathways. Sustains margin pools through practitioner channel premiums in Germany and South Korea.
- Liquid Extract:Captures apothecary positioning with standardized DNJ concentrations suitable for flexible dosing protocols. Popular in Seoul's direct-to-consumer channels where MFDS regulatory clarity accelerates premium uptake.
- Tincture:Occupies niche naturopathic markets with lower volume throughput. Australian practitioner clinics represent underpenetrated demand for clinical-dose liquid formats.
Powder sits at the top of the volume ranking, with capsule climbing the fastest.
End User:
Cost tier stratification separates commodity food-grade supply from premium pharmaceutical-grade extraction infrastructure, with nutraceuticals occupying the contested middle ground.
- Food Industry:Bakery and beverage manufacturers drive procurement of heat-stable powder formats. Clean-label bread producers in Germany seek DNJ-standardized extracts to replace synthetic dough conditioners.
- Nutraceuticals:Contract manufacturers anchor bulk demand through backward integration into standardized botanical supply. ISO 17025 accreditation and USDA organic certification function as baseline qualifiers for pharmacy placement.
- Pharmaceuticals:Requires ethanol purification infrastructure capable of achieving five percent DNJ standardization. Capex intensity excludes mid-tier processors from this tier.
- Cosmetics:Emerging application for antioxidant positioning in topical formulations. Regulatory pathway remains less defined compared to ingestible categories.
Nutraceuticals command the largest revenue base, with pharmaceuticals expanding most quickly as clinical evidence thresholds tighten.
Distribution Channel:
Customer type fragmentation distinguishes transparency-demanding direct procurement from traditional intermediary models, reshaping margin capture across the value chain.
- Online Retail:Direct-to-consumer brands in South Korea leverage MFDS regulatory clarity for blood glucose modulation claims. Vertical control over tincture and capsule lines enables rapid format innovation.
- Specialty Stores:Apothecary and natural health retailers in Germany require documented leaf provenance and DNJ standardization tiers. Clean-label supply chain transparency commands shelf price premiums.
- Pharmacies:Mandate ISO 17025 laboratory accreditation and pharmacopeial-grade specifications. EFSA novel food assessment timelines delay European market entry for new extract formats.
- Supermarkets:Emerging channel for functional food integration as beverage brands reformulate with glycemic management positioning. USDA organic certification increasingly functions as non-negotiable qualifier.
Specialty stores retain the highest margin capture, with online retail gaining share fastest through Seoul's regulatory-advantaged direct channels.
Pack Size:
Supply concentration in Shaanxi Province's aqueous extraction capacity dictates volume economics, with bulk procurement offering route to cost efficiency for large-scale formulators.
- Small:Targets practitioner dispensing and trial-size consumer acquisition. Liquid extracts and tinctures dominate this tier through apothecary channels.
- Medium:Serves encapsulators and mid-scale functional food manufacturers. Balances working capital efficiency against per-unit cost optimization.
- Large:Preferred by nutraceutical contract manufacturers with steady formulation demand. Enables batch consistency through single-source procurement.
- Bulk:Direct-procurement relationships between functional food brands and cultivator-extractors displace traditional distributor intermediaries. Bakery manufacturers negotiate backward integration contracts specifying leaf provenance.
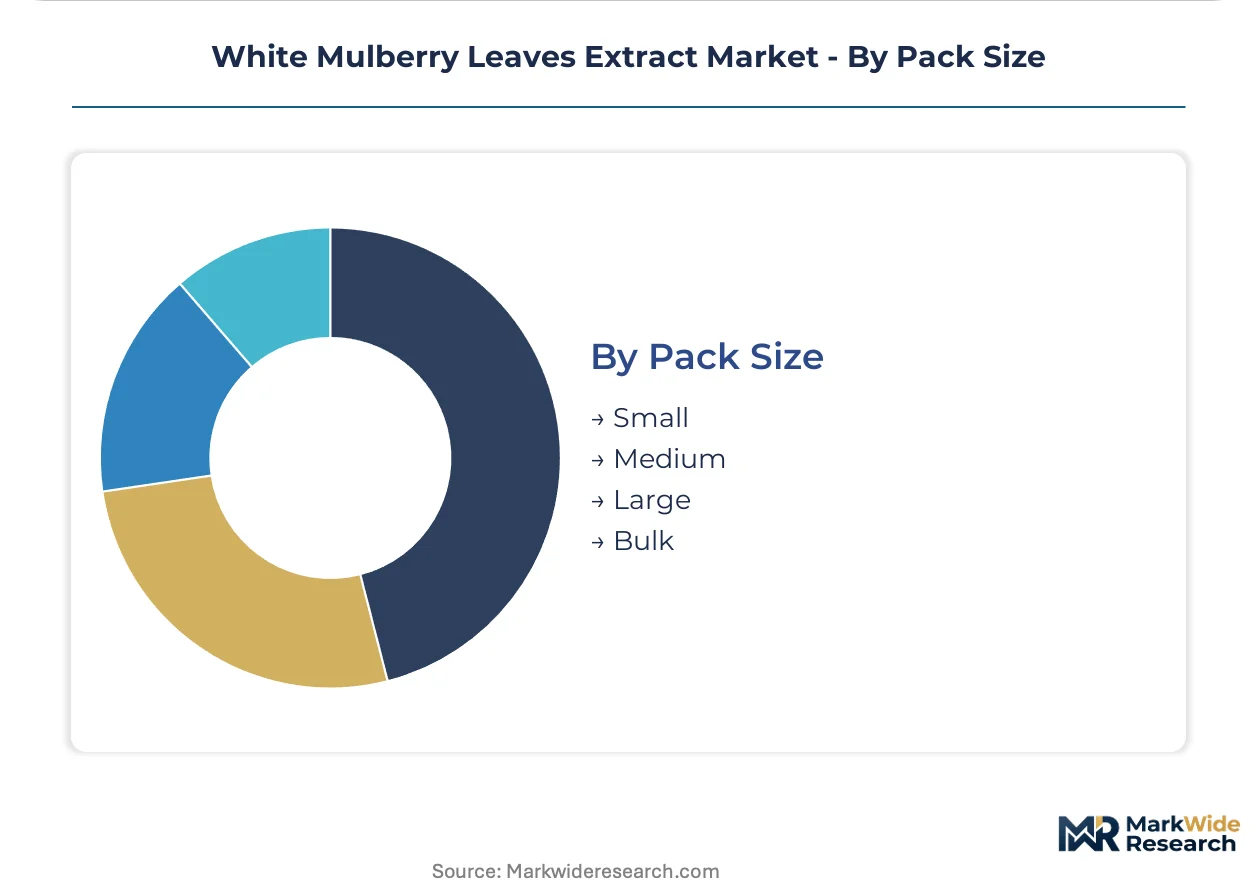
Bulk commands the steepest volume concentration, with small climbing fastest as practitioner channel expansion accelerates in Australia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phytochemical standardization expertise concentrates in Shaanxi Province's botanical processing corridor, where analytical chemists capable of validating DNJ content via HPLC-ELSD methods anchor aqueous extraction capacity. This workforce concentration draws functional food brands seeking backward integration into certified organic supply chains.
United States
Functional beverage brands in California and New York Metro drive procurement of heat-stable powder formats for glycemic management claims. FDA Current Good Manufacturing Practice enforcement elevates analytical burden for dietary supplement entrants. Pacific Northwest encapsulators source directly from Shaanxi cultivator-extractors to secure USDA organic certification.
Germany
Pharmacy chains in Bavaria and North Rhine-Westphalia mandate ISO 17025 laboratory accreditation as baseline shelf placement qualifiers. EFSA novel food assessment timelines delay European market entry for new extract formats. Baden-Württemberg apothecary retailers command premium positioning through documented leaf provenance requirements.
South Korea
Direct-to-consumer brands in Seoul Capital Area leverage MFDS regulatory clarity for blood glucose modulation health claims. Busan-Ulsan contract manufacturers anchor bulk capsule demand through pharmaceutical-grade DNJ standardization. Daegu-Gyeongbuk liquid extract specialists capture premium uptake in practitioner channels.
China
Shaanxi Province's Morus alba cultivation clusters supply aqueous extraction capacity for global nutraceutical formulators. SAMR green manufacturing incentives favor processors deploying closed-loop ethanol recovery systems. Yangtze River Delta functional food brands negotiate backward integration contracts specifying DNJ concentration tiers.
Australia
Naturopathic clinics in New South Wales and Victoria represent underpenetrated demand for clinical-dose liquid tincture formats. TGA regulatory pathways for complementary medicines shape evidence requirements for glycemic positioning. Queensland practitioner channels seek flexible dosing protocols from standardized extract suppliers.
White Mulberry Leaves Extract Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction technology tiers. Market structure fragments between Shaanxi-based aqueous processors, Western encapsulators with captive brands, and regional supercritical CO2 adopters. Three archetypes dominate: backward-integrated cultivator-extractors, toll-manufacturing contract processors, and vertically controlled direct-to-consumer marketers. Consolidation pressure intensifies through direct-procurement relationships displacing distributor intermediaries, while capacity expansion concentrates in modular skid-mounted extraction units.
Within the cultivator-extractor archetype, Xi'an Greena Biotech and Shaanxi SCIGROUND Biotechnology Co., Ltd. exemplify Shaanxi Province's concentration of aqueous processing capacity. Swanson Health Products occupies a position in the vertically integrated direct-to-consumer tier, representing brands that control formulation through retail shelf placement.
| Leading Market Players |
|---|
| Undersun Biomedtech Corp |
| Kordel's |
| Swanson Health Products |
| Nutra Business |
| Xi'an Greena Biotech |
| Nutra Green |
| Shaanxi SCIGROUND Biotechnology Co., Ltd. |
| Bio Nutrition |
| NuVitality |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction adoption is redistributing production capacity toward regional pharmaceutical clusters while simultaneously compressing per-unit extraction costs for DNJ-standardized outputs. This technology shift weakens Shaanxi Province's historical grip on aqueous processing economics, enabling mid-scale processors in Germany and South Korea to capture margin previously lost to toll-manufacturing markups.
Pricing Analysis
DNJ-standardized extracts trade through bundled analytical certification packages versus unbundled commodity powder transactions. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and food-grade certification levels anchors the market, with ISO 17025 laboratory accreditation and USDA organic certification commanding 15-25% premiums over uncertified supply. Cost compression in food-grade powder runs through backward integration contracts between functional food brands and Shaanxi cultivator-extractors. Nutraceutical contract manufacturers exhibit highest price sensitivity due to squeezed formulation margins, while pharmaceutical encapsulators in Seoul demonstrate lowest sensitivity given clinical-dose positioning premiums.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale nutraceutical contract manufacturer demand, displacing traditional distributor intermediaries. Raw Morus alba leaf supply concentrates in Shaanxi Province, China, with secondary cultivation clusters in Turkey and Serbia emerging for EU organic certification compliance. Aqueous and ethanol extraction infrastructure, HPLC-ELSD analytical validation capacity, and pharmacopeial-grade purification systems constitute critical input dependencies. Single-source vulnerability in Shaanxi's aqueous extraction stronghold presents structural risk, compounded by EFSA novel food assessment timelines that tie up working capital for European market entrants. Distribution runs through direct-procurement relationships, backward integration contracts, and apothecary wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in white mulberry leaf extracts rests on supercritical CO2 technology adoption reducing extraction cost curves and pharmaceutical-grade DNJ premiums widening as clinical evidence thresholds tighten.
For Market Incumbents: Cement defensible positioning through captive HPLC-ELSD analytical capabilities and ISO 17025 laboratory accreditation investments that mid-tier processors cannot replicate. Add modular supercritical CO2 capacity in Germany or South Korea to bypass Shaanxi supply concentration risk. Lock in backward integration contracts with functional food brands seeking clean-label supply chain transparency before new entrants capture bakery and beverage procurement relationships.
For New Entrants and Emerging Players: Australian naturopathic clinics represent an underserved buyer archetype with minimal incumbent penetration for clinical-dose liquid tincture formats. Target this white space through flexible dosing protocol positioning and TGA complementary medicines pathway navigation. Seoul's direct-to-consumer channels offer second penetration vector given MFDS regulatory clarity for blood glucose modulation claims, with lower competitive density than United States functional beverage procurement.
For Investors and Strategic Acquirers: Valuations sit cheapest among aqueous extraction specialists in Shaanxi Province lacking downstream brand control or supercritical CO2 transition capital. Long-term viability over a 5-10 year window favors processors with dual aqueous and supercritical capability plus captive analytical chemist teams. Watch for EFSA novel food assessment pathway acceleration as the inflection signal triggering premium-tier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Modular skid-mounted units in Germany and South Korea decentralize extraction capacity away from Shaanxi concentration. |
| Backward Integration Contracts | Direct leaf provenance specifications from cultivator-extractors secure clean-label supply chain transparency for functional food brands. |
| ISO 17025 Laboratory Accreditation | Pharmacy chain shelf placement in Germany and United States mandates this certification as baseline qualifier. |
| MFDS Health Claim Pathway Navigation | Explicit blood glucose modulation regulatory clarity in South Korea accelerates premium extract uptake in direct-to-consumer channels. |
| Practitioner Channel Expansion | Naturopathic clinic relationships in Australia capture underpenetrated demand for clinical-dose liquid tincture formats. |
Research Methodology
Coverage spans the United States, Germany, South Korea, China, and Australia, with primary inputs from each market cluster. The analysis combines structured interviews with nutraceutical contract manufacturing procurement directors, functional food brand formulation scientists, Shaanxi Province extraction facility technical managers, and pharmacy chain category buyers with secondary validation through FDA cGMP guidance documents, EFSA novel food assessment registers, MFDS health claim databases, and USDA organic certification records. Bottom-up volume estimates from extraction capacity utilization rates triangulate against top-down demand projections from end-use segment consumption patterns.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type (powder, capsule, liquid extract, tincture), end user tier (food industry, nutraceuticals, pharmaceuticals, cosmetics), distribution channel (online retail, specialty stores, pharmacies, supermarkets), and geographic regulatory cluster (FDA cGMP, EFSA novel food, MFDS health claim, TGA complementary medicines, SAMR green manufacturing). CAGRs derive from fitted growth curves calibrated to historical standardization adoption rates and regulatory pathway approval velocity. Industry-specific inputs include DNJ concentration standardization tier penetration and supercritical CO2 capacity deployment timelines.
Inputs from extraction facility operators and pharmacy procurement managers were available through the study window; gaps in pharmaceutical-grade DNJ batch-level cost data introduce uncertainty bands around premium-tier margin projections. Forecasts reflect assumptions regarding EFSA assessment timeline stability, Shaanxi leaf supply continuity, and supercritical CO2 technology cost reduction curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
North America Gelatin Market
Ingredients
Pepsin Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Durian Powder Market
Ingredients
Canola Oil Market
Ingredients
Avocado Oil Market
Ingredients
Lentils Flour Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
China Cane Sugar Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Sesame Seed Extract Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Lactase Enzyme Market