
 Artificial Ventilation and Anesthesia Masks Market | 2026-2036
Artificial Ventilation and Anesthesia Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Ventilation and Anesthesia Masks Market Analysis
The artificial ventilation and anesthesia masks category is restructuring around a widening split between premium silicone systems and commodity PVC alternatives. Medtronic leverages its vertical integration in respiratory care to sustain pricing power in high-acuity settings. Ambu A/S differentiates through single-use anesthesia mask portfolios that reduce cross-contamination risk in European surgical suites.
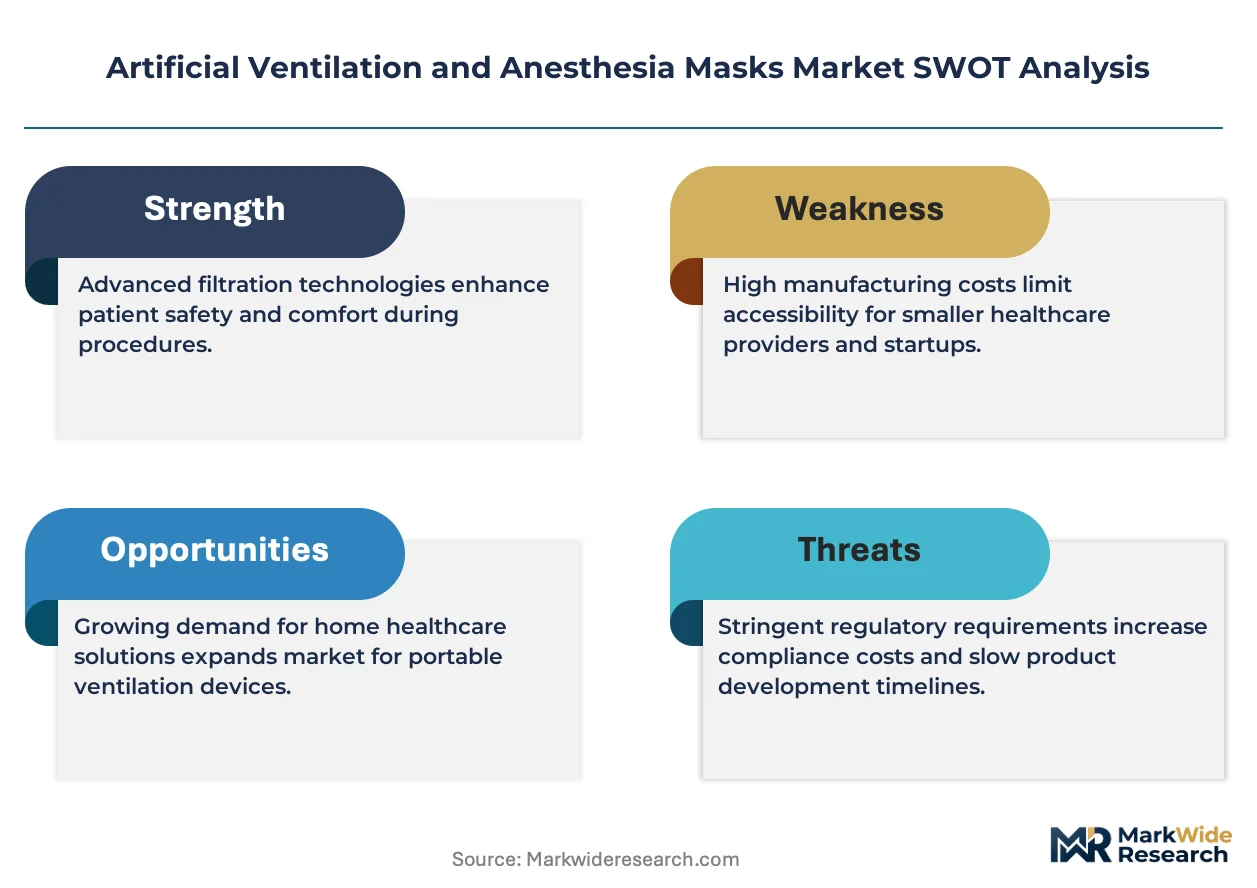
Artificial ventilation and anesthesia masks are medical interfaces designed to deliver controlled gas mixtures to patients during mechanical ventilation or sedation, typically molded from silicone, PVC, or polypropylene with seal pressures ranging from 20 to 60 cm H₂O to prevent aspiration and ensure airway patency. Their primary purpose spans emergency resuscitation, operative anesthesia delivery, prolonged intensive care support, and domiciliary non-invasive ventilation. Full-face masks for intensive care generate the deepest margin pools due to longer replacement cycles and higher technical validation requirements, while nasal masks for home care represent the fastest-expanding application as sleep apnea management shifts toward outpatient settings. Silicone material grades command premium positioning in surgical procedures where tissue compatibility and repeated sterilization tolerance prove decisive.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and market access barriers for manufacturers targeting the United States and European Economic Area. ISO 5356-1 connector standards and ASTM F2967 biocompatibility protocols further constrain design freedom while elevating compliance costs for new entrants. Stakeholders must monitor evolving MDR post-market surveillance obligations and FDA guidance on reusable device reprocessing validation as these frameworks will determine which material platforms and regional manufacturing footprints remain viable.
Market Dynamics
The artificial ventilation and anesthesia masks market is restructuring around infection-control mandates that privilege single-use disposables over reusable systems, compressing replacement cycles and elevating material costs for hospital procurement departments.
Growth Catalysts
- FDA Infection-Control Mandates:Stricter 510(k) clearance requirements for reusable device reprocessing validation are accelerating hospital conversion to single-use anesthesia masks in acute care settings.
- Silicone Biocompatibility Advantages:Full-face silicone designs are displacing PVC alternatives in German and French intensive care units due to reduced pressure injury rates and extended wear tolerance.
- Home Care Expansion:Sleep apnea management shifting toward outpatient settings is generating sustained demand for nasal mask configurations across North American domiciliary channels.
Market Restraints
- Medical-Grade Silicone Cost Volatility:Raw material price fluctuations for platinum-cured silicone elastomers are compressing margins for manufacturers dependent on premium biocompatible grades.
- EU MDR Compliance Burden:Post-market surveillance obligations and Class IIa certification timelines are extending product development cycles and elevating entry barriers for new market participants.
- Substitution by Laryngeal Mask Airways:Supraglottic airway devices are capturing select procedural volumes in ambulatory surgical centers where mask ventilation was previously standard.
Strategic Opportunities
- Underpenetrated Indian Hospital Sector:Tier-2 and tier-3 cities present expansion potential as CDSCO regulatory harmonization accelerates import substitution for anesthesia delivery interfaces.
- ISO 18562 Biocompatibility Testing Convergence:Streamlined validation protocols for breathing gas pathways are reducing time-to-market for novel material platforms in respiratory device portfolios.
- Direct-to-Provider Distribution:Bypassing traditional medical device distributors through hospital system GPO contracts is capturing margin previously allocated to channel intermediaries.
Industry Challenges
- Reprocessing Validation Expertise Gap:Manufacturers lack sufficient in-house toxicology and sterilization science capabilities to navigate FDA guidance on reusable mask reprocessing substantiation.
- Legacy ERP Integration Friction:Hospital supply chain systems require customized EDI mapping for automated mask consumption tracking, delaying vendor onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Ventilation and Anesthesia Masks Market |
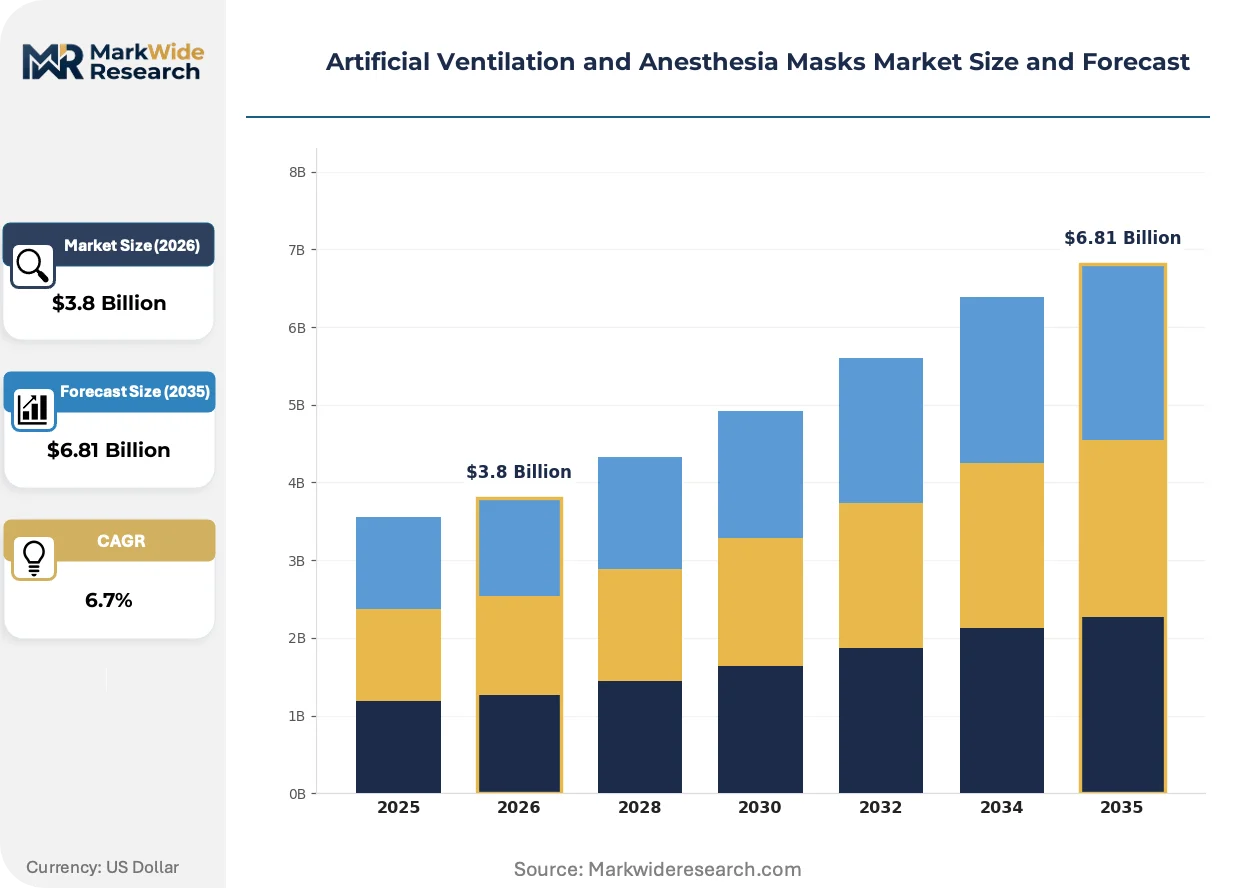
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilation Masks, Anesthesia Masks, Full-Face Masks, Nasal Masks Application: Emergency Care, Surgical Procedures, Intensive Care, Home Care End User: Hospitals, Clinics, Home Healthcare, Research Labs Material: Silicone, PVC, Rubber, Polypropylene |
| Companies Covered | Medtronic, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., ResMed, BD, Ambu A/S, Hamilton Medical, Vyaire Medical, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Ventilation and Anesthesia Masks Market Emerging Trajectories
Material science advances and regulatory harmonization are compressing development timelines while reshaping competitive differentiation around biocompatibility certification rather than basic functional performance.
Silicone full-face ventilation interfaces are consolidating market share in high-acuity intensive care settings. German university hospitals and French regional hospital groups are standardizing on these configurations for patients requiring prolonged non-invasive ventilation. This material transition is consolidating procurement decisions around vendors with captive silicone molding capabilities and ISO 13485-certified cleanroom infrastructure.
EU MDR post-market surveillance requirements are extending clinical evidence obligations for reusable anesthesia masks. Manufacturers must now maintain systematic vigilance data on material degradation and seal performance across sterilization cycles. Surgical suites in the Netherlands and Belgium are responding by accelerating validation of single-use alternatives that bypass reusable device regulatory complexity.
Hospital group purchasing organizations are unbundling mask procurement from anesthesia machine service contracts. Integrated delivery networks in the United States are negotiating direct supply agreements with manufacturers, displacing bundled distributor arrangements. This purchasing behavior shift is most visible in multi-hospital systems across Texas and Florida where standardization committees mandate single-source mask portfolios.
Artificial Ventilation and Anesthesia Masks Market Segmentation
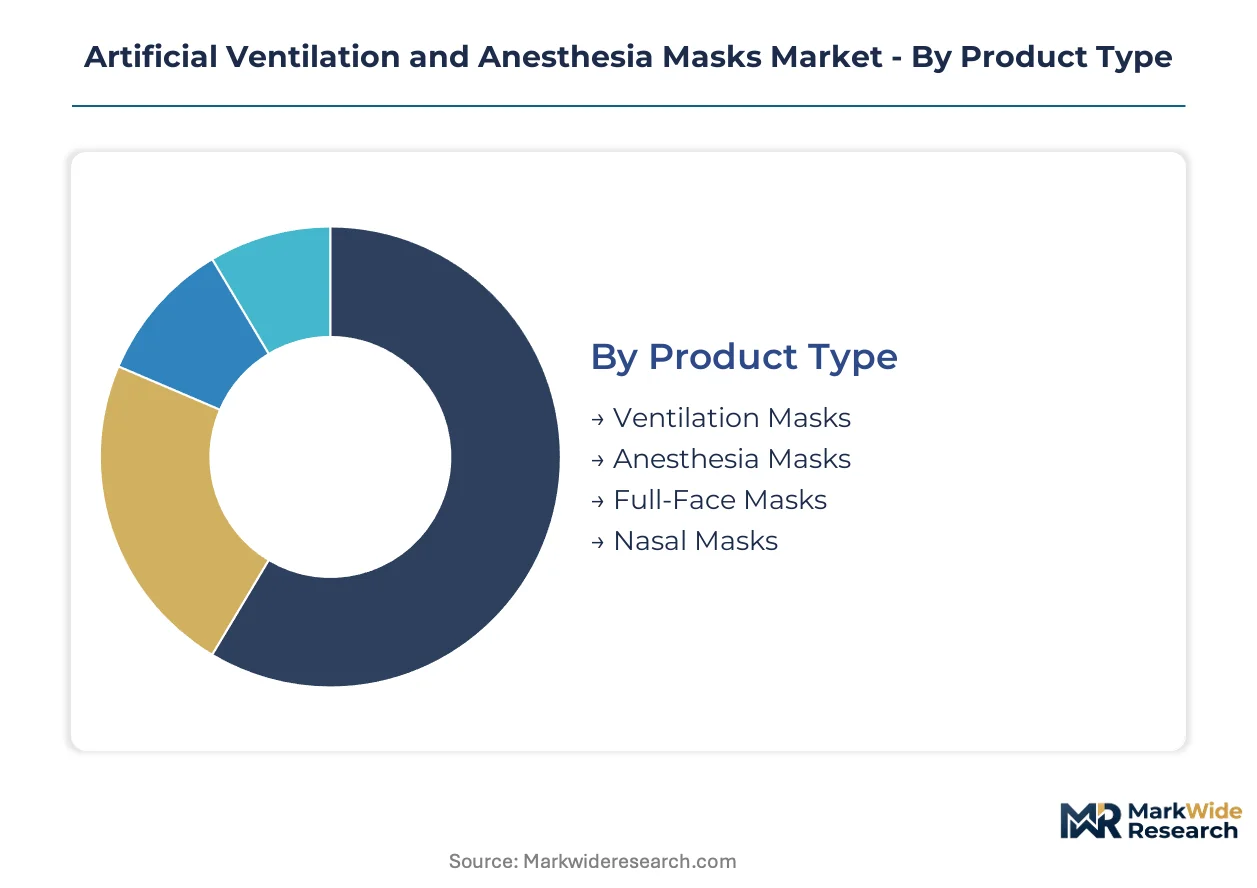
Segmentation in artificial ventilation and anesthesia masks determines regulatory pathway complexity and procurement economics. Material composition and application setting dictate whether manufacturers face Class IIa MDR obligations or streamlined 510(k) clearances.
Product Type:
FDA 510(k) clearance timelines stretch longest for full-face ventilation interfaces due to biocompatibility validation requirements, while nasal configurations benefit from predicate device pathways.
- Ventilation Masks:Designed for non-invasive positive pressure delivery with seal pressures calibrated between 20-60 cm H₂O. Demand concentrates in German and French intensive care units where prolonged wear tolerance drives silicone preference over PVC alternatives.
- Anesthesia Masks:Single-use configurations molded from medical-grade polymers for operative gas delivery. North American surgical suites are converting rapidly from reusable systems amid stricter FDA infection-control mandates for reprocessing validation.
- Full-Face Masks:Silicone elastomer designs dominate high-acuity settings requiring extended non-invasive ventilation support.
- Nasal Masks:Lightweight configurations for domiciliary sleep apnea management.
Leading the category by volume: Ventilation Masks. Growing fastest: Nasal Masks.
Application:
Cost tiers separate emergency disposable deployment from capital-intensive intensive care installations.
- Emergency Care:Rapid-deployment single-use masks stocked in crash carts and field resuscitation kits. Demand clusters in North American hospital emergency departments where FDA-mandated infection protocols prohibit reusable alternatives.
- Surgical Procedures:Anesthesia delivery interfaces requiring precise gas mixture control and aspiration prevention. European operating theaters are standardizing on silicone systems that withstand repeated sterilization cycles under MDR post-market surveillance obligations.
- Intensive Care:Prolonged non-invasive ventilation interfaces with pressure injury mitigation features.
- Home Care:Sleep apnea and chronic respiratory support devices distributed through domiciliary channels.
Highest procurement spend: Surgical Procedures. Steepest expansion trajectory: Home Care.
End User:
Customer type determines contract structure — GPO-negotiated system agreements versus individual clinic purchasing.
- Hospitals:Integrated delivery networks in Texas and Florida are unbundling mask procurement from anesthesia machine service contracts, negotiating direct manufacturer agreements that displace traditional distributor markups.
- Clinics:Ambulatory surgical centers face substitution pressure from laryngeal mask airways in select procedures.
- Home Healthcare:Domiciliary providers managing sleep apnea therapy across North American outpatient channels.
- Research Labs:Specialized configurations for preclinical and clinical trial applications.
Dominant volume share: Hospitals. Gaining share fastest: Home Healthcare.
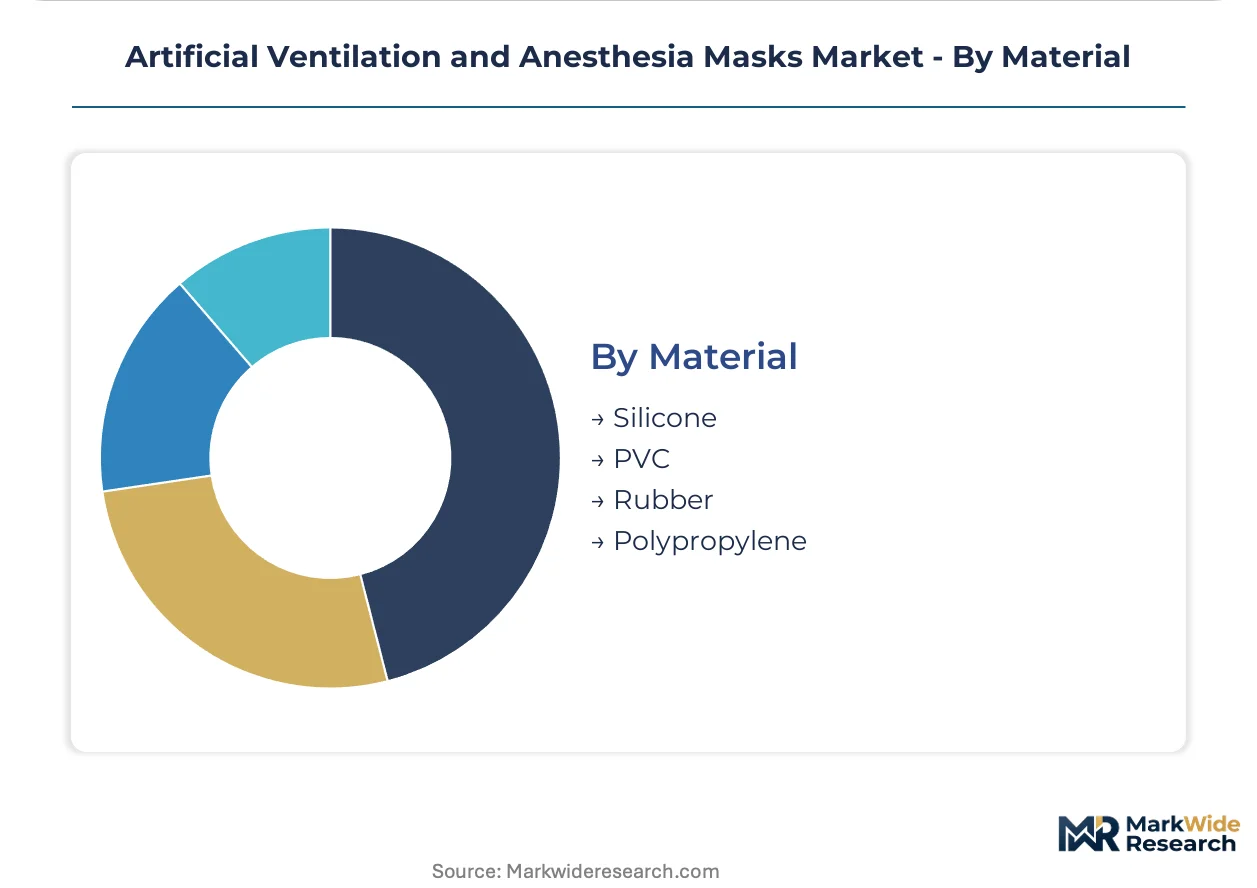
Material:
Margin structure diverges sharply between platinum-cured silicone grades and commodity polymer alternatives.
- Silicone:Biocompatible elastomers commanding premium positioning in surgical and intensive care applications. German university hospitals specifically require ISO 18562-validated silicone grades for prolonged patient contact.
- PVC:Cost-optimized polymers for high-volume disposable deployment in emergency and standard anesthesia applications.
- Rubber:Legacy elastomer formulations with declining utilization amid silicone substitution.
- Polypropylene:Rigid components for mask frames and connector housings.
Highest value concentration: Silicone. Expanding most quickly: Polypropylene in component applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American respiratory device engineering, with Medtronic's headquarters driving silicone molding R&D and FDA 510(k) validation protocols for intensive care ventilation interfaces.
United States
Integrated delivery networks in Texas and Florida unbundle mask procurement from anesthesia machine service contracts, negotiating direct manufacturer agreements. FDA infection-control mandates for reusable device reprocessing validation accelerate hospital conversion to single-use systems. Minneapolis and Irvine clusters concentrate silicone cleanroom manufacturing and predicate device engineering.
Germany
University hospitals in Baden-Württemberg and Bavaria standardize on ISO 18562-validated silicone full-face masks for prolonged non-invasive ventilation. EU MDR Class IIa certification timelines and post-market surveillance obligations elevate entry barriers. Tübingen and Freiburg medical clusters drive biocompatibility validation protocols for intensive care applications.
France
Regional hospital groups in Île-de-France and Auvergne-Rhône-Alpes accelerate single-use anesthesia mask adoption to bypass reusable device regulatory complexity. ANSM vigilance requirements extend clinical evidence obligations for material degradation tracking. Lyon and Grenoble surgical hubs concentrate procurement standardization committees.
India
Tier-2 and tier-3 cities present expansion potential as CDSCO regulatory harmonization accelerates import substitution. Maharashtra and Gujarat manufacturing corridors develop domestic silicone molding capabilities for anesthesia delivery interfaces. Mumbai and Ahmedabad clusters scale ISO 13485-certified production for hospital procurement.
China
NMPA medical device registration reform streamlines market access for ventilation interfaces in Yangtze River Delta hospital systems. Shanghai and Suzhou industrial zones concentrate polypropylene component molding and connector housing production. Domestic manufacturers scale captive silicone supply chains for intensive care applications.
Artificial Ventilation and Anesthesia Masks Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across material platforms and regulatory pathways. The market structures around three tiers: integrated respiratory care conglomerates with captive silicone molding, disposable-focused specialists with single-use portfolios, and regional fabricators serving price-sensitive procurement. Dominant competitive moves include backward integration into medical-grade silicone supply and direct-to-provider distribution contracts that displace traditional GPO intermediaries.
Among diversified health technology conglomerates, Medtronic and Koninklijke Philips N.V. occupy positions defined by vertical scope across respiratory care ecosystems. Drägerwerk AG & Co. KGaA exemplifies the European engineering-intensive archetype with deep anesthesia workstation integration. Ambu A/S represents the single-use disposable specialist model, while ResMed anchors the domiciliary sleep apnea channel with nasal mask configurations.
| Leading Market Players |
|---|
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| ResMed |
| BD |
| Ambu A/S |
| Hamilton Medical |
| Vyaire Medical |
| Teleflex Incorporated |
| Others |
Supply Flow & Price Mechanics
Hospital group purchasing organization consolidation in Texas and Florida is forcing manufacturers to absorb distributor margin compression while maintaining ISO 13485-certified cleanroom production standards. This procurement centralization elevates pricing power for suppliers with captive silicone molding capabilities and direct-to-provider contract structures.
Pricing Analysis
Outcome-based pricing anchors procurement decisions for prolonged intensive care ventilation, with German university hospitals paying premium rates for ISO 18562-validated silicone grades that reduce pressure injury incidence. Three-tier pricing structure across premium silicone, standard PVC, and economy polypropylene configurations separates procurement tiers by certification level and wear tolerance. Cost compression in the PVC disposable segment is intensifying because of medical-grade polymer feedstock volatility and single-use mandate compliance costs. Ambulatory surgical centers exhibit highest price sensitivity, while integrated delivery networks in North American acute care settings prioritize biocompatibility certification over unit cost.
Supply Chain Analysis
Direct-to-provider channels handle integrated delivery network demand in the United States, while traditional medical device distributors serve fragmented clinic and home healthcare segments. Manufacturing concentrates in Germany, the United States, and China, with silicone elastomer compounding anchored in German chemical corridors and polypropylene component molding scaling in Shanghai-Suzhou industrial zones. Raw material dependencies include platinum-cured silicone elastomers, medical-grade PVC resins, and polypropylene feedstocks. Single-source vulnerability in platinum catalyst supply creates exposure for premium mask manufacturers. Distribution runs through hospital system GPO contracts, anesthesia machine OEM bundling, and domiciliary equipment providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU MDR Class IIa certification timelines and post-market surveillance obligations construct barrier-to-entry moats that favor incumbents with established regulatory affairs infrastructure.
For Market Incumbents: Acquire captive silicone compounding assets to secure supply chain control over platinum-cured elastomer grades and neutralize raw material volatility exposure. Consolidate hospital system GPO contracts in Texas and Florida to displace distributor intermediaries and capture margin compression. Laryngeal mask airway substitution in ambulatory surgical centers threatens mask ventilation volumes, requiring defensive certification investment in supraglottic device adjacencies. For New Entrants and Emerging Players: Begin with tier-2 and tier-3 Indian hospital procurement channels where CDSCO regulatory harmonization accelerates import substitution and incumbent presence remains limited. Target domiciliary sleep apnea nasal mask configurations as the most penetrable segment, bypassing intensive care silicone validation complexity. Pursue direct-to-provider distribution partnerships with Maharashtra and Gujarat hospital groups to circumvent established distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with single-use disposable specialists given FDA infection-control mandate acceleration and reusable device reprocessing validation burden. Long-term viability favors manufacturers with backward integration into medical-grade silicone supply and ISO 13485-certified cleanroom infrastructure. Watch FDA guidance evolution on reusable mask reprocessing substantiation as inflection indicator for single-use conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for novel silicone full-face designs in acute care settings. |
| CE Marking Pathway | Validates EU MDR Class IIa compliance for German and French hospital procurement. |
| Hospital System Partnership | Secures direct-to-provider contracts with Texas and Florida integrated delivery networks. |
| Software Companion Development | Enables mask fit monitoring and pressure injury prediction for intensive care applications. |
| Reimbursement Strategy | Aligns domiciliary nasal mask pricing with CMS Medicare sleep apnea therapy codes. |
Methodological Framework
Independent corroboration across hospital procurement databases, GPO contract filings, and FDA 510(k) clearance records underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, anesthesia department heads, and GPO contracts managers combined with secondary validation from EMA submissions, CDSCO registration data, and ISO certification registries. Bottom-up demand modeling triangulates against top-down market sizing across material grade, application setting, and end-user type.
Rate-of-change decomposition separates volume expansion from price mix effects across the analysis window. Segmentation dimensions modeled include material composition, product configuration, application acuity level, end-user procurement structure, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, procedure volume trends, and conversion elasticity estimates for single-use adoption. Forecast inputs incorporate silicone elastomer price indices and hospital capital expenditure survey data.
Underlying measurement precision varies by segment; intensive care full-face mask volumes carry tighter precision than domiciliary nasal mask projections given procurement transparency differences. Forecasts reflect assumptions on regulatory enforcement intensity, raw material cost trajectories, and substitution elasticity for supraglottic airway devices. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Airway Management Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Medical Device Tester Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Global 3D Printed Surgical Models Market