
 Bone-Cutting Technologies Market | 2026-2036
Bone-Cutting Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Bone-Cutting Technologies Market Analysis
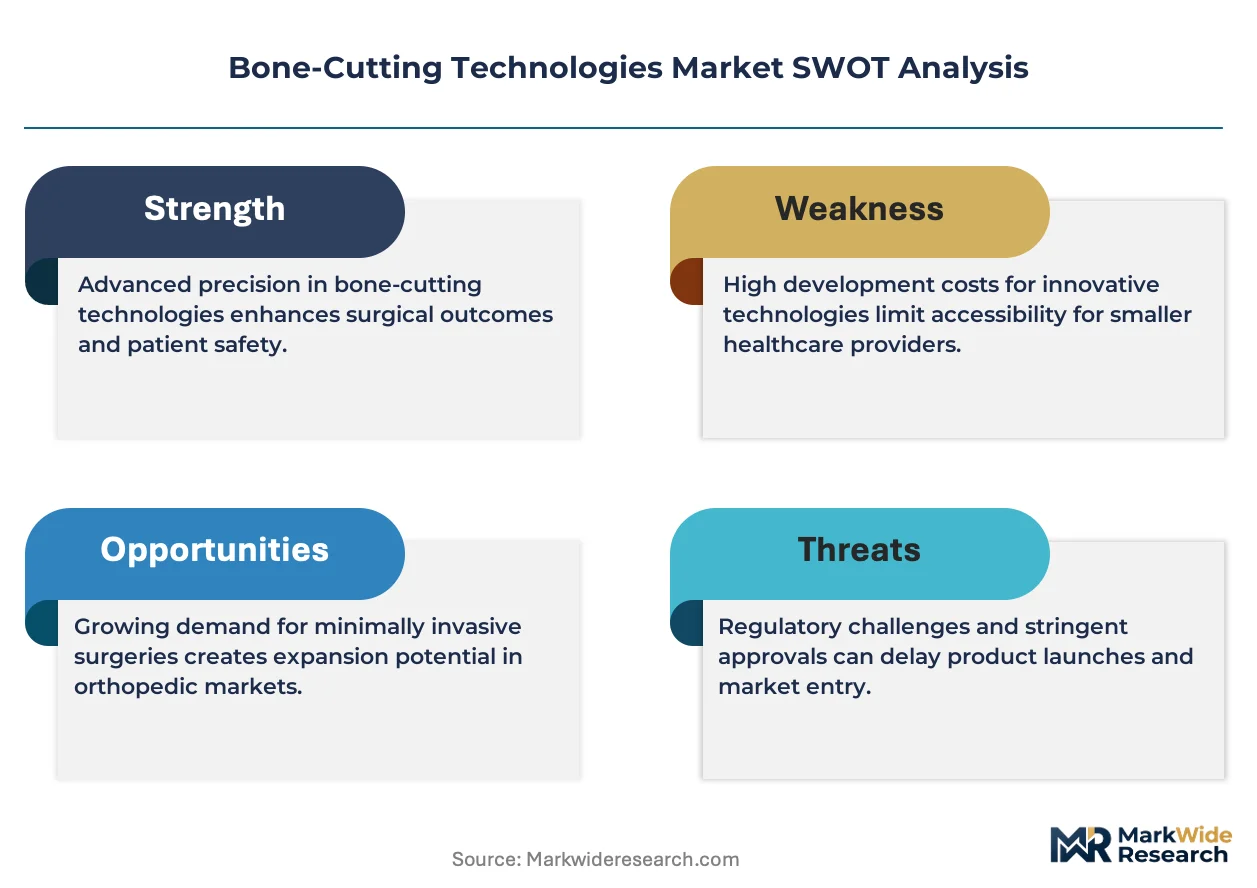
Capital-intensity divergence between integrated platform developers and single-product manufacturers is bifurcating competitive dynamics in bone-cutting technologies. Stryker Corporation leverages its end-to-end surgical ecosystem to bundle cutting instruments with navigation systems, locking in hospital procurement cycles. Medtronic plc anchors its position through deep R&D investment in powered instruments, sustaining technology leadership across mechanized and ultrasonic modalities. Zimmer Biomet Holdings, Inc. differentiates via specialized orthopedic applications, dominating revision arthroplasty procedures where cutting precision directly impacts implant longevity.
Bone-cutting technologies encompass powered and non-powered instruments engineered to section osseous tissue with controlled depth, temperature, and kerf width, typically operating at blade speeds of 15,000–30,000 rpm or ultrasonic frequencies of 20–60 kHz to minimize thermal necrosis. These systems serve primarily to enable precise osteotomy, resection, and graft preparation across surgical disciplines where structural integrity and healing outcomes depend on cut quality. Oscillating saws retain the largest installed base in joint replacement workflows, though ultrasonic cutting is gaining fastest in spinal and cranial applications where soft-tissue preservation commands premium positioning. Thermal cutting modalities face margin compression as electrosurgery and ultrasonic alternatives displace legacy devices in hospital capital budgets, while laser cutters occupy niche roles in dental implantology and microsurgical bone sculpting.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements are elevating barrier costs for new entrants, forcing consolidation around established quality management systems. ISO 13485 certification and IEC 60601 electrical safety standards now function as baseline predicates for commercial access across North America and Europe. Stakeholders must monitor how notified body capacity constraints and evolving biocompatibility testing protocols reshape product development timelines and geographic launch sequencing.
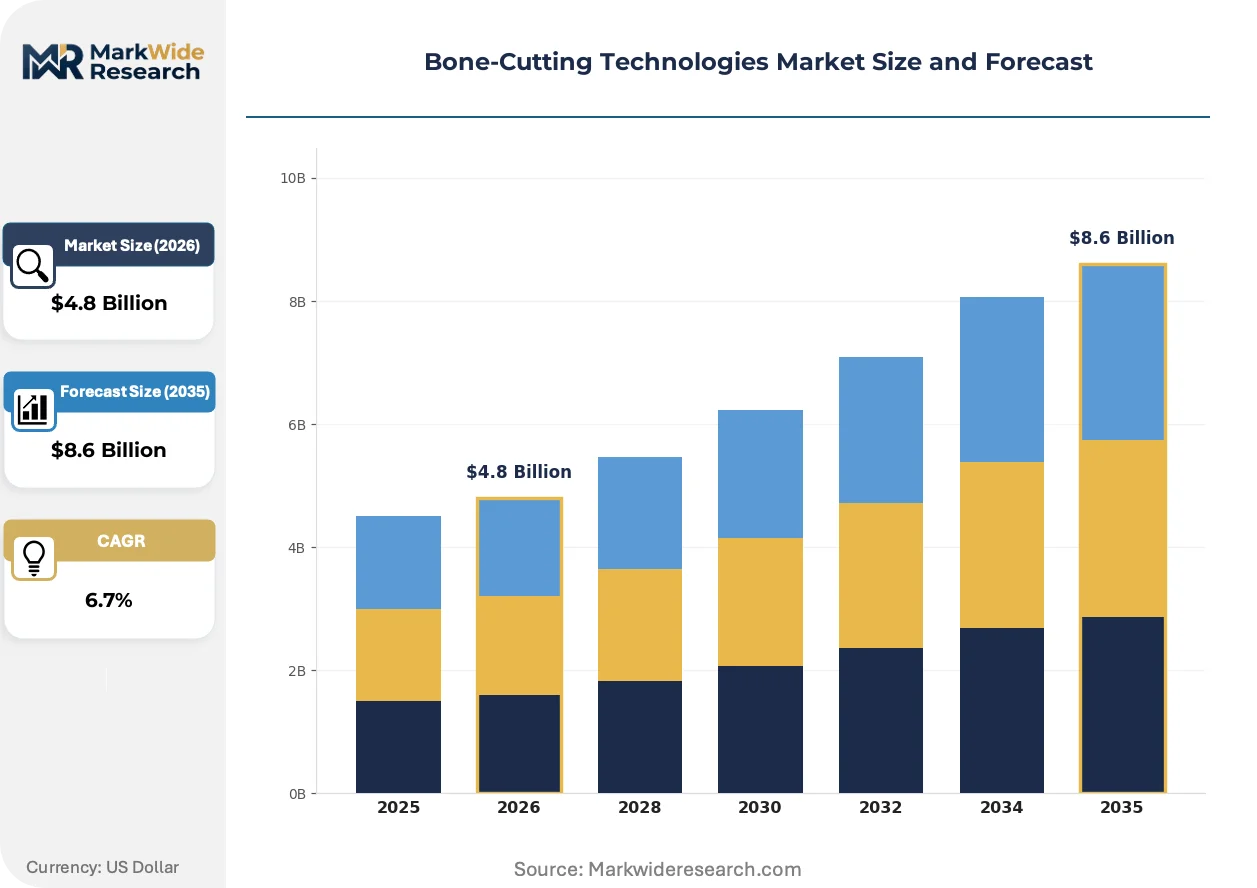
Market Dynamics
Hospital procurement consortia in Germany are consolidating purchasing power around integrated surgical platforms, forcing single-product manufacturers into price compression while rewarding end-to-end ecosystem providers with multi-year contract locks.
Growth Catalysts
- EU MDR Conformity Assessments:Tighter technical documentation requirements are filtering out marginal competitors and concentrating demand among ISO 13485-certified suppliers with established quality management systems.
- Revision Arthroplasty Procedures:Aging implant populations in developed healthcare systems are generating surgical volume where cutting precision directly determines implant longevity and revision survival rates.
- Ultrasonic Frequency Modulation:Advancement in 20–60 kHz transducer control is expanding soft-tissue preservation capabilities beyond spinal applications into cranial and maxillofacial surgical workflows.
Market Restraints
- Notified Body Capacity Constraints:EU MDR implementation has created bottlenecks in conformity assessment availability, extending product launch timelines by 12–18 months for non-priority device categories.
- Tungsten Carbide Supply Concentration:Cutting blade substrate sourcing depends on concentrated Chinese raw material processing, exposing manufacturers to export restriction volatility and input cost spikes.
- Thermal Necrosis Risk in Legacy Modalities:Oscillating saw systems operating above 30,000 rpm generate localized temperatures exceeding 47°C, driving liability exposure and accelerating displacement by ultrasonic alternatives.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentive structures are attracting contract manufacturing investment for export-oriented bone-cutting instrument production serving Middle East and Southeast Asian markets.
- AI-Assisted Cutting Path Planning:Integration of preoperative imaging segmentation with real-time navigation is creating premium positioning for systems that reduce operative time and varus/valgus alignment errors.
- Ambulatory Surgery Center Channel:Migration of joint replacement procedures to outpatient settings in the US is opening demand for compact, single-procedure cutting systems with simplified sterilization protocols.
Industry Challenges
- IEC 60601-1-2 Electromagnetic Compatibility Testing:Powered instrument manufacturers face escalating validation costs for wireless connectivity features and battery management systems in next-generation devices.
- Biocompatibility Protocol Evolution:ISO 10993-18 chemical characterization requirements are forcing reformulation of cutting surface coatings and lubricants, triggering supply chain requalification cycles.
- Legacy Navigation System Interoperability:Proprietary data protocols between cutting instruments and surgical navigation platforms create integration friction for hospitals with mixed-vendor installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone-Cutting Technologies Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oscillating Saws, Reciprocating Saws, Band Saws, Laser Cutters Application: Orthopedic Surgery, Dental Procedures, Neurosurgery, Veterinary Surgery Technology: Mechanized Systems, Ultrasonic Cutting, Thermal Cutting, Electrosurgery End User: Hospitals, Clinics, Research Facilities, Surgical Centers |
| Companies Covered | Medtronic plc, Stryker Corporation, Zimmer Biomet Holdings, Inc., Johnson & Johnson, Smith & Nephew plc, Globus Medical, Inc., B. Braun Melsungen AG, Intuitive Surgical, Inc., DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone-Cutting Technologies Market Emerging Trajectories
Active energy modality selection is splitting surgical workflows into distinct technology camps, with thermal cutting facing systematic displacement while ultrasonic systems capture premium positioning in precision-sensitive applications.
Ultrasonic bone cutting is bifurcating the powered instrument market by surgical discipline. Spinal and neurosurgical teams at academic medical centers are adopting 20–60 kHz systems for their soft-tissue sparing profiles. This modality split is compressing R&D budgets at legacy oscillating-saw manufacturers while enabling premium pricing for integrated ultrasonic platforms with real-time impedance feedback.
EU MDR technical documentation requirements are elevating barrier costs for new market entrants. The regulation mandates clinical evidence standards previously reserved for higher-risk device classes, forcing consolidation around established notified body relationships. Small and mid-sized manufacturers without dedicated regulatory affairs functions are exiting the European market or pursuing acquisition by larger platform holders.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases. German hospital consortia now negotiate cutting instrument supply agreements separately from maintenance and training services, compressing vendor margins on attach revenue. This purchasing pattern is most visible in North Rhine-Westphalia and Bavaria, where integrated delivery networks command sufficient volume to enforce service commoditization.
Bone-Cutting Technologies Market Segmentation
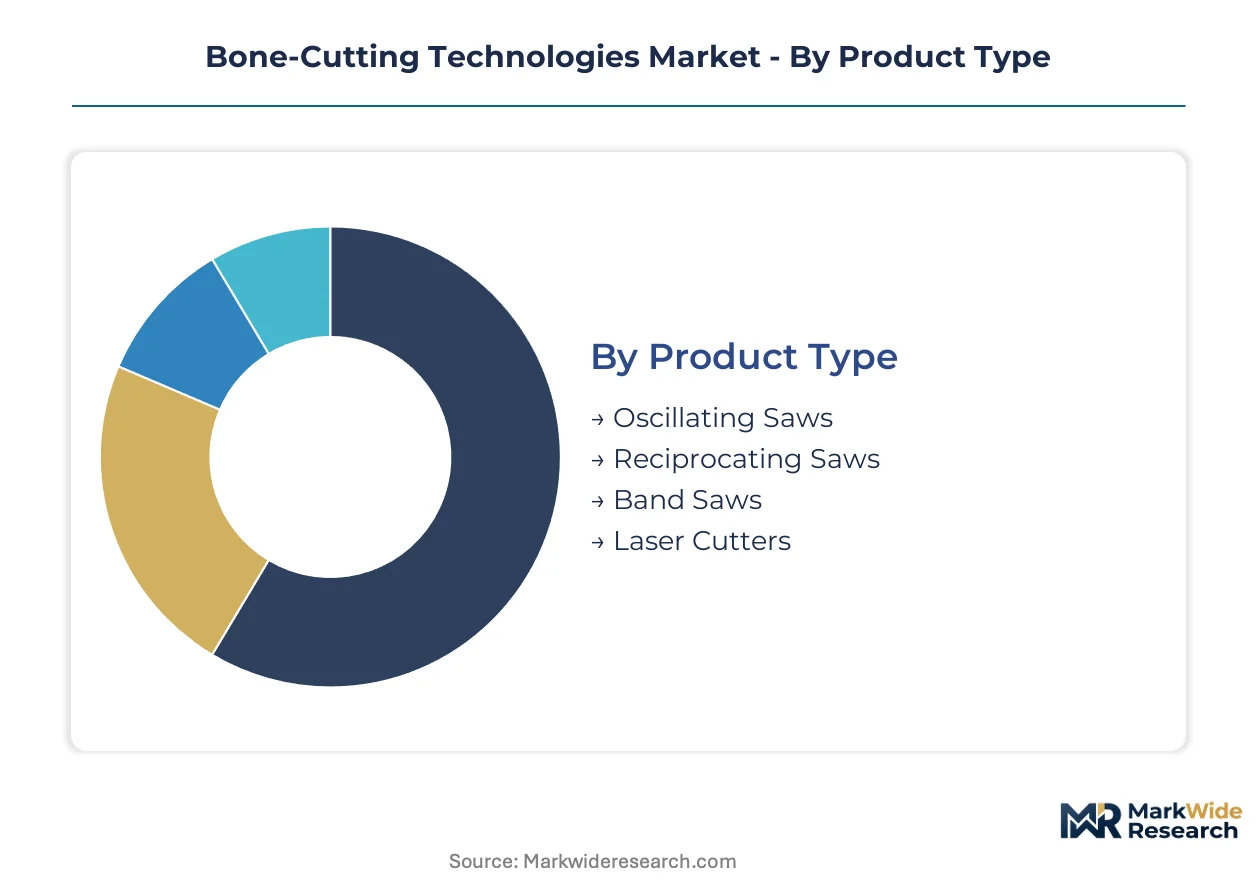
Segmentation in bone-cutting technologies reveals how substitution pressures and regulatory pathways reshape competitive positioning across instrument categories. Understanding where ultrasonic modalities displace legacy systems, which surgical disciplines drive premium pricing, and how end-user consolidation alters channel economics enables targeted resource allocation for technology developers and distribution strategists.
Product Type:
Substitution pressure from ultrasonic alternatives and laser systems is fragmenting the powered instrument market, with legacy saw technologies facing margin compression while precision modalities capture premium positioning in academic medical centers.
- Oscillating Saws:Blade systems operating at 15,000–30,000 rpm with reciprocating circular motion dominate joint replacement workflows. Demand concentrates in German hospital procurement consortia where multi-year contracts for integrated platforms lock in oscillating instrument supply, though thermal necrosis liability is accelerating displacement in spinal applications.
- Reciprocating Saws:Linear-stroke cutting instruments engineered for long-bone resection and trauma procedures. German orthopedic surgery departments at academic medical centers favor these systems for revision arthroplasty where cutting precision directly impacts implant longevity, sustaining volume despite ultrasonic encroachment in adjacent segments.
- Band Saws:Continuous-loop blade systems for large-scale osteotomy and graft preparation.
- Laser Cutters:Focused-beam modalities for microsurgical bone sculpting in dental implantology and cranial applications.
Oscillating saws anchor the volume base while laser cutters gain share at the steepest rate.
Application:
Cost tier stratification separates high-acuity hospital procedures from outpatient settings, with reimbursement differentials driving technology selection and capital equipment investment intensity.
- Orthopedic Surgery:Joint replacement, trauma fixation, and revision arthroplasty procedures requiring controlled osteotomy depth and kerf width. German hospital procurement consortia in North Rhine-Westphalia and Bavaria concentrate demand for integrated cutting platforms, unbundling after-sales service contracts to compress vendor margins on attach revenue.
- Neurosurgery:Cranial and spinal procedures where soft-tissue preservation commands premium positioning. Academic medical centers in Germany are adopting 20–60 kHz ultrasonic systems for impedance feedback capabilities, creating the steepest expansion trajectory among application segments as thermal cutting modalities face systematic displacement.
- Dental Procedures:Implant site preparation and alveolar ridge modification in outpatient settings.
- Veterinary Surgery:Companion animal orthopedic and dental applications with simplified regulatory pathways.
Orthopedic surgery anchors the volume base while neurosurgery climbs the fastest as ultrasonic penetration deepens.
Technology:
Supply concentration in transducer manufacturing and Chinese tungsten carbide processing is reshaping margin structures across mechanized and energy-based modalities.
- Ultrasonic Cutting:20–60 kHz transducer systems with real-time impedance feedback for soft-tissue sparing. German spinal and neurosurgical teams at academic medical centers are driving adoption, enabling premium pricing for integrated platforms as oscillating-saw manufacturers compress R&D budgets in response.
- Mechanized Systems:Electric and pneumatic powered instruments with established ISO 13485 quality management systems. FDA 510(k) clearance pathways and EU MDR technical documentation requirements elevate barrier costs, filtering out marginal competitors and concentrating demand among certified suppliers.
- Thermal Cutting:Legacy modalities facing margin compression as electrosurgery and ultrasonic alternatives displace devices in hospital capital budgets.
- Electrosurgery:Radiofrequency and plasma-based bone sectioning with niche positioning in specific orthopedic workflows.
Mechanized systems anchor the volume base while ultrasonic cutting expands most quickly through academic medical center adoption.
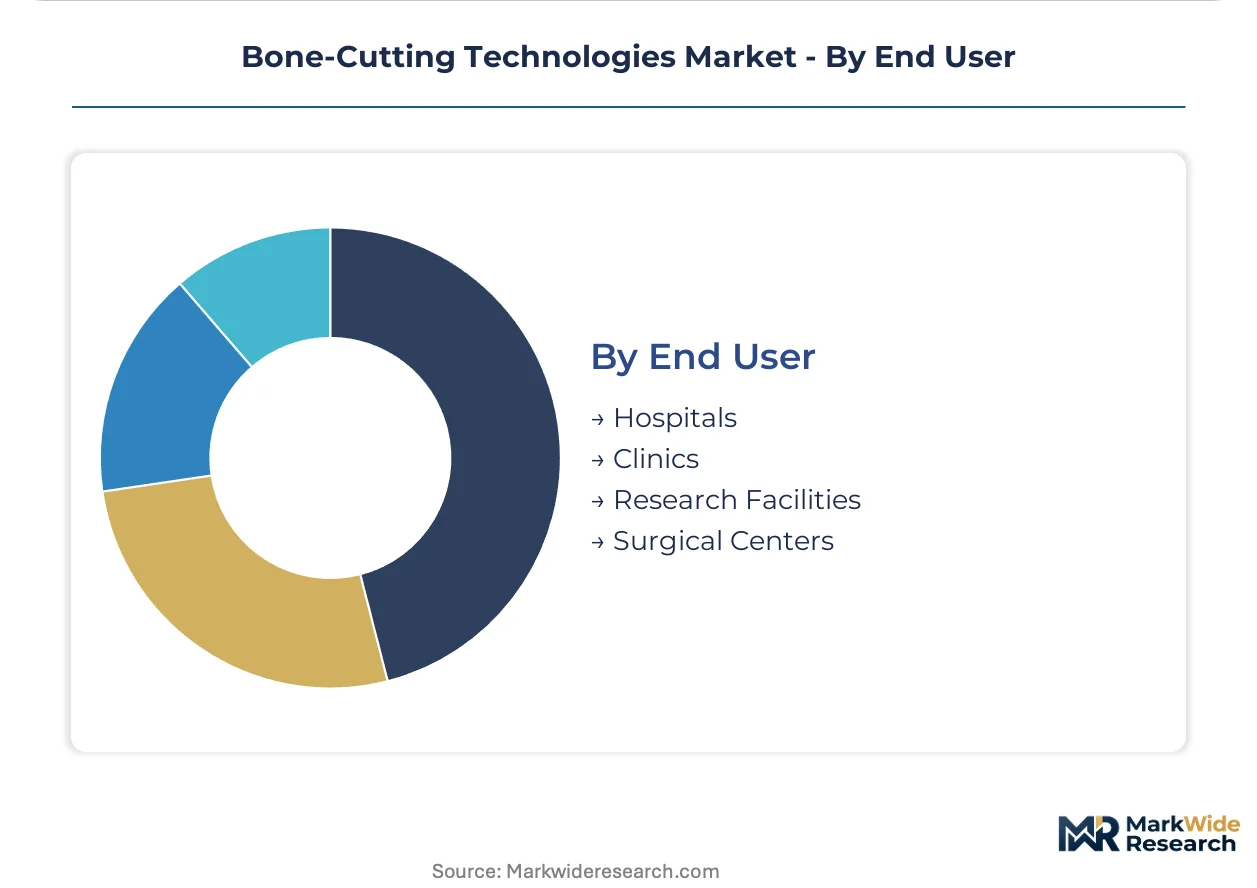
End User:
Customer type fragmentation reflects divergent purchasing authority, with integrated delivery networks wielding consolidated power against single-product manufacturers.
- Hospitals:Tertiary and academic medical centers with capital equipment procurement committees and multi-year contract frameworks. German hospital consortia are consolidating purchasing power around integrated surgical platforms, forcing single-product manufacturers into price compression while rewarding end-to-end ecosystem providers.
- Surgical Centers:Ambulatory settings where migration of joint replacement procedures to outpatient environments in the US is opening demand for compact, single-procedure cutting systems with simplified sterilization protocols.
- Clinics:Private practice and specialty outpatient facilities with limited capital budgets.
- Research Facilities:Academic and preclinical testing centers for device validation and training.
Hospitals anchor the volume base while surgical centers gain share fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German hospital procurement consortia while US ambulatory surgery centers compress margins through unbundled purchasing. This asymmetry shapes where manufacturers prioritize integrated platform sales versus single-instrument volume plays.
Germany
Academic medical centers in North Rhine-Westphalia and Bavaria drive demand for precision cutting systems with navigation integration. EU MDR conformity assessments through notified bodies like TÜV SÜD extend product launch timelines, filtering out uncertified suppliers. Hospital procurement consortia in these states unbundle after-sales service contracts, forcing vendors to compete on instrument pricing alone.
United States
Migration of joint replacement procedures to outpatient settings fuels demand for compact, single-procedure cutting systems. FDA 510(k) clearance pathways elevate barrier costs for new entrants lacking established quality management systems. Ambulatory surgery centers in Florida and Texas prioritize simplified sterilization protocols over capital-intensive integrated platforms.
China
Domestic production capacity for tungsten carbide cutting substrates concentrates in Hunan and Jiangxi provinces, exposing manufacturers to export restriction volatility. NMPA medical device registration requirements tighten clinical evidence standards for powered instruments. Shanghai and Beijing academic hospitals anchor adoption of ultrasonic systems for spinal applications.
India
PLI scheme incentives attract contract manufacturing investment for export-oriented instrument production serving Middle Eastern markets. CDSCO medical device rules mandate quality management system certification for Class B and above devices. Gujarat and Maharashtra host emerging clusters of precision instrument fabricators targeting Southeast Asian distribution.
Japan
Aging implant populations generate revision arthroplasty volume where cutting precision determines implant longevity. PMDA premarket approval timelines for novel energy modalities exceed 24 months, favoring incremental improvements over breakthrough technologies. Osaka and Nagoya medical device clusters concentrate mechanized system manufacturing for domestic orthopedic workflows.
Bone-Cutting Technologies Market Vendor Landscape
Concentration sits with diversified surgical platform developers possessing end-to-end ecosystem capabilities. The vendor base stratifies across three tiers: integrated platform holders commanding multi-year hospital contracts, specialized orthopedic instrument manufacturers dominating revision procedures, and regional fabricators competing on price in emerging markets. Strategic moves center on regulatory consolidation through notified body capacity capture and backward integration into transducer manufacturing.
Among diversified platform developers, Medtronic plc and Stryker Corporation exemplify the ecosystem archetype, anchoring competitive positioning through bundled instrument-navigation offerings. Zimmer Biomet Holdings, Inc. occupies a specialist position within orthopedic applications, particularly where cutting precision interfaces with implant longevity outcomes.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Johnson & Johnson |
| Smith & Nephew plc |
| Globus Medical, Inc. |
| B. Braun Melsungen AG |
| Intuitive Surgical, Inc. |
| DePuy Synthes |
| Others |
Supply Flow & Price Mechanics
Multi-year service bundling contracts lock in German hospital procurement consortia to predictable instrument supply costs while insulating integrated platform vendors from spot-price volatility in tungsten carbide substrates. This contractual architecture concentrates pricing power with ecosystem providers possessing captive blade manufacturing capabilities.
Pricing Analysis
The customization-premium spread separates configured-to-order ultrasonic platforms with impedance feedback modules from standard oscillating saw configurations. Three-tier pricing structure across premium navigation-integrated systems, standard mechanized instruments, and economy disposable blade contracts dominates hospital procurement. Cost compression in economy tiers intensifies because Chinese tungsten carbide export restrictions feed raw material uncertainty into spot purchasing. Ambulatory surgery centers in US outpatient settings exhibit highest price sensitivity, while German academic medical centers absorb premium positioning for precision-critical revision arthroplasty workflows.
Supply Chain Analysis
Inventory buffers for transducer assemblies and cutting blade substrates extend lead times when Hunan and Jiangxi province export controls disrupt tungsten carbide flow. Manufacturing concentration centers on China for raw material processing, Germany for precision instrument fabrication, and India for contract assembly under PLI scheme incentives. Supply chains draw from tungsten carbide substrates, piezoelectric transducer ceramics, and surgical-grade stainless steel. Single-source vulnerability in Chinese rare earth processing for transducer magnets exposes downstream assemblers to quota restrictions. Distribution runs through hospital procurement consortia in developed markets and regional distributors in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bone-cutting technologies sit in early-cycle expansion as ultrasonic modality penetration accelerates beyond spinal applications into cranial and maxillofacial precision workflows. This technology migration creates asymmetric opportunity for stakeholders positioned at the modality frontier.
For Market Incumbents: Secure notified body capacity through exclusive assessment contracts before EU MDR bottlenecks extend conformity timelines further. Deepen backward integration into transducer manufacturing to offset Chinese magnet supply volatility. Lock in multi-year service contracts with German hospital consortia before procurement departments complete unbundling of maintenance agreements.
For New Entrants and Emerging Players: Lead with AI-assisted cutting path planning software as the attach wedge into ambulatory surgery center workflows. Target US outpatient joint replacement migration where compact single-procedure systems face limited integrated platform competition. Pursue CDSCO quality certification for Gujarat-based contract manufacturing serving Middle Eastern distribution.
For Investors and Strategic Acquirers: Specialized ultrasonic transducer developers with ISO 13485 certification and existing notified body relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on modality substitution curves favoring soft-tissue sparing technologies over legacy thermal cutting. Monitor FDA 510(k) clearance velocity for ultrasonic platforms as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway Acceleration | Notified body capacity capture through TÜV SÜD partnerships shortens German market entry timelines. |
| Backward Integration into Transducer Manufacturing | In-house piezoelectric ceramic production insulates margin structures from Chinese supply volatility. |
| Ambulatory Surgery Center Channel Development | Compact sterilization-protocol systems capture US outpatient joint replacement volume migration. |
| AI-Assisted Navigation Software Companion | Preoperative segmentation integration reduces varus/valgus alignment errors in revision arthroplasty. |
| India PLI Scheme Manufacturing Footprint | Gujarat-based precision fabrication targets Middle Eastern and Southeast Asian export demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries. Primary interviews spanned biomedical engineers at academic medical centers, GPO contracts managers, regulatory affairs leads at notified bodies, and orthopedic surgeons performing revision arthroplasty. Secondary validation drew from ISO 13485 certification records, customs trade data for tungsten carbide substrates, and CMS Medicare procedure volume statistics. Bottom-up instrument shipment analysis triangulates against top-down healthcare capital expenditure tracking.
Segmentation dimensions modeled include energy modality, surgical discipline, end-user facility type, and geographic regulatory cluster across the projection horizon. CAGRs derive from procedure volume elasticity to aging implant populations, technology substitution curves between mechanized and ultrasonic systems, and capital equipment replacement cycles. Forecast inputs incorporate EU MDR implementation pace, ambulatory surgery center reimbursement policy shifts, and tungsten carbide export quota trajectories.
Underlying assumptions cover stable notified body assessment capacity, continued US outpatient migration for joint replacement, and unimpeded Chinese rare earth processing, with deviation risk concentrated in regulatory timeline extensions and raw material trade restrictions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Venturi Mask Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Brachytherapy Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Medical Radiation Detectors Market