
 Stool Management Systems Market | 2026-2036
Stool Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Stool Management Systems Market Analytics
European medical device manufacturing capacity is expanding across Germany and Denmark as producers respond to post-MDR certification timelines. B. Braun Melsungen AG leverages its integrated sterilization and catheter production infrastructure to dominate Central European hospital procurement. Medtronic anchors North American distribution through its direct sales force targeting level-one trauma centers. Coloplast A/S specializes in hydrocolloid-based ostomy interfaces that reduce peristomal complications in long-term care.
Stool management systems comprise closed-collection catheter assemblies, external pouches, and suction-assisted evacuation devices engineered to contain fecal output and protect perineal skin integrity in immobilized or incontinent patients. These systems typically incorporate medical-grade silicone or latex-free elastomer tubing rated for 24-72 hour dwell times, with pressure-sensitive adhesive flanges designed to maintain seal integrity under moisture exposure. Automated systems lead inpatient care adoption due to labor savings and reduced cross-contamination risk, while compact systems represent the fastest-growing segment as home care providers seek portable alternatives to institutional equipment. Smart systems embedding digital flow sensors command premium positioning despite limited reimbursement coverage, concentrating margin pools among technology-integrated suppliers.
FDA 510(k) clearance pathways govern U.S. market entry for stool management devices classified as Class II medical devices, while EU MDR technical documentation requirements have extended conformity assessment timelines for non-European applicants. EMA notified body capacity constraints are forcing manufacturers to prioritize CE mark renewals for highest-volume SKUs. Stakeholders must monitor evolving CMS durable medical equipment reimbursement codes and EU Green Deal circular-economy mandates affecting single-use plastic components in disposable collection systems.
Market Dynamics
EU MDR conformity assessment bottlenecks are compressing supplier margins while automated electromechanical platforms capture disproportionate inpatient demand concentration in acute care networks.
Growth Catalysts
- MDR Compliance Deadlines:EU notified body capacity constraints force hospital procurement toward pre-certified suppliers, accelerating consolidation among sterilization-integrated manufacturers in Germany and Denmark.
- Perineal Skin Integrity Protocols:Long-term care facilities adopt closed-collection catheter assemblies rated for extended dwell times to reduce pressure injury incidence and associated litigation exposure.
- Silicone Elastomer Advances:Medical-grade tubing formulations with enhanced moisture resistance enable 72-hour wear protocols, cutting nursing labor hours per patient by eliminating frequent changeout cycles.
Market Restraints
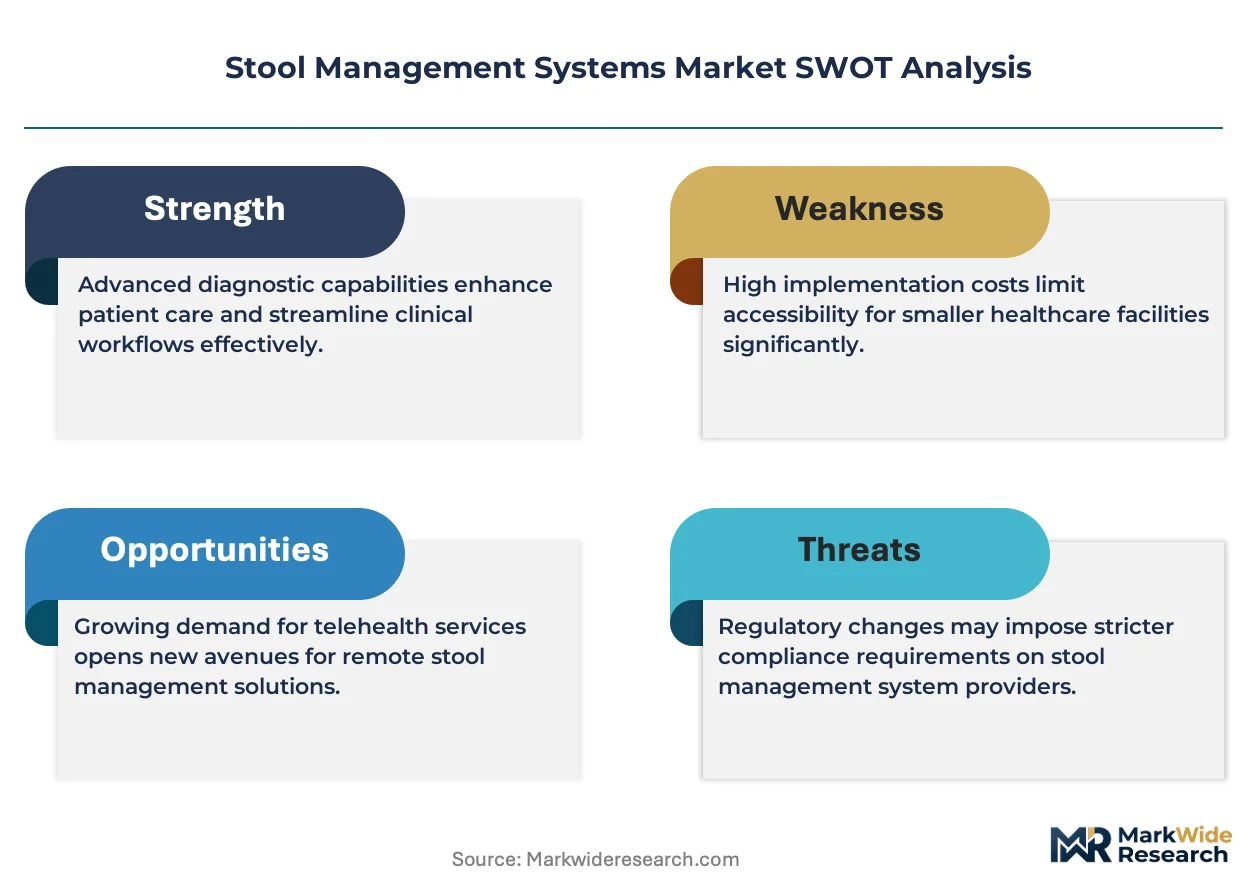
- Notified Body Scarcity:EMA-designated conformity assessment organizations face 18-month backlogs, freezing market entry for non-European applicants lacking legacy CE mark portfolios.
- Single-Use Plastic Mandates:EU Green Deal circular-economy requirements threaten disposable collection system economics, forcing material reengineering investments without guaranteed reimbursement pass-through.
- Home Care Substitution:Compact external pouch systems with manual closure mechanisms compete against automated suction devices on portability, constraining premium pricing power in ambulatory segments.
Strategic Opportunities
- Digital Flow Sensor Integration:Smart systems embedding real-time output monitoring command premium positioning in level-one trauma centers despite limited CMS durable medical equipment code coverage.
- Home Care Channel Expansion:Portable compact systems represent underpenetrated demand as post-acute providers seek alternatives to institutional equipment for aging-in-place populations.
- CE Mark Renewal Prioritization:Manufacturers with highest-volume SKU concentration in Central European hospital networks capture procurement share as competitors face extended technical documentation timelines.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, delaying 510(k) submissions to FDA for novel adhesive flange formulations.
- Legacy System Interoperability:Electromechanical suction platforms require integration with existing hospital bed power and data infrastructure, complicating retrofit deployment in aging acute care facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stool Management Systems Market |
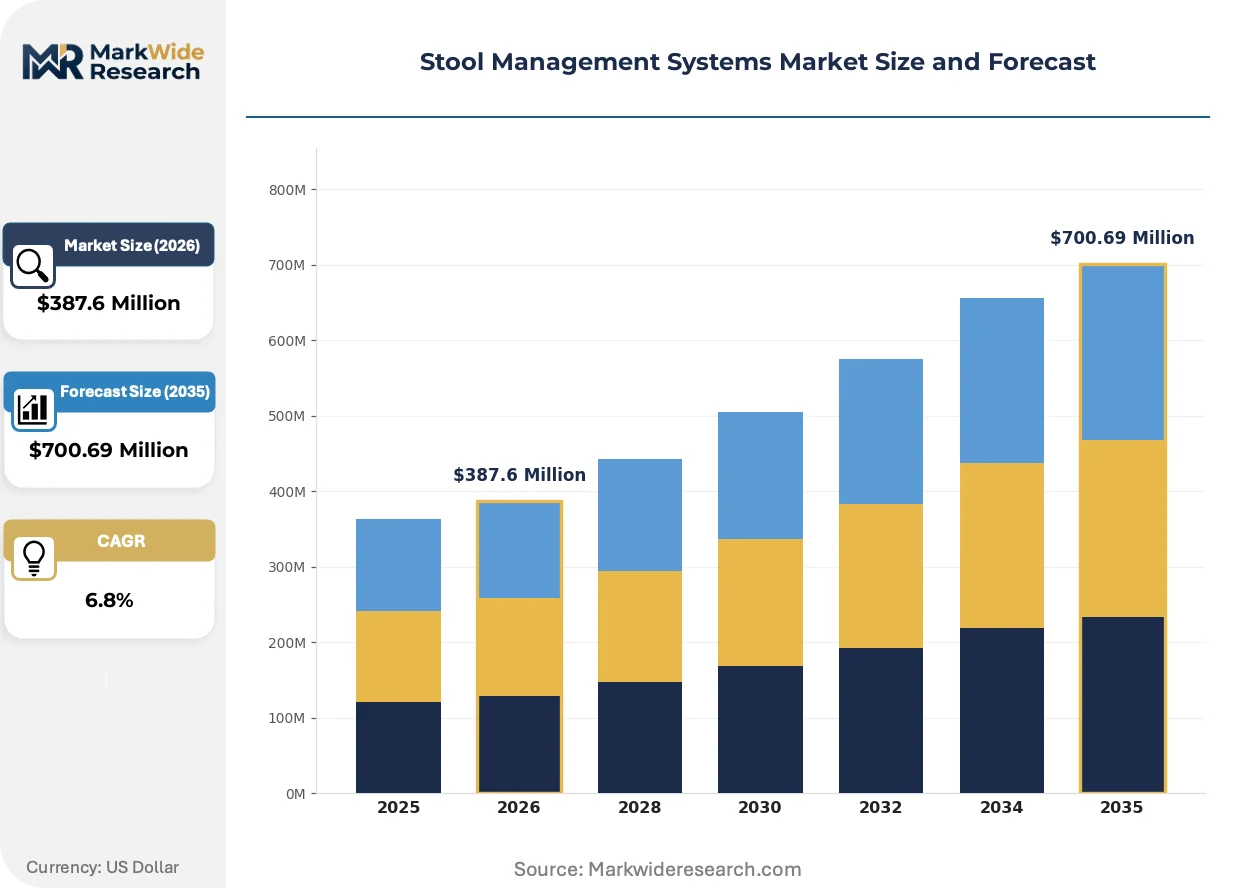
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Compact Systems, Modular Systems End User: Hospitals, Nursing Homes, Home Care Providers, Rehabilitation Centers Technology: Mechanical, Electromechanical, Digital, Smart Systems Application: Inpatient Care, Outpatient Care, Elderly Care, Pediatric Care |
| Companies Covered | B. Braun Melsungen AG, Medtronic, Coloplast A/S, Welland Medical Limited, Axonics Inc., ConvaTec Group PLC, Hollister Incorporated, ProSys International Ltd, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stool Management Systems Market Evolving Landscape
Digital sensing capabilities and material science advances are compressing the boundary between institutional and home-based care, while regulatory documentation burdens reshape competitive entry barriers.
Electromechanical evacuation platforms with integrated pressure regulation and automated flush cycles are rewriting labor economics in intensive care units. Level-one trauma centers in the United States deploy these systems to reduce cross-contamination risk and nursing documentation burden. The technology is compressing differentiation between premium automated and mid-tier manual systems as electromechanical reliability improves.
EU MDR technical documentation requirements have extended conformity assessment timelines beyond historical CE mark renewal cycles. Non-European manufacturers without established EU authorized representatives face frozen market access while German and Danish producers leverage integrated sterilization infrastructure to accelerate certification. Hospital procurement committees in Germany now require MDR-compliant technical files as mandatory bid evaluation criteria.
Home care providers are unbundling after-sales service from equipment acquisition, demanding standalone training and maintenance contracts for compact stool management systems. Durable medical equipment distributors in North America respond with subscription-based support models replacing traditional capital-plus-service bundled pricing. This pattern concentrates margin capture among suppliers with dedicated field clinical specialist networks rather than pure manufacturing operations.
Stool Management Systems Market Segmentation
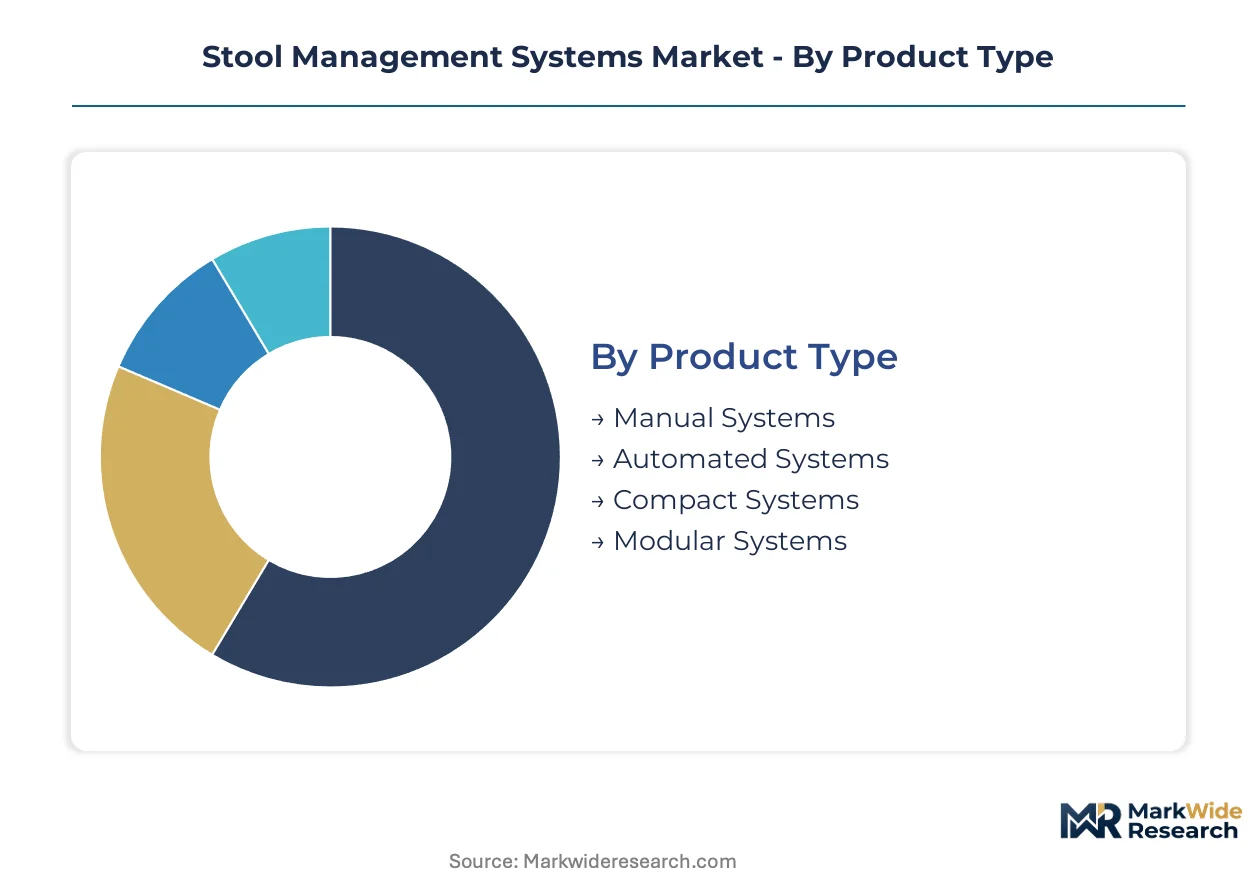
Stool management systems fragment across four intersecting dimensions that determine reimbursement eligibility, procurement workflows, and manufacturing scale economics. Each segmentation axis carries distinct margin profiles and regulatory documentation burdens.
Product Type:
Standardization dominates high-volume hospital procurement while customization concentrates in post-acute and home settings where patient mobility varies.
- Automated Systems:Electromechanical evacuation platforms with integrated pressure regulation and automated flush cycles. Level-one trauma centers in the United States deploy these systems to reduce cross-contamination risk and nursing documentation burden.
- Compact Systems:Portable external pouch assemblies with manual closure mechanisms rated for ambulatory use. Home care providers in Germany seek these alternatives to institutional equipment for aging-in-place populations.
- Manual Systems:Closed-collection catheter assemblies with passive gravity drainage and adhesive flange seals.
- Modular Systems:Interchangeable components allowing upgrade from manual to electromechanical functionality.
Most installed capacity flows through automated systems. Expansion is steepest in compact systems.
End User:
Acute care networks command volume pricing power while long-term care facilities prioritize dwell-time extension to reduce labor hours.
- Hospitals:Centralized procurement committees in Germany now require MDR-compliant technical files as mandatory bid evaluation criteria, freezing out non-certified suppliers.
- Nursing Homes:Facilities adopt closed-collection catheter assemblies rated for extended dwell times to reduce pressure injury incidence and associated litigation exposure.
- Home Care Providers:Distributors respond with subscription-based support models replacing traditional capital-plus-service bundled pricing.
- Rehabilitation Centers:Transitional care settings with mixed acuity patient populations.
Hospital procurement absorbs the majority of electromechanical platform shipments. Rehabilitation centers are gaining share fastest.
Technology:
Digital integration separates premium positioning from commodity replacement cycles across reimbursement tiers.
- Electromechanical:Suction-assisted evacuation devices with automated pressure cycling and occlusion detection algorithms.
- Smart Systems:Platforms embedding real-time output monitoring and predictive maintenance alerts. These command premium positioning despite limited CMS durable medical equipment code coverage.
- Mechanical:Passive drainage systems without powered components.
- Digital:Flow-sensor-equipped devices with data logging for clinical documentation.
Electromechanical platforms anchor current installed base. Smart systems are climbing the fastest.
Application:
Reimbursement coding density varies sharply between institutional and community-based care settings.
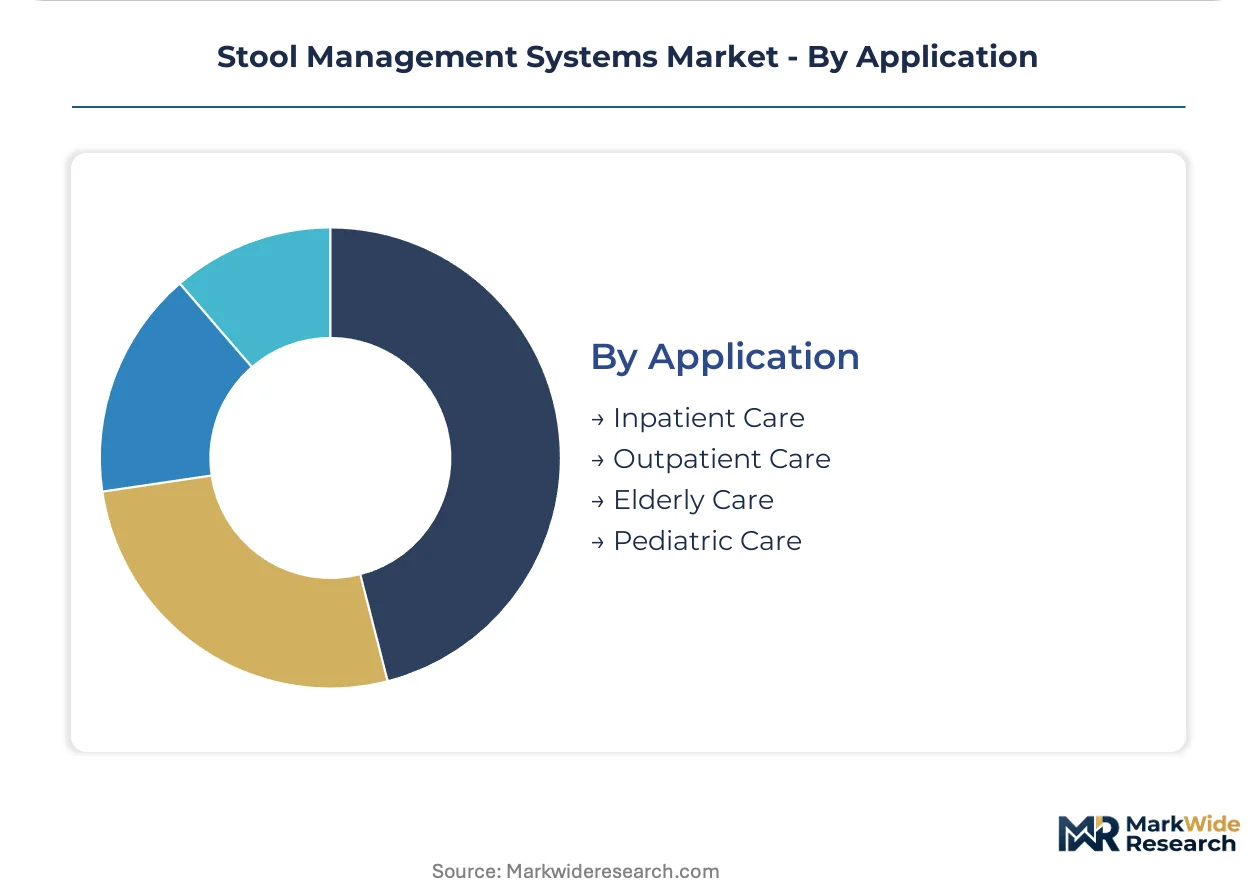
- Inpatient Care:Intensive care units and step-down units with immobilized patients requiring 24-72 hour dwell protocols.
- Elderly Care:Long-term care facilities where perineal skin integrity protocols drive closed-system adoption to reduce pressure injury litigation.
- Outpatient Care:Ambulatory surgical centers and short-stay units.
- Pediatric Care:Neonatal and pediatric intensive care with specialized sizing and biocompatibility requirements.
Inpatient care channels dominate current revenue. Elderly care is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with integrated sterilization infrastructure and shorter MDR certification queues. German and Danish producers now capture disproportionate procurement share from hospitals facing compressed compliance timelines.
United States
Level-one trauma centers in Texas and California drive electromechanical platform procurement to reduce nursing documentation burden and cross-contamination risk. FDA 510(k) clearance pathways govern Class II device market entry, though biocompatibility testing backlogs delay novel adhesive flange submissions. The Minneapolis medical device corridor anchors North American distribution infrastructure for automated evacuation systems.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia now mandate MDR-compliant technical files as bid evaluation criteria, freezing non-certified suppliers from tender participation. EU MDR conformity assessment bottlenecks compress margins while sterilization-integrated manufacturers accelerate certification timelines. The Melsungen industrial cluster dominates Central European catheter production through backward integration into ethylene oxide sterilization.
Denmark
Long-term care facilities in Zealand and the Capital Region adopt closed-collection catheter assemblies rated for 72-hour dwell times to reduce pressure injury litigation exposure. EMA notified body capacity constraints favor domestic producers with established EU authorized representatives. The Medicon Valley biotech corridor concentrates hydrocolloid interface manufacturing for ostomy applications.
United Kingdom
Post-acute providers in Greater London and the Midlands seek portable compact systems for aging-in-place populations, unbundling after-sales service from equipment acquisition. MHRA transitional arrangements for legacy CE-marked devices expire in 2024, forcing re-certification investments. The Cambridge medical technology cluster develops digital flow sensor platforms for predictive maintenance alerts.
Japan
Rehabilitation centers in Kanto and Kansai regions gain share fastest as transitional care settings with mixed acuity patient populations adopt modular upgradeable systems. PMDA consultation procedures for novel silicone elastomer formulations extend pre-market timelines. The Osaka medical device manufacturing district specializes in miniaturized suction components for pediatric care applications.
Stool Management Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital integration and home care portability. The vendor base concentrates among sterilization-integrated European manufacturers and North American distribution-heavy incumbents. Three archetypes dominate: integrated sterilization-catheter producers, direct-sales trauma center specialists, and hydrocolloid interface innovators. Competitive moves center on CE mark renewal prioritization for highest-volume SKUs and subscription-based service unbundling for home care channels.
Among German sterilization-integrated producers, B. Braun Melsungen AG exemplifies the integrated infrastructure archetype through captive ethylene oxide capacity. Medtronic occupies a position on the premium-tier vector as a North American direct-sales anchor. Coloplast A/S represents the specialized interface tier with Danish hydrocolloid manufacturing concentration. These three sit within distinct competitive spaces shaped by regulatory compliance speed, distribution reach, and material science differentiation.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Medtronic |
| Coloplast A/S |
| Welland Medical Limited |
| Axonics Inc. |
| ConvaTec Group PLC |
| Hollister Incorporated |
| ProSys International Ltd |
| Becton, Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Ethylene oxide sterilization specialists concentrated in Germany's Melsungen industrial cluster command wage premiums that widen spreads between MDR-certified premium systems and economy-grade alternatives lacking integrated sterilization infrastructure.
Pricing Analysis
Distributor margins on automated electromechanical platforms absorb 15-20 point spreads before hospital procurement committees see final landed costs. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified electromechanical systems from compact manual alternatives and unbranded commodity pouches. Cost compression in standard-tier catheter assemblies intensifies as German sterilization-integrated manufacturers exploit notified body bottlenecks to accelerate certification timelines. Nursing homes exhibit highest price sensitivity due to fixed per-diem reimbursement caps, while level-one trauma centers prioritize cross-contamination risk reduction over unit economics.
Supply Chain Analysis
Freight cost volatility on medical-grade silicone elastomer shipments from Germany and Denmark compresses margins for North American distributors lacking backward integration into polymer compounding. Raw material dependencies center on medical-grade silicone tubing, hydrocolloid adhesives, and ethylene oxide sterilization services. Single-source vulnerability concentrates in EMA-designated notified body capacity, where 18-month assessment backlogs freeze market entry for non-European applicants. Distribution runs through durable medical equipment distributors in North America and direct hospital contracts in Central Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hospital procurement committees in Germany mandating MDR-compliant technical files as mandatory bid evaluation criteria, shifting demand toward certified premium specifications.
For Market Incumbents: Hedge margin exposure by accelerating CE mark renewals for highest-volume SKUs before notified body capacity constraints worsen, while building captive ethylene oxide sterilization capacity to defend against emerging entrants lacking integrated infrastructure. Prioritize backward integration into medical-grade silicone compounding to offset raw material cost volatility. For New Entrants and Emerging Players: Launch via subscription-based service unbundling for home care compact systems, targeting underpenetrated aging-in-place populations in post-acute settings where institutional equipment alternatives create portability demand. White-space concentration sits in portable compact systems with standalone training contracts, bypassing sterilization-integrated manufacturing barriers through OEM sourcing partnerships. For Investors and Strategic Acquirers: Sterilization-integrated mid-cap specialists with established EU authorized representatives are the most active acquirer in this space, consolidating notified body relationships and MDR technical documentation capabilities. Long-term viability hinges on regulatory compliance speed rather than manufacturing scale alone. Watch EMA notified body capacity expansion announcements as inflection signal for competitive entry dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates CE mark renewal timelines for highest-volume SKUs ahead of competitor bottlenecks. |
| Backward Integration into Sterilization | Captive ethylene oxide capacity in Germany's Melsungen cluster compresses certification cycles. |
| Digital Flow Sensor Platform Development | Smart systems embedding real-time monitoring command premium positioning in level-one trauma centers. |
| Home Care Channel Subscription Model | Unbundled after-sales service contracts replace capital-plus-service pricing for compact systems. |
| Silicone Elastomer Formulation Partnership | 72-hour wear protocols with enhanced moisture resistance cut nursing labor hours per patient. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract reviews, CMS durable medical equipment reimbursement filings, and EMA notified body capacity assessments — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and field clinical specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation guidance, hospital capital expenditure surveys, and medical device trade flow records. Bottom-up SKU-level volume builds and top-down macro healthcare expenditure trends were triangulated to anchor market sizing.
Cross-referencing historical shipment patterns against panel input from distribution channel partners and sterilization service providers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user, technology platform, and application setting alongside reimbursement code coverage tiers. CAGRs were derived from weighted average growth trajectories across these segments, with electromechanical platform adoption curves and MDR compliance deadline impacts as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged EMA notified body backlogs or abrupt EU Green Deal circular-economy mandates affecting single-use plastic components. Forecasts reflect assumptions about regulatory capacity expansion and reimbursement code stability that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
IV Poles Market
Medical Devices
Portable OT Light Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Gel Implants Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
MRI Coils Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Global Wheelchair Market
Medical Devices
Chest Drainage System Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
PPG Biosensors Market