
 Brachytherapy Catheters Market | 2026-2036
Brachytherapy Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Brachytherapy Catheters Market Outlook
Multi-lumen high-dose-rate specifications is bifurcating the competitive landscape into premium precision tiers and standard clinical workhorse lines. Boston Scientific Corporation leverages integrated imaging catheter systems to sustain its position in advanced prostate applications. C.R. Bard anchors hospital supply contracts through broad GPO access across North American cancer centers. Varian Medical Systems differentiates via Elekta AB competes on software-defined dwell-time optimization for complex gynecological cases.
Brachytherapy catheters are hollow, flexible tubes manufactured from medical-grade polyethylene, silicone, or PVC, designed to deliver sealed radioactive sources directly into or adjacent to tumor tissue with millimeter positional accuracy. Their primary purpose is to achieve conformal dose distribution while sparing surrounding healthy organs at risk. HDR catheters command the strongest margin pools due to shorter treatment protocols and higher reimbursement per fraction, while interstitial configurations lead procedural volumes in prostate and breast applications. Material selection increasingly favors silicone for repeat-use flexibility in research institutions, whereas polyethylene dominates single-use disposable economics across high-throughput cancer treatment centers.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and sterilization validation costs for all manufacturers seeking market access. ISO 13485 quality management systems and AAPM TG-43 dose calculation standards further constrain design freedom and post-market surveillance obligations. Stakeholders must monitor evolving CMS reimbursement codes for hypofractionated brachytherapy and anticipate how NMPA harmonization with GB standards will reshape competitive entry into Chinese oncology networks.
Market Dynamics
Image-guided adaptive brachytherapy protocols are forcing catheter manufacturers to integrate real-time MRI compatibility and electromagnetic tracking into standard product lines, collapsing the traditional separation between hardware and software value capture.
Growth Catalysts
- CMS reimbursement codes for hypofractionated protocols:United States payers now cover condensed treatment schedules, accelerating hospital investments in HDR catheter suites and disposable inventory.
- Silicone material advances:Research institutions in Germany and Japan are validating repeat-use silicone catheters for cost-sensitive academic medical centers, creating dual-track procurement strategies.
- Organ-preserving oncology protocols:Prostate and cervical cancer treatment guidelines now prioritize fertility-sparing approaches, expanding interstitial catheter placements beyond curative resection candidates.
Market Restraints
- Iridium-192 source supply concentration:Three specialized reactors in Canada, the Netherlands, and South Africa control medical isotope production, exposing catheter-dependent clinics to radiopharmaceutical shortage risk.
- EU MDR technical documentation burdens:Sterile single-use catheter reclassifications under 2017/745 are extending conformity assessment timelines and elevating notified body audit costs.
- External beam radiotherapy precision advances:CyberKnife and proton therapy systems are capturing oligometastatic cases previously referred for brachytherapy boost sequences.
Strategic Opportunities
- NMPA harmonization with GB standards:China's medical device regulator is aligning quality management requirements with ISO 13485, lowering entry barriers for catheter manufacturers into tertiary oncology networks in Shanghai and Beijing.
- Pediatric sarcoma applications:Interstitial templates for extremity lesions in adolescents represent an underserved procedural category with limited competing modalities.
- 3D-printed patient-specific applicators:Convergence of biocompatible photopolymer printing and treatment planning software enables custom gynecological catheter geometries for complex anatomy cases.
Industry Challenges
- Medical physics staffing shortages:AAPM-certified dosimetrists capable of complex dwell-time optimization are concentrated in major metropolitan cancer centers, constraining community hospital program expansion.
- Legacy LINAC integration:Hybrid operating rooms require electromagnetic interference shielding between brachytherapy afterloaders and surgical navigation systems, complicating facility retrofit timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brachytherapy Catheters Market |
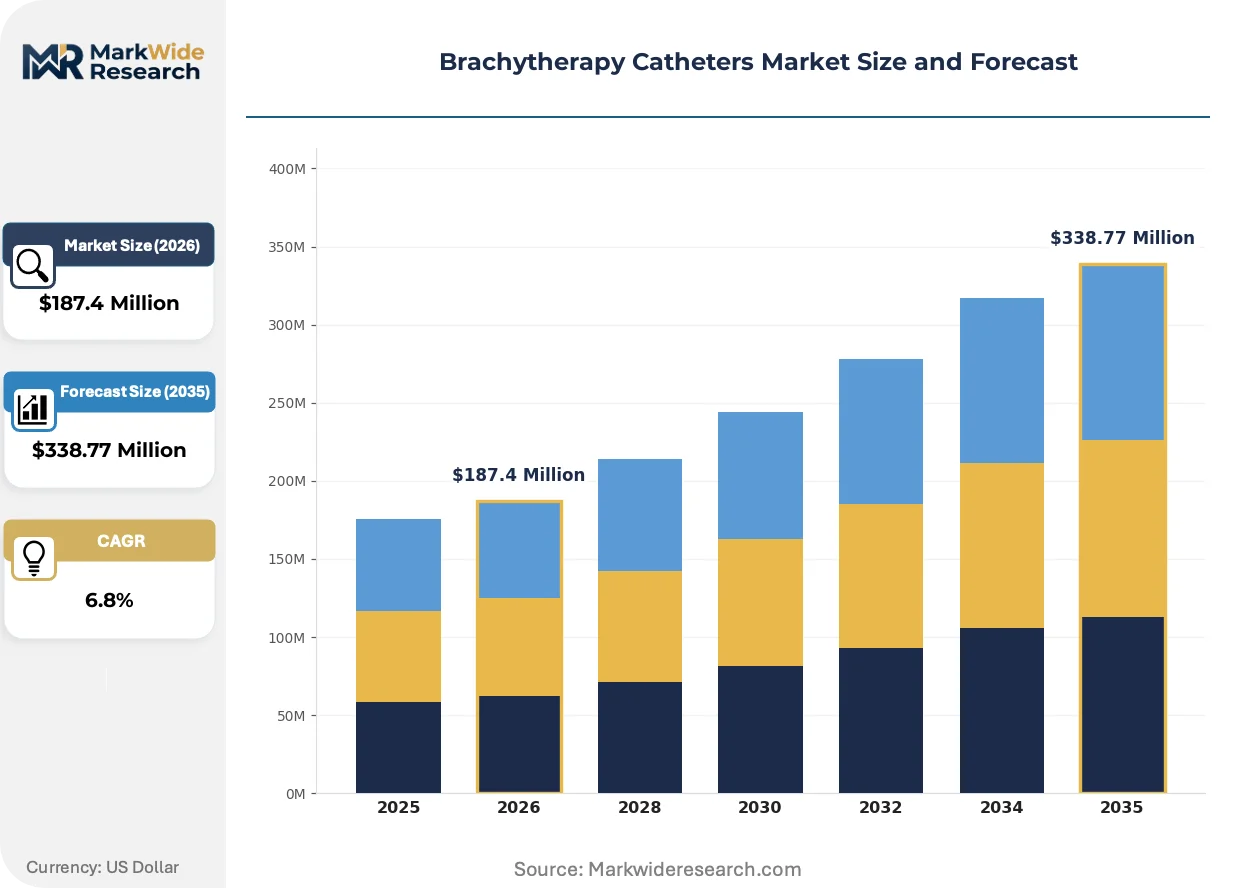
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interstitial Catheters, Curved Catheters, LDR Catheters, HDR Catheters Material: Polyethylene, Silicone, Vinyl, PVC Application: Prostate Cancer, Breast Cancer, Gynecological Cancer, Skin Cancer End User: Hospitals, Cancer Treatment Centers, Research Institutions, Clinics |
| Companies Covered | Boston Scientific Corporation, C.R. Bard, CIVCO Medical Solutions, Cook Medical, Elekta AB, Varian Medical Systems, Eckert & Ziegler, Hologic, TeamBest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brachytherapy Catheters Market Strategic Shifts
Catheter-based dose delivery is converging with real-time imaging and artificial intelligence-driven treatment planning, compressing the gap between simulation and intervention while redistributing value toward integrated system vendors.
Carbon-loaded polyurethane is supplanting standard polyethylene in HDR catheter construction for its superior radiopacity and kink resistance. Major cancer centers in the United States and Germany are adopting these materials for complex gynecological interstitial cases. The shift is compressing margins for commodity polyethylene suppliers while enabling premium pricing for specialty compounders with medical-grade carbon masterbatch capabilities.
EU MDR Article 117 clinical evidence requirements are extending post-market surveillance obligations for sterile single-use catheters from five to ten years. Manufacturers must now maintain implant registries and periodic safety update reports beyond traditional product lifecycles. High-throughput disposable producers are responding by consolidating SKUs and standardizing platform designs to amortize documentation costs across larger production volumes.
Hospital procurement committees are unbundling catheter supply from afterloader service contracts, reversing two decades of bundled equipment-leasing arrangements. Independent distributors and GPO-authorized suppliers are capturing catheter purchasing decisions previously controlled by radiation oncology equipment vendors. This fragmentation is most visible in United States community hospital settings where capital equipment refresh cycles have lengthened beyond catheter consumption rates.
Brachytherapy Catheters Market Segmentation
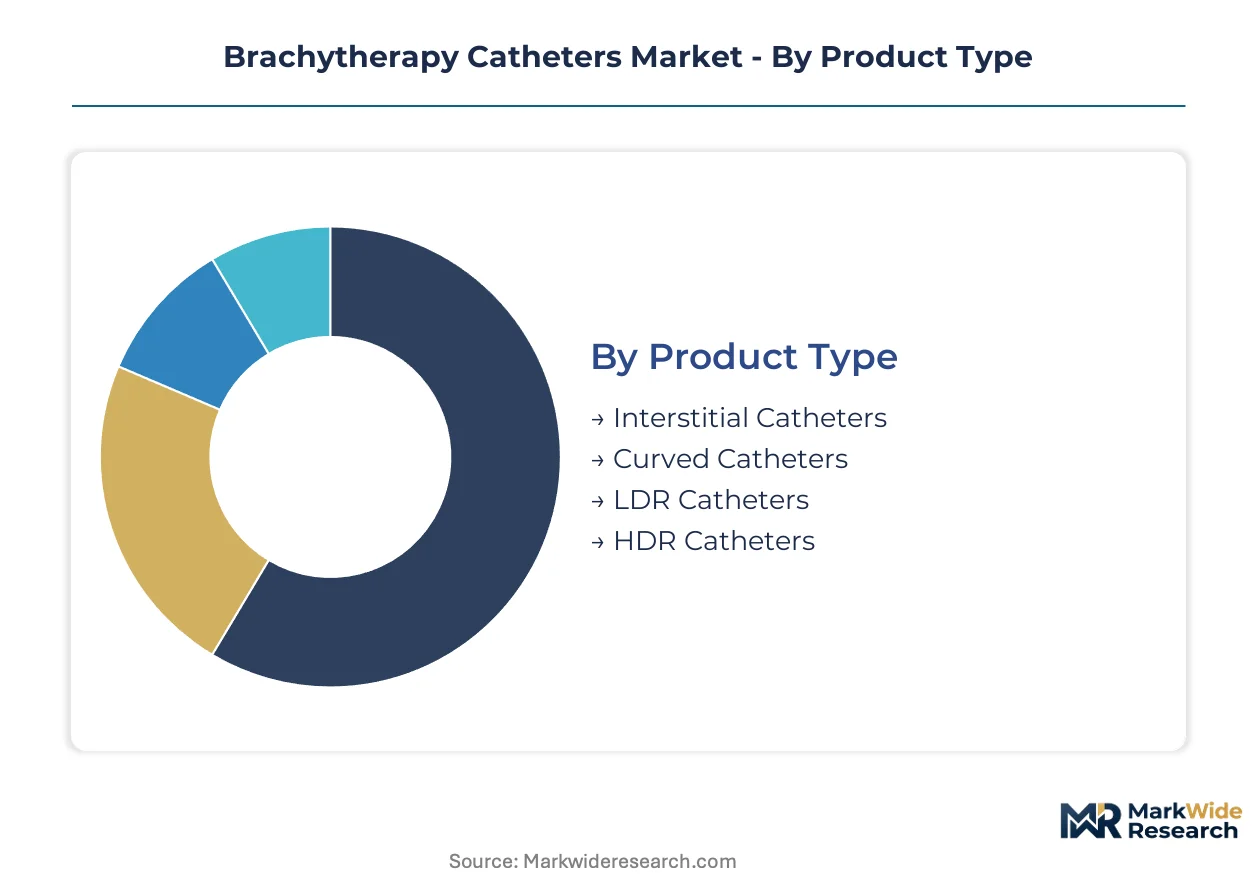
Catheter segmentation in brachytherapy reflects divergent reimbursement economics and procedural complexity across cancer types. Material selection and dose-rate specifications determine capital intensity, sterilization protocols, and inventory turnover profiles for purchasing departments.
Product Type:
Domestic production concentrates on standard interstitial lines for high-volume prostate programs, while curved and HDR specifications draw heavily from German and Japanese import channels.
- HDR Catheters:High-dose-rate configurations employ carbon-loaded polyurethane or specialized polyethylene for superior radiopacity and kink resistance during afterloader insertion. Demand clusters in United States academic medical centers and German university hospitals where hypofractionated protocols maximize linear accelerator utilization. CMS reimbursement codes for condensed treatment schedules sustain premium pricing.
- Interstitial Catheters:Straight, multi-lumen designs dominate procedural volumes in prostate and breast applications, manufactured primarily from medical-grade polyethylene for single-use economics. Community hospitals in the United States and cancer treatment centers in Japan represent the core demand base, driven by organ-preserving oncology guidelines favoring fertility-sparing approaches.
- Curved Catheters:Anatomically pre-shaped geometries address complex gynecological and head-neck cases requiring conformal dose distribution around curved tissue planes.
- LDR Catheters:Low-dose-rate lines persist in select prostate seed programs and palliative applications where permanent implantation suits patient mobility constraints.
Interstitial configurations hold the largest share; momentum sits with HDR specifications as treatment protocols compress.
Material:
Cost tiers separate commodity disposables from research-grade repeat-use inventory, with carbon-loaded compounds commanding manufacturing premiums.
- Polyethylene:Medical-grade formulations dominate single-use disposable economics across high-throughput cancer treatment centers in the United States and Germany. FDA 510(k) clearance pathways and sterilization validation costs favor standardized polymer platforms that amortize documentation across large production volumes.
- Silicone:Platinum-cured elastomers enable repeat-use flexibility validated in German and Japanese research institutions for cost-sensitive academic medical centers. Biocompatibility testing burdens under EU MDR Article 117 extend post-market surveillance obligations, favoring suppliers with established implant registries.
- Vinyl:Cost-competitive alternative for standard LDR applications with limited radiopacity requirements.
- PVC:Legacy material base gradually displaced by polyethylene in new catheter designs due to plasticizer migration concerns.
Polyethylene commands current volume leadership; silicone is climbing the fastest as academic procurement strategies bifurcate.
Application:
Prostate and breast indications drive standardized catheter geometries, while gynecological complexity demands patient-specific applicator innovation.
- Prostate Cancer:Transperineal interstitial templates and HDR boost configurations represent the procedural backbone of catheter-based brachytherapy. United States community hospitals and Japanese tertiary centers anchor demand, supported by AAPM TG-43 dose calculation standards and image-guided adaptive protocols integrating real-time MRI compatibility.
- Gynecological Cancer:Cervical and endometrial applications require curved catheters, tandem-and-ovoid assemblies, and emerging 3D-printed patient-specific geometries for complex anatomy cases. Elekta AB software-defined dwell-time optimization and electromagnetic tracking integration differentiate premium system offerings in this segment.
- Breast Cancer:Accelerated partial breast irradiation via interstitial or intracavitary catheters serves lumpectomy patients seeking cosmetic preservation.
- Skin Cancer:Superficial mold and plaque applications for non-melanoma lesions represent a niche procedural category with limited competing modalities.
Prostate applications retain dominant position; gynecological configurations gain share fastest through precision-dose software integration.
End User:
Purchasing authority concentrates in hospital procurement committees unbundling catheter supply from afterloader service contracts, with independent distributors capturing decisions previously vendor-controlled.
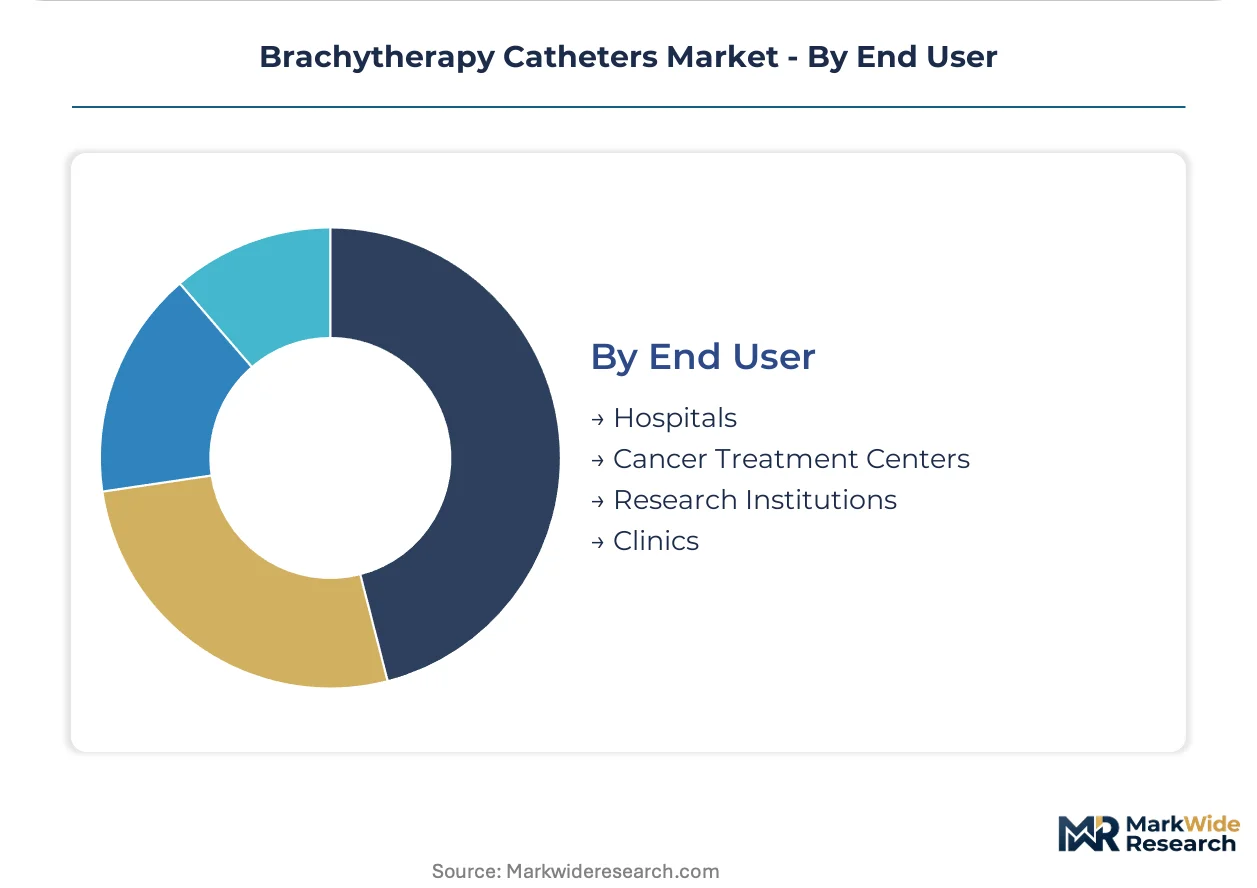
- Hospitals:Tertiary oncology networks in the United States, Germany, and Japan expand catheter-based programs as curative intent shifts toward organ-preserving protocols. Hybrid operating room investments complicate facility retrofit timelines due to electromagnetic interference shielding requirements between afterloaders and surgical navigation systems.
- Cancer Treatment Centers:Dedicated radiation oncology facilities drive highest catheter consumption intensity per linear accelerator, favoring high-throughput disposable economics and GPO-authorized supply contracts.
- Research Institutions:German and Japanese academic medical centers validate repeat-use silicone platforms and pediatric sarcoma interstitial templates for extremity lesions in adolescents.
- Clinics:Limited brachytherapy penetration due to medical physics staffing shortages constraining community program expansion.
Hospitals represent the largest procurement volume; cancer treatment centers show steepest expansion trajectory as standalone facility development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized reactors in Canada, the Netherlands, and South Africa control Iridium-192 isotope supply, tethering catheter-dependent clinics to concentrated radiopharmaceutical networks. Hospital procurement committees in tertiary oncology centers now unbundle catheter purchasing from afterloader service contracts, redistributing authority toward independent distributors and GPO-authorized suppliers.
United States
CMS reimbursement codes for hypofractionated protocols drive hospital investments in HDR catheter suites across academic medical centers. FDA 510(k) clearance pathways shape sterilization validation costs and product development timelines for domestic manufacturers. Boston Scientific Corporation anchors integrated imaging catheter systems in advanced prostate applications throughout major metropolitan cancer centers.
Germany
EU MDR Article 117 clinical evidence requirements extend post-market surveillance obligations from five to ten years for sterile single-use catheters. Research institutions validate repeat-use silicone platforms for cost-sensitive academic medical centers. University hospitals in Munich and Heidelberg lead adoption of carbon-loaded polyurethane materials for complex gynecological interstitial cases.
Japan
PMDA harmonization with international standards accelerates regulatory pathways for imported HDR specifications. METI supports domestic production capacity for medical-grade silicone compounds. Tokyo and Osaka tertiary centers drive highest catheter consumption intensity per linear accelerator in the Asia-Pacific region.
China
NMPA alignment with GB standards lowers entry barriers for catheter manufacturers into Shanghai and Beijing oncology networks. The country's national pharmaceutical regulator streamlines quality management requirements toward ISO 13485 equivalence. Domestic production concentrates on standard interstitial lines for high-volume prostate programs in provincial cancer hospitals.
United Kingdom
NHS procurement frameworks favor GPO-authorized supply contracts for high-throughput disposable economics. MHRA post-Brexit regulatory autonomy maintains CE marking recognition for EU-manufactured catheters while developing independent conformity assessment pathways. London cancer treatment centers expand pediatric sarcoma interstitial template programs for extremity lesions in adolescents.
Brachytherapy Catheters Market Competitive Environment
Concentration sits with diversified medtech conglomerates controlling integrated imaging-afterloader ecosystems. The vendor base spans three distinct tiers: premium precision manufacturers commanding software-defined dwell-time optimization, clinical workhorse suppliers anchoring hospital supply contracts through GPO access, and regional fabricators serving cost-sensitive disposable economics. Strategic moves center on electromagnetic tracking integration for hybrid operating room compatibility and SKU consolidation to amortize EU MDR documentation burdens across standardized platform designs.
Among North American-based conglomerates, Boston Scientific Corporation and C.R. Bard occupy positions across the premium and standard-tier vectors respectively. Elekta AB represents the European precision-systems archetype with software-centric differentiation. Varian Medical Systems exemplifies the integrated radiation oncology platform model. These three anchors illustrate how competitive positioning increasingly depends on collapsing hardware-software boundaries rather than standalone catheter manufacturing scale.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| C.R. Bard |
| CIVCO Medical Solutions |
| Cook Medical |
| Elekta AB |
| Varian Medical Systems |
| Eckert & Ziegler |
| Hologic |
| TeamBest |
| Others |
Value Chain & Pricing Dynamics
Carbon-loaded polyurethane substitution for standard polyethylene simultaneously relocates manufacturing toward German and Japanese specialty compounders and compresses margin pools for commodity resin suppliers. This material transition elevates radiopacity premiums while fragmenting procurement authority across hospital committees and GPO-authorized distributors.
Pricing Analysis
EU MDR Article 117 dictates the pricing tier structure across sterile single-use catheters, extending post-market surveillance obligations from five to ten years. Three-tier pricing separates carbon-loaded polyurethane HDR specifications from medical-grade polyethylene interstitial lines from legacy PVC alternatives. Cost compression in standard polyethylene disposables intensifies because SKU consolidation amortizes documentation burdens across larger production volumes. Community hospitals in the United States exhibit highest price sensitivity due to capital equipment refresh cycles lengthening beyond catheter consumption rates, while academic medical centers in Germany and Japan absorb premium pricing for repeat-use silicone platforms.
Supply Chain Analysis
Strategic stockpiling of Iridium-192 sources dominates inventory strategy across catheter-dependent clinics, given reactor concentration in Canada, the Netherlands, and South Africa. Medical-grade silicone feedstock draws from METI-supported domestic production in Japan and specialized elastomer compounders in Germany. Raw material dependencies center on platinum-cured silicone elastomers, carbon masterbatch additives, and medical-grade polyethylene resins. Single-source vulnerability in medical isotope production exposes clinics to radiopharmaceutical shortage risk. Distribution runs through GPO-authorized suppliers capturing purchasing decisions previously controlled by radiation oncology equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brachytherapy catheters sit in early-cycle expansion as organ-preserving oncology protocols extend catheter-based interventions beyond curative resection candidates into fertility-sparing treatment guidelines.
For Market Incumbents: Fortify software-defined dwell-time optimization capabilities to defend against external beam radiotherapy precision advances capturing oligometastatic cases. Consolidate electromagnetic tracking integration for hybrid operating room compatibility, leveraging existing hospital supply contracts to amortize EU MDR documentation costs across standardized platform designs. For New Entrants and Emerging Players: NMPA harmonization with GB standards offers the fastest regulatory pathway into Shanghai and Beijing tertiary oncology networks. Pediatric sarcoma interstitial templates for extremity lesions in adolescents represent the most penetrable procedural category with limited competing modalities. Pursue independent distributor partnerships to bypass entrenched equipment-leasing arrangements controlling catheter purchasing decisions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-systems specialists holding software-centric differentiation but lacking integrated imaging-afterloader ecosystems. Five-to-ten year viability hinges on collapsing hardware-software boundaries rather than standalone catheter manufacturing scale. Watch CMS reimbursement code expansion for hypofractionated protocols as the inflection indicator for hospital HDR suite investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 117 compliance unlocks access to German university hospital procurement frameworks. |
| Hospital System Partnership | Unbundled catheter supply contracts with GPO-authorized distributors bypass legacy equipment vendor control. |
| Software Companion Development | Real-time MRI compatibility and electromagnetic tracking integration collapse hardware-software value capture boundaries. |
| Reimbursement Strategy | CMS code alignment for hypofractionated protocols accelerates HDR catheter suite investments across academic medical centers. |
| FDA Submission | 510(k) clearance for carbon-loaded polyurethane materials sustains premium positioning in complex gynecological interstitial cases. |
Study Parameters
A standing panel of radiation oncology department heads, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement code updates, and hospital procurement system records. Bottom-up catheter consumption modeling triangulated against top-down cancer incidence projections and linear accelerator installation data.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product type specifications, material grade tiers, application complexity, end-user facility category, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, reimbursement rate evolution, and material cost curve projections. Industry-specific forecast inputs incorporated Iridium-192 source availability constraints and medical physics staffing concentration patterns.
Decision-makers should treat outputs as directional under assumptions of sustained organ-preserving protocol adoption and stable isotope supply chain configuration; material deviation would warrant model refresh. Revision becomes warranted when external beam radiotherapy precision thresholds or EU MDR documentation burden escalations cross critical inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Medical Device Manufacturing Outsourcing Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Corneal Implants Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Heart Closure Devices Market