
 Robotic Hair Transplant System Market | 2026-2036
Robotic Hair Transplant System Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Hair Transplant System Market Analytics
Polyetheretherketone is shifting toward titanium alloy in robotic arm housings and needle guide assemblies, reducing weight while maintaining sterilization-cycle durability. Restoration Robotics, Inc. leverages in-house kinematic software development to sustain procedure accuracy claims across varied hair types. Venus Concept Inc. anchors its competitive position through integrated aesthetic platform sales that bundle robotic transplantation with laser and radiofrequency devices. ARTAS Robotics dominates North American clinic installations through direct-to-physician training programs and proprietary follicular unit mapping algorithms.
A robotic hair transplant system comprises electromechanical articulating arms, stereoscopic vision modules, and automated punch mechanisms designed to extract and implant individual follicular units with sub-millimeter precision, typically operating at extraction rates exceeding one thousand grafts per hour with physician oversight. The primary commercial purpose centers on reducing procedural variability, minimizing donor-site scarring, and shortening technician-dependent harvesting phases in both cosmetic and reconstructive hair restoration. FUE technology leads procedural volume due to its minimally invasive extraction profile and faster patient recovery trajectories compared to strip-harvesting alternatives. Cosmetic surgeons represent the fastest-expanding end-user channel as solo practitioners invest in capital equipment to differentiate against high-volume clinic chains. Automated harvesting systems concentrate margin pools through recurring software licensing and per-procedure consumable attach rates.
FDA 510(k) clearance requirements govern robotic surgical device commercialization in the United States, while the EU MDR demands expanded clinical follow-up data for active implantable surgical equipment entering European markets. Turkey's Ministry of Health regulates medical tourism clinic accreditation, directly shaping inbound patient flows for robotic transplant procedures in Istanbul and Ankara. South Korea's MFDS enforces stringent biocompatibility testing for automated punch tips contacting human tissue. Stakeholders must monitor evolving reimbursement codes for robot-assisted dermatological surgery across national health systems, as coverage decisions will determine clinic-level payback periods for capital-intensive system deployments.
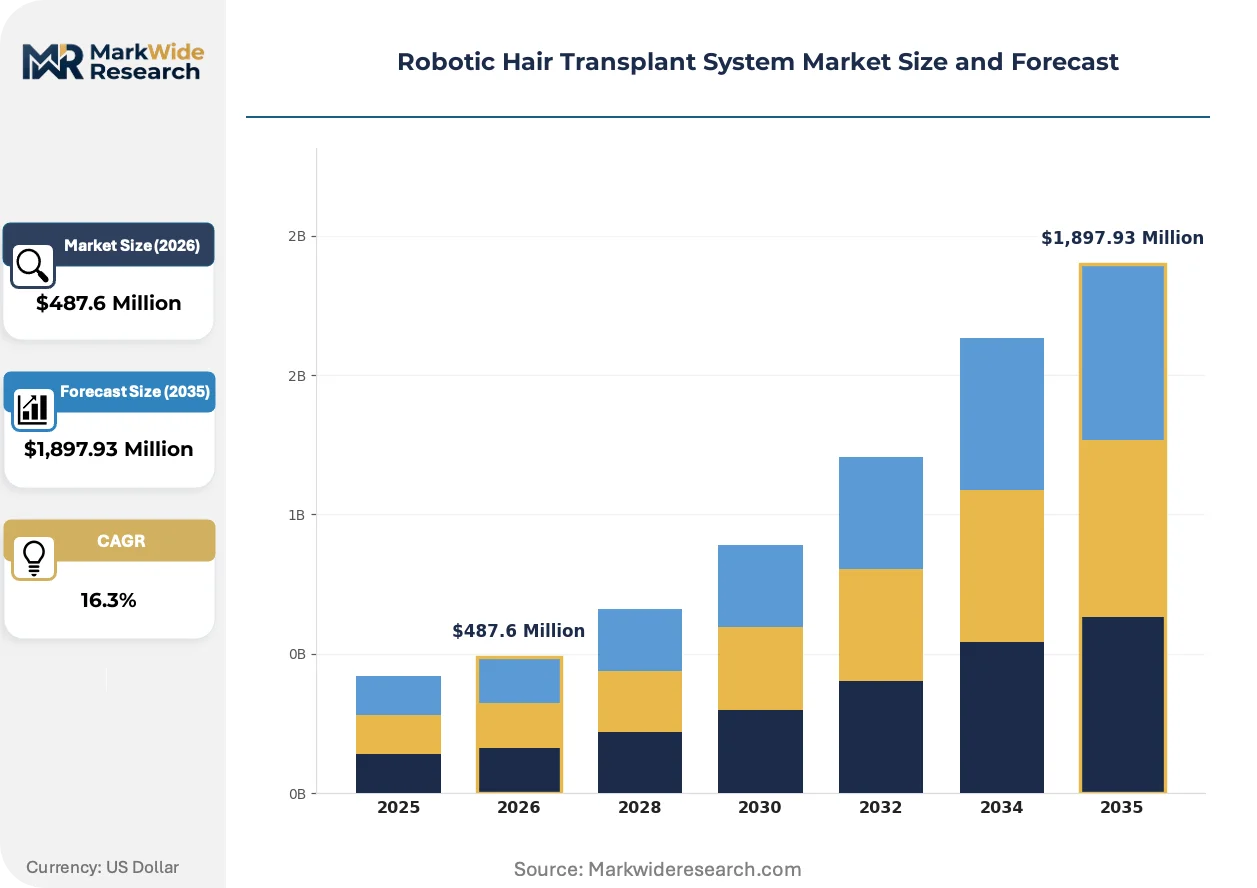
Market Dynamics
Class II surgical robot clearance pathways and EU MDR clinical-evidence mandates are compressing product development timelines while elevating capital requirements for new entrants, reshaping competitive economics across automated follicular unit extraction systems.
Growth Catalysts
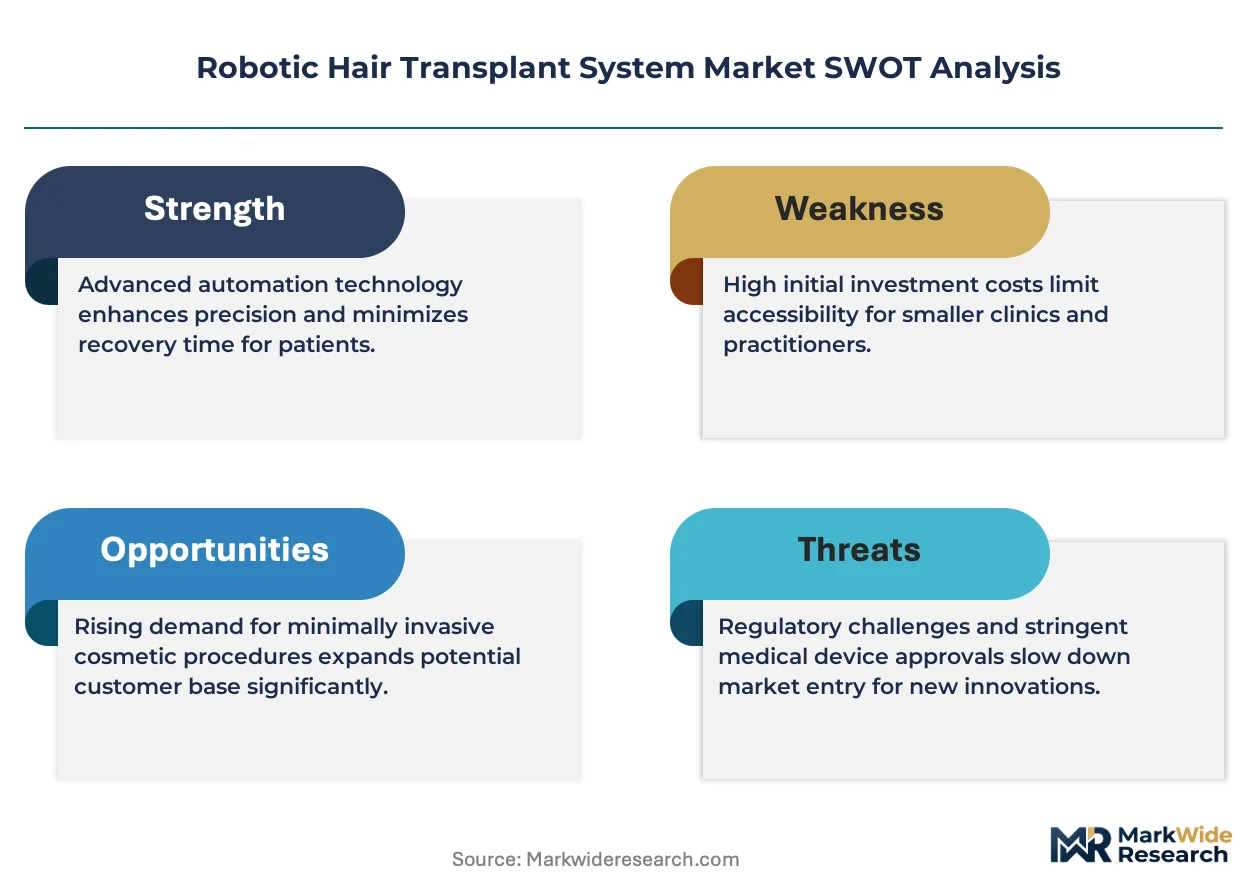
- FDA 510(k) Precedent Pathways:Established clearance frameworks for predicate surgical robots reduce regulatory uncertainty for follicular extraction device submissions, accelerating commercialization timelines for qualified manufacturers.
- Medical Tourism Infrastructure:Turkey's Ministry of Health clinic accreditation standards for robotic procedures channel inbound patient flows toward Istanbul and Ankara facilities equipped with automated harvesting systems.
- Titanium Alloy Adoption:Material substitution in needle guide assemblies and arm housings reduces sterilization-cycle fatigue while maintaining sub-millimeter positioning accuracy across extended procedure volumes.
Market Restraints
- Capital Equipment Intensity:Robotic FUE systems require substantial upfront investment in electromechanical articulating arms and stereoscopic vision modules, constraining adoption among solo dermatology practitioners.
- EU MDR Clinical Follow-up Burden:Expanded post-market surveillance requirements for active implantable surgical equipment extend validation timelines and inflate regulatory compliance costs for European market entry.
- Strip-Harvesting Substitution Persistence:Conventional follicular unit transplantation retains cost advantages for high-graft-volume cases, limiting robotic system penetration in price-sensitive patient segments.
Strategic Opportunities
- South Korean MFDS Biocompatibility Standards:Automated punch tip certification requirements create differentiation pathways for manufacturers investing in advanced surface engineering and tissue-contact material science.
- Laser-Radiofrequency Platform Convergence:Bundled aesthetic device sales integrating robotic transplantation with complementary energy-based therapies expand per-clinic revenue capture and equipment utilization rates.
- Direct-to-Physician Training Programs:Proprietary education and certification ecosystems build switching costs and lock in recurring software licensing revenue streams across installed base expansion.
Industry Challenges
- Kinematic Software Talent Scarcity:Procedure accuracy claims depend on in-house development of follicular unit mapping algorithms and motion-control systems, creating recruitment bottlenecks for specialized robotics engineers.
- Reimbursement Code Uncertainty:Evolving national health system coverage decisions for robot-assisted dermatological surgery determine clinic-level payback periods, complicating capital budgeting for system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Hair Transplant System Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,897.93 Million |
| CAGR (2026 – 2036) | 16.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: FUE, FUT, Robotics, Automated Systems End User: Clinics, Hospitals, Dermatology Centers, Cosmetic Surgeons Product Type: Direct Hair Implantation, Manual Punches, Automated Harvesting, Implantation Devices Application: Aesthetic Procedures, Medical Treatments, Restoration Services, Hair Loss Solutions |
| Companies Covered | Restoration Robotics, Inc., Venus Concept Inc., ARTAS Robotics, Cole Instruments, Inc., Medicamat S.A., NeoGraft Solutions, Inc., I Brain Robotics Inc., CEGO Medical S.r.l., Sowon Meditech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Hair Transplant System Market Evolving Landscape
Automation density in follicular extraction is accelerating as stereoscopic vision modules and automated punch mechanisms achieve procedural parity with manual technician harvesting, compressing the skill-premium that previously justified labor-intensive approaches.
AI-powered follicular unit mapping is rewriting competitive positioning in high-throughput clinics. Convolutional neural networks now classify graft angle, depth, and density in real-time, enabling extraction rates exceeding one thousand grafts per hour with reduced physician oversight burden. Seoul and Los Angeles dermatology centers are deploying these systems to differentiate against technician-dependent alternatives, compressing the value capture previously concentrated in specialized surgical labor.
EU MDR tightened clinical-evidence requirements for active implantable surgical equipment are extending market access timelines for European commercialization. Manufacturers must now submit expanded post-market surveillance data and longitudinal safety outcomes, elevating documentation costs and favoring incumbents with established quality management systems. Smaller robotics developers are responding through notified body pre-submission consultations and staged clinical trial designs targeting specific member state approvals.
Patient preference for minimally invasive extraction profiles is rotating demand toward cosmetic surgeon channels and away from high-volume clinic chains. Solo practitioners in the United States and Turkey are acquiring capital equipment to capture premium pricing for reduced scarring and faster recovery trajectories, unbundling the procedure volume previously consolidated in centralized harvesting facilities. This channel fragmentation elevates importance of direct manufacturer training and per-procedure consumable attach rate economics.
Robotic Hair Transplant System Market Segmentation
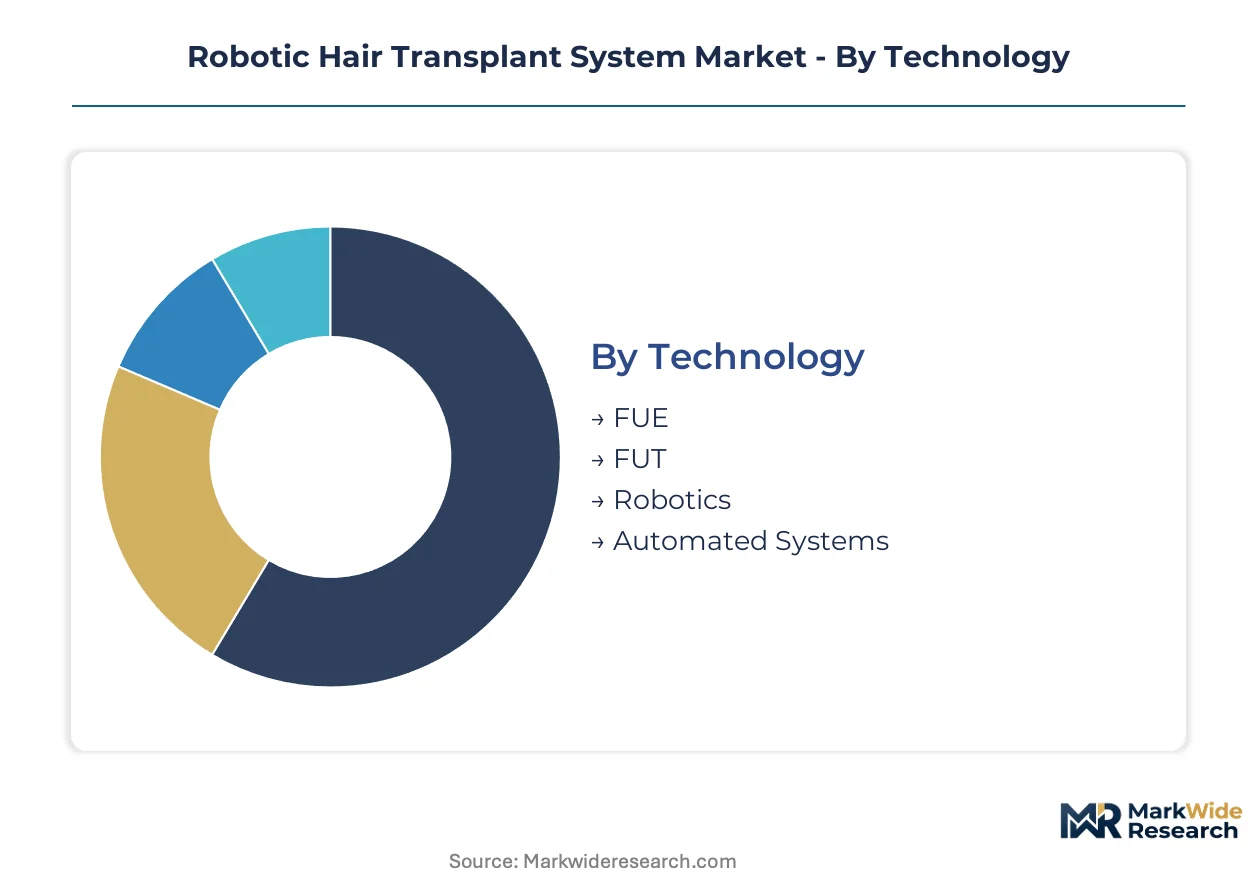
Segmentation in robotic hair transplant systems reveals how technological sophistication, clinical setting, and procedural intent reshape procurement patterns across the value chain. Manufacturers must align hardware specifications, software licensing models, and training ecosystems to distinct buyer capabilities and patient volume profiles.
Technology:
Standardization dominates high-volume extraction protocols while customization concentrates in vision-guided robotics requiring physician-specific calibration.
- Robotics:Electromechanical articulating arms with stereoscopic vision modules achieve sub-millimeter follicular extraction precision. Demand concentrates in Seoul, Tokyo, and Los Angeles dermatology centers where patient premiums support capital-intensive system deployments and physician oversight reduction.
- FUE:Minimally invasive follicular unit extraction using motorized or manual punch devices dominates procedural volume through faster recovery trajectories and reduced donor-site scarring. Turkey's medical tourism infrastructure channels inbound patient flows toward Istanbul clinics equipped with automated FUE harvesting systems.
- Automated Systems:Software-driven punch mechanisms with AI-powered graft mapping reduce technician dependency in high-throughput environments.
- FUT:Strip-harvesting techniques retain cost advantages for high-graft-volume cases despite longer recovery periods and linear scarring.
Leading the category by volume: FUE. Growing fastest: Robotics.
End User:
Capital intensity and procedure volume determine channel concentration, with solo practitioners seeking differentiation against consolidated clinic chains.
- Cosmetic Surgeons:Solo practitioners invest in robotic systems to capture premium pricing for reduced scarring and faster recovery trajectories, unbundling volume from centralized harvesting facilities. United States demand concentrates in metropolitan markets where disposable income supports per-procedure software licensing economics.
- Dermatology Centers:Multi-physician facilities in Seoul and Los Angeles deploy integrated aesthetic platforms bundling robotic transplantation with laser and radiofrequency devices to maximize equipment utilization rates.
- Clinics:High-volume chains in Turkey leverage medical tourism accreditation to channel inbound robotic procedure demand.
- Hospitals:Reconstructive hair restoration services integrate with broader plastic surgery departments under institutional procurement frameworks.
Cosmetic surgeons command the steepest expansion trajectory. Dermatology centers retain the largest installed base.
Product Type:
Margin capture shifts toward recurring revenue streams as hardware commoditization pressures upfront system pricing.
- Automated Harvesting:Electromechanical punch mechanisms with titanium alloy needle guides reduce sterilization-cycle fatigue while maintaining extraction accuracy. South Korea's MFDS biocompatibility standards for tissue-contact surfaces create certification differentiation pathways.
- Implantation Devices:Precision delivery systems for follicular unit placement complete the procedural workflow in high-throughput clinical environments.
- Direct Hair Implantation:Combined extraction-implantation systems streamline single-session procedures for time-constrained patients.
- Manual Punches:Basic handheld devices retain cost-sensitive market presence despite labor intensity and variability constraints.
Automated harvesting generates dominant revenue share. Direct hair implantation gains share fastest.
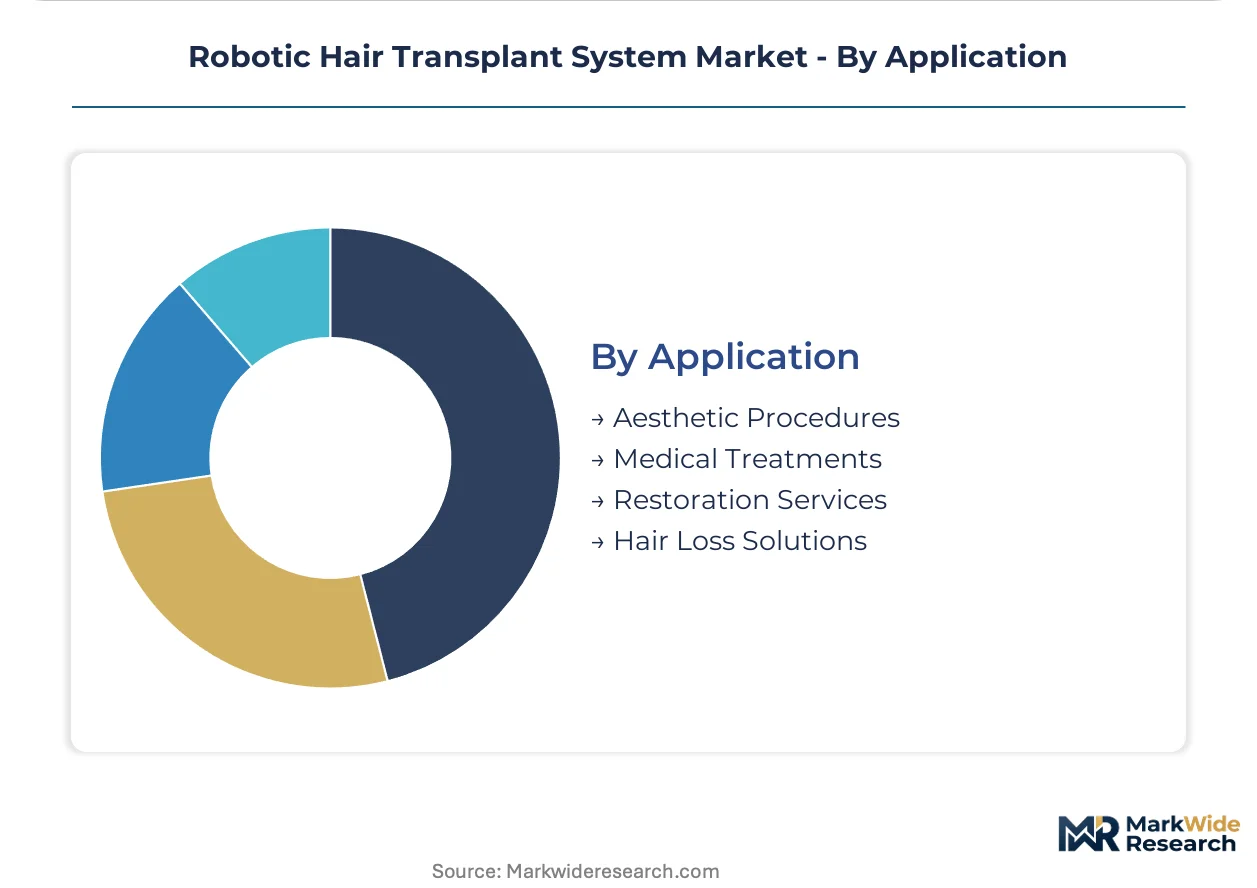
Application:
Cosmetic intent drives capital equipment acquisition while medical necessity procedures face reimbursement uncertainty.
- Aesthetic Procedures:Elective hairline restoration and density enhancement command premium pricing in United States and South Korean metropolitan markets. Patient preference for minimally invasive extraction profiles rotates demand toward robotic channels and away from technician-dependent alternatives.
- Hair Loss Solutions:Pattern baldness interventions targeting male and female androgenetic alopecia represent the core commercial volume.
- Restoration Services:Scar camouflage and eyebrow reconstruction applications extend system utilization beyond scalp procedures.
- Medical Treatments:Post-traumatic or post-surgical hair restoration faces coverage variability across national health systems.
Aesthetic procedures anchor category volume. Restoration services expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient preference for minimally invasive extraction and medical tourism infrastructure concentrate demand in the United States, South Korea, and Turkey. Disposable income levels and clinic accreditation standards determine where capital-intensive robotic systems achieve viable payback periods.
United States
Cosmetic surgeons in Los Angeles and New York Metro acquire robotic FUE systems to capture premium pricing for reduced scarring outcomes. FDA 510(k) clearance pathways for Class II surgical robots provide regulatory certainty for predicate device submissions. Metropolitan dermatology centers deploy integrated aesthetic platforms bundling transplantation with energy-based therapies.
South Korea
Seoul's dermatology clusters drive adoption as MFDS biocompatibility standards for automated punch tips create certification differentiation. The ministry enforces stringent tissue-contact material testing for devices contacting human skin. Gangnam district clinics leverage AI-powered follicular mapping to differentiate against technician-dependent alternatives.
Turkey
Istanbul and Ankara facilities channel inbound medical tourism flows through Ministry of Health clinic accreditation for robotic procedures. Disposable income asymmetries between source markets and local pricing enable premium equipment economics. High-volume chains consolidate procedure volume through automated harvesting system deployments.
Japan
Tokyo dermatology centers expand robotic adoption as METI standards for surgical device software validation elevate quality requirements. PMDA consultation pathways for novel electromechanical systems extend pre-market preparation timelines. Osaka and Nagoya clinics concentrate early adoption among multi-physician aesthetic platforms.
Germany
EU MDR clinical-evidence mandates for active implantable surgical equipment extend market access timelines for European commercialization. Notified body pre-submission consultations concentrate in Munich and Berlin medical device clusters. Post-market surveillance requirements favor incumbents with established quality management systems.
Robotic Hair Transplant System Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers bundle robotic transplantation with complementary aesthetic devices to expand per-clinic revenue capture. The vendor base concentrates around integrated platform specialists and standalone harvesting system developers. Three archetypes define positioning: kinematic software developers, multi-modality platform vendors, and consumable-centric equipment suppliers. Geographic expansion through direct-to-physician training programs and technology licensing agreements constitute the primary competitive vectors.
Among North American system developers, Restoration Robotics, Inc. and Venus Concept Inc. exemplify divergent strategic approaches to platform integration. Restoration Robotics, Inc. anchors the kinematic software development archetype through in-house motion-control capabilities. Venus Concept Inc. occupies the multi-modality bundling position within aesthetic device portfolios. ARTAS Robotics represents the installed-base expansion model through proprietary follicular mapping algorithms and physician certification ecosystems. These three entities collectively illustrate how competitive positioning fragments across software differentiation, platform convergence, and training-based switching costs.
| Leading Market Players |
|---|
| Restoration Robotics, Inc. |
| Venus Concept Inc. |
| ARTAS Robotics |
| Cole Instruments, Inc. |
| Medicamat S.A. |
| NeoGraft Solutions, Inc. |
| I Brain Robotics Inc. |
| CEGO Medical S.r.l. |
| Sowon Meditech Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Titanium alloy spot pricing on the London Metal Exchange cascades through robotic hair transplant system manufacturing, compressing margins for needle guide assembly suppliers while elevating procurement costs for Korean and Turkish clinic chains negotiating volume-tiered equipment contracts.
Pricing Analysis
Volume-based procurement separates high-throughput dermatology centers from solo cosmetic surgeons, with the former extracting per-procedure software licensing discounts above fifty annual cases. FDA 510(k) certification tier and MFDS biocompatibility grade anchor price differentiation between North American and East Asian market entries. Cost compression in standard FUE devices intensifies as Turkish medical tourism clinics consolidate purchasing power through Ministry of Health accreditation networks. Solo practitioners in the United States exhibit highest price sensitivity due to capital equipment payback uncertainty, while Seoul's Gangnam district multi-physician platforms absorb premium robotics pricing.
Supply Chain Analysis
Air freight rates from Shenzhen to Los Angeles and Incheon to Istanbul determine landed costs for stereoscopic vision modules and electromechanical articulating arms. Component sourcing concentrates in China for machined titanium housings, South Korea for optical sensor arrays, and Germany for precision drive systems. Sterilization-grade polymer supply draws from single-source Japanese suppliers, creating vulnerability to export license delays. Distribution runs through manufacturer-direct sales teams for North American cosmetic surgeons and authorized medical device distributors for European dermatology centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical-evidence mandates and FDA 510(k) predicate pathway complexity are forcing subscale robotics developers toward acquisition or exit, consolidating viable vendor count around kinematic software specialists and multi-modality platform holders.
For Market Incumbents: Anticipate margin compression from AI-powered follicular mapping commoditization by deepening in-house algorithm development and locking physician switching costs through expanded certification ecosystems. Secure titanium alloy supply agreements with South Korean and German mills before medical device demand spikes. Prioritize backward integration into automated punch tip surface engineering to satisfy MFDS biocompatibility differentiation requirements. For New Entrants and Emerging Players: Begin with white-space targeting of direct hair implantation systems for time-constrained aesthetic patients in Istanbul and Ankara medical tourism corridors, where Ministry of Health accreditation creates procurement preference for new equipment suppliers. Penetrate the manual punch replacement segment through disposable automated harvesting attachments compatible with existing clinic infrastructure. Deploy per-procedure consumable revenue models to bypass capital equipment purchase barriers among Turkish high-volume chains. For Investors and Strategic Acquirers: Distressed-cycle entries favor kinematic software developers with FDA-cleared predicate devices in South Korea and the United States, where MFDS and 510(k) pathway investments represent stranded capital for undercapitalized founders. Long-term viability hinges on recurring software licensing attach rates above sixty percent across installed bases. Monitor reimbursement code determinations for robot-assisted dermatological surgery as the inflection signal for clinic-level capital expenditure recovery.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Biocompatibility Certification | Automated punch tip surface engineering unlocks Seoul dermatology center premium procurement. |
| Direct-to-Physician Training Ecosystem | Proprietary certification programs lock in recurring software licensing across Los Angeles cosmetic surgeon installed bases. |
| Laser-Radiofrequency Platform Bundling | Integrated aesthetic device sales maximize per-clinic equipment utilization rates in Tokyo multi-modality centers. |
| EU MDR Staged Clinical Trial Design | Notified body pre-submission consultations accelerate market access timelines for Munich and Berlin medical device clusters. |
| Titanium Alloy Supply Agreement | Long-term mill contracts secure sterilization-cycle fatigue resistance for needle guide assembly production. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with robotic system product managers, dermatology clinic procurement directors, biomedical engineers, and MFDS regulatory consultants. FDA 510(k) clearance databases, EU MDR notified body documentation, South Korean customs export statistics, and Turkish Ministry of Health medical tourism accreditation registries supplied quantitative foundations. Bottom-up clinic installation counts and top-down medical device trade flow analysis enabled triangulation.
Granularity-level modeling proceeded at the country-city-procedure tier for demand estimation and the component-supplier-assembler tier for supply-side reconstruction. Technology segmentation captured robotics, FUE, automated systems, and FUT modalities; end-user segmentation distinguished cosmetic surgeons, dermatology centers, clinics, and hospitals; product type segmentation tracked automated harvesting, implantation devices, direct hair implantation, and manual punches. CAGRs derived from procedure volume growth rates, equipment replacement cycles, and per-procedure consumable attach rate trajectories across the analysis window. Kinematic software development talent scarcity and reimbursement code uncertainty served as scenario-weighting inputs.
Underlying measurement precision varies by segment; United States and South Korean procedure volume estimates carry tighter precision than emerging market projections due to hospital procurement database coverage gaps. Forecasts reflect assumptions regarding FDA clearance timeline stability, EU MDR notified body capacity, and titanium alloy price volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neuro Medical Devices Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Trial Prostheses Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Global Nebuliser Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Indonesia Devices Market