
 Neuroprosthetics Market | 2026-2036
Neuroprosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Neuroprosthetics Market Intelligence
Closed-loop neural interface architecture is fragmenting into modality-specific stacks for sensory, motor, and cognitive pathways. Medtronic leverages its integrated neuromodulation platform to sustain leadership across implantable pulse generator categories. Cochlear Limited anchors the auditory restoration segment with specialized electrode array designs that dominate ENT surgical workflows.
Neuroprosthetics are implantable or wearable systems that restore or augment neural function through electrical, optical, or chemical stimulation of the peripheral or central nervous system, typically incorporating biocompatible electrode materials with impedance values below 10 kΩ at 1 kHz to ensure signal fidelity. Their primary purpose is to bypass damaged neural tissue and restore sensory input, motor output, or modulate pathological activity in conditions such as deafness, paralysis, Parkinson's disease, or chronic pain. Cochlear implants lead product type revenue due to mature reimbursement and standardized surgical training, while brain-machine interfaces represent the fastest-expanding segment as microelectrode array density improves and wireless power transfer eliminates percutaneous connectors. Pain management applications command substantial volume through spinal cord stimulation, though motor function restoration is attracting R&D investment as closed-loop decoding algorithms advance.
FDA premarket approval and EU MDR conformity assessment shape neuroprosthetics development timelines, with both frameworks demanding extensive clinical evidence for active implantable devices. The FDA breakthrough device program offers expedited review for technologies addressing irreversibly debilitating conditions, while EU MDR technical documentation requirements have lengthened notified body engagement periods. Japan's PMDA and South Korea's MFDS maintain parallel but distinct approval tracks that manufacturers must navigate for Asia-Pacific access. Stakeholders should monitor reimbursement policy evolution for novel indications, as payer acceptance often lags regulatory clearance by several adoption cycles and determines commercial viability.
Market Dynamics
Closed-loop neural interface architecture is fragmenting into modality-specific stacks for sensory, motor, and cognitive pathways. Medtronic leverages its integrated neuromodulation platform to sustain leadership across implantable pulse generator categories. Cochlear Limited anchors the auditory restoration segment with specialized electrode array designs that dominate ENT surgical workflows.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for technologies addressing irreversibly debilitating conditions compress commercial timelines for brain-machine interface developers.
- Germany Statutory Health Insurance Coverage:Reimbursement mandates for cochlear and deep brain stimulation procedures eliminate payer uncertainty and drive surgical volume.
- Microelectrode Array Density Improvements:Advances in neural signal resolution enable more precise motor decoding for spinal cord injury rehabilitation programs at major university hospitals.
Market Restraints
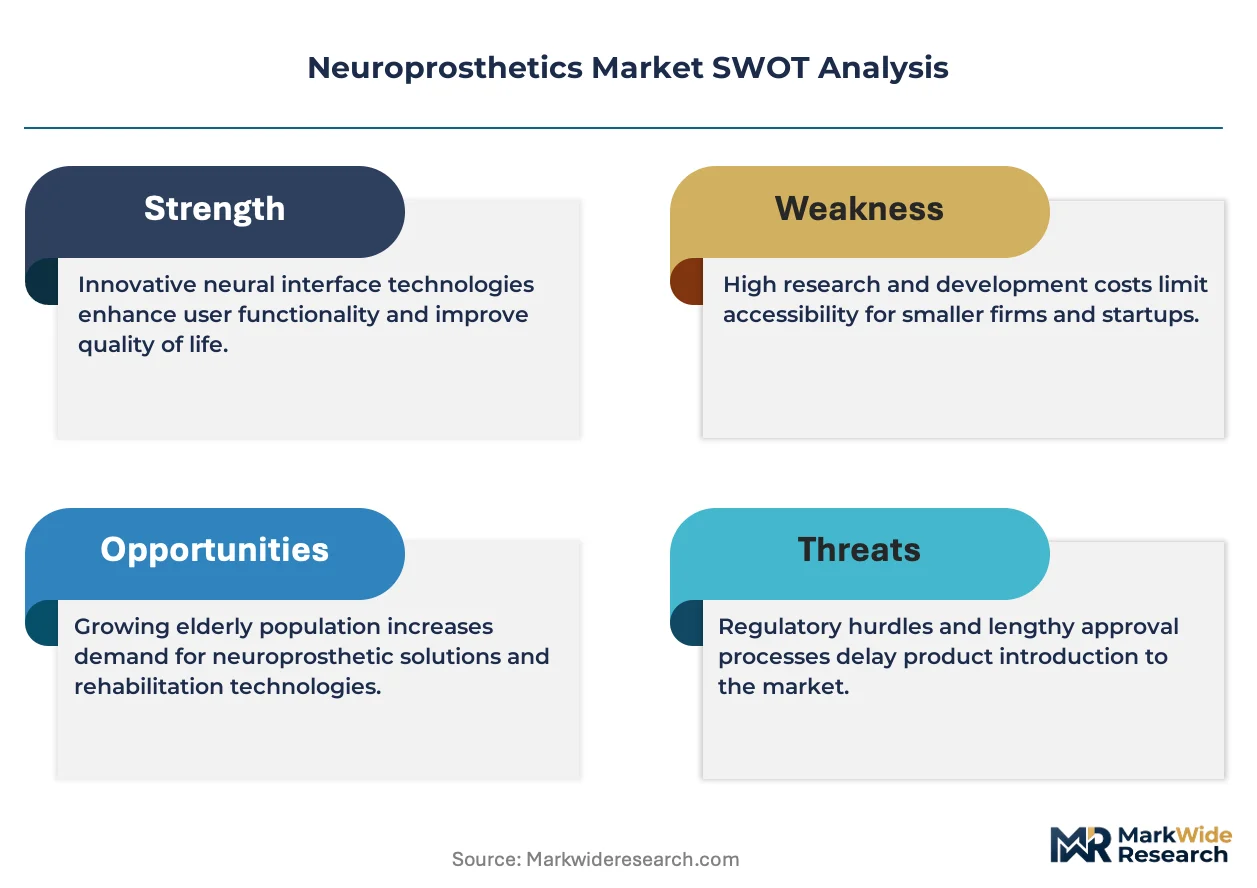
- Platinum-Iridium Electrode Material Costs:Volatility in precious metal prices squeezes margins for manufacturers of high-channel-count implantable devices.
- EU MDR Technical Documentation Burden:Lengthened notified body engagement periods delay product launches and tie up regulatory capital for 18-24 months.
- Non-Invasive Neuromodulation Substitution:Transcranial magnetic stimulation and focused ultrasound systems capture chronic pain and depression cases that might otherwise receive implants.
Strategic Opportunities
- Japan PMDA Parallel Track Navigation:Dedicated regulatory pathways for novel neuroprosthetic indications offer first-mover advantages in Asia-Pacific's second-largest medical device market.
- Wireless Power Transfer Convergence:Elimination of percutaneous connectors through inductive charging and Bluetooth Low Energy telemetry reduces infection risk and expands ambulatory patient candidacy.
- South Korea MFDS Fast-Track Designation:Accelerated approval for innovative medical devices supports market entry for motor cortex interface developers targeting stroke rehabilitation centers.
Industry Challenges
- Neural Signal Processing Talent Scarcity:Competition for computational neuroscientists and machine learning engineers with biological signal expertise extends R&D timelines.
- Biocompatibility Certification Complexity:ISO 10993 cytotoxicity and sensitization testing for novel polymer encapsulants requires 12-18 month validation cycles before clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuroprosthetics Market |
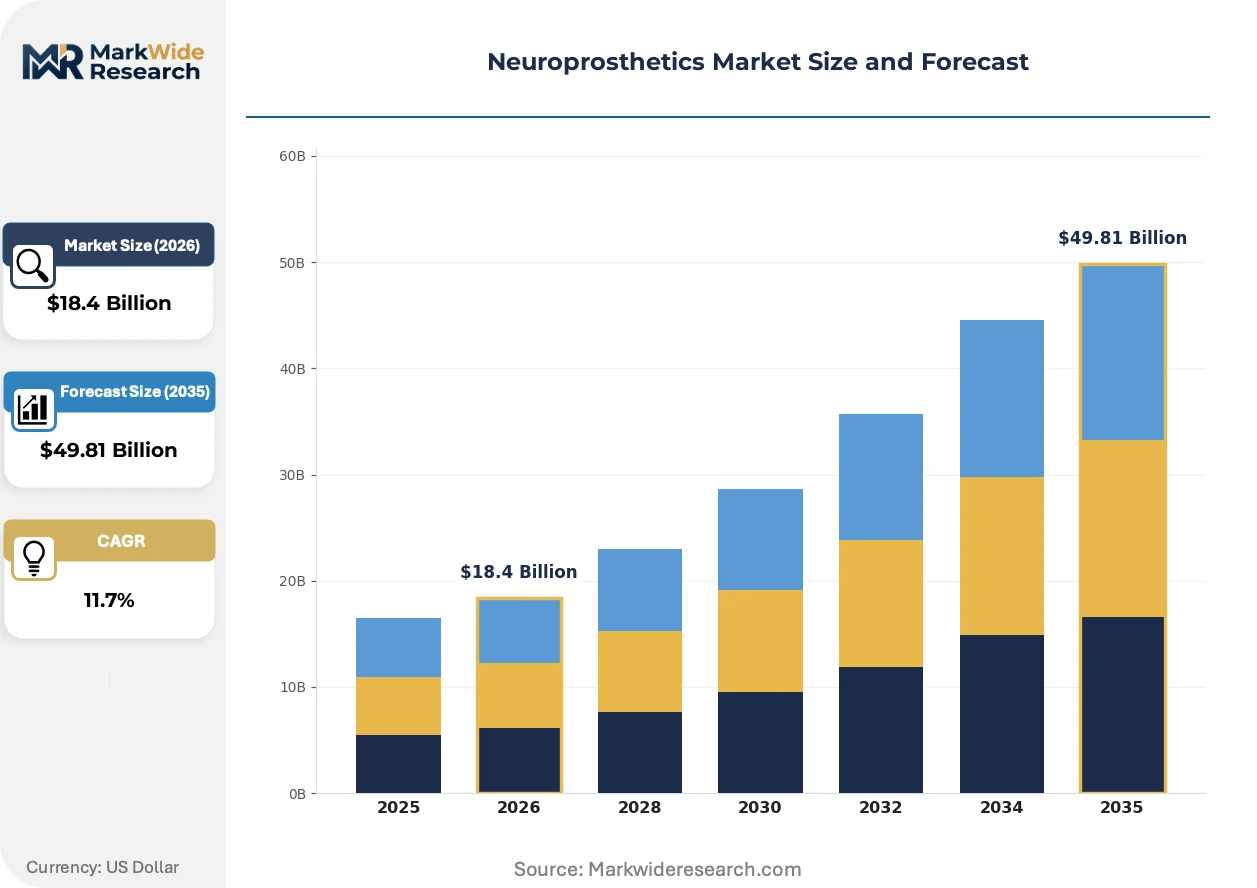
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $49.81 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brain-Machine Interface, Cochlear Implants, Retinal Implants, Spinal Cord Stimulators, Deep Brain Stimulators Application: Motor Function Restoration, Sensory Restoration, Pain Management, Epilepsy Control, Cognitive Enhancement End User: Neurology Clinics, Rehabilitation Centers, Research Institutes, Home Care Patients Technology: Microelectrode Arrays, Wireless Systems, Neurofeedback Devices, Implantable Sensors, Optical Sensors |
| Companies Covered | Medtronic, Boston Scientific Corporation, Cochlear Limited, Abbott Laboratories, LivaNova PLC, NeuroPace, Inc., Nevro Corp., MED-EL Medical Electronics, Sonova Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuroprosthetics Market Strategic Shifts & Innovations
Neural interface hardware is undergoing platform consolidation as manufacturers abandon bespoke analog front-ends in favor of standardized system-on-chip architectures. This shift enables faster iteration cycles and reduces non-recurring engineering costs for new indication expansion.
High-density microelectrode arrays is migrating from research-grade silicon probes toward clinical-grade flexible polymer substrates. Academic medical centers in the United States are piloting these devices for speech restoration in locked-in syndrome patients. The technology is compressing the gap between laboratory neuroscience and reimbursable clinical practice.
EU MDR Article 117 requirements for drug-device combination neuroprosthetics have triggered wholesale redesign of implantable pulse generator labeling and clinical evidence packages. Manufacturers now face mandatory consultation with medicinal product regulators for devices incorporating pharmaceutical coatings. Pain management applications bear the heaviest compliance burden due to prior reliance on predicate device pathways.
Hospital procurement committees are demanding unbundled service contracts that separate device acquisition from programming and maintenance obligations. Neurophysiologists and rehabilitation specialists in Germany increasingly contract directly with manufacturers for ongoing parameter optimization. This disintermediation of traditional distributor relationships concentrates vendor accountability at the point of care.
Neuroprosthetics Market Segmentation
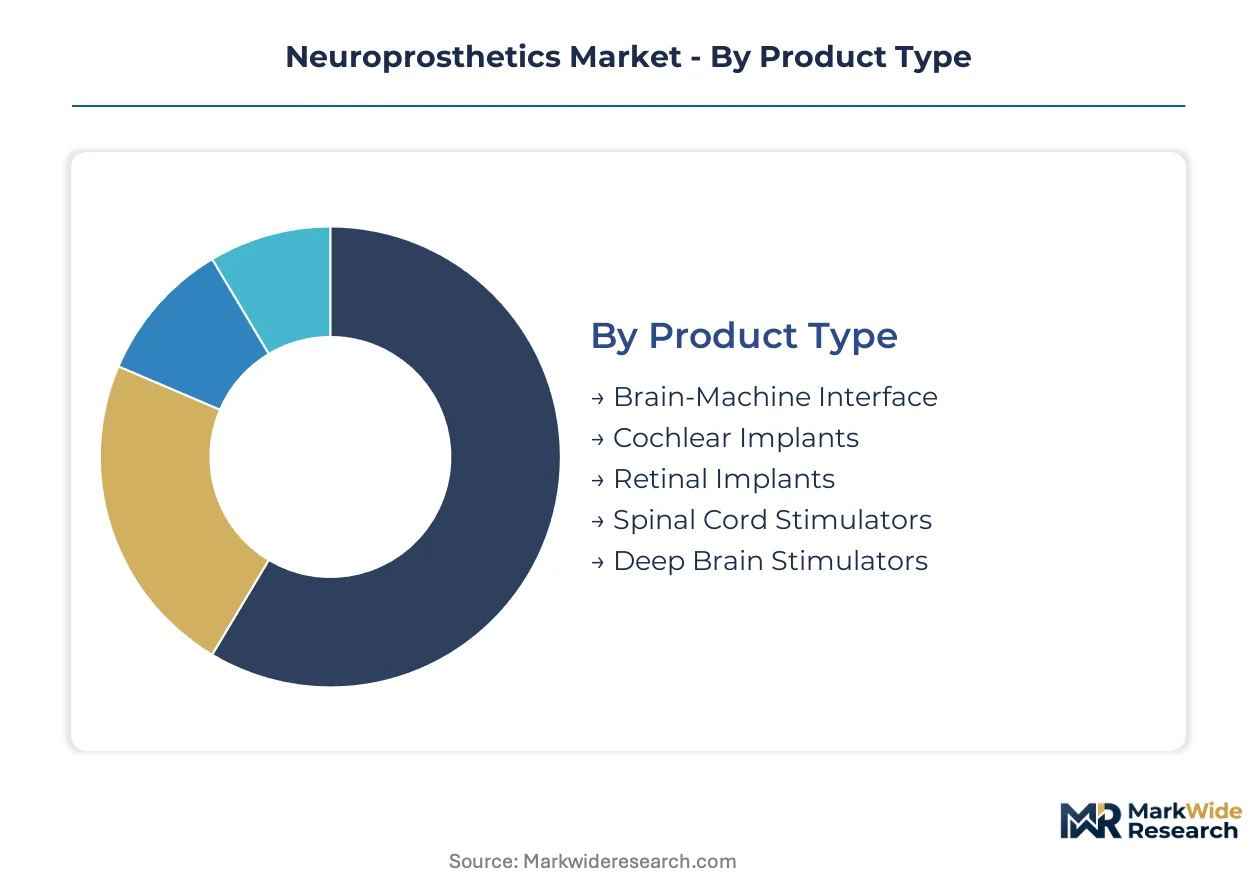
Neuroprosthetics segmentation reveals distinct commercialization timelines across product categories, with reimbursement maturity and surgical workflow integration determining revenue concentration. Understanding these divisions enables targeted resource allocation across development, regulatory, and market access functions.
Product Type:
Use-case spectrum spans auditory restoration through cognitive augmentation, with each modality presenting unique electrode material requirements and signal processing architectures.
- Cochlear Implants:Electrode arrays with 12-24 contacts interface directly with the cochlear nerve, enabling frequency-place coding for severe-to-profound sensorineural hearing loss. Germany's statutory health insurance mandates coverage, eliminating payer friction and sustaining surgical volume at major ENT centers.
- Brain-Machine Interface:High-density microelectrode arrays decode motor cortex signals for cursor control or robotic arm operation in spinal cord injury patients. Major university hospitals in the United States pilot these systems for locked-in syndrome, though reimbursement remains investigational.
- Retinal Implants:Epiretinal and subretinal electrode configurations restore limited light perception in retinitis pigmentosa.
- Spinal Cord Stimulators:Implantable pulse generators with percutaneous leads modulate dorsal column activity for chronic neuropathic pain.
- Deep Brain Stimulators:Bilateral electrode targeting of subthalamic nucleus or globus pallidus interna manages Parkinson's motor symptoms.
The dominant share belongs to Cochlear Implants, while Brain-Machine Interface is closing the gap fastest.
Application:
Customer pain severity and functional impairment level determine willingness to undergo implantation surgery and accept device maintenance obligations.
- Pain Management:Spinal cord and peripheral nerve stimulation address failed back surgery syndrome and complex regional pain syndrome. Volume concentrates at interventional pain clinics in the United States, though non-invasive neuromodulation alternatives capture mild-to-moderate cases.
- Motor Function Restoration:Brain-machine interfaces and functional electrical stimulation systems bypass damaged corticospinal tracts. Rehabilitation centers at major university hospitals drive pilot adoption, with parameter optimization requiring direct manufacturer-physician collaboration.
- Sensory Restoration:Cochlear and retinal implants replace lost transduction mechanisms with engineered electrode-neural interfaces.
- Epilepsy Control:Responsive neurostimulation detects seizure onset and delivers targeted counter-stimulation.
- Cognitive Enhancement:Experimental deep brain stimulation targets memory circuits in early Alzheimer's disease.
Pain Management captures the highest procedure volume, while Motor Function Restoration shows the steepest expansion trajectory as decoding algorithms mature.
End User:
Procurement authority and technical sophistication vary sharply across settings, from hospital committees to individual patients.
- Neurology Clinics:Movement disorder specialists program deep brain stimulators and manage medication-device interactions. Germany's reimbursement framework supports dedicated programming sessions, concentrating post-implant care at certified centers.
- Rehabilitation Centers:Spinal cord injury programs integrate functional electrical stimulation with physical therapy protocols. Major university hospitals in the United States pilot brain-machine interface training regimens.
- Research Institutes:Academic medical centers validate novel electrode materials and closed-loop algorithms before regulatory submission.
- Home Care Patients:Self-administered transcutaneous electrical nerve stimulation and emerging wearable neuroprosthetics bypass clinical settings entirely.
Neurology Clinics account for the largest revenue share, though Rehabilitation Centers are gaining share fastest as spinal cord injury programs expand.
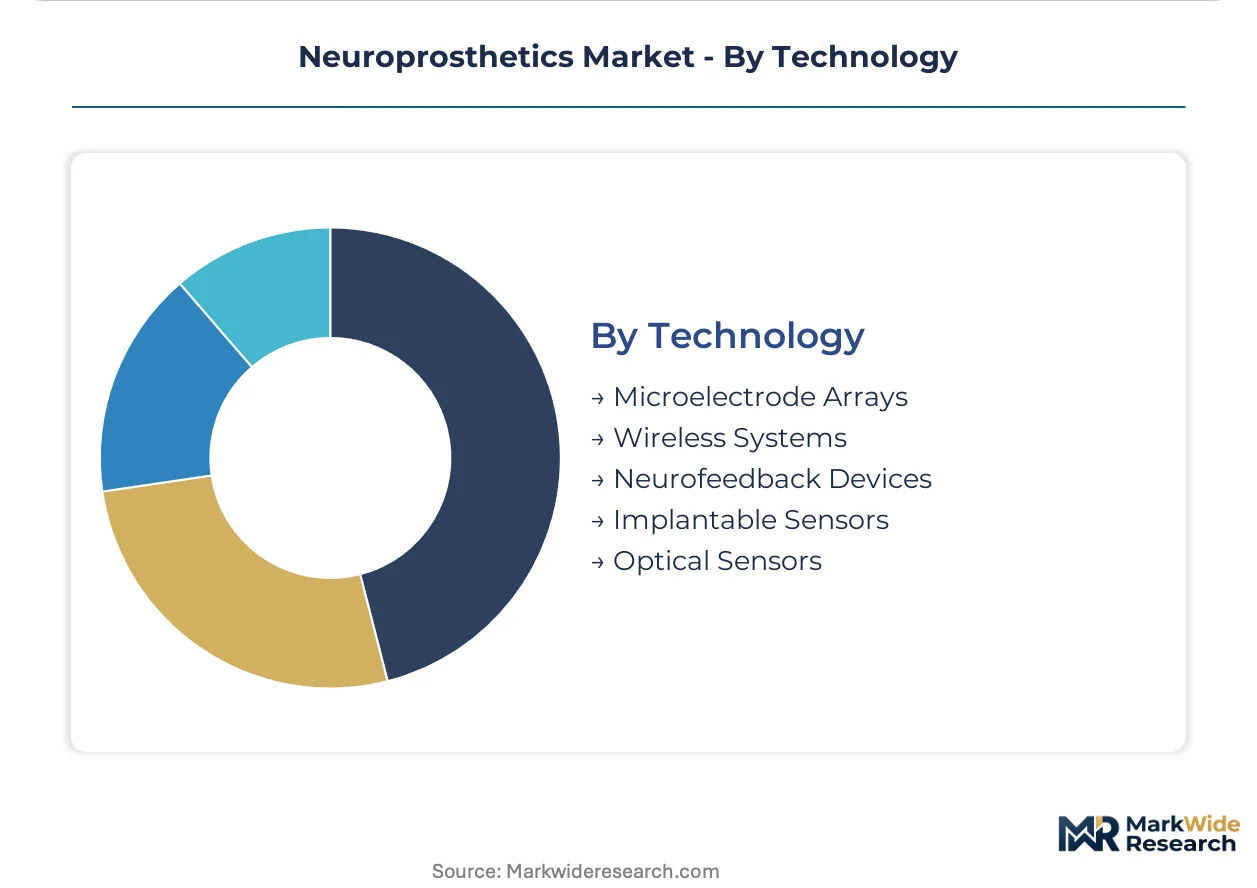
Technology:
Hardware architecture choices determine signal fidelity, power consumption, and regulatory classification complexity.
- Microelectrode Arrays:Silicon or polymer substrates with electrode densities exceeding 100 channels per square millimeter enable single-neuron resolution. Academic medical centers in the United States deploy these for speech restoration research, though clinical translation requires ISO 10993 biocompatibility validation.
- Wireless Systems:Inductive power transfer and Bluetooth Low Energy telemetry eliminate percutaneous connectors, reducing infection risk and expanding ambulatory candidacy. FDA breakthrough device designation accelerates review for wireless brain-machine interfaces.
- Neurofeedback Devices:Real-time brain state visualization supports self-regulation training for attention or anxiety disorders.
- Implantable Sensors:Chronic electrochemical or electrophysiological monitoring enables closed-loop parameter adjustment.
- Optical Sensors:Fiber-optic or optogenetic approaches offer spatial precision without electrical artifact.
Microelectrode Arrays hold the dominant technology position, while Wireless Systems are climbing the fastest as infection risk reduction becomes a procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German neuroprosthetic manufacturers export cochlear and deep brain stimulation systems to university hospitals across the United States, Japan, and South Korea, establishing a dominant trade corridor in active implantable devices.
United States
FDA breakthrough device designation accelerates commercial timelines for brain-machine interface developers targeting spinal cord injury rehabilitation. The agency's expedited review pathway compresses regulatory cycles for technologies addressing irreversibly debilitating conditions. Major university hospitals in California and Massachusetts pilot high-density microelectrode arrays for locked-in syndrome patients.
Germany
Statutory health insurance mandates reimbursement for cochlear and deep brain stimulation procedures, eliminating payer friction and sustaining surgical volume. The EU MDR conformity assessment framework demands extensive clinical evidence for active implantable devices, lengthening notified body engagement. ENT surgical workflows in Berlin and Munich concentrate demand for auditory restoration systems.
Japan
PMDA parallel track navigation offers dedicated regulatory pathways for novel neuroprosthetic indications, creating first-mover advantages in Asia-Pacific's second-largest medical device market. METI funding programs support domestic development of closed-loop neural interfaces. Tokyo and Osaka academic medical centers validate flexible polymer substrate electrodes before regulatory submission.
South Korea
MFDS fast-track designation accelerates approval for innovative medical devices, supporting market entry for motor cortex interface developers. Government-backed stroke rehabilitation centers drive pilot adoption of brain-machine interface training regimens. Seoul and Daejeon host concentration of neural signal processing research institutes.
Switzerland
Swissmedic maintains distinct approval tracks for neuroprosthetics that manufacturers must navigate for European market access beyond EU MDR. Precision manufacturing clusters in Basel and Zurich supply biocompatible electrode materials with impedance values below 10 kΩ. Academic partnerships between ETH Zurich and university hospitals advance optical sensor technologies.
Neuroprosthetics Market Key Industry Players
Channel-controlling players compete with product-specialist players across implantable pulse generator categories, creating a tiered market structure where integrated neuromodulation platforms face challenge from modality-specific innovators. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with neuromodulation divisions, pure-play auditory restoration specialists, and emerging brain-machine interface developers. Dominant competitive moves include portfolio diversification into wireless power transfer capabilities and strategic partnerships with academic medical centers for clinical validation.
Within the diversified conglomerate tier, Medtronic and Boston Scientific Corporation exemplify channel-controlling players that sustain leadership across multiple implantable pulse generator categories. Cochlear Limited occupies a specialist position, anchoring the auditory restoration segment with dedicated electrode array expertise. These three companies represent distinct competitive positions: integrated platform breadth, multi-indication scale, and single-modality depth.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Cochlear Limited |
| Abbott Laboratories |
| LivaNova PLC |
| NeuroPace, Inc. |
| Nevro Corp. |
| MED-EL Medical Electronics |
| Sonova Holding AG |
| Others |
Cost & Logistics Intelligence
Platinum-iridium electrode material volatility compresses margin structures across high-channel-count implantable devices, forcing manufacturers to widen spreads between FDA breakthrough-designated premium tiers and economy alternatives while reshaping sourcing strategies toward Swiss and German precision clusters.
Pricing Analysis
Current-generation wireless brain-machine interfaces command substantial premiums over prior-generation percutaneous connector systems, while next-generation closed-loop architectures with inductive charging establish new price ceilings. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated motor cortex interfaces from EU MDR-certified pain management devices and basic functional electrical stimulation systems. Price differentiation rests on ISO 10993 biocompatibility certification grade and channel density specifications. Cost compression in the economy tier is intensifying because South Korean and Chinese manufacturers are entering spinal cord stimulator categories. Rehabilitation centers at major university hospitals exhibit lowest price sensitivity due to dedicated research funding streams, while community neurology clinics face acute budget constraints.
Supply Chain Analysis
Extended payment terms from German statutory health insurance procurement committees are forcing manufacturers to deploy supply-chain finance facilities covering 90-120 day receivable cycles. Biocompatible electrode materials concentrate in Switzerland, Germany, and Japan, with precision manufacturing clusters in Basel, Munich, and Osaka supplying impedance-calibrated components. Raw material dependencies include platinum-iridium alloys, medical-grade silicone encapsulants, and lithium-ion cells for implantable pulse generators. Single-source vulnerability permeates high-density microelectrode array substrates sourced from specialized semiconductor foundries. Distribution runs through hospital procurement committees in the United States and direct manufacturer-physician contracting networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programming and parameter optimization services are expanding faster than hardware sales as hospital procurement committees unbundle device acquisition from maintenance obligations, creating recurring revenue pools that outpace implantable pulse generator shipments.
For Market Incumbents: Entrench wireless power transfer capabilities across neuromodulation portfolios before non-invasive neuromodulation substitutes capture chronic pain cases. Deepen backward integration into biocompatible electrode materials to offset platinum-iridium cost volatility. Lock in exclusive programming service contracts with German rehabilitation centers to defend against emerging brain-machine interface developers. For New Entrants and Emerging Players: Establish a beachhead in South Korean stroke rehabilitation centers where MFDS fast-track designation accelerates market entry. Target motor function restoration applications where reimbursement remains investigational and incumbent pricing discipline is weakest. Pursue direct contracting relationships with university hospital neurophysiologists to bypass established distributor networks. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors acquisition of specialized electrode array designers over diversified neuromodulation conglomerates. Five-to-ten year viability hinges on closed-loop algorithm differentiation rather than hardware scale. Watch FDA breakthrough device designation grants to brain-machine interface developers as the inflection signal indicating reimbursement pathway clarity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pursuit | Expedited review compresses commercial timelines for spinal cord injury rehabilitation systems. |
| Wireless Power Transfer Integration | Elimination of percutaneous connectors reduces infection risk and expands ambulatory candidacy pools. |
| EU MDR Technical Documentation Investment | Lengthened notified body engagement periods demand dedicated regulatory capital allocation. |
| University Hospital Partnership Network | Direct manufacturer-physician collaboration secures locked-in syndrome and stroke rehabilitation validation sites. |
| Biocompatibility Certification Pipeline | ISO 10993 validation cycles for novel polymer encapsulants precede clinical trial initiation. |
Research Approach
The analysis maps cochlear implant, brain-machine interface, spinal cord stimulator, and deep brain stimulator sub-sectors, each validated through neurophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with industry stakeholders combined with secondary validation against FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up channel checks and top-down macroeconomic triangulation anchored volume estimates.
Assumptions held fixed include regulatory pathway timelines and statutory reimbursement mandates, while variables spanned microelectrode array density improvements and wireless power transfer adoption curves. Segmentation dimensions modeled encompass product type, application, end user, and technology architecture across the projection horizon. CAGRs derived from fitted growth curves incorporating neural signal processing talent availability and biocompatibility certification cycle durations.
Stress conditions across platinum-iridium price volatility, EU MDR notified body capacity constraints, and non-invasive neuromodulation substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement policy evolution and regulatory clearance trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Neurotechnology Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Germany Contraceptive Devices Market