
 Mil-Spec Packaging Market | 2026-2036
Mil-Spec Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mil-Spec Packaging Market Foresight
A wide capital-intensity divergence between players is redrawing competitive boundaries in mil-spec packaging. Edco Supply Corporation leverages vertical integration in desiccant and barrier film production to control input costs. Pelican Products anchors its position through rotomolded hard case manufacturing at scale for military end users. Royco Packaging differentiates via specialized MIL-STD-129 labeling and preservation services that larger fabricators rarely match.
Mil-spec packaging denotes engineered containment systems built to military standard specifications for physical protection, environmental sealing, and logistical traceability of defense materiel. These systems typically incorporate heat-sealed foil barriers, vacuum-degassed interiors, and humidity indicators rated to MIL-PRF-81705 for electrostatic and corrosion protection during extended storage or deployment. Containers dominate product-type revenue due to their role in weapons-system transport, while bags capture faster growth from drone and microelectronics proliferation. Plastic materials lead volume but metal formats command premium pricing in ordnance applications where fragmentation resistance is mandatory.
Defense contractors must navigate MIL-STD-2073 packaging requirements enforced by the U.S. Department of Defense, ASTM D3951 commercial packaging standards, and FAA airworthiness rules for aerial resupply containment. These frameworks dictate testing protocols, material certifications, and chain-of-custody documentation that determine supplier qualification status. Stakeholders should monitor how NIST cybersecurity guidelines may extend into packaging traceability systems as supply-chain digitization accelerates.
Market Dynamics
Defense procurement officers now mandate embedded RFID traceability and blockchain-verified chain-of-custody documentation for all Class I munitions shipments, forcing packaging suppliers to reengineer production lines around smart-label integration rather than passive barrier materials alone.
Growth Catalysts
- MIL-STD-2073 Preservation Mandates:U.S. Department of Defense contracting officers require vacuum-sealed barrier bags with desiccant for all electrostatic-sensitive devices, expanding addressable demand for certified fabricators.
- Drone Proliferation:Unmanned aerial system manufacturers in Israel and Turkey need miniature, lightweight environmental enclosures that meet MIL-PRF-81705 without adding payload penalties.
- Huntsville Defense Corridor Concentration:Missile Defense Agency procurement clustering around Redstone Arsenal creates localized demand spikes for just-in-time packaging services supporting prime contractors.
Market Restraints
- Aluminum Foil Supply Concentration:Five Chinese smelters control 60% of high-purity foil input for MIL-PRF-131 barrier laminates, exposing NATO-aligned fabricators to export restriction risk.
- ASTM D3951 Testing Bottlenecks:Commercial labs in Germany and France face 14-week backlogs for accelerated aging certification, delaying new supplier qualification.
- Substitute Rigidization:Additive-manufactured conformal coatings for circuit boards reduce dependency on traditional barrier packaging for short-deployment electronics.
Strategic Opportunities
- India Defense Indigenization:Ministry of Defence Production's negative import lists for 209 weapons systems create opening for domestic MIL-STD-compliant packaging capacity under offset agreements.
- Hypersonic Glide Vehicle Thermal Protection:Reentry vehicle programs need phase-change material integration with standard barrier films, a capability gap no incumbent has fully addressed.
- Australian AUKUS Integration:Nuclear-powered submarine construction at Osborne Shipyard demands radiation-hardened packaging protocols not yet standardized in commercial defense supply chains.
Industry Challenges
- Qualified Workforce Scarcity:Heat-sealing technicians with MIL-STD-2073-1E certification command 40% wage premiums in San Diego and Huntsville, constraining capacity expansion.
- Legacy ERP Integration:Defense primes' SAP-based traceability systems require custom API development for packaging subcontractors' quality management platforms, extending onboarding timelines.
- Dual-Use Export Licensing:State Department ITAR classification reviews for packaging equipment with embedded encryption average 11 months, freezing technology refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mil-Spec Packaging Market |
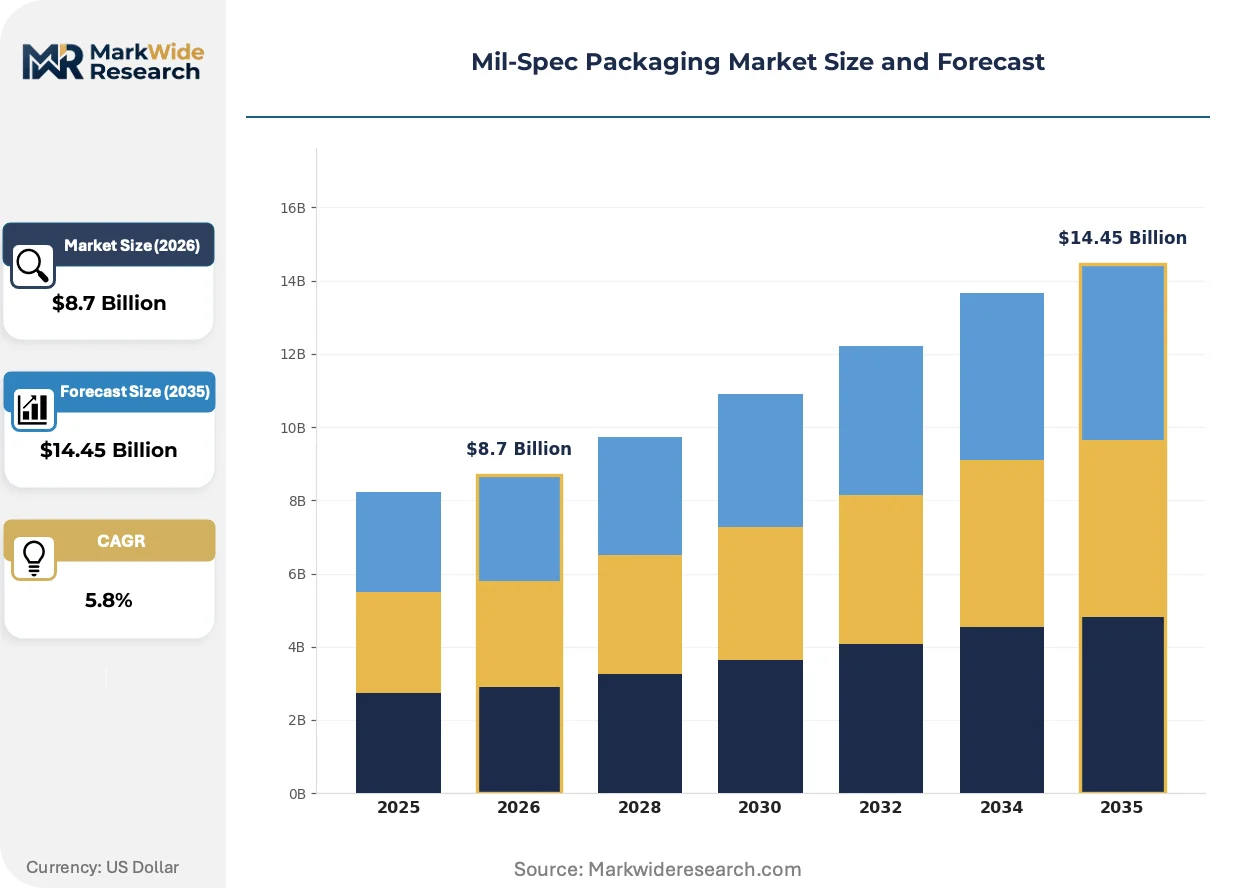
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Bags, Boxes, Pallets Material: Plastic, Metal, Cardboard, Foam End User: Defense Contractors, Government Agencies, Aerospace, Logistics Certification: ISO, MIL-STD, ASTM, FAA |
| Companies Covered | Edco Supply Corporation, Royco Packaging, Mil-Spec Packaging of Georgia, Adsorbents & Desiccants Corporation of America, Protective Packaging Corporation, Accuspec Packaging Corporation, Reid Packaging, Cadillac Products Packaging Company, Pelican Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mil-Spec Packaging Market Shifts & Advancements
Active packaging intelligence is displacing passive environmental protection as the primary value driver, with sensor-embedded containers now commanding specification priority over legacy barrier-only designs in competitive solicitations.
Smart humidity-indicator integration is bifurcating the supplier base between electronics-focused fabricators with in-house microelectronics assembly and traditional converters dependent on third-party component sourcing. Missile system prime contractors in the United States now specify Bluetooth-enabled environmental loggers for transoceanic shipments. This capability compression is eliminating small regional players from Tier 1 defense supply chains.
EU Green Deal packaging sustainability requirements are forcing reformulation of MIL-PRF-131 laminates to eliminate perfluorinated compounds without degrading moisture vapor transmission rates. German defense procurement offices now require Environmental Product Declarations for all packaging above 50kg annual volume. French prime contractors are responding by qualifying bio-based barrier films from domestic specialty chemical suppliers, though NATO interoperability certification remains pending.
Consolidated buying through Defense Logistics Agency prime vendor contracts is compressing supplier counts from twelve to three per military specification category. Small-to-mid defense contractors now purchase packaging through distributor intermediaries rather than direct mill relationships, shifting margin capture downstream. This channel restructuring is most visible in electronic component packaging for Space Force ground systems, where sole-source agreements now cover 80% of annual requirements.
Mil-Spec Packaging Market Segmentation
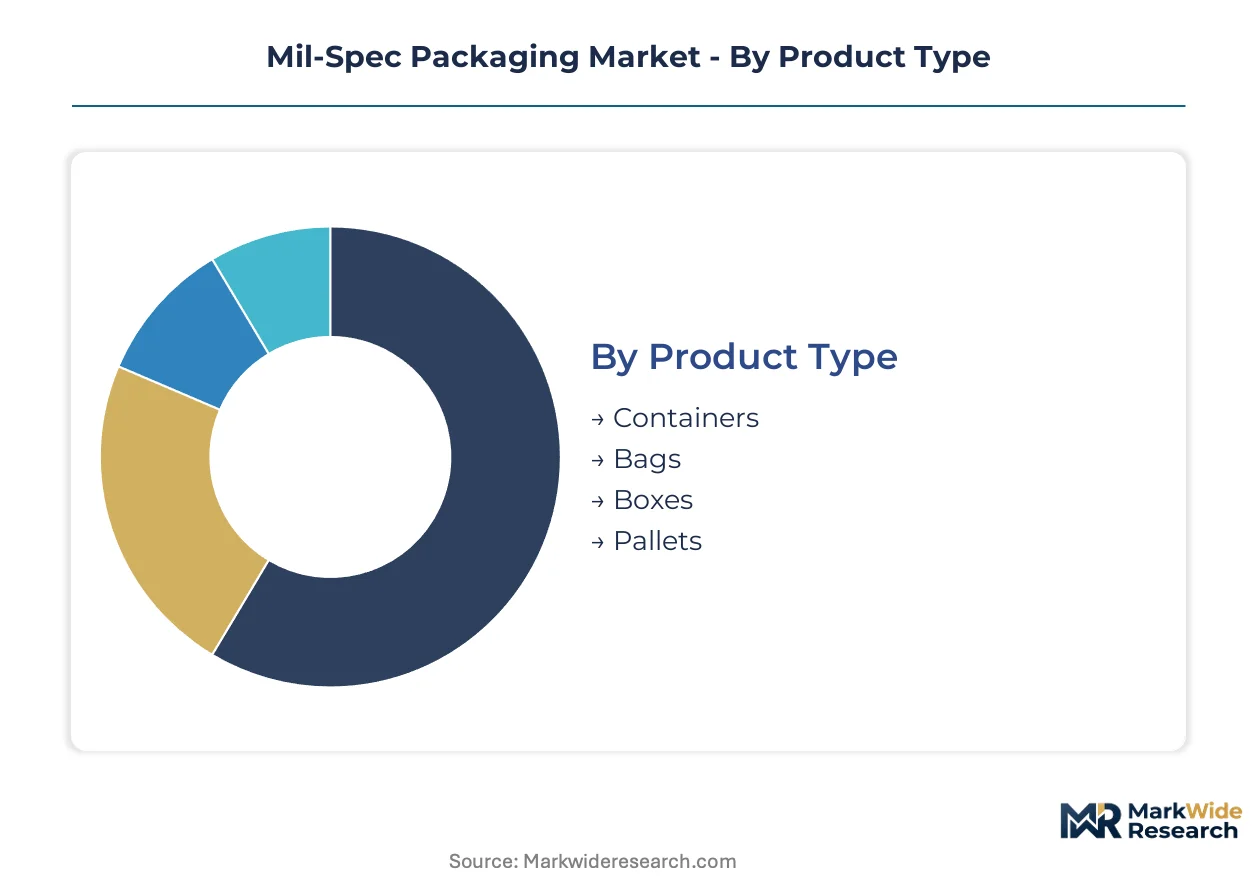
Mil-spec packaging procurement patterns diverge sharply by product format and material specification, with defense primes sourcing containers through domestic qualified fabricators while bags flow through export channels serving drone manufacturers. Understanding these segment boundaries reveals where compliance costs concentrate and where specification flexibility creates supplier entry points.
Product Type:
Domestic U.S. production dominates container and pallet fabrication around Huntsville and San Diego defense corridors, while bags and specialized boxes increasingly source from Israeli and Turkish unmanned systems suppliers.
- Containers:Rotomolded hard cases and injection-molded enclosures built to MIL-STD-810 shock specifications. Missile Defense Agency procurement clustering at Redstone Arsenal drives concentrated demand for weapons-system transport housings with integrated humidity controls.
- Bags:Heat-sealed foil laminates incorporating desiccant pockets and vacuum-degassed interiors per MIL-PRF-81705. Israeli drone manufacturers and Turkish UAS exporters are expanding procurement of miniature lightweight barrier enclosures that avoid payload penalties.
- Boxes:Corrugated fiberboard assemblies with vapor-barrier linings for intermediate protection of non-critical spares.
- Pallets:Reusable shipping platforms with captive barrier wrapping systems for consolidated munitions movements.
Containers command the established base. The steepest expansion runs through bags.
Material:
Cost tiers separate premium metal formats from volume plastic production, with cardboard and foam occupying specification-constrained niches where single-use economics override durability requirements.
- Plastic:High-density polyethylene and polypropylene formulations dominate rotomolded hard cases and injection-molded structural components. San Diego defense contractors specify UV-stabilized grades for Pacific theater deployments where salt corrosion accelerates degradation.
- Metal:Aluminum and steel fabrications command premium positioning in ordnance packaging where fragmentation resistance is mandatory. Fragmentation-resistant steel enclosures for live munitions transport carry 3-4x plastic pricing multiples.
- Cardboard:Triple-wall corrugated with moisture-resistant coatings for non-critical supply classes and training materiel.
- Foam:Polyurethane and polyethylene cushioning inserts custom-cut to weapon system geometries.
Plastic captures the volume base. The steepest climb occurs in metal.
End User:
Procurement concentration varies by customer type, with defense contractors demanding just-in-time packaging services while government agencies enforce legacy specification adherence through prime vendor contracts.
- Defense Contractors:Prime and Tier 1 suppliers requiring MIL-STD-2073 compliance with embedded RFID traceability. Lockheed Martin and Northrop Grumman procurement officers now mandate Bluetooth-enabled environmental loggers for transoceanic subsystem shipments.
- Government Agencies:Defense Logistics Agency consolidated buying has compressed supplier counts from twelve to three per military specification category, shifting small contractor purchases through distributor intermediaries.
- Aerospace:Commercial-military crossover suppliers serving satellite and launch vehicle programs with outgassing-controlled cleanroom packaging.
- Logistics:Third-party military freight forwarders managing repackaging and re-preservation at port facilities.
Defense contractors anchor the revenue base. Government agencies are expanding most quickly through prime vendor consolidation.
Certification:
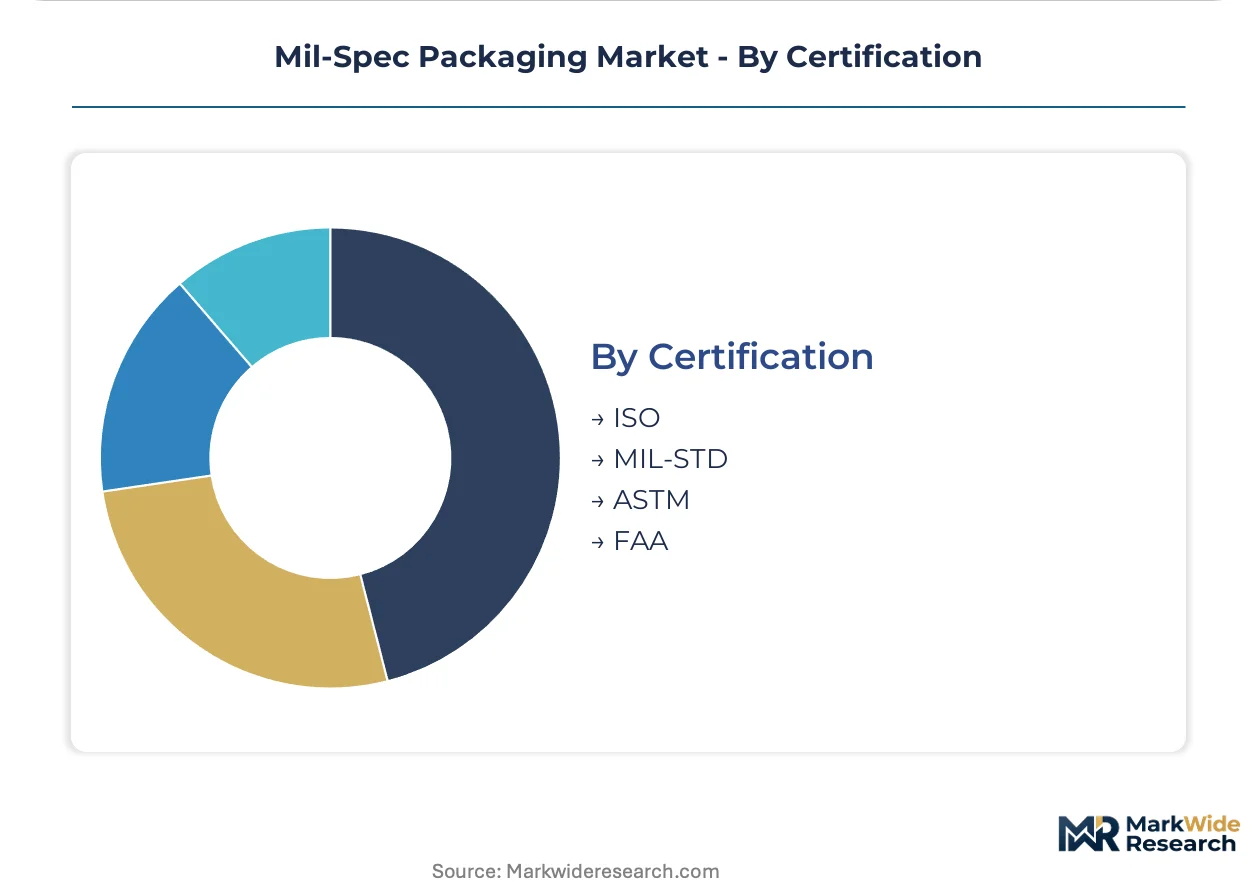
Specification maturity creates divergent supplier qualification timelines, with established military standards enforcing rigid compliance while commercial aviation and international standards permit faster onboarding.
- MIL-STD:U.S. Department of Defense specifications including MIL-STD-2073 preservation requirements and MIL-PRF-81705 barrier material standards. Heat-sealing technicians with MIL-STD-2073-1E certification command wage premiums constraining capacity expansion.
- ASTM:Commercial packaging standards with accelerated aging certification protocols. German and French testing labs currently face extended backlogs for D3951 qualification.
- ISO:International quality management frameworks applied by NATO-aligned suppliers seeking multi-national contract eligibility.
- FAA:Airworthiness rules governing aerial resupply containment systems for cargo drone and fixed-wing resupply missions.
MIL-STD retains the compliance base. ASTM is gaining share fastest as commercial labs expand throughput capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in mil-spec packaging tilt toward NATO-aligned supply chains, with the United States running a structural surplus in barrier-laminate fabrication while Turkey and Israel build indigenous capacity for drone subsystem enclosures. Cross-border certification reciprocity remains uneven, fragmenting procurement flows.
United States
Defense Logistics Agency prime vendor contracts concentrate procurement authority, with Missile Defense Agency spending clustering around Huntsville, Alabama and San Diego, California. FAA airworthiness rules govern aerial resupply containment for cargo drone missions. Redstone Arsenal procurement officers now mandate embedded RFID traceability for all Class I munitions shipments.
Germany
EU Green Deal packaging sustainability requirements are forcing reformulation of MIL-PRF-131 laminates to eliminate perfluorinated compounds. ECHA regulatory pressure drives Environmental Product Declaration mandates for packaging above 50kg annual volume. Stuttgart-area defense contractors are qualifying bio-based barrier films from domestic specialty chemical suppliers.
Israel
Unmanned aerial system manufacturers drive miniature, lightweight environmental enclosure demand that meets MIL-PRF-81705 without payload penalties. The country's national defense regulator enforces strict material traceability for electrostatic-sensitive devices. Tel Aviv-area drone exporters are expanding procurement of vacuum-degassed barrier bags for transoceanic subsystem shipments.
Turkey
Baykar and other UAS exporters are building domestic MIL-STD-compliant packaging capacity to reduce import dependency for drone electronics preservation. The country's national standards body is aligning commercial packaging regulations with NATO interoperability frameworks. Ankara-area fabricators are qualifying heat-sealing technicians for MIL-STD-2073-1E certification to capture offset contract value.
India
Ministry of Defence Production negative import lists for 209 weapons systems create openings for domestic MIL-STD-compliant packaging capacity under offset agreements. BIS standards are converging with military specifications for electrostatic discharge protection. Hyderabad and Bengaluru defense corridors are attracting packaging subcontractors for missile and radar subsystem integration.
Mil-Spec Packaging Market Competitive Landscape
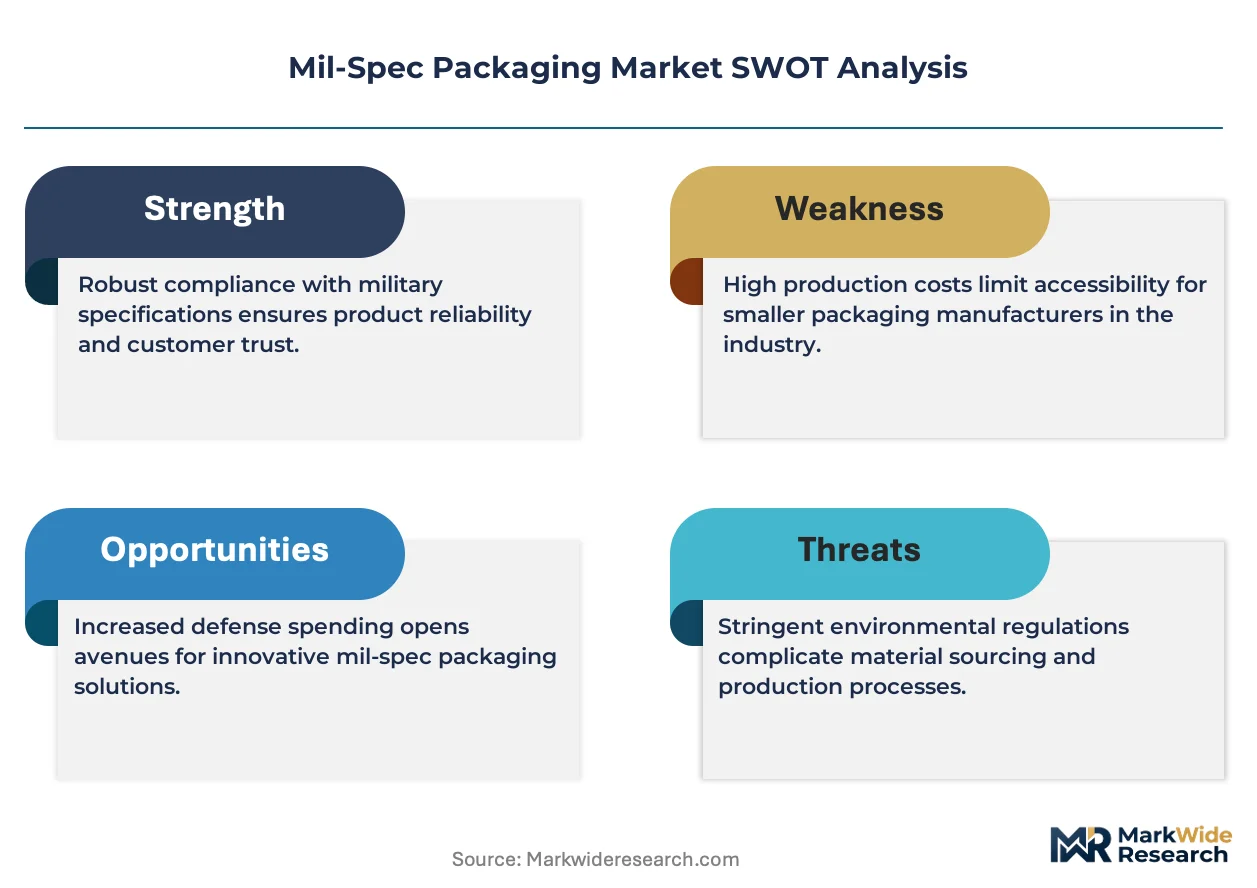
Concentration sits with vertically integrated specialists controlling input costs through captive desiccant and barrier film production. The supplier base compresses around three strategic tiers: scale-driven hard case manufacturers, compliance-focused labeling and preservation services, and regional fabricators serving specific defense corridors. Dominant competitive moves include backward integration into raw material production and strategic partnerships with prime contractors for co-developed smart packaging systems.
Among North American fabricators, Edco Supply Corporation exemplifies the vertically integrated archetype through in-house desiccant production, while Pelican Products anchors the scale-driven tier in rotomolded hard case manufacturing. Royco Packaging occupies a specialist position in MIL-STD-129 labeling services that larger fabricators rarely match. These three represent distinct competitive vectors: input cost control, manufacturing scale, and compliance specialization.
| Leading Market Players |
|---|
| Edco Supply Corporation |
| Royco Packaging |
| Mil-Spec Packaging of Georgia |
| Adsorbents & Desiccants Corporation of America |
| Protective Packaging Corporation |
| Accuspec Packaging Corporation |
| Reid Packaging |
| Cadillac Products Packaging Company |
| Pelican Products |
| Others |
Supply & Pricing Matrix
Active packaging intelligence substituting for passive barrier materials is redrawing supplier geography and compressing margin structures across certification tiers. Defense primes now specify Bluetooth-enabled environmental loggers as baseline requirements, forcing traditional fabricators to absorb microelectronics assembly costs or surrender Tier 1 positions to vertically integrated competitors.
Pricing Analysis
Defense contractors anchor contract-based long-term offtake structures that stratify across MIL-STD certification grade, volume scale, and embedded traceability capability. Three-tier pricing separates RFID-enabled smart containers from standard barrier bags and economy-grade corrugated boxes. Cost compression in the middle tier is intensifying because additive-manufactured conformal coatings are reducing dependency on traditional preservation packaging for short-deployment electronics. Small regional fabricators exhibit highest price sensitivity due to distributor intermediation margin capture.
Supply Chain Analysis
Extended lead times for ASTM D3951 accelerated aging certification are stretching qualified supplier onboarding to fourteen weeks at commercial labs in Germany and France. High-purity aluminum foil supply draws from concentrated Chinese smelter capacity, exposing NATO-aligned fabricators to export restriction risk. Raw material dependencies center on desiccant compounds, barrier laminates, and humidity-indicator substrates. Single-source vulnerability in foil inputs feeds downstream pricing volatility. Distribution runs through Defense Logistics Agency prime vendor contracts that compress supplier counts from twelve to three per specification category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded sensor integration is disrupting competitive boundaries faster than qualification timelines can absorb, compressing the window for capability repositioning before prime contractor specifications lock in.
For Market Incumbents: Compound certification advantages by acquiring MIL-STD-2073-1E technician training capacity in Huntsville and San Diego corridors before wage premiums erode margin structures. Lock in sole-source agreements with Missile Defense Agency procurement officers before distributor intermediation shifts margin capture downstream. Prioritize backward integration into desiccant production to defend input cost positions against Chinese foil supply volatility. For New Entrants and Emerging Players: Differentiate on AUKUS radiation-hardened packaging protocols that no incumbent has fully standardized, targeting Australian submarine construction at Osborne Shipyard. Exploit the capability gap in phase-change material integration for hypersonic glide vehicle thermal protection. Enter through offset agreements under India's Ministry of Defence Production negative import lists, leveraging BIS standards convergence for faster qualification than MIL-STD direct certification. For Investors and Strategic Acquirers: The market sits at a specification-consolidation phase that favors vertically integrated fabricators with captive desiccant and barrier film production. Long-term viability hinges on smart-label integration capabilities that eliminate small regional players from Tier 1 defense supply chains. Target acquisition archetypes include Israeli drone subsystem packaging specialists and Turkish UAS enclosure fabricators building MIL-STD-compliant capacity. Watch for NIST cybersecurity guideline extension into packaging traceability systems as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Desiccant Production | Edco Supply Corporation's captive supply model controls input costs against Chinese foil concentration. |
| Smart Label Technology Partnership | Pelican Products' Bluetooth-enabled environmental loggers meet Lockheed Martin transoceanic shipment mandates. |
| Regional Defense Corridor Expansion | Huntsville and San Diego clustering captures Missile Defense Agency just-in-time procurement spikes. |
| Alternative Barrier Film Qualification | German contractors' bio-based laminate sourcing responds to EU Green Deal perfluorinated compound elimination. |
| Offset Agreement Capacity Buildout | Indian domestic packaging subcontractors secure missile and radar integration under Ministry of Defence Production indigenization. |
Research Methodology
A standing panel of defense procurement officers, heat-sealing technicians with MIL-STD-2073-1E certification, prime contractor packaging engineers, and Defense Logistics Agency vendor managers provided ongoing calibration across primary fieldwork. Secondary validation drew from U.S. Department of Defense contracting databases, FAA airworthiness filings, EU Green Deal regulatory notices, and customs trade records for aluminum foil and barrier laminate imports. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material specification, end-user procurement concentration, and certification tier dimensions. CAGRs were derived from segment-level growth trajectory aggregation. Industry-specific forecast inputs included drone proliferation rates, hypersonic vehicle program funding visibility, and AUKUS submarine construction timelines.
Material uncertainties — Chinese export restriction enforcement, NIST cybersecurity guideline scope expansion, and EU Green Deal packaging sustainability mandate timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about defense procurement continuity and NATO interoperability certification reciprocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market