
 Blister Paper Market | 2026-2036
Blister Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Blister Paper Market Outlook
Contract packaging networks between Germany and the Netherlands is rewriting procurement geography for blister paper converters. Huhtamaki Oyj anchors Nordic supply through integrated fiber sourcing and thermoforming capabilities. Ecobliss Packaging Group specializes in sustainable cold-seal blister systems for temperature-sensitive pharmaceuticals. Syntegon Technology GmbH dominates equipment-linked material specifications, forcing substrate compliance across its installed base.
Blister paper consists of coated or laminated fiberboard substrates engineered for thermoformability, typically incorporating heat-seal coatings of vinyl or aqueous dispersions at basis weights between 200 and 400 gsm. The material forms cavities through vacuum or pressure thermoforming, then seals to lidding film to create tamper-evident unit-dose packages for tablets, capsules, and medical devices. Paper-based substrates within product type segmentation lead in sustainability positioning but trail PVC and PET in moisture barrier performance, creating a split where premium pharmaceutical applications favor hybrid constructions while consumer electronics and personal care gravitate toward lighter paper-only formats. Application segmentation shows pharmaceuticals commanding the highest specification thresholds, with food packaging representing the fastest volume expansion as snack and confectionery brands adopt fiber-based visibility packaging.
FDA unit-dose labeling requirements and EMA serialization mandates shape blister paper specifications through traceability coding surfaces and child-resistant opening features. REACH restrictions on phthalate plasticizers and EU Green Deal circularity targets push converters toward aqueous coating systems and recycled fiber content verification. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables, as regulatory divergence between FDA container closure guidance and European Pharmacopoeia chapters threatens to fragment substrate approval pathways.
Market Dynamics
Europe's F-Gas Regulation and REACH standards are compressing plastic blister demand while forcing pharmaceutical packagers toward fiber-based substrates that meet thermoformability and barrier specifications simultaneously.
Growth Catalysts
- EMA serialization mandates:European pharmaceutical manufacturers must upgrade packaging lines to accommodate traceability coding surfaces, expanding specification requirements for printable blister paper substrates.
- Unit-dose compliance packaging:Aging demographics in Germany and Japan drive pharmaceutical dispensing reforms that favor pre-formed cavity packs over bulk containers.
- Aqueous coating systems:Water-based heat-seal dispersions eliminate solvent emissions while maintaining seal integrity against aluminum lidding films.
Market Restraints
- Pulp price volatility:Northern European softwood fiber costs swing with energy market turbulence, compressing converter margins on fixed-price pharmaceutical contracts.
- Moisture barrier inferiority:Uncoated paper substrates exhibit water vapor transmission rates 40-100x higher than PVC, limiting deployment for hygroscopic drug formulations.
- Equipment lock-in effects:Syntegon Technology GmbH's installed base of thermoforming lines specifies narrow substrate parameter windows, freezing out experimental fiber grades.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO's alignment with ICH stability guidelines creates substrate approval pathways for European-qualified blister paper suppliers.
- Food visibility packaging:Snack brands in France and Italy trial fiber-based transparent windows as single-use plastic bans tighten.
- Cold-seal adhesive convergence:Pressure-sensitive natural rubber formulations enable room-temperature sealing for temperature-sensitive biologics without heat degradation.
Industry Challenges
- Extractables validation timelines:European Pharmacopoeia chapters 3.2.9 and USP <661> require 24-month stability studies for new coating chemistries, delaying commercialization.
- Thermoforming technician scarcity:Vacuum-forming process optimization for fiber-based substrates demands skills absent from conventional plastic blister operations.
- Multi-material separation:Hybrid paper-plastic constructions complicate pharmaceutical packaging waste streams under EU Green Deal circularity targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blister Paper Market |
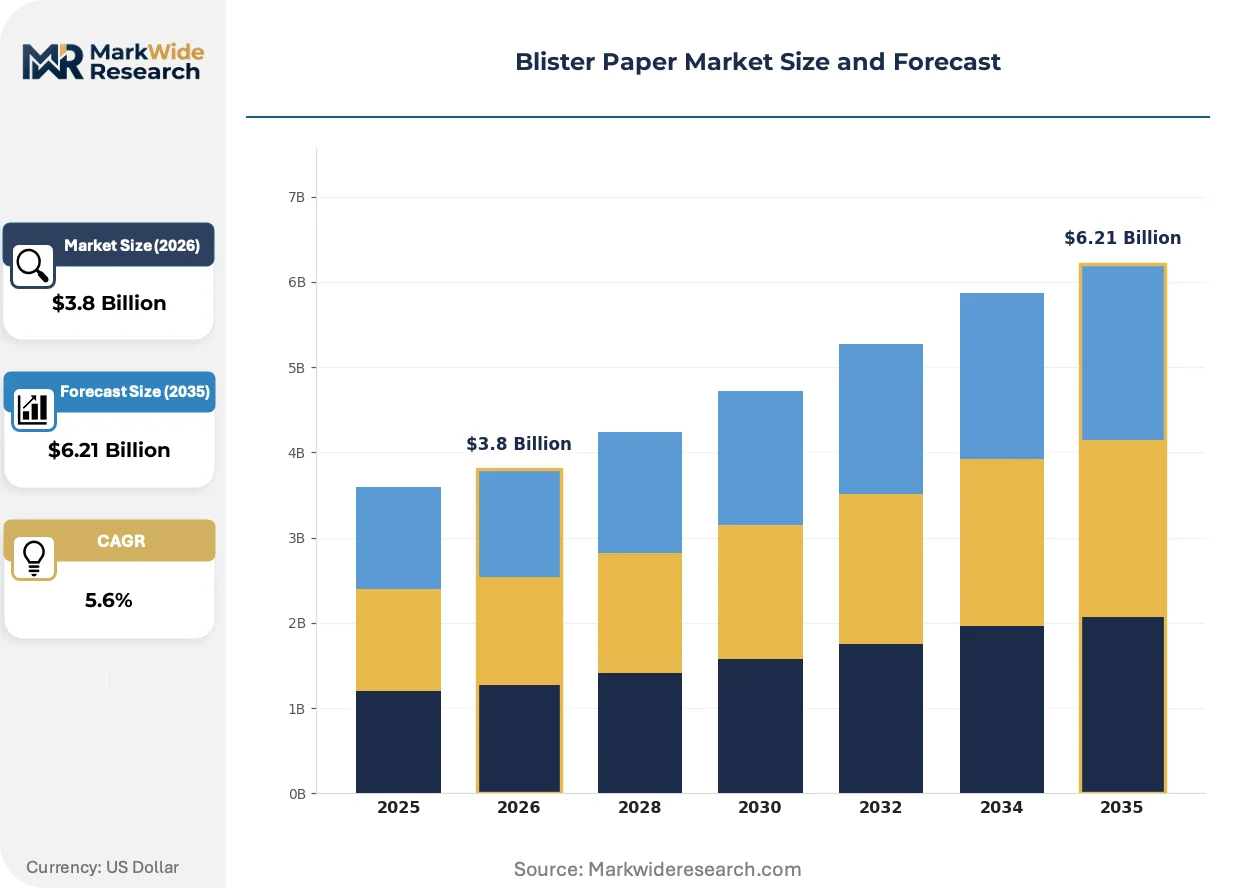
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, PET, PS, Paper Application: Pharmaceuticals, Food Packaging, Consumer Electronics, Personal Care End User: Manufacturers, Retailers, Distributors, Wholesalers Thickness: Thin, Medium, Heavy, Extra Heavy |
| Companies Covered | Huhtamaki Oyj, Ecobliss Packaging Group, Syntegon Technology GmbH, Van de Velde Packaging, Atlantic Corporation, Scafa Thermoforming GmbH, r-pac International, Romaco Group, Paperfoam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blister Paper Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are rewriting substrate specifications faster than equipment replacement cycles, compressing development timelines for compliant formulations.
High-barrier bio-based coatings derived from cellulose nanofibrils are rendering obsolete conventional polyethylene extrusion layers in premium pharmaceutical applications. German contract packagers at the Dusseldorf hub have adopted these substrates for 30% of new product introductions since 2023. The shift is compressing demand for fossil-derived barrier films while forcing coating specialists to scale aqueous deposition capacity.
REACH Annex XVII restrictions on phthalate plasticizers have eliminated vinyl-based heat-seal coatings from European pharmaceutical packaging specifications. Converters now specify aqueous acrylic or EVA dispersions that meet migration limits under EFSA food contact guidelines. Pediatric and geriatric tablet formats show fastest reformulation velocity due to heightened regulatory scrutiny of endocrine-disrupting compounds.
Direct purchasing relationships between Indian pharmaceutical exporters and Nordic fiber suppliers are disintermediating traditional distributor networks for qualified substrates. Mumbai-based formulation companies now specify basis weights and coating chemistries in original equipment tenders rather than accepting converter recommendations. This pattern concentrates volume with suppliers maintaining dual pharmacopeial dossiers for USP and EP compliance.
Blister Paper Market Segmentation
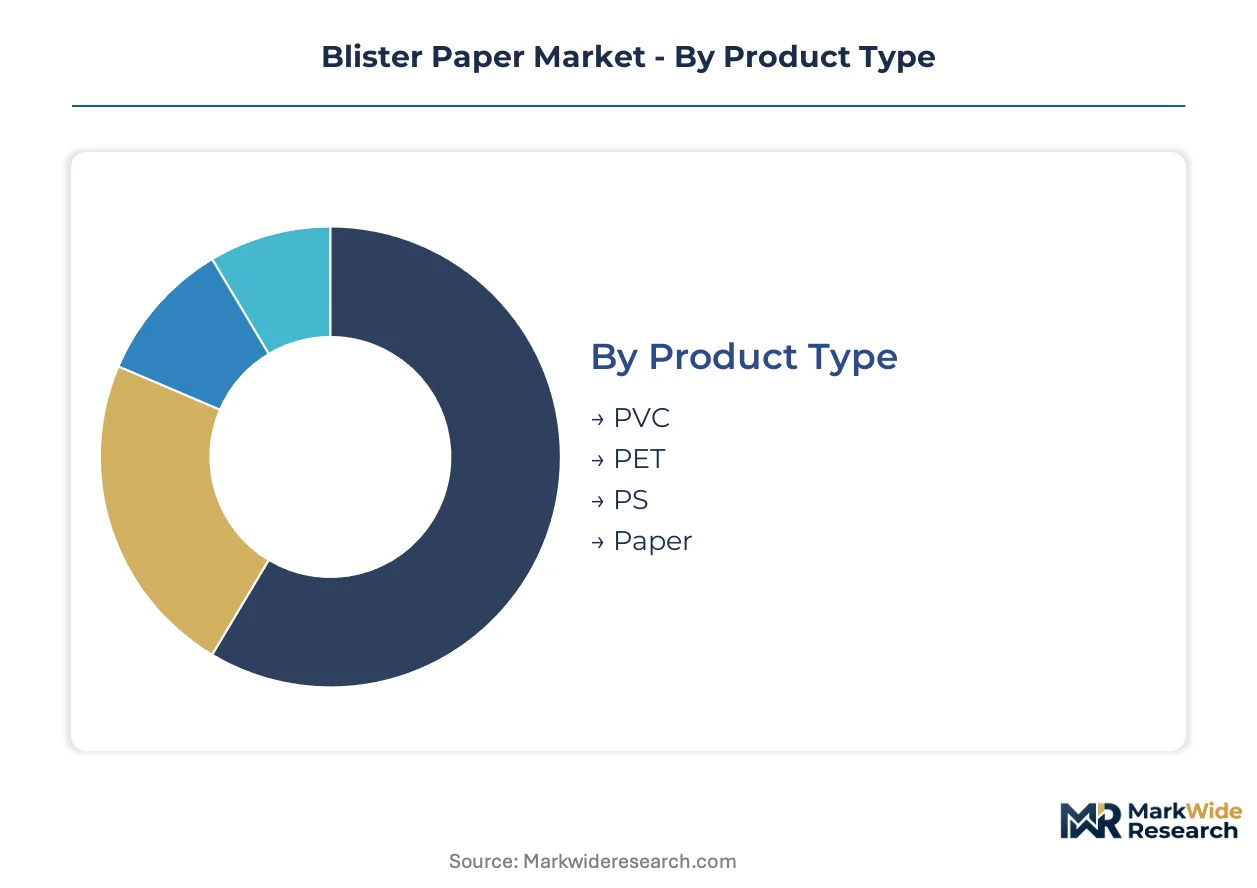
Blister paper segmentation reveals divergent specification requirements across pharmaceutical, food, and electronics end-uses. Substrate selection hinges on barrier performance thresholds, thermoforming compatibility, and regulatory compliance pathways that vary sharply by application.
Product Type:
Material composition determines thermoformability ranges, seal integrity against lidding films, and sustainability positioning under EU packaging directives.
- PVC:Polyvinyl chloride substrates deliver superior moisture barrier performance with water vapor transmission rates below 0.5 g/m²/day. Pharmaceutical manufacturers in Germany continue specifying PVC for hygroscopic drug formulations despite REACH pressure on chlorine-based chemistries.
- PET:Polyethylene terephthalate offers optical clarity and dimensional stability for high-visibility consumer electronics packaging. French and Italian retailers specify PET-blister hybrids for premium device visibility windows where fiber alternatives lack transparency.
- PS:Polystyrene serves cost-sensitive food and personal care applications with adequate formability at lower basis weights. Snack brands in Spain trial PS-laminated paper constructions for confectionery visibility packs.
- Paper:Fiber-based substrates incorporate aqueous heat-seal coatings and cellulose nanofibril barrier layers for pharmaceutical compliance. Nordic suppliers anchor capacity expansion around paper grades qualified under both USP and European Pharmacopoeia standards.
PVC holds installed capacity. Paper is rotating up the share rankings.
Application:
End-use specification intensity ranges from pharmacopeial-grade extractables testing to basic visual merchandising requirements.
- Pharmaceuticals:Unit-dose tablet and capsule packaging demands child-resistant opening features, traceability coding surfaces, and 24-month stability validation. EMA serialization mandates and FDA container closure guidance create dual compliance burdens for substrate suppliers.
- Food Packaging:Snack and confectionery visibility packs are expanding fastest as French and Italian brands replace single-use plastic windows with fiber-based alternatives. FSSAI alignment with EU food contact regulations opens export pathways for European-qualified converters.
- Consumer Electronics:Tamper-evident blister packs for accessories and small devices prioritize optical clarity and die-cutting precision. German electronics distributors specify medium-weight substrates with anti-static coatings.
- Personal Care:Cosmetic sampler and travel-size formats favor lightweight paper-only constructions with cold-seal adhesives for temperature-sensitive formulations. Dutch contract packagers specialize in these room-temperature sealing systems.
Pharmaceuticals command specification premiums. Food packaging is climbing the fastest.
End User:
Customer type shapes procurement scale, technical service requirements, and inventory positioning in the supply chain.
- Manufacturers:Pharmaceutical and food brand owners specify substrates directly in original equipment tenders, disintermediating traditional distributor networks. Mumbai-based formulation companies now mandate basis weights and coating chemistries.
- Retailers:Private-label food and personal care brands source through centralized packaging procurement functions with sustainability scorecards. German drugstore chains audit fiber content verification under EU Green Deal circularity targets.
- Distributors:Regional substrate wholesalers maintain qualified inventory for small-batch pharmaceutical converters. Inventory concentration in the Dusseldorf hub serves contract packaging networks spanning Germany and the Netherlands.
- Wholesalers:Bulk paper and film merchants supply non-pharmaceutical applications with lower specification thresholds. Price volatility in Northern European softwood fiber markets compresses their margin structures.
Manufacturers direct the largest volume flows. Retailers are gaining procurement influence.
Thickness:
Basis weight tiers align with cavity depth requirements, barrier performance needs, and equipment compatibility windows.
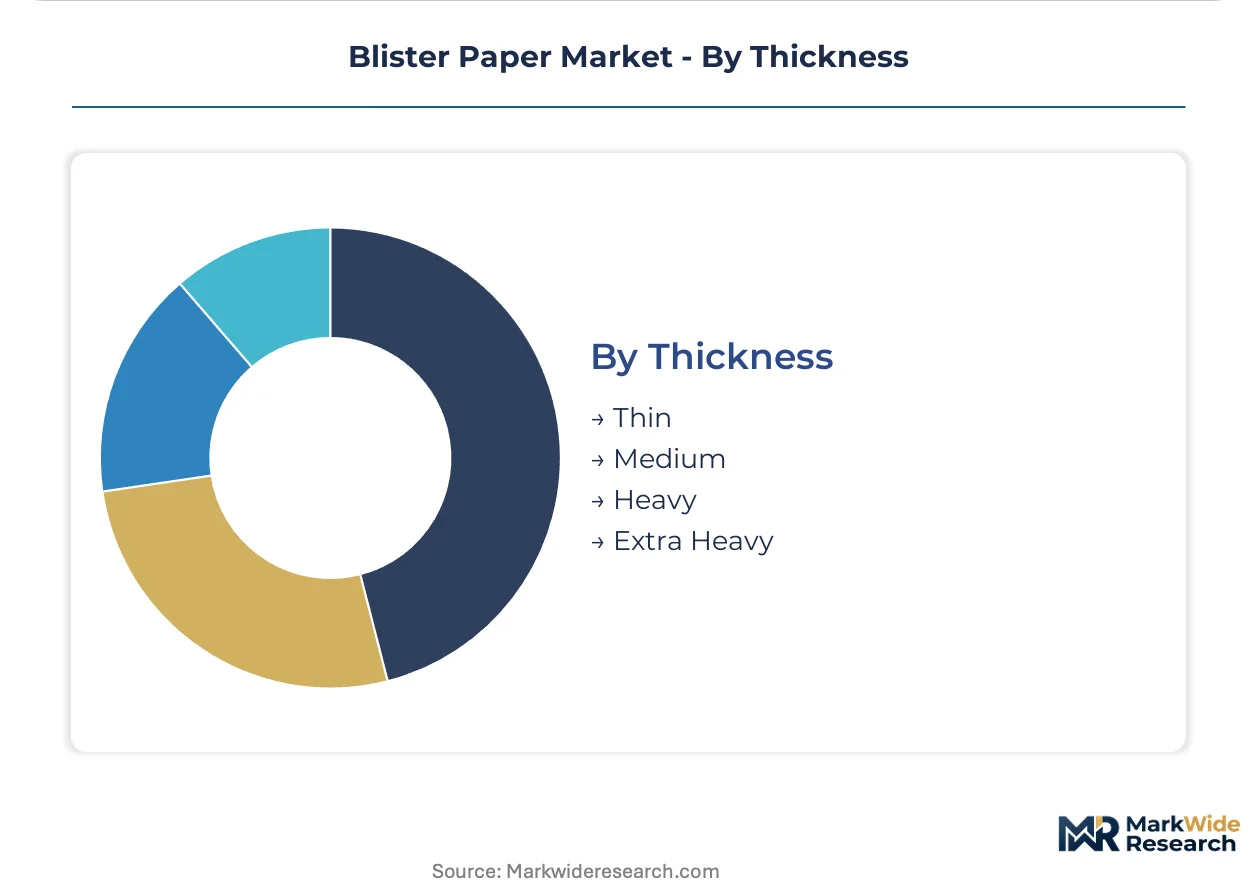
- Thin:Sub-200 gsm substrates serve shallow personal care samplers and lightweight confectionery formats. These grades run on legacy thermoforming lines with narrow parameter windows.
- Medium:200-300 gsm specifications dominate standard pharmaceutical tablets and consumer electronics accessories. Syntegon Technology GmbH equipment-linked material specifications center on this tier.
- Heavy:300-400 gsm constructions accommodate deep-draw cavities for medical devices and large food portions. German contract packagers have adopted these for 30% of new product introductions since heavy-grade cellulose nanofibril coatings reached commercial scale.
- Extra Heavy:Above-400 gsm specialty grades address structural rigidity requirements for premium electronics and diagnostic kits. Limited supplier base concentrates in Nordic integrated fiber operations.
Medium thickness holds equipment compatibility. Heavy grades are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German contract packaging clusters while Indian pharmaceutical exporters extract cost advantages through direct Nordic fiber sourcing. This asymmetry reshapes procurement geography for qualified substrates.
Germany
Contract packaging services cluster around pharmaceutical hubs in Dusseldorf and Munich, driving specification intensity for EMA-compliant blister paper. REACH Annex XVII restrictions on phthalate plasticizers eliminate vinyl-based coatings from domestic formulations. The Dusseldorf hub anchors integrated networks spanning the Netherlands, with 30% of new product introductions since 2023 adopting heavy-grade cellulose nanofibril constructions.
India
Mumbai-based formulation companies now mandate basis weights and coating chemistries in original equipment tenders rather than accepting converter recommendations. CDSCO alignment with ICH stability guidelines creates substrate approval pathways for European-qualified suppliers. Direct purchasing relationships with Nordic fiber suppliers disintermediate traditional distributor networks for qualified substrates.
United States
FDA unit-dose labeling requirements and container closure guidance shape blister paper specifications through traceability coding surfaces and child-resistant opening features. Pharmaceutical manufacturers face dual compliance burdens alongside European Pharmacopoeia standards for export formulations. The analysis notes regulatory divergence threatens to fragment substrate approval pathways between FDA and EP requirements.
France
Snack and confectionery brands trial fiber-based transparent windows as single-use plastic bans tighten under EU Green Deal circularity targets. Retail procurement functions apply sustainability scorecards that audit fiber content verification. Lyon-based food packagers specialize in visibility packaging formats that bridge premium positioning with regulatory compliance.
Netherlands
Dutch contract packagers specialize in cold-seal adhesive systems for temperature-sensitive biologics, leveraging pressure-sensitive natural rubber formulations. The country's logistics infrastructure supports just-in-time substrate delivery to German pharmaceutical networks. Rotterdam serves as a distribution node for qualified inventory serving small-batch converters across the Rhine-Ruhr corridor.
Blister Paper Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on substrate and coating technology. The market exhibits tiered concentration with equipment-linked specifications freezing out experimental fiber grades. Three archetypes dominate: integrated fiber-to-form converters, equipment-locked material suppliers, and cold-seal adhesive specialists. Competitive moves center on pharmacopeial dossier expansion and aqueous coating capacity scaling.
Among Nordic integrated operators, Huhtamaki Oyj anchors supply through captive fiber sourcing and thermoforming capabilities. Ecobliss Packaging Group occupies a position within sustainable cold-seal systems, while Syntegon Technology GmbH exemplifies equipment-linked specification power that forces substrate compliance across installed bases. These three represent the dominant competitive anchors shaping procurement relationships and technical standards.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Ecobliss Packaging Group |
| Syntegon Technology GmbH |
| Van de Velde Packaging |
| Atlantic Corporation |
| Scafa Thermoforming GmbH |
| r-pac International |
| Romaco Group |
| Paperfoam |
| Others |
Value Chain & Pricing Dynamics
Düsseldorf's contract packaging cluster concentrates heavy-grade cellulose nanofibril capacity, translating upstream fiber integration into pricing leverage over pharmaceutical converters locked into EMA compliance requirements. Northern European softwood fiber volatility feeds directly into converter margin compression, while equipment-linked specifications at Syntegon Technology GmbH freeze price competition within narrow substrate parameter windows.
Pricing Analysis
Customization-premium spreads separate aqueous-coated pharmaceutical grades from commodity paper-only formats for food visibility applications. Three-tier pricing structure across premium, standard, and economy levels reflects USP/EP dual pharmacopeial dossier costs, volume scale commitments, and after-sales technical service bundling. Pricing pressure stems from pulp cost volatility compressing margins on fixed-price pharmaceutical contracts. Small-batch pharmaceutical converters exhibit highest price sensitivity due to inventory carrying costs, while integrated Nordic fiber operators command lowest sensitivity through captive supply.
Supply Chain Analysis
Upstream Northern European softwood fiber draws from Swedish and Finnish integrated pulp operations, with German mechanical engineering anchoring thermoforming equipment fabrication. Coating chemistries rest on acrylic and EVA dispersion supply from Belgian and Dutch chemical specialists. Single-source vulnerability concentrates in Syntegon Technology GmbH's installed base specifications, which dictate substrate compliance across European pharmaceutical packaging lines. Distribution runs through Rotterdam's logistics node serving Rhine-Ruhr corridor contract packagers with just-in-time qualified inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: dual USP/EP pharmacopeial dossiers create switching costs that freeze out experimental fiber grades and protect incumbent qualification positions.
For Market Incumbents: Pre-empt coating chemistry consolidation by scaling aqueous dispersion capacity ahead of REACH Annex XVII expansion, while locking in long-term softwood fiber supply agreements to neutralize pulp price volatility threats from energy market turbulence. Backward integration into cellulose nanofibril production secures barrier performance advantages against hybrid paper-plastic substitutes. For New Entrants and Emerging Players: Build out cold-seal adhesive specialization for temperature-sensitive biologics, targeting Dutch contract packaging networks where pressure-sensitive natural rubber formulations remain underpenetrated against heat-seal dominance. Food visibility packaging for French and Italian snack brands offers the most penetrable entry vector, with sustainability scorecard alignment as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because pharmacopeial validation timelines and extractables study requirements create structural barriers that compound over decade horizons. Acquisition targets should screen for dual USP/EP dossier maintenance and aqueous coating capacity scale. The signal to watch is CDSCO alignment velocity with ICH guidelines, which would accelerate Indian pharmaceutical export demand and strain qualified substrate supply.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Dossier Expansion | Dual USP/EP compliance opens substrate approval pathways for Indian pharmaceutical exports under CDSCO guidelines. |
| Aqueous Coating Capacity Scaling | Water-based heat-seal dispersion investments eliminate solvent emissions while meeting EFSA migration limits. |
| Cold-Seal Adhesive Convergence | Pressure-sensitive natural rubber formulations enable room-temperature sealing for temperature-sensitive biologics. |
| Cellulose Nanofibril Barrier Integration | High-barrier bio-based coatings displace fossil-derived polyethylene extrusion layers in premium pharmaceutical applications. |
| Direct Nordic Fiber Sourcing | Mumbai-based formulation companies now mandate basis weights and coating chemistries, disintermediating distributor networks. |
Study Parameters
A spread of perspectives from pharmaceutical packaging engineers, contract manufacturing procurement leads, thermoforming equipment specialists, and regulatory affairs directors converged on the working assumptions. Primary fieldwork combined with secondary validation against EMA serialization mandate documentation, REACH Annex XVII restriction filings, FDA container closure guidance, and European Pharmacopoeia chapter revisions. Bottom-up substrate demand modeling and top-down pharmaceutical packaging value chain analysis were triangulated.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, application intensity, end-user procurement scale, and thickness-grade equipment compatibility. CAGRs were derived from installed base expansion rates, regulatory compliance upgrade cycles, and fiber-based substitution elasticity. Forecast inputs incorporated pulp cost volatility scenarios and pharmacopeial approval timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Nordic integrated fiber operators or accelerated CDSCO harmonization would shift outcomes. Cross-checking against EMA serialization implementation benchmarks and EU Green Deal circularity target enforcement is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Welded Blisters Market
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Blister Cards Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Blister Packs Market