
 Holographic Foils Market | 2026-2036
Holographic Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic Foils Market Analytics
Aftermarket service revenue for holographic die maintenance and pattern re-licensing is narrowing as OEMs pull authentication services in-house. Kurz Transfer Products sustains technology leadership through captive mastering facilities in Europe and Asia. API Group dominates security-sector contracting with government document programs across multiple continents. Univacco Foils Corporation leverages cold-stamping expertise to compete in flexible packaging conversions where speed matters.
Holographic foils are micro-embossed metallized films, typically 12-50 micron PET or BOPP substrates carrying surface-relief diffraction gratings that reconstruct three-dimensional imagery under coherent or white light illumination; manufacturers employ electron-beam lithography or holographic interferometry to create master shims, then electroform nickel copies for rotary embossing, with vacuum metallization applying aluminum or zirconium oxide reflective layers. Hot stamping foils retain the largest value share due to entrenched wine and cosmetics packaging workflows, while cold stamping foils are expanding fastest as narrow-web flexographic presses eliminate heat dwell time and reduce substrate distortion. Security applications command premium pricing through serialized track-and-trace integration, whereas decorative packaging segments compete on optical breadth and color-shifting sophistication.
REACH compliance in Europe restricts certain solvent-based release coatings and mandates substance-of-very-high-concern disclosure throughout the metallization supply chain, while FDA regulations in the United States govern indirect food-contact layers for holographic labels on consumable goods. China's GB standards for packaging materials and the EU Green Deal's recyclability targets are forcing substrate redesign toward mono-material PET constructions compatible with existing recycling streams. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in water-based coating lines or partner with regional recyclers to maintain market access across jurisdictions.
Market Dynamics
Anti-counterfeiting mandates in pharmaceutical packaging are compressing adoption timelines while substrate recyclability requirements under the EU Green Deal force metallization chemistry redesigns.
Growth Catalysts
- REACH substance disclosure mandates:ECHA's SVHC tracking requirements across the metallization supply chain are accelerating transparency investments that favor established holographic foil producers with compliant coating lines.
- Wine and cosmetics packaging workflows:Premium brand owners in Germany's Stuttgart-Munich corridor are specifying serialized holographic elements for authentication at point-of-sale terminals.
- Cold stamping speed advantages:Narrow-web flexographic presses eliminating heat dwell time are displacing conventional hot stamping in flexible packaging conversions where substrate distortion tolerance is minimal.
Market Restraints
- Aluminum and zirconium oxide price volatility:Vacuum metallization feedstock costs fluctuate with energy-intensive smelter output, compressing margin visibility for mid-tier converters.
- Master shim supply concentration:Electron-beam lithography and holographic interferometry expertise clusters in Western Europe and select East Asian facilities, creating single-source vulnerability for complex security patterns.
- Mono-material PET substrate transition costs:Redesigning release coatings and adhesive layers for existing recycling streams demands capital outlay without immediate volume recovery.
Strategic Opportunities
- India's pharmaceutical export packaging:CDSCO track-and-trace requirements for active pharmaceutical ingredients create demand for serialized holographic verification layers on blister foils and cartons.
- Digital watermark convergence:Machine-readable holographic structures integrating with blockchain verification protocols are opening authentication-as-a-service revenue models for brand protection agencies.
- Extended producer responsibility schemes:France's Citeo and Germany's Der Grüne Punkt are creating preferential access for foil suppliers with verified closed-loop recycling partnerships.
Industry Challenges
- Electron-beam lithography technician scarcity:Master origination facilities report 18-month training pipelines for operators capable of sub-micron grating precision, constraining pattern refresh velocity.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact approval and EFSA compliance for the same metallized layer structure extends product launch cycles by 14-22 months.
- Legacy hot stamping equipment retrofit complexity:Converting installed base presses for cold stamping compatibility requires mechanical modifications that disrupt just-in-time packaging contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holographic Foils Market |
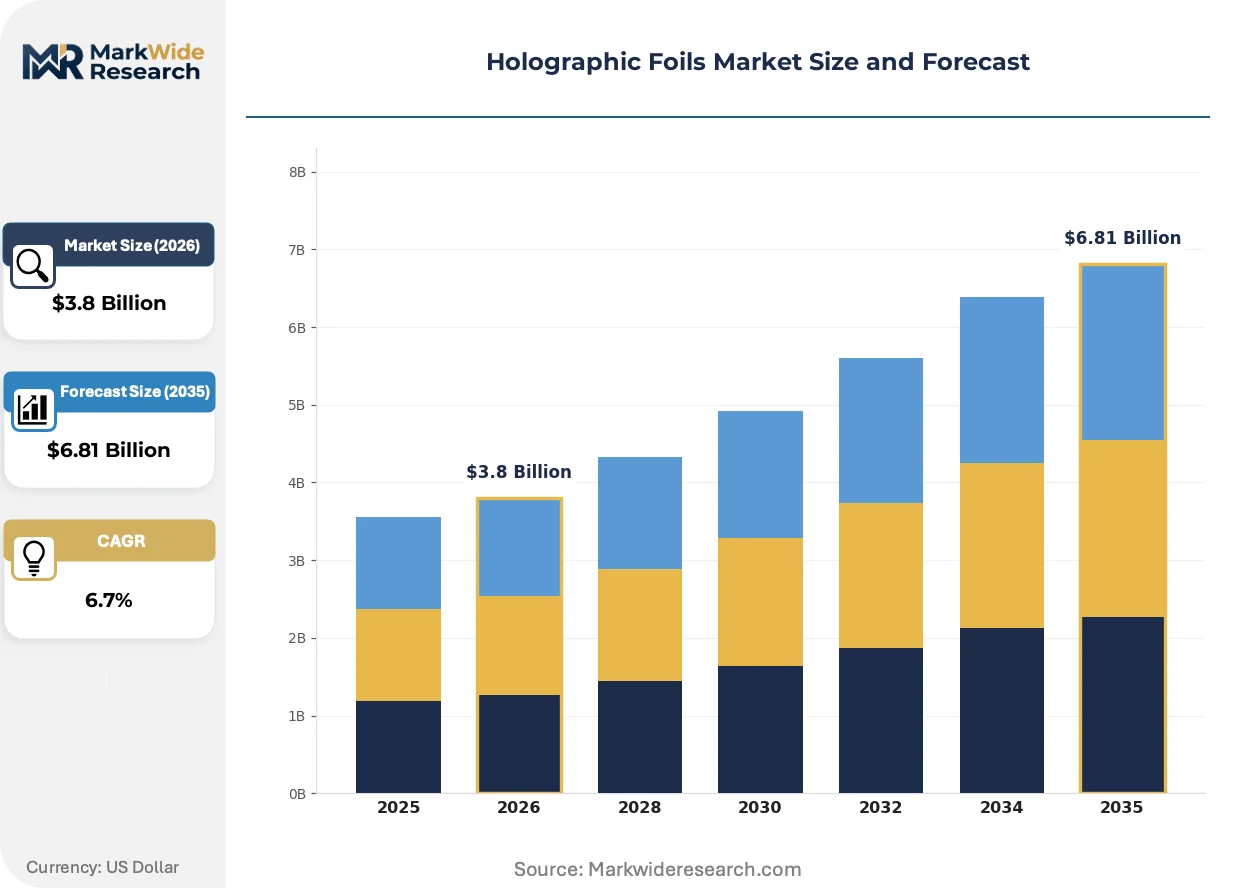
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Stamping Foils, Cold Stamping Foils, Transfer Foils, Overlay Foils Material: PET, PVC, PVC/PE Blends, BOPP End User: Packaging, Printed Electronics, Graphics, Security Application: Labeling, Branding, Decorative Packaging, Anti-Counterfeiting |
| Companies Covered | Kurz Transfer Products, API Group, Univacco Foils Corporation, K Laser Technology Inc., Light Logics Holography and Optics, Uflex Limited, Cosmo Films Limited, Crown Roll Leaf, Inc., ITW Foils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic Foils Market Evolving Landscape
Nano-embossing precision and digital authentication integration are redefining competitive differentiation beyond optical aesthetics toward functional verification ecosystems.
Surface-relief diffraction gratings with sub-wavelength feature sizes are hybridizing with printed electronics to create dual-mode optical-electrical authentication tags. Pharmaceutical contract packagers in Switzerland and South Korea are piloting these structures for temperature-integrity verification. The convergence is compressing the addressable market for standalone decorative foils lacking embedded functionality.
China's GB standards for packaging materials are tightening heavy-metal thresholds in metallized layers, forcing aluminum deposition process modifications. Domestic converters near Shanghai and Shenzhen are investing in electron-beam evaporation systems to maintain export eligibility. The regulatory pressure is accelerating supplier consolidation toward vertically integrated producers with in-house vacuum coating capabilities.
Brand owners are unbundling holographic authentication from traditional label procurement, contracting directly with pattern licensees for serialized track-and-trace integration. This disintermediation is compressing converter margins while shifting value capture toward mastering houses with proprietary image origination libraries. The behavioral shift is most pronounced in French and Italian luxury cosmetics verticals where counterfeiting losses exceed packaging material costs by an order of magnitude.
Holographic Foils Market Segmentation
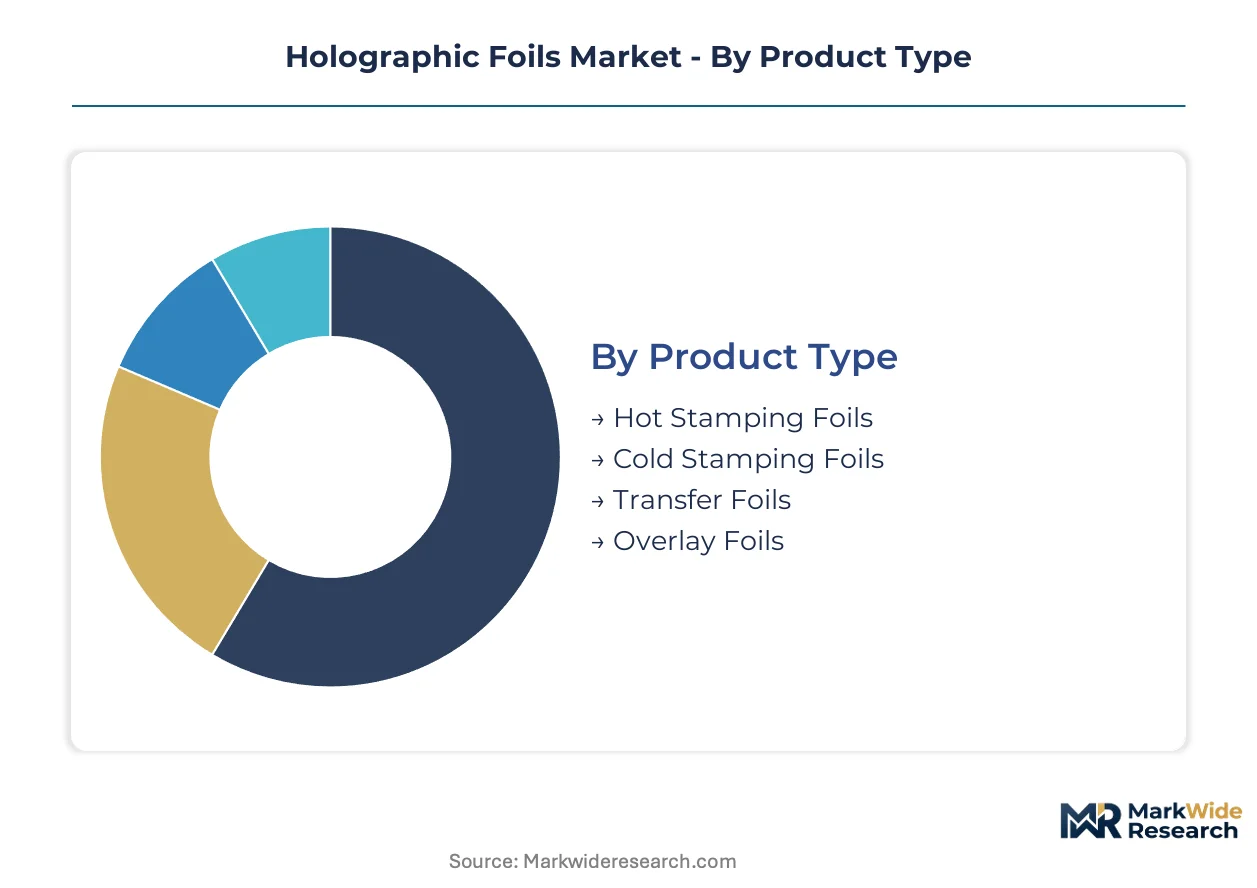
Holographic foil segmentation reveals how substrate chemistry and stamping temperature dictate equipment compatibility and end-use access. Product type and material choices cascade through regulatory compliance requirements, particularly for pharmaceutical and food-contact applications.
Product Type:
Mature hot stamping workflows dominate established packaging verticals while cold stamping gains traction in speed-sensitive flexible packaging conversions.
- Hot Stamping Foils:These foils require thermal activation through heated dies to transfer metallized layers onto substrates, maintaining entrenched positions in wine and cosmetics packaging workflows. German premium brand owners around Stuttgart and Munich specify serialized holographic elements for point-of-sale authentication, sustaining demand despite longer cycle times.
- Cold Stamping Foils:Pressure-activated transfer eliminates heat dwell time, enabling narrow-web flexographic presses to process temperature-sensitive films without substrate distortion. Swiss pharmaceutical contract packagers are piloting these structures for temperature-integrity verification alongside printed electronics integration.
- Transfer Foils:Carrier-based systems enable precise pattern placement on irregular surfaces common in luxury goods packaging.
- Overlay Foils:Laminate constructions protect underlying holographic structures from abrasion in high-wear security document applications.
Hot stamping foils handle the majority of throughput; cold stamping foils are gaining share fastest in flexible packaging conversions.
Material:
Substrate selection hinges on recyclability mandates and metallization chemistry compatibility across regional regulatory frameworks.
- PET:Mono-material polyethylene terephthalate constructions are redesigning release coatings and adhesive layers to meet EU Green Deal recyclability targets, with domestic converters near Shanghai and Shenzhen investing in electron-beam evaporation systems to maintain export eligibility under tightening GB standards.
- BOPP:Biaxially oriented polypropylene offers superior moisture barrier properties for flexible food packaging, though metallization adhesion requires modified primer systems to satisfy FDA indirect food-contact governance.
- PVC:Rigid vinyl substrates persist in security card overlays despite REACH substance disclosure mandates complicating plasticizer sourcing.
- PVC/PE Blends:Hybrid constructions balance processability with cost positioning in emerging market decorative applications.
PET commands the dominant material position; BOPP shows the steepest expansion trajectory in food-contact flexible packaging.
End User:
Customer concentration varies sharply between authentication-premium security verticals and volume-driven decorative segments.
- Security:Government document programs and pharmaceutical track-and-trace systems command premium pricing through serialized holographic integration, with API Group dominating multi-continent contracting and brand owners unbundling authentication from traditional label procurement.
- Packaging:Wine, cosmetics, and consumer goods applications compete on optical breadth and color-shifting sophistication, with aftermarket service revenue narrowing as OEMs pull authentication services in-house.
- Printed Electronics:Hybrid optical-electrical structures are piloting in South Korean pharmaceutical temperature-integrity verification.
- Graphics:Point-of-sale and promotional materials prioritize visual impact over embedded functionality.
Security commands the highest margin position; packaging delivers the largest absolute volume.
Application:
Functional differentiation separates authentication-driven specifications from aesthetic-driven procurement.
- Anti-Counterfeiting:Machine-readable holographic structures integrating with blockchain verification protocols are opening authentication-as-a-service revenue models, with French and Italian luxury cosmetics verticals driving disintermediation as counterfeiting losses exceed packaging material costs.
- Labeling:Serialized track-and-trace integration is compressing converter margins while shifting value toward mastering houses with proprietary image origination libraries.
- Branding:Premium positioning relies on color-shifting sophistication and optical depth in Germany's Stuttgart-Munich corridor.
- Decorative Packaging:Competing primarily on visual differentiation without embedded verification functionality.
Anti-counterfeiting carries the steepest premium; decorative packaging serves the broadest customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes holographic foils primarily for pharmaceutical authentication and luxury cosmetics packaging, whereas China deploys them across export-oriented consumer electronics and flexible food packaging at substantially higher volumes with lower per-unit value capture.
Germany
Stuttgart and Munich host dense clusters of premium brand owners specifying serialized holographic elements for point-of-sale verification. REACH substance disclosure mandates through ECHA accelerate transparency investments among metallization suppliers. Baden-Württemberg converters are retrofitting coating lines to meet EU Green Deal mono-material PET recyclability targets.
China
Domestic pharmaceutical exporters and consumer electronics manufacturers drive foil demand for anti-counterfeiting layers. GB standards for packaging materials tighten heavy-metal thresholds in metallized layers, forcing process modifications. Converters near Shanghai and Shenzhen invest in electron-beam evaporation systems to maintain export eligibility under evolving regulatory pressure.
United States
FDA indirect food-contact governance shapes metallized layer specifications for holographic labels on consumable goods. Pharmaceutical track-and-trace requirements under DSCSA sustain security-grade foil procurement. Packaging converters in the Northeast Corridor balance multi-jurisdiction certification timelines spanning FDA and EFSA compliance.
India
CDSCO track-and-trace mandates for active pharmaceutical ingredients create demand for serialized holographic verification on blister foils and cartons. Maharashtra and Gujarat pharmaceutical exporters upgrade packaging lines to meet export market authentication standards. Domestic converters partner with European mastering houses for complex security pattern licensing.
Switzerland
Swissmedic-regulated pharmaceutical contract packagers pilot hybrid optical-electrical authentication structures for temperature-integrity verification. Precision manufacturing traditions support high-value security document applications. Basel-area converters specialize in serialized track-and-trace integration for luxury watch authentication.
Holographic Foils Market Competitive Landscape
Capability concentration sits with mastering houses possessing proprietary image origination libraries; scale advantage sits with metallized film converters serving high-volume flexible packaging. The vendor base stratifies across three tiers: integrated producers with captive electron-beam lithography, regional converters licensing patterns from independent mastering facilities, and commodity metallizers competing on coating throughput. Dominant competitive moves include backward integration into vacuum coating equipment and strategic partnerships with brand protection agencies for authentication-as-a-service revenue models.
Within the integrated mastering tier, Kurz Transfer Products and API Group exemplify contrasting geographic anchoring strategies. Kurz Transfer Products represents European-based producers sustaining technology leadership through captive facilities across multiple continents. API Group occupies a position exemplifying security-sector specialists dominating government document programs through multi-continent contracting presence. Univacco Foils Corporation sits within the cold-stamping specialization vector, competing in flexible packaging conversions where press speed and substrate integrity determine procurement decisions.
| Leading Market Players |
|---|
| Kurz Transfer Products |
| API Group |
| Univacco Foils Corporation |
| K Laser Technology Inc. |
| Light Logics Holography and Optics |
| Uflex Limited |
| Cosmo Films Limited |
| Crown Roll Leaf, Inc. |
| ITW Foils |
| Others |
Value Network & Pricing Analysis
Master shim supply concentration in Western Europe and select East Asian facilities creates single-source vulnerability that compresses margin visibility for mid-tier converters while stratifying pricing tiers around pattern complexity and origination exclusivity. This dependency structure forces buyers into long-term licensing arrangements with captive mastering houses or risk pattern obsolescence.
Pricing Analysis
Long-term offtake contracts dominate security-grade holographic foil procurement, with government document programs and pharmaceutical track-and-trace systems locking in multi-year volumes through API Group and Kurz Transfer Products. Three-tier pricing structure across premium, standard, and economy levels separates serialized authentication foils with blockchain integration from decorative packaging grades lacking embedded functionality. Cost compression in decorative segments is intensifying because brand owners unbundle authentication from traditional label procurement, shifting value toward mastering houses. Pharmaceutical contract packagers exhibit the least price sensitivity due to regulatory compliance mandates, while flexible packaging converters face acute margin pressure from cold-stamping speed demands.
Supply Chain Analysis
Export-control regimes limiting electron-beam lithography equipment flows constrain master origination capacity expansion, tethering complex security pattern production to facilities in Germany, Switzerland, and Japan. Vacuum metallization draws from aluminum and zirconium oxide feedstocks whose energy-intensive smelter output fluctuates with regional power costs. Single-source vulnerability concentrates in nickel electroforming copies for rotary embossing, where 18-month technician training pipelines constrain pattern refresh velocity. Distribution runs through regional converters licensing from independent mastering facilities, with vertically integrated producers capturing premium security-sector contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Holographic foils sit at an early-cycle expansion phase as anti-counterfeiting mandates in pharmaceutical packaging compress adoption timelines and substrate recyclability redesigns open technology substitution windows.
For Market Incumbents: Insulate mastering capabilities through captive electron-beam lithography facilities and pattern re-licensing revenue streams against the threat of digital watermark convergence displacing standalone optical authentication. Prioritize backward integration into vacuum coating equipment to control metallization chemistry compliance across REACH and FDA jurisdictions. For New Entrants and Emerging Players: India's pharmaceutical export packaging underpenetration by serialized holographic verification layers offers white-space access, particularly for blister foil and carton applications under CDSCO track-and-trace mandates. Target Maharashtra and Gujarat pharmaceutical exporters upgrading packaging lines for export market authentication standards, partnering with European mastering houses for complex security pattern licensing rather than competing on origination infrastructure. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors vertically integrated producers with captive mastering and vacuum metallization capabilities over pure-play converters. Long-term viability across the analysis window hinges on authentication-as-a-service revenue models integrating blockchain verification protocols. Watch for electron-beam lithography technician pipeline expansion as an inflection indicator for pattern refresh velocity and competitive differentiation sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Coating | Captive metallization control secures REACH and FDA compliance without supplier dependency. |
| Authentication-as-a-Service Partnership | Blockchain verification integration with brand protection agencies creates recurring revenue streams. |
| Cold Stamping Speed Specialization | Narrow-web flexographic press compatibility captures flexible packaging volume from hot stamping displacement. |
| Mono-Material PET Substrate Transition | EU Green Deal recyclability alignment maintains market access across extended producer responsibility schemes. |
| Mastering Facility Geographic Expansion | Regional electron-beam lithography capacity reduces single-source vulnerability and pattern licensing costs. |
Research Methodology
Initial hypotheses were tested against primary input from holographic mastering technicians, pharmaceutical packaging procurement managers, flexographic press operators, and brand protection agency technical directors and refined through secondary validation against ECHA SVHC disclosure databases, FDA food-contact guidance documents, EU Green Deal recyclability target specifications, and customs trade flow records for metallized film imports. Bottom-up demand modeling across end-use segments triangulated with top-down supply-side capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning hot versus cold stamping temperature compatibility, PET versus BOPP substrate chemistry, and security versus decorative end-use authentication requirements. CAGRs were derived from installed base press capacity expansion, regulatory mandate adoption curves, and brand owner specification trend analysis. Forecast inputs incorporated electron-beam lithography technician pipeline constraints and mono-material PET transition capital outlay recovery timelines.
Practitioners should monitor aluminum and zirconium oxide smelter energy cost volatility, REACH substance disclosure list expansions, and CDSCO track-and-trace mandate enforcement intensity for early signals of forecast revision triggers. Forecasts reflect assumptions around pattern licensing fee structures and cold stamping press retrofit adoption rates. Material shifts in EU Green Deal recyclability timeline acceleration or electron-beam lithography equipment export-control tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Europe Luxury Packaging Market