
 Spain Plastic Bottles Market | 2026-2036
Spain Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Plastic Bottles Market Insights
Personal care applications is broadening as Spanish cosmetics houses shift from glass to premium PET and HDPE bottles. Amcor Group GmbH leverages its European film and bottle platform to supply lightweight formats for sunscreen and shampoo lines. Berry Global Inc. anchors production through its Iberian operations, sustaining capacity for household cleaner and beverage clients. Alcion Packaging Solutions SL specializes in small-run decorative bottles, competing on design flexibility for regional beauty brands.
Spain plastic bottles are hollow containers typically blow-molded from thermoplastic resins, with PET grades offering clarity and barrier performance down to 0.3mm wall thickness for carbonated beverages. These vessels store, transport, and dispense liquid and semi-solid products across retail and institutional channels. Polyethylene Terephthalate leads material demand due to its recyclability and established collection infrastructure, while High-Density Polyethylene retains strength in industrial and household cleaner segments where chemical resistance matters. Closure type selection follows application requirements, with flip-tops gaining share in personal care and on-the-go beverage formats.
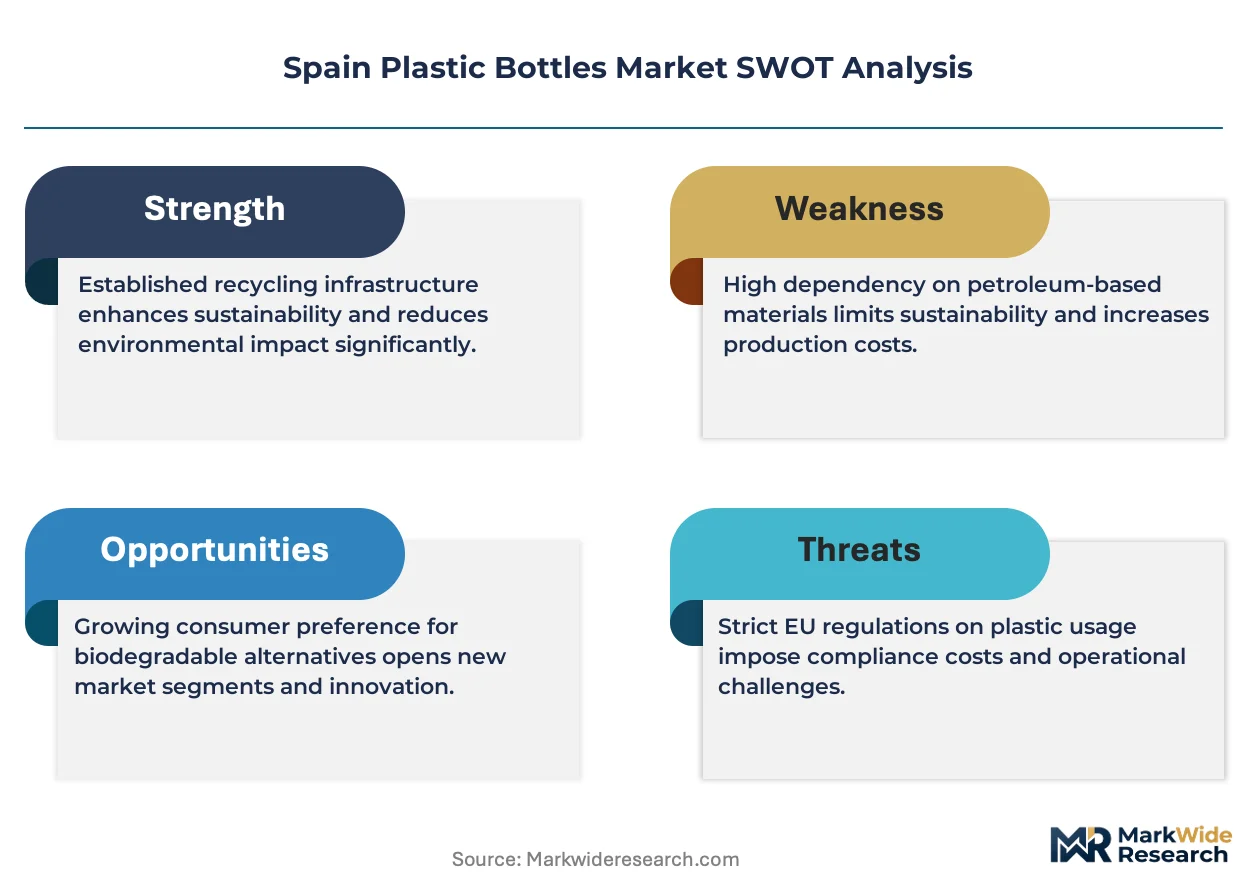
Spain's packaging sector operates under national transpositions of EU Packaging and Packaging Waste Directive obligations, with extended producer responsibility schemes administered at regional level. The EU Green Deal and Spanish national circular economy plans mandate minimum recycled content thresholds, forcing converters to certify post-consumer feedstock streams. Stakeholders must monitor enforcement timelines and recyclate certification costs to preserve margin structures.
Market Dynamics
EU Green Deal mandates on recycled content thresholds are compressing converter margins while forcing rapid reconfiguration of Spain's PET feedstock supply chains around certified post-consumer streams.
Growth Catalysts
- EU Packaging and Packaging Waste Directive transposition:Spain's regional extended producer responsibility schemes create compliance-driven demand for bottles with verified recyclate content. Municipal collection infrastructure expansion in Catalonia and Madrid improves feedstock availability for converters.
- Lightweight PET technology diffusion:Downgaugeing to 0.3mm wall thickness reduces resin consumption per unit while maintaining carbonated beverage barrier performance. Bottling lines across Barcelona-Tarragona corridor retrofit for thinner preforms.
- Personal care format migration:Spanish cosmetics houses accelerate glass-to-plastic conversion for sunscreen and shampoo lines. Premium decorative finishes on PET and HDPE bottles capture shelf differentiation without weight penalties.
Market Restraints
- rPET price volatility:Post-consumer flake supply tightens during summer tourism peaks when bottle collection diverts to export markets. Spanish converters face input cost spikes that virgin PET pricing does not mirror.
- Single-supplier dependency in catalysis:Antimony-based catalyst systems for PET polymerization concentrate with German and Dutch specialty chemical producers. Disruption risk elevates inventory carrying costs for Iberian resin compounders.
- Glass persistence in premium spirits:Heritage brand positioning and consumer taste perception sustain bottle demand for aged wine and spirits categories. Substitution ceiling limits plastic penetration in high-margin alcoholic segments.
Strategic Opportunities
- Andalusia agricultural chemical packaging:Olive oil and pesticide bottlers in Jaén-Seville axis underutilize HDPE formats with barrier coextrusion. Regional cooperatives seek domestic suppliers for 5-20 liter containers.
- EU Green Deal bonus mechanism:Proposed recycled content credits for packaging exceeding minimum thresholds would reward early compliance investments. Spanish converters certifying 30%+ rPET access preferential public procurement channels.
- Digital watermark traceability:HolyGrail 2.0 sorting technology convergence with blockchain verification enables bottle-level provenance claims. Pilot deployments in Valencia sorting facilities demonstrate commercial scalability.
Industry Challenges
- Polymer chemist scarcity:Spain's technical universities graduate fewer PET rheology specialists than converter hiring plans require. Compounding knowledge gaps slow rPET viscosity stabilization for high-speed blow molding.
- Recyclate certification lag:EN 15343 traceability audits backlog at Spanish accreditation bodies extends 14-18 weeks. Converter working capital ties up in uncertified inventory awaiting compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Plastic Bottles Market |
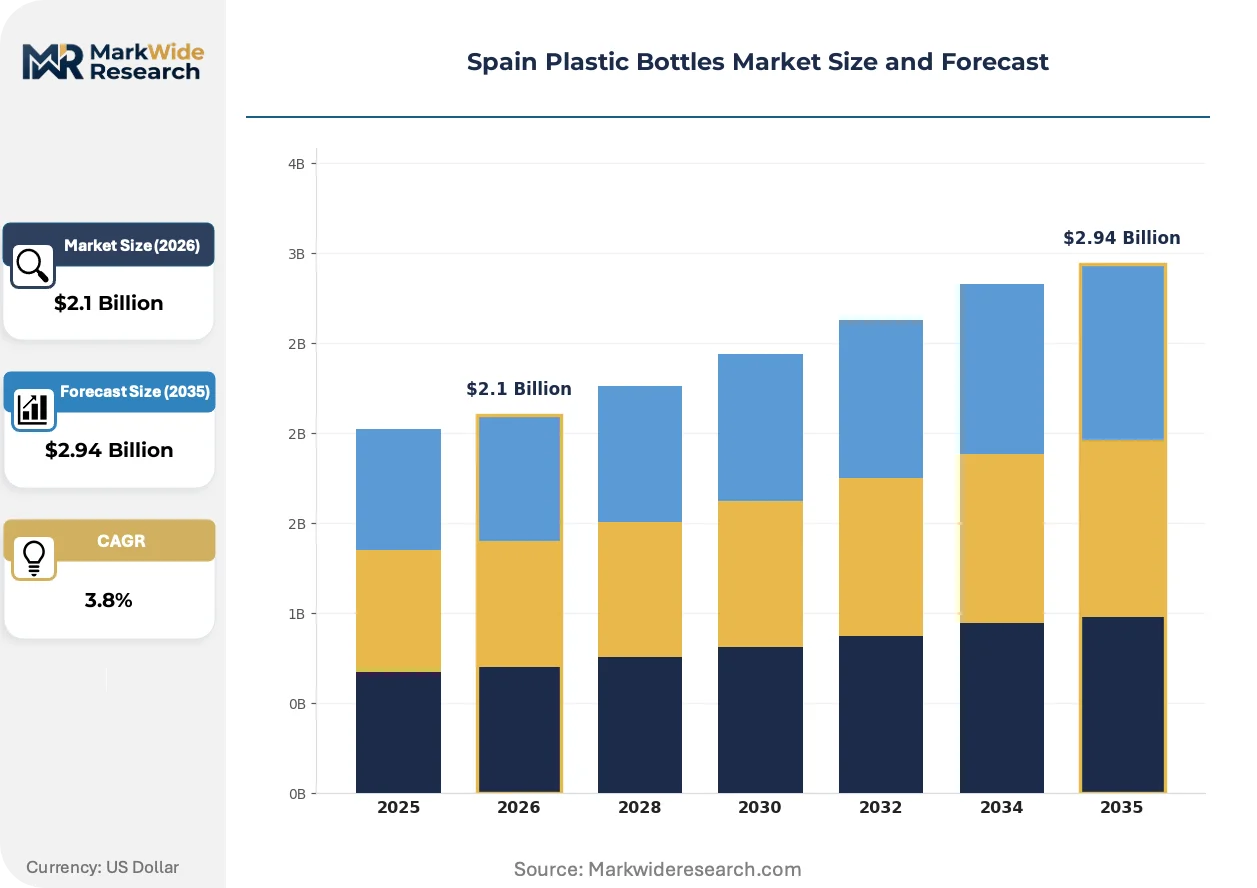
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Polystyrene Application: Consumer Beverages, Personal Care Products, Household Cleaners, Pharmaceuticals Closure Type: Screw Caps, Snap Caps, Flip-tops, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., Alpla Group, Gerresheimer AG, Alcion Packaging Solutions SL, Berlin Packaging, Urola Packaging, Caiba Packaging, Frapak Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Plastic Bottles Market Trends and Innovations
Blow molding equipment and resin formulation advances are compressing cycle times while regulatory pressure on carbon intensity forces parallel investment in electrified production and renewable power purchase agreements.
Mono-material PET bottle designs with integrated label compatibility are consolidating technical specifications across Spanish converter operations. Beverage brands in the Barcelona corridor specify these formats to satisfy EU Green Deal recyclability targets. Equipment retrofits at existing plants compress capital deployment timelines versus greenfield capacity.
Spain's national circular economy plan transposes EU Green Deal mandates into binding recycled content thresholds with phased enforcement from 2025. Converters must certify post-consumer feedstock streams through accredited bodies or forfeit access to extended producer responsibility fee discounts. Personal care and household cleaner segments face earlier compliance deadlines than beverage applications.
Buyer consolidation among Spanish retail private-label bottlers concentrates procurement leverage with three national distributors. Regional beauty brands respond through cooperative purchasing pools that aggregate small-run decorative bottle orders. Valencia and Alicante cosmetics clusters demonstrate this aggregation model most visibly.
Spain Plastic Bottles Market Segmentation
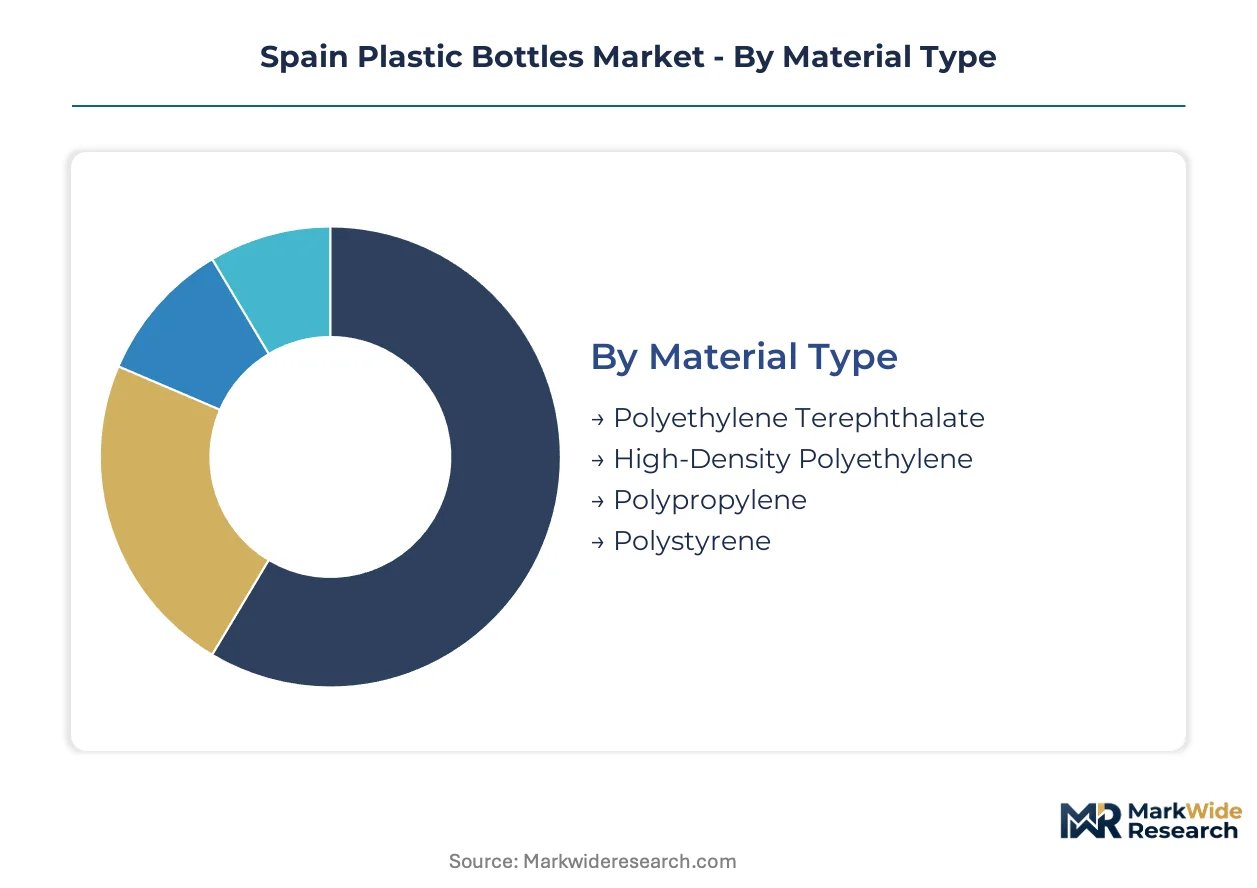
Material selection and closure engineering determine recyclability compliance and line speed economics for Spanish converters navigating EU Green Deal mandates. Application mix shifts reflect regional manufacturing strengths in Catalonia's beverage corridor and Valencia's cosmetics clusters.
Material Type:
Upgrade cycles in blow-molding equipment favor resins with established recycling infrastructure and viscosity stability for high-speed production.
- Polyethylene Terephthalate:Dominant material for carbonated beverages and personal care, offering optical clarity down to 0.3mm wall thickness. Barcelona-Tarragona bottling lines specify PET for its compatibility with HolyGrail 2.0 digital watermark sorting systems.
- High-Density Polyethylene:Preferred for household cleaners and agricultural chemicals requiring chemical resistance. Jaén-Seville olive oil cooperatives source HDPE formats for 5-20 liter barrier coextrusion containers.
- Polypropylene:Deployed in hot-fill applications and pharmaceutical bottles where sterilization tolerance matters. Valencia medical packaging specialists specify PP for vial and dropper formats.
- Polystyrene:Retains niche use in crystal-clear cosmetic jars and diagnostic kit packaging. Limited adoption due to EU recyclability penalties and rPS feedstock scarcity.
Volume placements concentrate in Polyethylene Terephthalate; the faster expansion belongs to High-Density Polyethylene.
Application:
Customer procurement patterns split between high-volume beverage contracts and fragmented beauty brand orders requiring design flexibility.
- Consumer Beverages:Carbonated soft drinks, water, and juice bottlers drive PET demand through the Barcelona-Catalonia corridor. Downgaugeing to lightweight preforms reduces resin consumption per unit while maintaining CO2 barrier performance.
- Personal Care Products:Sunscreen and shampoo lines accelerate glass-to-plastic conversion. Spanish cosmetics houses specify premium decorative finishes on PET and HDPE bottles for shelf differentiation.
- Household Cleaners:Bleach and detergent bottlers favor HDPE for chemical resistance. Extended producer responsibility schemes mandate earlier recycled content compliance for this segment than beverages.
- Pharmaceuticals:Prescription bottles and OTC packaging require child-resistant closure compatibility. Madrid and Valencia pharmaceutical clusters drive demand for barrier-grade PET and PP formats.
Procurement scale peaks with Consumer Beverages; Personal Care Products climb fastest on premium format migration.
Closure Type:
Line retrofit investments favor closure systems that maintain seal integrity across thinner wall specifications and faster cycle speeds.
- Screw Caps:Standard for beverages and pharmaceuticals requiring resealability. Thread specification standardization reduces changeover downtime on Barcelona corridor bottling lines.
- Snap Caps:Common in household cleaners where one-handed dispensing matters. HDPE compatibility dominates this segment.
- Flip-tops:Gaining share in personal care and on-the-go beverage formats. Valencia cosmetics brands specify hinge durability for travel-size shampoo and sunscreen bottles.
- Pouches:Flexible alternatives for refill and sample formats. Limited rigid bottle substitution due to EU Green Deal recyclability scoring disadvantages.
Equipment standardization favors Screw Caps; Flip-tops capture the steepest share gains.
Distribution Channel:
Channel selection determines lot size economics and inventory velocity for converters balancing line efficiency against customization demands.
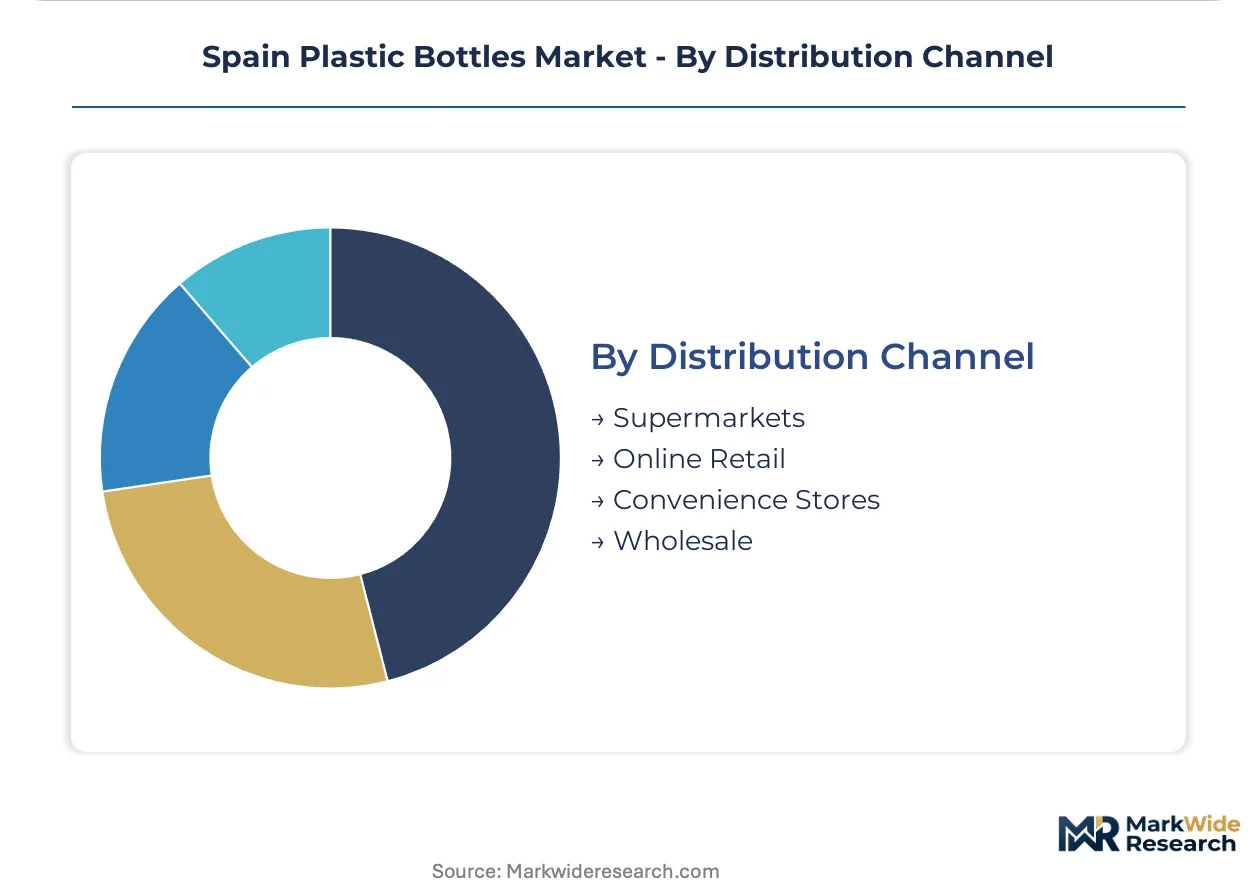
- Supermarkets:National retail chains consolidate procurement through three dominant distributors. Private-label bottlers in the Barcelona corridor serve this channel with mono-material PET specifications.
- Online Retail:E-commerce fulfillment requires damage-resistant lightweight formats. Regional beauty brands aggregate small-run orders through cooperative purchasing pools for this channel.
- Convenience Stores:Single-serve and impulse formats dominate. Flip-top closures and slim neck profiles optimize shelf space efficiency.
- Wholesale:Institutional and foodservice buyers purchase larger formats. Agricultural chemical packaging in Andalusia routes primarily through this channel.
Order concentration sits with Supermarkets; Online Retail expands most quickly on aggregation model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish production capacity concentrates in Catalonia while consumption spreads across autonomous communities with distinct sectoral demands. The Barcelona-Tarragona corridor exports lightweight formats throughout Southern Europe. Regional compliance timelines for EU Green Deal mandates vary by waste management infrastructure maturity.
Catalonia
Beverage bottlers and personal care converters drive PET demand through the Barcelona-Tarragona industrial axis. Extended producer responsibility schemes administered by the Catalan Waste Agency enforce earlier recyclate certification deadlines than national baselines. HolyGrail 2.0 digital watermark pilots at Valencia sorting facilities supply feedstock to Tarragona compounders.
Madrid
Pharmaceutical packaging clusters and national retail distributor headquarters concentrate procurement leverage for barrier-grade bottles. The national circular economy plan transposes EU Green Deal thresholds through the Ministry for Ecological Transition. Coslada logistics platforms coordinate just-in-time delivery to central Iberian bottling lines.
Andalusia
Agricultural chemical cooperatives in the Jaén-Seville corridor underutilize HDPE formats for olive oil and pesticide containment. Regional waste management infrastructure lags Catalonia in post-consumer flake recovery capacity. Seville-based converters serve cooperatives with 5-20 liter barrier coextrusion containers.
Valencia
Cosmetics houses and medical packaging specialists specify PP and PET formats for vials, droppers, and decorative bottles. The Valencian Institute of Business Competitiveness subsidizes mono-material design retrofits for EU recyclability compliance. Alicante beauty brand clusters aggregate small-run orders through cooperative purchasing pools.
Basque Country
Industrial chemical resistance applications and automotive fluid packaging sustain HDPE demand outside consumer sectors. Basque environmental authorities administer stricter recyclate traceability audits than Spanish national standards. Bilbao port logistics facilitate resin import and finished bottle export to French Atlantic markets.
Spain Plastic Bottles Market Competitive Landscape
Top-tier vendors anchor European multinational supply platforms, while mid-tier Iberian specialists compete on design flexibility and regional responsiveness. The market structure splits between scale-driven converters with integrated European operations and domestic fabricators serving fragmented beauty and agricultural chemical segments. Strategic archetypes include lightweight technology licensors, decorative small-run specialists, and barrier coextrusion compounders. Capacity expansion and mono-material format certification dominate competitive moves.
Among European-anchored multinationals, Amcor Group GmbH and Berry Global Inc. occupy positions exemplifying scale-driven platform supply, while Alcion Packaging Solutions SL represents the domestic specialist archetype focused on design-intensive formats. These three entities illustrate the competitive tension between standardized lightweight production and customized regional responsiveness that shapes procurement decisions across Spanish end-use segments.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| Alpla Group |
| Gerresheimer AG |
| Alcion Packaging Solutions SL |
| Berlin Packaging |
| Urola Packaging |
| Caiba Packaging |
| Frapak Packaging |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap converters in Catalonia and Valencia anchor supply discipline through generational ownership structures that resist short-term margin compression, enabling sustained investment in rPET certification despite working capital strain from EN 15343 audit backlogs.
Pricing Analysis
Margin tightening in standard-grade PET bottles reflects rPET flake price volatility during summer tourism peaks when collection diverts to export markets. Three-tier pricing structure across premium certified-rPET, standard virgin-blend, and economy non-compliant levels separates converters by EN 15343 certification status. Cost-down pressure on household cleaner segments accelerates because extended producer responsibility schemes mandate earlier compliance deadlines than beverage applications. Private-label bottlers serving national retail chains exhibit highest price sensitivity, while premium cosmetics houses tolerate premium-mid-economy pricing differentiation for decorative small-run formats.
Supply Chain Analysis
Dual-sourcing qualification requirements from Barcelona-Tarragona beverage bottlers mandate at least two approved resin compounders per SKU to mitigate single-supplier dependency in antimony-based catalyst systems. Raw material flows draw from German and Dutch specialty chemical producers for polymerization catalysts, domestic Tarragona compounders for rPET flake, and Saudi and Qatari feedstock for virgin PET resin. Single-source vulnerability in catalysis elevates inventory carrying costs for Iberian resin compounders. Distribution runs through Coslada logistics platforms for central Iberian bottling lines and Bilbao port facilities for French Atlantic export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's plastic bottles market functions as a vertical-integration race where converters capturing certified post-consumer feedstock streams upstream secure preferential access to extended producer responsibility fee discounts downstream.
For Market Incumbents: Cement rPET viscosity stabilization capabilities through captive polymer chemist hiring or technical university partnerships, defending against specialty compounders from Germany and the Netherlands expanding Iberian technical service presence. Prioritize mono-material format certification investments to lock in Barcelona-Catalonia beverage contract renewals before EU Green Deal enforcement timelines harden. For New Entrants and Emerging Players: Digital watermark traceability platforms offer technology-first wedge positioning for HolyGrail 2.0 sorting system integration at Valencia and Alicante facilities. Target Andalusia agricultural chemical cooperatives in the Jaén-Seville corridor for 5-20 liter HDPE barrier coextrusion containers, where domestic supplier gaps persist. Pursue cooperative purchasing pool aggregation models for regional beauty brands as the primary go-to-market angle. For Investors and Strategic Acquirers: EN 15343 accreditation body backlog clearance timelines are the leading indicator that working capital efficiency differentials will separate acquisition targets across the next decade. Focus on mid-cap converters with established Catalan Waste Agency compliance relationships and existing rPET certification infrastructure. Monitor rPET price spread compression versus virgin PET as the signal for feedstock security premium revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Collection | Catalan converters securing municipal collection contracts capture feedstock security premium before summer tourism export diversion peaks. |
| Mono-Material Format Certification | Barcelona-Tarragona bottlers specifying integrated label compatibility satisfy EU Green Deal recyclability targets without line replacement. |
| Digital Watermark Traceability Deployment | HolyGrail 2.0 sorting technology convergence with blockchain verification enables bottle-level provenance claims for premium personal care lines. |
| Technical University Partnership Programs | Valencia and Alicante cosmetics clusters addressing polymer chemist scarcity through subsidized graduate placement secure compounding knowledge gaps. |
| Cooperative Purchasing Pool Formation | Regional beauty brands aggregating small-run decorative bottle orders achieve lot size economics against consolidated national distributor leverage. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Spain plastic bottles market assessment, combining primary interviews with blow molding equipment operators, rPET compounder procurement leads, Catalan Waste Agency compliance officers, and personal care brand packaging directors with bottom-up and top-down triangulation. Secondary validation drew from EU Packaging and Packaging Waste Directive transposition documents, EN 15343 accreditation body audit schedules, HolyGrail 2.0 pilot deployment reports, and extended producer responsibility scheme fee structures administered at regional level.
Reconciliation of volume and value data streams across material type, application, closure engineering, and distribution channel dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level demand elasticity modeling against EU Green Deal recycled content threshold phase-ins. Industry-specific forecast inputs incorporated rPET flake supply seasonality patterns and bottling line retrofit capital deployment timelines across the Barcelona-Tarragona corridor.
Several conditions sit outside the modeled scope, including potential antimony catalyst supply disruptions from German and Dutch specialty chemical producers, unilateral regional waste management infrastructure acceleration in Andalusia, and EU Green Deal bonus mechanism legislative passage timelines. Forecasts reflect assumptions regarding EN 15343 accreditation body capacity expansion and municipal collection infrastructure investment continuity. Deviation in rPET price volatility amplitude or summer tourism collection export diversion intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
Global Plastic Container Market