
 Europe Confectionery Packaging Market | 2026-2036
Europe Confectionery Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Confectionery Packaging Market Foresight
Packaging engineering talent is rotating toward bio-based material science and circular design protocols across European converter networks. Huhtamaki OYJ leverages its Nordic R&D infrastructure to dominate molded fiber tray development for premium confectionery. Amcor PLC anchors its position through extended shelf-life barrier films that protect chocolate bloom sensitivity in southern European climates. Mondi plc competes via integrated kraft paper operations that supply confectionery brands with traceable, FSC-certified wrapping substrates.
Europe confectionery packaging encompasses primary and secondary enclosures engineered to preserve organoleptic properties, prevent fat bloom migration, and comply with food-contact migration limits measured in total volatile content. Heat-sealable barrier laminates, cold-seal coated papers, and grease-resistant folding cartons constitute the dominant technical formats, each specified by oxygen transmission rates and water vapor permeability thresholds calibrated to cocoa butter crystallization behavior. Flexible bags lead volume throughput across supermarket private-label chocolate lines where cost efficiency governs procurement, while rigid boxes capture margin pools in gift and seasonal segments where structural embossing and magnetic closures justify premium positioning. Biodegradable film represents the fastest-growing material trajectory as converters reformulate PLA and cellulose-based layers to meet home-composting certification under OK Compost and Seedling standards.
EMA food-contact guidelines, REACH chemical restriction frameworks, and the EU Packaging and Packaging Waste Regulation collectively shape material substitution timelines and extended producer responsibility obligations across the value chain. EFSA migration testing protocols for printing inks and adhesives directly determine which laminate structures gain market access for chocolate and sugar confectionery applications. Stakeholders must monitor whether the EU's pending mandatory recycled content thresholds for plastic packaging will accelerate fiber substitution or spur chemical recycling investments in food-grade polyolefin streams.
Market Dynamics
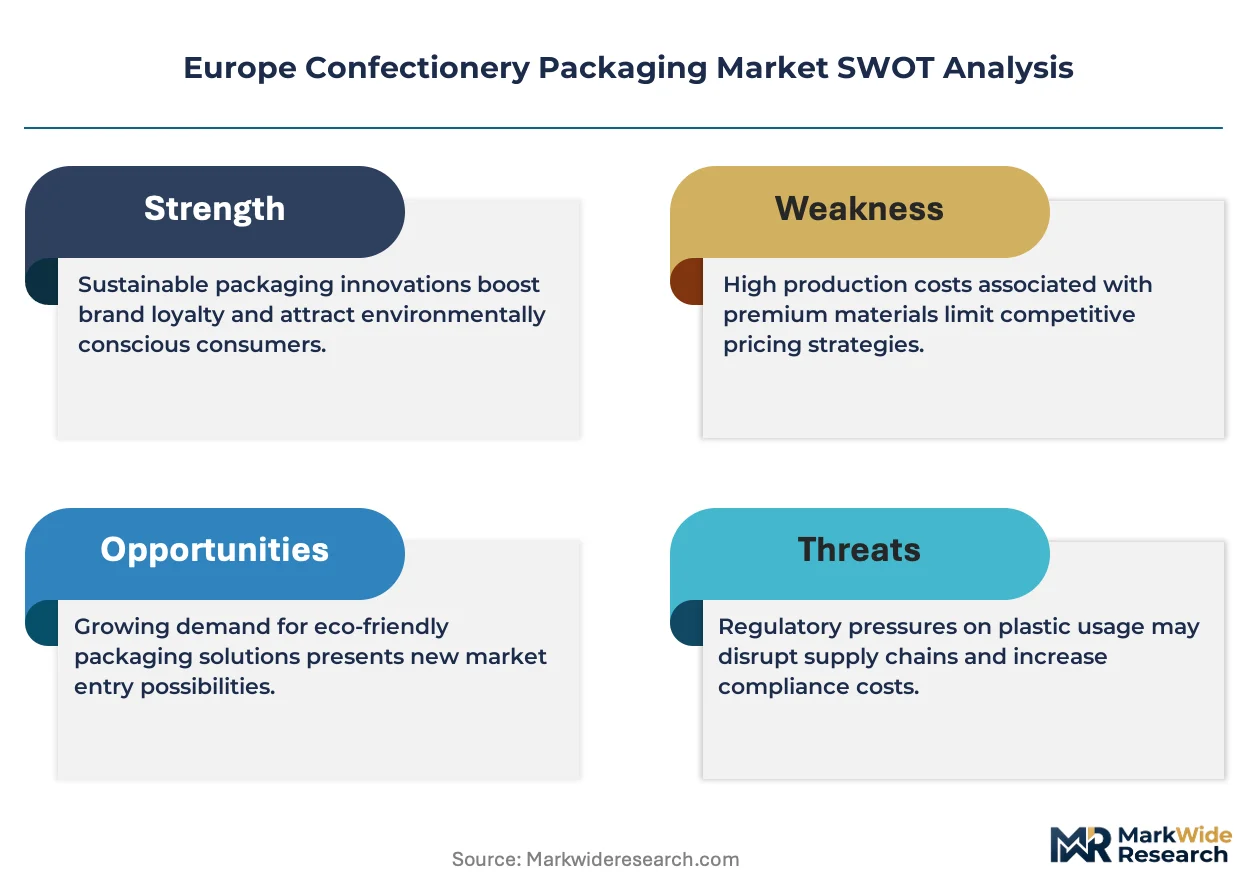
The EU Packaging and Packaging Waste Regulation is forcing immediate reformulation across converter networks, as recyclability thresholds and extended producer responsibility obligations compress material substitution timelines for chocolate and sugar confectionery applications.
Growth Catalysts
- REACH chemical restriction frameworks:These mandates accelerate fiber-based packaging migration by restricting certain plastic additives, creating procurement pull for FSC-certified kraft paper and molded fiber alternatives in premium chocolate segments.
- Benelux packaging cluster concentration:Dense converter infrastructure around Antwerp and Rotterdam enables rapid prototyping of biodegradable laminates, shortening development cycles for brands seeking OK Compost certification.
- Dual carbon goals alignment:Northern Italian converter hubs leverage renewable energy access to produce low-carbon folding cartons, attracting sustainability-linked procurement from French and German premium brands.
Market Restraints
- Pulp input cost volatility:Kraft paper pricing fluctuates with Nordic softwood supply cycles, squeezing margin pools for mid-tier converters supplying private-label chocolate lines.
- Barrier performance limitations:Current PLA and cellulose-based films fail to match polyolefin oxygen transmission rates for extended shelf-life applications in southern European climates.
- ECHA authorization bottlenecks:Novel bio-based adhesives face prolonged substance evaluation timelines, delaying laminate structure approvals for food-contact migration compliance.
Strategic Opportunities
- Poland and Czech Republic penetration:Underdeveloped sustainable packaging infrastructure in Central European confectionery manufacturing creates first-mover positioning for integrated kraft paper suppliers.
- Chemical recycling feedstock partnerships:Emerging food-grade polyolefin recovery streams offer pathway to meet pending EU mandatory recycled content thresholds without sacrificing barrier performance.
- Smart packaging integration:Convergence of printed electronics with cold-seal coated papers enables freshness indicators and authentication features for gift and seasonal chocolate segments.
Industry Challenges
- Bio-based material science talent scarcity:European converter networks compete for polymer chemists and circular design specialists capable of reformulating compostable layers to meet Seedling standards.
- EFSA migration testing backlog:Extended queue times for printing ink and adhesive safety evaluations delay product launches, compressing seasonal packaging development windows.
- Legacy heat-seal equipment retrofit costs:Converters face capital intensity in adapting production lines for cold-seal coated papers and fiber-based formats without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Confectionery Packaging Market |
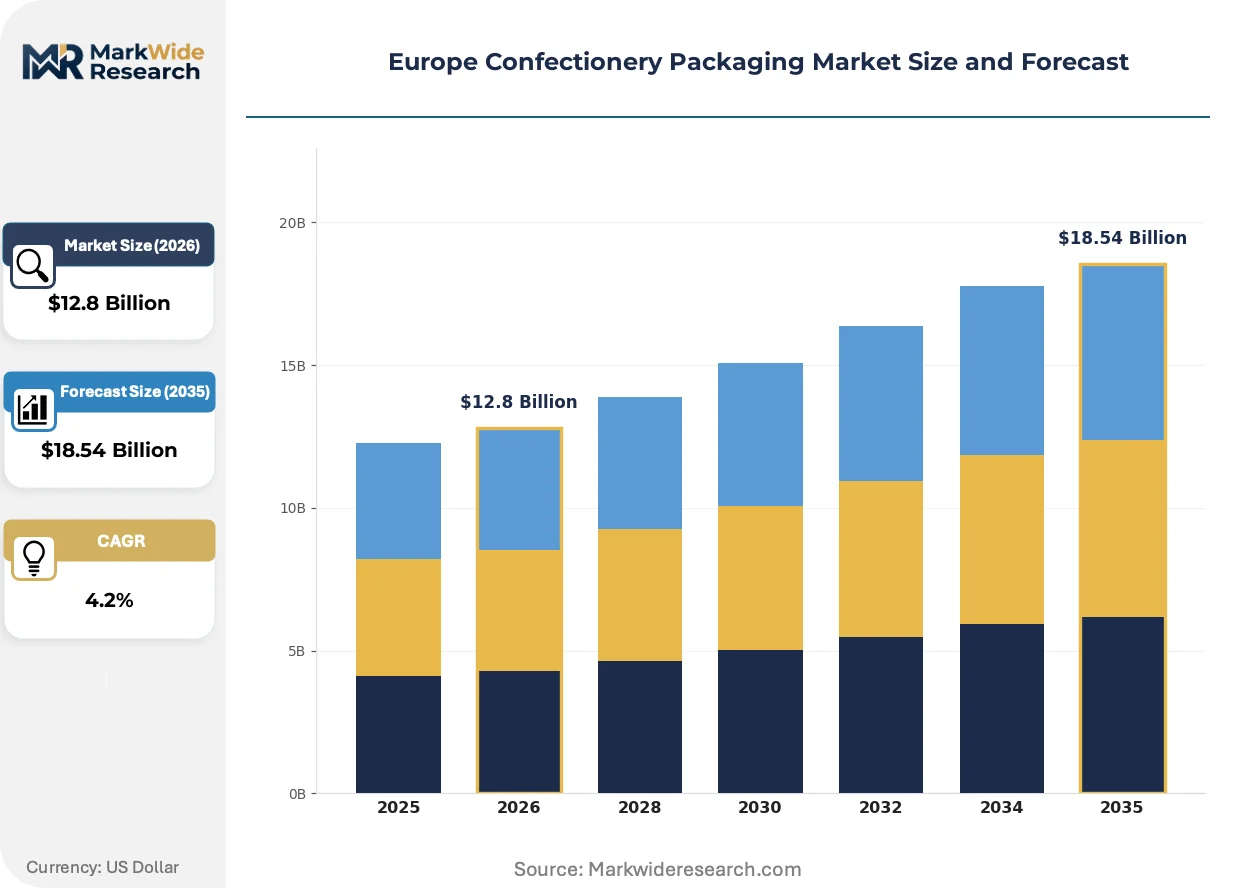
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $18.54 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Bags, Rigid Boxes, Paper Wraps, Plastic Containers Material: Paper, Plastic, Metal, Biodegradable Film End User: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops Design Style: Traditional, Modern, Eco-friendly, Thematic |
| Companies Covered | Huhtamaki OYJ, Amcor PLC, Smurfit Kappa Group, WestRock Company, Berry Global, International Paper, Mondi plc, Crown Holdings, Sealed Air Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Confectionery Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory compression are actively restructuring how European confectionery brands specify primary and secondary packaging formats, with sustainability credentials now determining supplier selection criteria ahead of unit economics.
Cellulose-based barrier films incorporating nanocellulose reinforcement layers are decomposing the technical performance gap between conventional plastics and bio-based alternatives. Premium chocolate brands in Switzerland and Belgium are piloting these laminates for praline assortments. The technology is decomposing incumbent polyolefin dependence by achieving water vapor permeability thresholds previously exclusive to metallized structures.
The EU Packaging and Packaging Waste Regulation's recyclability-by-design mandates are reshaping laminate architecture specifications across the value chain. Extended producer responsibility obligations now require brands to finance end-of-life collection systems. Southern European converters serving temperature-sensitive chocolate applications are responding with mono-material barrier structures that maintain shelf-life performance while satisfying mechanical recycling sortability criteria.
Certification-driven procurement criteria are restructuring buyer-supplier relationships in the gift and seasonal chocolate segment. Brands now require OK Compost or Seedling credentials as table stakes for vendor qualification, displacing traditional price-volume negotiations. This behavioral shift is most visible in Germany, where Aldi and Lidl private-label sustainability commitments cascade through their northern Italian converter networks.
Europe Confectionery Packaging Market Segmentation
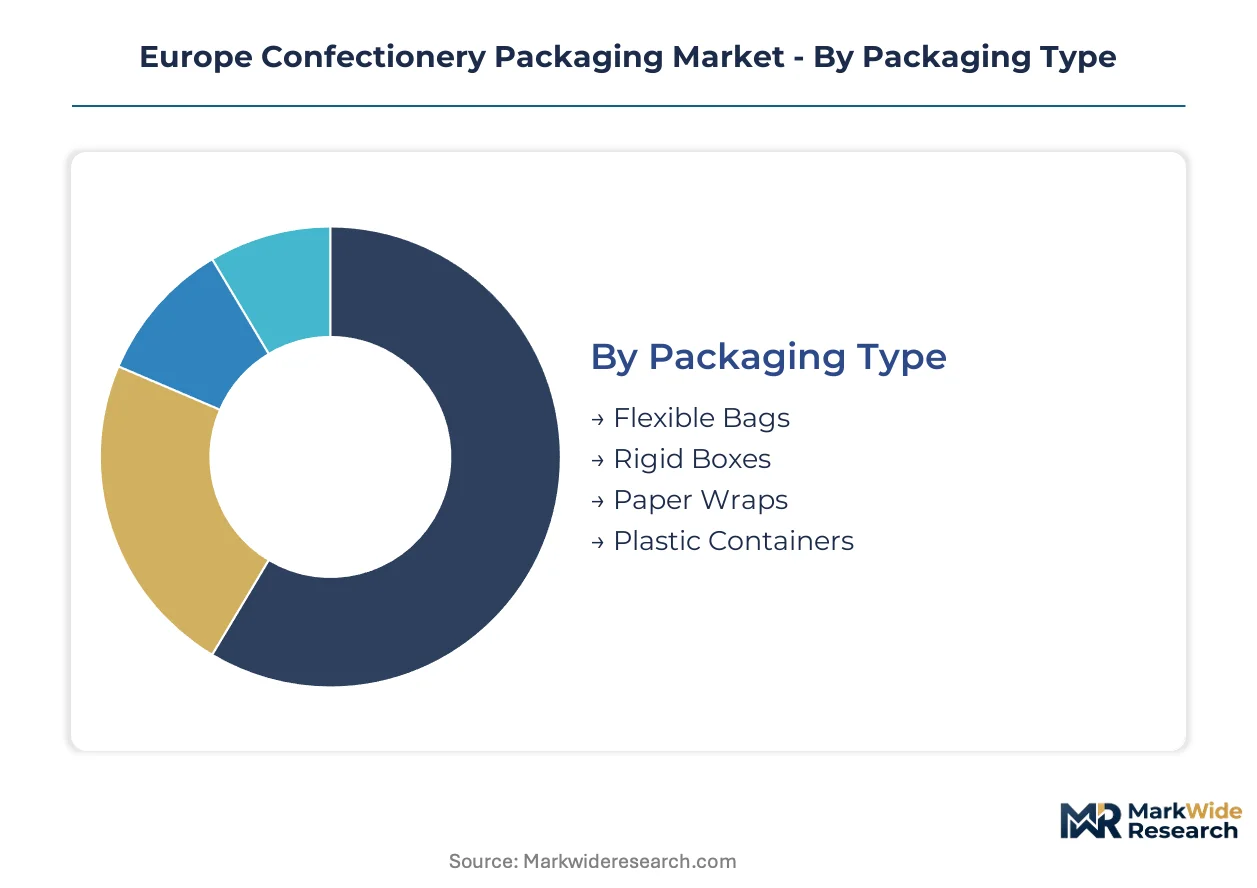
Packaging specification in European confectionery diverges sharply across temperature sensitivity, shelf-life requirements, and sustainability credentials. Segment boundaries are hardening as EU Packaging and Packaging Waste Regulation mandates force brands to requalify suppliers around recyclability thresholds rather than unit cost alone.
Packaging Type:
Flexible formats face acute substitution pressure from fiber-based alternatives as REACH restrictions on plastic additives accelerate converter migration toward paper solutions.
- Flexible Bags:Heat-sealable barrier laminates dominate supermarket private-label chocolate lines across Germany and France. Cost efficiency governs procurement, though EFSA migration testing bottlenecks for novel bio-based adhesives compress seasonal development windows.
- Rigid Boxes:Structural embossing and magnetic closures justify premium positioning in gift and seasonal segments. Northern Italian converter hubs leverage renewable energy access to produce low-carbon folding cartons for Swiss and Belgian praline brands.
- Paper Wraps:Cold-seal coated papers with grease-resistant barriers serve single-serve chocolate bars. Benelux packaging clusters enable rapid prototyping of biodegradable laminates seeking OK Compost certification.
- Plastic Containers:Polypropylene tubs retain presence in sugar confectionery bulk formats. Pending EU mandatory recycled content thresholds threaten this segment unless chemical recycling feedstock partnerships mature.
Flexible Bags anchors the volume base while Paper Wraps gains share at the steepest rate.
Material:
Cost tier stratification separates premium-certified substrates from commodity grades, with FSC traceability commanding measurable procurement premiums.
- Paper:Kraft paper operations supply traceable, FSC-certified wrapping substrates. Pulp input cost volatility squeezes margin pools for mid-tier converters supplying Aldi and Lidl private-label lines.
- Plastic:Polyolefin barrier films protect chocolate bloom sensitivity in southern European climates. Mono-material structures are displacing multi-layer laminates to satisfy mechanical recycling sortability criteria.
- Metal:Metallized films and foil laminates preserve extended shelf-life for temperature-sensitive applications. ECHA authorization bottlenecks for novel barrier coatings delay laminate structure approvals.
- Biodegradable Film:PLA and cellulose-based layers reformulated to meet home-composting certification under Seedling standards. Nanocellulose reinforcement layers are decomposing the technical performance gap with conventional plastics.
Paper commands the revenue base while Biodegradable Film climbs the fastest on certification-driven procurement.
End User:
Channel concentration in Western European retail networks determines volume allocation, with sustainability-linked procurement cascading through dominant grocery formats.
- Supermarkets:Aldi and Lidl sustainability commitments cascade through northern Italian converter networks. Private-label chocolate lines prioritize cost-efficient flexible formats with FSC-certified paper alternatives.
- Convenience Stores:Single-serve and impulse formats favor heat-sealable barrier laminates with extended shelf-life properties. Southern European climates demand superior oxygen transmission rate specifications.
- Online Retailers:E-commerce penetration demands protective secondary packaging with dimensional efficiency. Smart packaging integration enables freshness indicators for direct-to-consumer gift segments.
- Specialty Shops:Premium chocolate brands in Switzerland and Belgium pilot cellulose-based barrier films for praline assortments. Structural differentiation through magnetic closures and embossing justifies margin capture.
Supermarkets anchors volume throughput while Online Retailers expands most quickly on channel shift dynamics.
Design Style:
Maturity gradients separate established aesthetic conventions from emerging sustainability-forward visual languages that now determine vendor qualification.
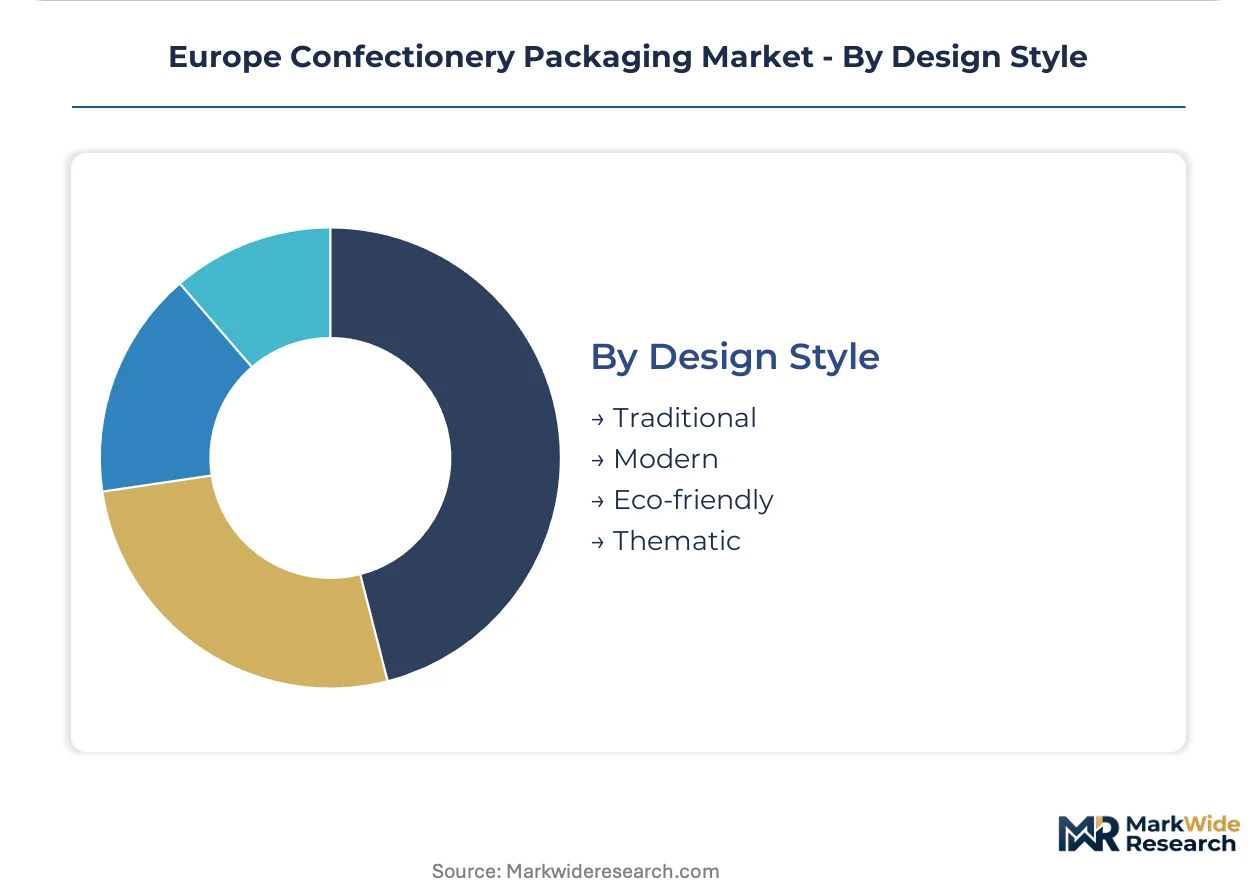
- Traditional:Heritage typography and seasonal motifs dominate gift and seasonal chocolate segments. German and French premium brands retain these formats for established consumer loyalty.
- Modern:Minimalist graphics and structural innovation attract urban demographics in Benelux markets. Cold-seal coated papers enable high-fidelity printing with barrier performance.
- Eco-friendly:Certification marks and material transparency claims now serve as table stakes. OK Compost and Seedling credentials displace traditional price-volume negotiations.
- Thematic:Limited-edition collaborations and event-driven packaging compress development timelines. EFSA migration testing backlog for printing inks threatens seasonal launch windows.
Traditional retains the margin base while Eco-friendly advances fastest on regulatory compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premium chocolate brands favor rigid folding cartons with magnetic closures, while French supermarkets prioritize cost-efficient flexible formats. Italian converters supply both with renewable-energy-produced substrates. Swiss and Belgian praline manufacturers pilot cellulose-based barrier films for extended shelf-life applications.
Germany
Aldi and Lidl sustainability commitments cascade through northern Italian converter networks, driving FSC-certified paper procurement for private-label chocolate lines. REACH chemical restriction frameworks accelerate fiber-based packaging migration by restricting certain plastic additives. The Benelux packaging cluster around Antwerp and Rotterdam enables rapid prototyping of biodegradable laminates for German brands seeking OK Compost certification.
France
Premium chocolate brands accelerate demand for sustainable folding carton solutions with structural embossing and heritage typography. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that favor fiber-based formats over multi-layer laminates. Northern Italian converter hubs leverage renewable energy access to produce low-carbon folding cartons for French premium brands.
Switzerland
Praline manufacturers pilot cellulose-based barrier films incorporating nanocellulose reinforcement layers for temperature-sensitive applications. EFSA migration testing protocols for printing inks and adhesives directly determine which laminate structures gain market access. Swissmedic food-contact guidelines shape material substitution timelines for chocolate and sugar confectionery applications.
Belgium
Specialty chocolate producers demand mono-material barrier structures that satisfy mechanical recycling sortability criteria under extended producer responsibility obligations. The EU Green Deal alignment creates procurement pull for bio-based alternatives in gift and seasonal segments. Dense converter infrastructure around Antwerp enables rapid development cycles for brands seeking Seedling certification.
Italy
Converter hubs in the north supply traceable, FSC-certified wrapping substrates to German and French supermarket private-label lines. Dual carbon goals alignment attracts sustainability-linked procurement from premium brands across the Alps. Pulp input cost volatility squeezes margin pools for mid-tier converters supplying cost-efficient flexible bag formats.
Europe Confectionery Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in Nordic R&D infrastructure and integrated kraft paper operations. The market structure favors converters with captive pulp supply and renewable energy access over asset-light traders. Three archetypes dominate: integrated fiber-based substrate producers, barrier film specialists with extended shelf-life capabilities, and rigid format engineers serving gift segments. Competitive moves center on chemical recycling feedstock partnerships and smart packaging integration with printed electronics.
Within the integrated fiber-based tier, Huhtamaki OYJ and Mondi plc exemplify Nordic-origin converters with captive material science capabilities. Amcor PLC occupies a position among barrier film specialists addressing chocolate bloom sensitivity in southern European climates. These three anchors represent distinct competitive vectors—fiber integration, barrier performance, and geographic climate adaptation—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Huhtamaki OYJ |
| Amcor PLC |
| Smurfit Kappa Group |
| WestRock Company |
| Berry Global |
| International Paper |
| Mondi plc |
| Crown Holdings |
| Sealed Air Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between northern Italian converter hubs and Nordic pulp suppliers lock in both fiber substrate access and eighteen-month price visibility for FSC-certified kraft paper operations serving German and French premium chocolate brands.
Pricing Analysis
Project-based pricing for custom rigid folding cartons dominates gift and seasonal segments, while spot-market transactions govern flexible bag formats for Aldi and Lidl private-label lines. Three-tier pricing structure across premium certified, standard FSC-traceable, and economy-grade paper tiers separates Swiss praline brands from mid-tier Belgian producers. Cost compression in biodegradable film laminates is intensifying because ECHA authorization bottlenecks delay novel adhesive approvals and extend development cycles. Private-label supermarket buyers exhibit highest price sensitivity, while specialty chocolate houses in Belgium and Switzerland prioritize certification premiums over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp elevates inbound logistics costs for South American pulp shipments feeding Benelux packaging clusters. Raw material sourcing draws from Nordic softwood operations, German chemical adhesive producers, and Italian renewable energy infrastructure. Single-source vulnerability concentrates in metallized barrier film supply from German specialty coating operations. Distribution runs through converter-direct relationships with Aldi and Lidl procurement networks, bypassing traditional wholesale channels for private-label chocolate packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Aldi and Lidl sustainability-linked procurement commitments that cascade qualification requirements across northern Italian converter networks, fragmenting supplier negotiating leverage.
For Market Incumbents: Consolidate backward integration into Nordic pulp supply to defend margin pools against kraft paper price volatility squeezing mid-tier converters. Secure captive renewable energy capacity in Italian hub locations to maintain low-carbon folding carton cost advantages as EU carbon border adjustments mature. Prioritize EFSA pre-submission for novel bio-based adhesives to compress seasonal development windows ahead of competitor filings. For New Entrants and Emerging Players: Rapid prototyping services for OK Compost certification represent the most penetrable service-layer gap where incumbent converters under-serve mid-size Belgian praline brands. Target Poland and Czech Republic sustainable packaging infrastructure gaps through technical partnership offers to Central European confectionery manufacturers. Lead with chemical recycling feedstock advisory capabilities to differentiate from established fiber-based substrate suppliers. For Investors and Strategic Acquirers: Specialist barrier film developers with nanocellulose reinforcement patents offer the clearest acquisition target archetype for exposure to cellulose-based laminate substitution trajectories. Long-term viability hinges on whether bio-based materials achieve oxygen transmission rate parity with polyolefin benchmarks across the analysis window. Monitor EFSA migration testing queue lengths as inflection indicator for seasonal packaging development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Feedstock Partnership | Enables compliance with pending EU recycled content thresholds without sacrificing chocolate barrier performance. |
| Smart Packaging Integration | Converges printed electronics with cold-seal papers for freshness indicators in direct-to-consumer gift segments. |
| Renewable Energy Capacity Expansion | Secures low-carbon folding carton production credentials for sustainability-linked procurement from French premium brands. |
| EFSA Pre-Certification Investment | Accelerates novel bio-based adhesive approvals ahead of seasonal packaging development windows. |
| Central European Geographic Expansion | Captures first-mover positioning in underdeveloped Poland and Czech Republic sustainable packaging infrastructure. |
Research Methodology
The analysis maps flexible bag, rigid box, paper wrap, and plastic container formats, each validated through converter operations directors, Aldi and Lidl category procurement managers, EFSA regulatory affairs specialists, and Nordic pulp supply planners. Primary interview data triangulates against secondary sources including EU Packaging and Packaging Waste Regulation implementation drafts, REACH restriction candidate list updates, FSC chain-of-custody certification databases, and Benelux customs trade records. Bottom-up volume modeling from individual converter capacity disclosures reconciles with top-down market sizing from European packaging association aggregates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include packaging type, material substrate, end-user channel, and design style tier, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from weighted average growth assumptions across each segment's modeled trajectory, incorporating pulp input cost volatility indices and EU mandatory recycled content threshold implementation pacing as forecast inputs.
Material uncertainties — pulp price cycle reversals, ECHA authorization timeline extensions, and EU recycled content threshold finalization — sit outside the modeled envelope. Forecasts reflect assumptions about REACH restriction enforcement intensity and OK Compost certification adoption velocity. Recalibration cycles align with material shifts in EFSA migration testing protocols and EU Packaging and Packaging Waste Regulation secondary legislation releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Confectionery Packaging Market