
 Europe Dietary Supplement Packaging Market | 2026-2036
Europe Dietary Supplement Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dietary Supplement Packaging Market Foresight
The EU Green Deal is consolidating demand toward mono-material and post-consumer recycled substrates across European supplement packaging. Amcor Group GmbH leverages its continental manufacturing footprint to supply pharmaceutical-grade barrier films. Gerresheimer AG anchors high-end glass and plastic bottle production for premium vitamin brands. Berry Global Group Inc. competes on scale in HDPE and PET container formats for mass-market probiotics.
Europe Dietary Supplement Packaging encompasses primary and secondary containment systems engineered to protect bioactive compounds from moisture, oxidation, and UV degradation through specified barrier layers, desiccant integration, and child-resistant closure mechanisms. Blister packs lead unit volume due to unit-dose compliance advantages in pharmacy channels, while sachets register the fastest growth as powder and gummy formats expand in direct-to-consumer online distribution. Plastic maintains dominant share across bottles and jars, though aluminum and paper substrates are gaining structural ground where EPR fees and national packaging taxes elevate the cost of virgin polymer.
EMA stability guidelines and EU Packaging and Packaging Waste Regulation (PPWR) obligations shape material selection and shelf-life validation protocols for all market participants. REACH compliance on chemical migration and national extended producer responsibility schemes in France, Germany, and Italy directly determine converter cost structures and brand owner sourcing criteria. Stakeholders must monitor upcoming PPWR recycled content mandates and evolving EPR fee differentials between mono-material and multi-layer structures when committing to capital equipment and supply agreements.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing converter margins while forcing rapid substrate transitions toward mono-material films and post-consumer recycled content across European pharmaceutical packaging supply chains.
Growth Catalysts
- Sports Nutrition Procurement Surge:Cross-border e-commerce fulfillment networks are pulling HDPE bottles and flexible pouches into Poland and Romania as brands regionalize distribution.
- REACH Chemical Migration Standards:Harmonized safety protocols are eliminating fragmented national testing regimes, reducing time-to-market for compliant barrier laminates.
- Desiccant Integration Technology:Embedded humidity control systems are extending shelf-life claims for hygroscopic probiotic powders in direct-to-consumer sachet formats.
Market Restraints
- EPR Fee Differentials:Extended producer responsibility schemes in France, Germany, and Italy impose cost penalties on multi-layer structures versus mono-material alternatives.
- Post-Consumer Recycled Resin Supply:Food-grade rPET and rHDPE availability concentrates among German and Dutch chemical recyclers, creating input bottlenecks.
- Blister Pack Aluminum Substitution Limits:Paper-based push-through lidding films currently fail child-resistance certification thresholds for iron and calcium supplements.
Strategic Opportunities
- Central and Eastern Europe Manufacturing:Greenfield converter investments in Hungary and Czechia capture labor cost arbitrage while maintaining EU regulatory alignment.
- Refillable Glass Bottle Systems:Deposit-return schemes in Germany and Nordic markets create circular revenue streams for premium vitamin brands.
- EU Green Deal Packaging Taxonomy:Recycled content mandates scheduled through 2030 are accelerating brand owner commitments to long-term supply agreements.
Industry Challenges
- Pharmaceutical-Grade Barrier Film Certification:EMA stability validation protocols require 24-36 month qualification timelines for new substrate combinations.
- Legacy Heat-Seal Equipment Retrofit:Mono-material polyolefin films demand temperature profile reconfiguration incompatible with existing PVC-oriented machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dietary Supplement Packaging Market |
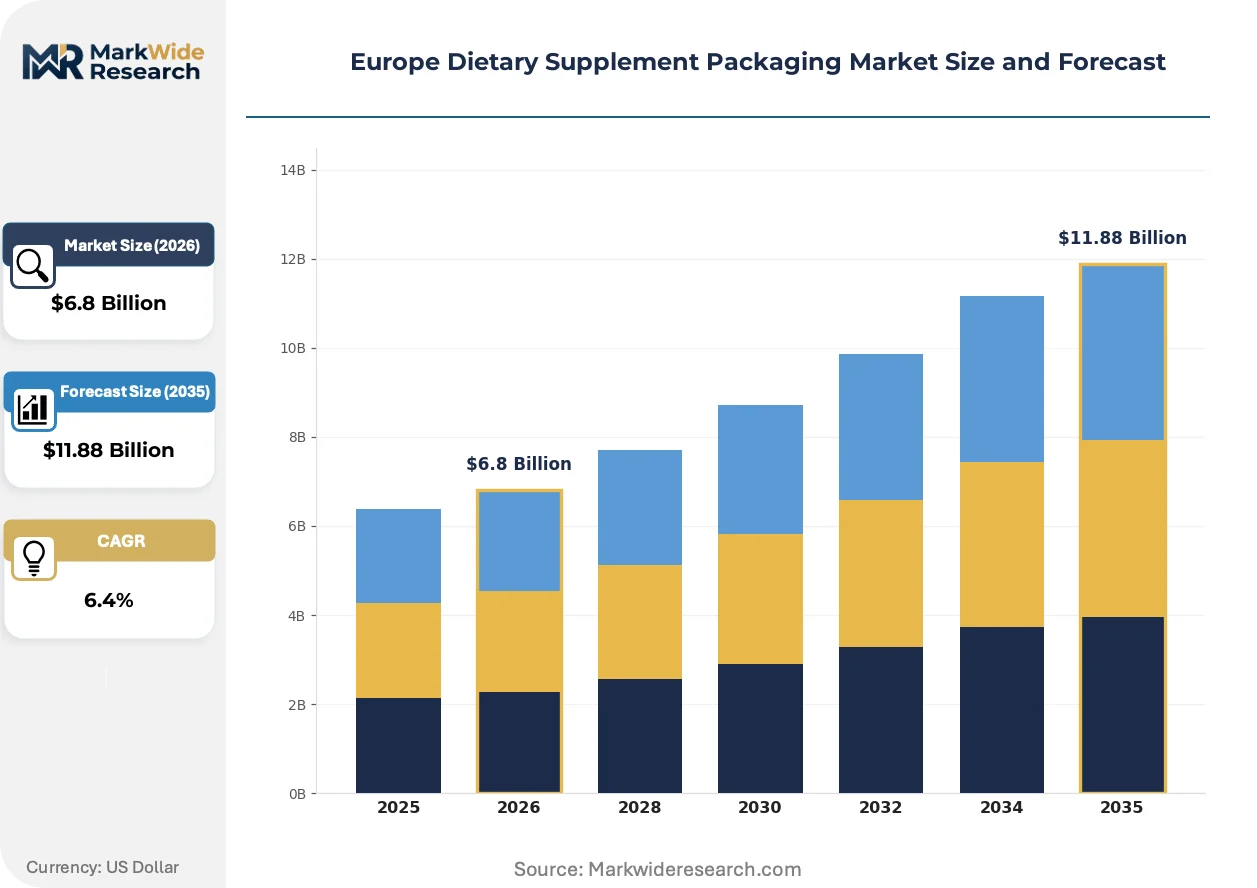
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Sachets, Blister Packs, Jars Material: Plastic, Glass, Paper, Aluminum Closure Type: Screw Caps, Flip Tops, Snap On, Push Down Distribution Channel: Retail Stores, Online, Pharmacies, Supermarkets |
| Companies Covered | OPM Group Ltd, Novio Packaging B.V., Alpha Packaging, Amcor Group GmbH, Law Print & Packaging Management Ltd., Gerresheimer AG, Graham Packaging Company, Berry Global Group Inc., Moulded Packaging Solutions Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dietary Supplement Packaging Market Shifts & Advancements
Active and intelligent packaging systems are penetrating European supplement channels as brands seek differentiation through compliance verification and consumer engagement features.
Mono-material polypropylene blister films are expanding into pharmacy-dispensed vitamin segments previously dominated by PVC-PVDC laminates. German and Swiss contract manufacturers are retrofitting thermoforming lines to process these substrates at commercial scale. This transition is expanding into high-barrier applications as metallization and SiOx coating technologies mature for oxygen-sensitive formulations.
EU Green Deal carbon border adjustment mechanisms are reshaping converter sourcing decisions for aluminum foil and virgin polymer feedstocks. The regulatory pressure is compressing margins on imported multi-layer structures while incentivizing localized recycling infrastructure investments. Italian and Spanish packaging clusters are responding fastest through consortium arrangements with chemical recycling ventures.
Direct-to-consumer subscription models are fragmenting order profiles toward small-batch, SKU-diverse production runs. Powder and gummy formats in unit-dose sachets and stick packs are displacing bulk jar configurations among urban millennial demographics. This behavioral shift concentrates in Benelux and Scandinavian markets where last-mile delivery density supports profitable micro-fulfillment economics.
Europe Dietary Supplement Packaging Market Segmentation
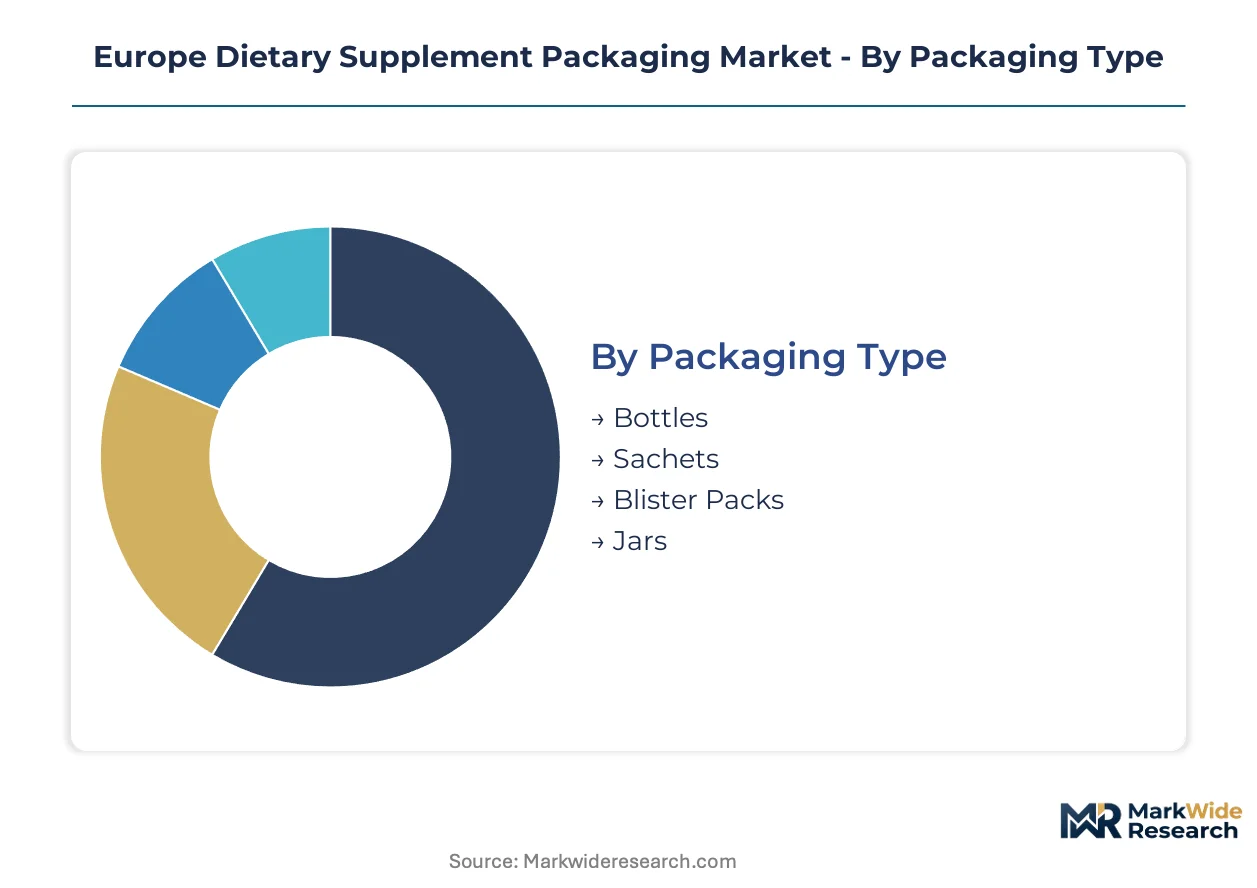
Packaging format selection in European dietary supplements reflects divergent shelf-life requirements, child-safety mandates, and direct-to-consumer fulfillment economics. Material and closure specifications cascade from these primary containment decisions, with each combination triggering distinct regulatory qualification pathways under EMA stability guidelines.
Packaging Type:
Standardized pharmacy formats compete against customizable direct-to-consumer configurations across this spectrum, with automation compatibility and line-speed economics determining converter investment priorities.
- Bottles:HDPE and PET containers dominate mass-market probiotic and multivitamin distribution through German and French retail pharmacy networks. Demand clusters around Frankfurt logistics corridors where contract manufacturers operate high-speed filling lines optimized for 60-400cc formats.
- Sachets:Flexible stick packs and flat pouches serve powder and gummy formats in Benelux subscription commerce, where micro-fulfillment economics favor lightweight, postage-optimized containment. Desiccant-integrated laminates extend shelf-life claims for hygroscopic formulations in this channel.
- Blister Packs:PVC-PVDC and emerging mono-material polypropylene films provide unit-dose compliance advantages for pharmacy-dispensed iron and calcium supplements.
- Jars:Wide-mouth PET and glass configurations accommodate scoop-dosed protein powders and bulk gummy formats in sports nutrition segments.
Leading the category by volume: Bottles. Growing fastest: Sachets.
Material:
Cost tier stratification separates virgin polymer feedstocks from recycled-content premiums and specialty barrier substrates, with EPR fee differentials compressing margins on multi-layer structures.
- Plastic:Virgin and post-consumer recycled HDPE, PET, and polypropylene constitute the baseline substrate for bottles, jars, and flexible films. German and Dutch chemical recyclers concentrate food-grade rPET and rHDPE supply, creating input bottlenecks for converters seeking EU Green Deal compliance.
- Glass:Amber and flint pharmaceutical-grade bottles serve premium vitamin brands in German and Nordic deposit-return scheme markets, where refillable systems generate circular revenue streams.
- Paper:Fiber-based cartons and emerging barrier boards gain ground in secondary packaging and promotional multipacks where plastic reduction targets apply.
- Aluminum:Blister lidding foils and tube formats provide absolute moisture and light barriers for oxygen-sensitive formulations, though carbon border adjustment mechanisms elevate imported substrate costs.
Dominating volume: Plastic. Steepest expansion trajectory: Paper.
Closure Type:
Application-specific safety requirements and consumer convenience expectations segment this category across child-resistant mandates and single-handed accessibility standards.
- Screw Caps:Continuous-thread HDPE and PP closures with induction seals secure bottles for hygroscopic powders and liquid formulations across retail and pharmacy channels.
- Flip Tops:Hinged polypropylene designs enable single-handed dispensing for sports nutrition and on-the-consumption scenarios in direct-to-consumer formats.
- Snap On:Press-fit closures for jars and wide-mouth containers balance resealability with manufacturing simplicity in high-volume gummy and powder segments.
- Push Down:Child-resistant mechanisms for iron supplement bottles meet pharmacy dispensing requirements in France, Germany, and Italy where pediatric safety regulations apply.
Highest penetration: Screw Caps. Climbing the fastest: Push Down.
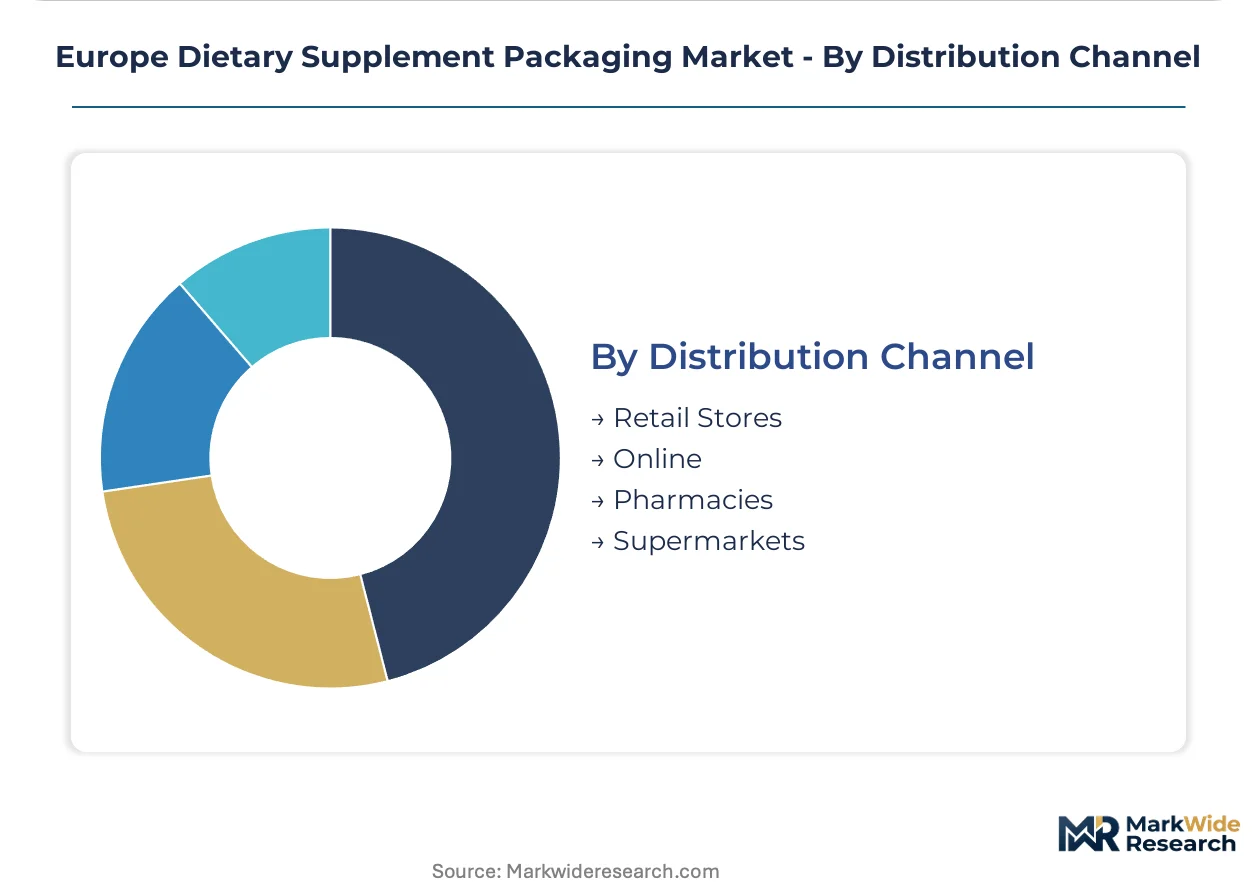
Distribution Channel:
Customer type and purchase occasion fragment order profiles, with channel-specific packaging specifications diverging on batch size, labeling language requirements, and promotional display functionality.
- Retail Stores:Health food and specialty vitamin shops in Germany and the UK demand shelf-ready secondary packaging with multi-language labeling and promotional billboard features.
- Online:Direct-to-consumer and marketplace fulfillment networks in Benelux and Scandinavia prioritize damage-resistant, postage-optimized formats with unboxing experience design.
- Pharmacies:German and French pharmacy dispensing channels require unit-dose compliance packaging, child-resistant closures, and prescription-adjacent shelf positioning.
- Supermarkets:Mass-market grocery retail in Poland and Romania pulls high-volume, price-optimized bottle and jar formats for private-label supplement lines.
Channel leader by volume: Retail Stores. Gaining share fastest: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Hamburg anchor European supplement packaging procurement, with contract manufacturers clustering around these logistics corridors to serve pharmacy and direct-to-consumer channels. German demand for pharmaceutical-grade barrier films and child-resistant closures sets material specifications across the continent.
Germany
Sports nutrition brands drive procurement of HDPE bottles and flexible pouches through Frankfurt's contract manufacturing belt. The national packaging tax under Germany's Extended Producer Responsibility scheme penalizes multi-layer structures, accelerating converter transitions toward mono-material alternatives. Hamburg's port infrastructure enables rPET and rHDPE imports from Dutch chemical recyclers.
France
Pharmacy-dispensed iron and calcium supplements sustain demand for unit-dose blister packs with push-through lidding. ANSM pediatric safety regulations mandate child-resistant certification thresholds that paper-based alternatives currently fail. Lyon and Paris packaging clusters specialize in high-barrier laminates for hygroscopic probiotic formulations.
United Kingdom
Health food retail chains in London and the Southeast require shelf-ready secondary packaging with multi-language labeling for export markets. Post-Brexit REACH alignment maintains chemical migration testing protocols equivalent to EU standards. Midlands converters supply induction-sealed bottles for liquid supplement distribution.
Netherlands
Benelux subscription commerce concentrates demand for postage-optimized sachets and stick packs in urban fulfillment networks. Rotterdam's chemical recycling infrastructure supplies food-grade rPET to converters serving premium vitamin brands. Amsterdam-based brands lead unboxing experience design for direct-to-consumer formats.
Poland
Cross-border e-commerce fulfillment networks pull HDPE bottles and flexible pouches into Warsaw and Krakow distribution hubs. Regionalized brand strategies exploit labor cost arbitrage while maintaining EU regulatory alignment. Poznan's emerging converter investments target German and French brand owner supply agreements.
Europe Dietary Supplement Packaging Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with continental manufacturing footprints. Consolidation among barrier film specialists and rigid container producers has compressed mid-tier converter margins. Three archetypes dominate: pharmaceutical-grade barrier specialists, mass-market scale players, and regional flexible packaging experts. Capacity expansion in Central European greenfield sites and strategic partnerships with chemical recyclers constitute the primary competitive moves.
Among Germany-based rigid packaging specialists, Gerresheimer AG and Amcor Group GmbH exemplify the pharmaceutical-grade tier, while Berry Global Group Inc. represents scale-driven container production. These anchors reflect the market's bifurcation between premium barrier specifications and high-volume commodity formats.
| Leading Market Players |
|---|
| OPM Group Ltd |
| Novio Packaging B.V. |
| Alpha Packaging |
| Amcor Group GmbH |
| Law Print & Packaging Management Ltd. |
| Gerresheimer AG |
| Graham Packaging Company |
| Berry Global Group Inc. |
| Moulded Packaging Solutions Limited |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade barrier certification tiers bifurcate the European supplement packaging market into premium validated substrates and commodity-grade alternatives, with EMA stability protocols and EU Green Deal mandates simultaneously elevating qualification costs and compressing margins on multi-layer structures. This tier divergence concentrates pricing power among German and Swiss converters with in-house metallization capabilities while forcing mid-tier players toward mono-material transitions that sacrifice barrier performance for EPR compliance.
Pricing Analysis
Outcome-linked pricing tied to shelf-life extension claims anchors premium tier valuations for desiccant-integrated sachets and high-barrier blister films. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certification levels separates contract manufacturers serving pharmacy channels from mass-market private-label suppliers. Cost compression in commodity HDPE bottles is intensifying because Polish and Romanian converters exploit labor arbitrage without sacrificing REACH compliance. Private-label supermarket buyers in Central Europe exhibit highest price sensitivity, while premium vitamin brands in German deposit-return markets absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Deposit-return scheme flows and refillable glass bottle refurbishment networks create reverse-logistics revenue streams that offset virgin material costs in German and Nordic markets. Raw material supply concentrates in Germany, the Netherlands, and Belgium, where chemical recyclers produce food-grade rPET and rHDPE for compliant substrate production. Converter operations draw from aluminum foil imports facing EU carbon border adjustment exposure, alongside specialized desiccant masterbatch supply from Swiss compounders. Single-source vulnerability sits with Dutch chemical recycling infrastructure for pharmaceutical-grade recycled resins. Distribution runs through Frankfurt and Hamburg logistics corridors serving contract manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Dietary Supplement Packaging Market functions as a cost-of-compliance arena where EU Packaging and Packaging Waste Regulation mandates erect capital barriers that favor incumbent converters with amortized qualification investments. This regulatory moat protects validated players while exposing under-capitalized entrants to 24-36 month EMA stability protocol timelines.
For Market Incumbents: Cement barrier film specialization advantages by acquiring Central European flexible packaging assets in Hungary and Czechia before greenfield competition intensifies. Threat substitution from paper-based push-through lidding demands accelerated SiOx coating R&D to maintain child-resistance certification for iron supplement formats. Capacity addition in Poznan and Bratislava corridor captures e-commerce fulfillment growth while defending margin position against resin cost volatility through backward integration into chemical recycling partnerships. For New Entrants and Emerging Players: Direct-to-consumer subscription brands represent the most penetrable anchor customer segment, with Benelux and Scandinavian markets offering unboxing experience differentiation opportunities absent entrenched supplier relationships. White-space targets include postage-optimized stick packs for urban millennial demographics and refillable glass systems for German deposit-return scheme participation. Go-to-market execution should prioritize co-development partnerships with Amsterdam and Copenhagen-based brands seeking rapid SKU iteration. For Investors and Strategic Acquirers: Re-rating potential sits with mono-material barrier specialists given PPWR recycled content mandates accelerating brand owner long-term supply commitments. Five-to-ten year viability favors converters with demonstrated EMA validation track records and established chemical recycler feedstock agreements. Acquisition target archetype encompasses mid-tier flexible packaging players in Central Europe with underutilized thermoforming capacity compatible with polypropylene film transitions. Signal to monitor: EPR fee differential expansion between mono-material and multi-layer structures as inflection indicator for substrate transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Film Transition | EMA validation protocols for polypropylene blister substrates unlock pharmacy channel access previously restricted to PVC-PVDC laminates. |
| Chemical Recycling Partnership | Long-term rPET and rHDPE supply agreements with Dutch and German recyclers secure EU Green Deal compliance ahead of mandated recycled content thresholds. |
| Central European Capacity Expansion | Greenfield converter investments in Hungary and Czechia capture labor cost arbitrage while maintaining REACH regulatory alignment with Western European brand owners. |
| Desiccant Integration Technology | Embedded humidity control systems extend shelf-life claims for hygroscopic probiotic powders in direct-to-consumer sachet formats. |
| Refillable Glass System Deployment | Deposit-return scheme participation in German and Nordic markets generates circular revenue streams for premium vitamin brands. |
Research Methodology
Independent corroboration across converter production data, brand owner procurement disclosures, and regulatory filing repositories underwrites the qualitative findings presented in this study. Primary interviews with contract manufacturing executives, packaging procurement leads at sports nutrition brands, regulatory affairs specialists at EMA-notified bodies, and flexible packaging plant managers informed substrate transition timelines and qualification bottlenecks. Secondary validation drew from EU Packaging and Packaging Waste Regulation impact assessments, EMA stability guideline documentation, extended producer responsibility fee schedules in France, Germany, and Italy, and chemical recycling capacity announcements from Dutch and German producers. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis.
Historical reference periods spanning pre-pandemic baseline through post-PPWR announcement response phases anchored the forecast window to observable regulatory shock effects and converter adaptation patterns. The analytical framework disaggregates volume and value projections across packaging format, material substrate, closure type, and distribution channel dimensions, with supplemental segmentation by barrier performance tier and certification status. CAGRs derive from regression-adjusted trend extrapolation incorporating EPR fee trajectory assumptions and chemical recycling capacity buildout schedules. Industry-specific forecast inputs include desiccant integration adoption curves and mono-material film line retrofit investment pipelines reported by German and Swiss equipment suppliers.
Several conditions sit outside the modeled scope, including potential REACH restriction amendments on specific polymer additives, unilateral national packaging tax escalations beyond current EPR schedules, and breakthrough barrier technologies that circumvent existing validation protocols. Forecasts reflect documented assumptions regarding recycled resin availability and brand owner compliance timelines. Practitioners should monitor PPWR delegated act publications and EMA stability guideline revision consultations for early signals of regulatory trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Container Market