
 Brandy Market | 2026-2036
Brandy Market Size, Share, and Industry Trends Forecast 2026-2036
Brandy Market Intelligence
Bars and restaurants is repositioning brandy consumption away from traditional at-home sipping toward mixology-driven occasions. Hennessy leverages its dominance in Cognac to control premium on-premise placements across major metropolitan venues. Martell sustains competitive pressure through specialized reserve expressions targeting bartender education programs. E&J Brandy anchors the accessible tier in North American retail channels with consistent volume positioning.
Brandy denotes a spirit distilled from wine or fermented fruit mash, typically aged in oak casks at 40% alcohol by volume or higher, with color and complexity deriving from wood extraction and oxidation during maturation. Its primary commercial purpose centers on premium beverage consumption, culinary application, and mixology integration across hospitality and retail environments. Pure Brandy occupies the largest margin pool due to heritage authentication and aging infrastructure requirements, while Flavored Brandy competes for entry-level trial among younger legal-age drinkers. Duty-Free Shops channel growth reflects travel retail recovery and tourism-dependent purchasing patterns in airport and cruise environments.
EU regulations through EFSA and the EU Green Deal mandate granular ingredient sourcing disclosure and carbon footprint reduction in spirits packaging, reshaping production economics for exporters. US FDA labeling requirements and TTB certification standards govern market access for imported brandy, creating compliance thresholds that filter smaller producers. Stakeholders must monitor evolving sustainability mandates and on-premise recovery trajectories to calibrate inventory and positioning strategies.
Market Dynamics
EU Green Deal carbon accounting mandates and EFSA ingredient disclosure rules are compressing production economics while accelerating consolidation among exporters unable to absorb compliance costs.
Growth Catalysts
- Premium cocktail culture:Upscale metropolitan bars in France, Spain, and the United States are repositioning brandy from traditional after-dinner consumption into mixology-driven occasions. Bartender education programs expand trial among younger legal-age drinkers.
- REACH-compliant packaging innovation:European producers investing in lightweight glass and recycled content formats satisfy EU Green Deal targets while reducing freight costs. This unlocks duty-free channel expansion in airport and cruise retail environments.
- Cognac appellation concentration:France's tightly controlled geographic indication system limits supply growth, sustaining price premiums for aged expressions. Export volume to Asian markets reinforces the category's prestige positioning.
Market Restraints
- Input cost volatility:French oak barrel prices fluctuate with forestry harvest cycles and cooperage capacity constraints. Aged inventory requirements lock capital for decades, amplifying working capital pressure.
- Substitution threat from brown spirits:American whiskey and Japanese whisky capture share among younger consumers seeking heritage-authenticated alternatives. Retail shelf space reallocation favors faster-turning categories.
- Regulatory friction from TTB certification:United States import labeling requirements create compliance thresholds that filter smaller European producers. Certification timelines delay market entry by 12-18 months.
Strategic Opportunities
- Flavored brandy white space:Entry-level expressions targeting legal-age drinkers in Germany and the United Kingdom compete with ready-to-drink cocktails. Fruit-forward formulations reduce the barrier to trial.
- E-commerce direct-to-consumer channels:Regulatory relaxation in select United States states permits winery and distillery shipping. This bypasses traditional three-tier distribution economics.
- Sustainability certification differentiation:Organic vineyard conversion and carbon-neutral distillation processes align with CSRD reporting requirements. Early adopters capture premium positioning in Nordic markets.
Industry Challenges
- Master distiller talent scarcity:Generational succession gaps in French Cognac houses threaten institutional knowledge transfer. Compensation inflation for qualified cellar masters compresses margin.
- Aged stock forecasting complexity:Twenty-to-forty-year inventory commitments require demand prediction across volatile export cycles. Misalignment between production and consumption timing creates write-down risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brandy Market |
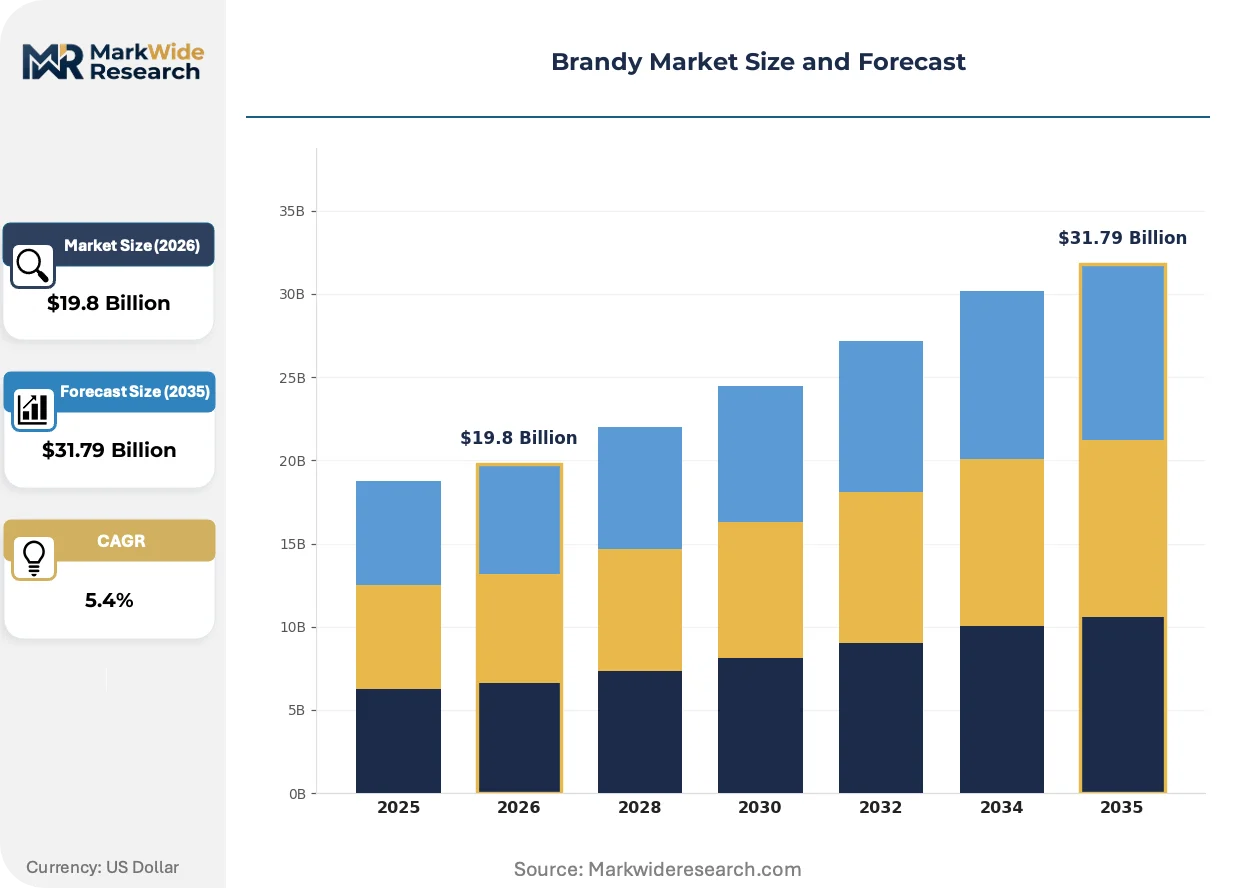
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Brandy, Flavored Brandy, Fruit Brandy, Vintage Brandy Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Duty-Free Shops End User: Bars, Restaurants, Retail Consumers, Nightclubs Price Tier: Premium, Mid-Range, Budget, Super-Premium |
| Companies Covered | E&J Brandy, Martell, Hennessy, Aznauri Brandy, Emperador, Old Admiral, Courrier Napoleon Brandy, Old Kenigsberg, Dreher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brandy Market Strategic Shifts & Innovations
Maturation science and digital traceability systems are compressing traditional production timelines while expanding provenance verification capabilities across the value chain.
Precision oak alternative technologies are modularizing the extraction process that traditionally required decades of cask aging. Mid-tier producers in Spain and California adopt stave inserts and micro-oxygenation systems to accelerate color and flavor development. This compresses the competitive moat previously held by heritage houses with deep aged stock reserves.
EU Green Deal sustainability reporting mandates through CSRD require granular carbon footprint disclosure across packaging, logistics, and agricultural inputs. French and Italian exporters redesign supply chains to reduce scope three emissions. Premium tier producers invest in on-site renewable distillation energy to maintain access to Nordic retail channels.
On-premise consumption patterns rotate toward experience-driven occasions in Tokyo, London, and New York cocktail bars. Bartender-created serves displace traditional neat pours. Hospitality procurement prioritizes versatile expressions that perform across stirred, shaken, and built applications rather than age-statement prestige bottles.
Brandy Market Segmentation
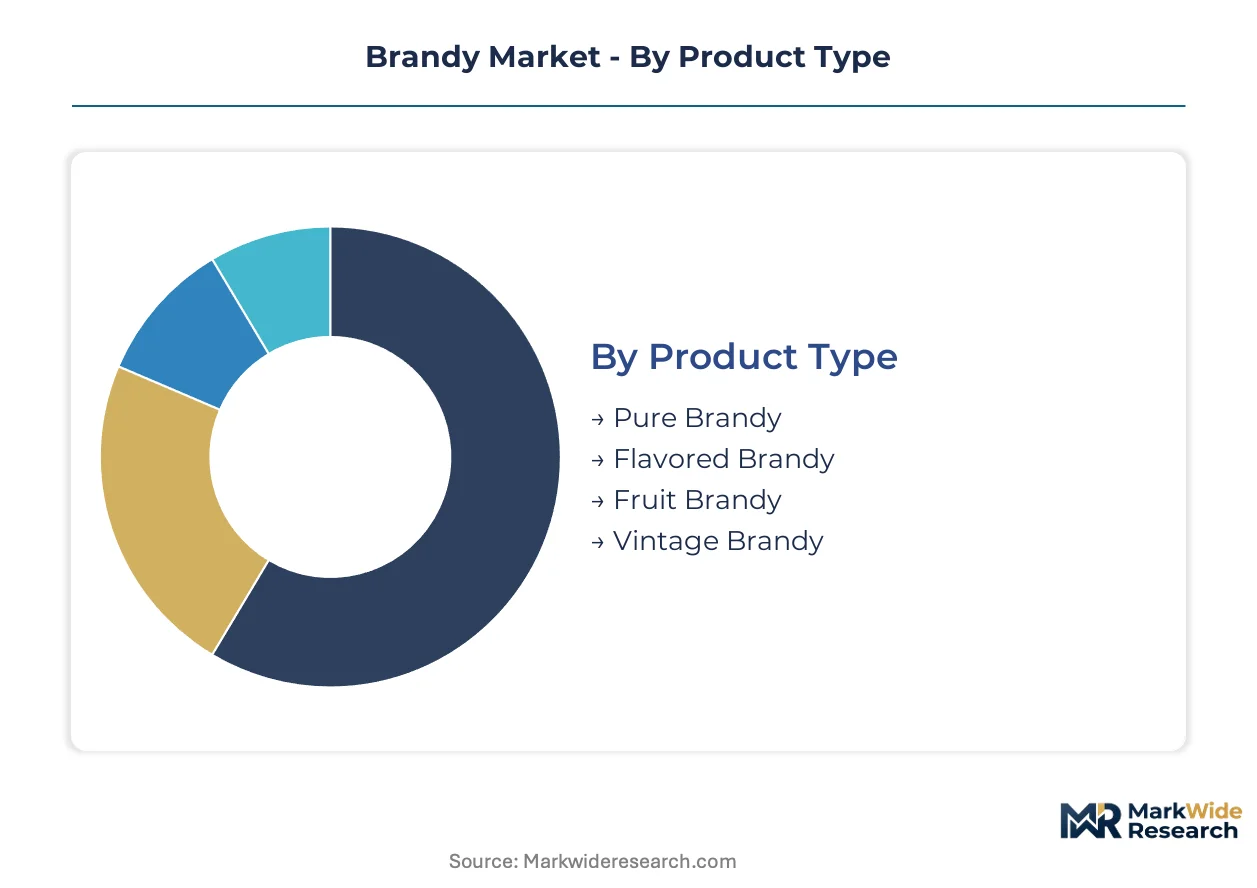
Brandy producers navigate distinct margin pools and capital requirements across product architectures. Segmentation reveals where aging infrastructure investments concentrate versus where flavor innovation drives trial.
Product Type:
Pure Brandy commands the steepest production economics due to extended oak maturation requirements.
- Pure Brandy:Distilled from wine and aged in oak casks for minimum periods defined by appellation rules. Demand concentrates in French Cognac houses where century-old inventory sustains luxury positioning against American whiskey encroachment.
- Flavored Brandy:Base spirit infused with fruit, spice, or botanical extracts to reduce entry barriers for legal-age drinkers. Germany and United Kingdom retail channels show fastest expansion as flavored variants compete with ready-to-drink cocktails.
- Fruit Brandy:Distilled from fermented fruit mash rather than grape wine, common in Central European tradition.
- Vintage Brandy:Single-year distillation with declared harvest date, requiring precise cellar tracking.
Mature deployment sits with Pure Brandy. Newer deployment is concentrated in Flavored Brandy.
Distribution Channel:
Channel selection determines margin capture versus volume velocity tradeoffs.
- Duty-Free Shops:Airport and cruise retail environments where travel recovery concentrates purchasing. Asian tourism corridors sustain prestige-tier velocity for aged expressions.
- Online Retail:Direct-to-consumer shipping where regulatory relaxation in select United States states bypasses three-tier distribution. E-commerce climbs fastest among channels as logistics infrastructure matures.
- Supermarkets:Mass retail placement for accessible-tier volume.
- Specialty Stores:Curated selection emphasizing provenance storytelling.
Volume leadership rests with Supermarkets. Margin expansion concentrates in Duty-Free Shops.
End User:
Consumption occasion shapes product format and packaging requirements.
- Bars:Mixology-driven occasions in Tokyo, London, and New York where bartender education programs expand trial. Versatile expressions perform across stirred, shaken, and built applications.
- Restaurants:After-dinner service and culinary pairing where age-statement bottles signal occasion significance.
- Retail Consumers:At-home sipping and gifting where packaging aesthetics influence selection.
- Nightclubs:Bottle service environments emphasizing brand visibility and pour efficiency.
Traditional volume centers on Retail Consumers. Experience-driven growth concentrates in Bars.
Price Tier:
Price architecture reflects production time intensity and scarcity positioning.
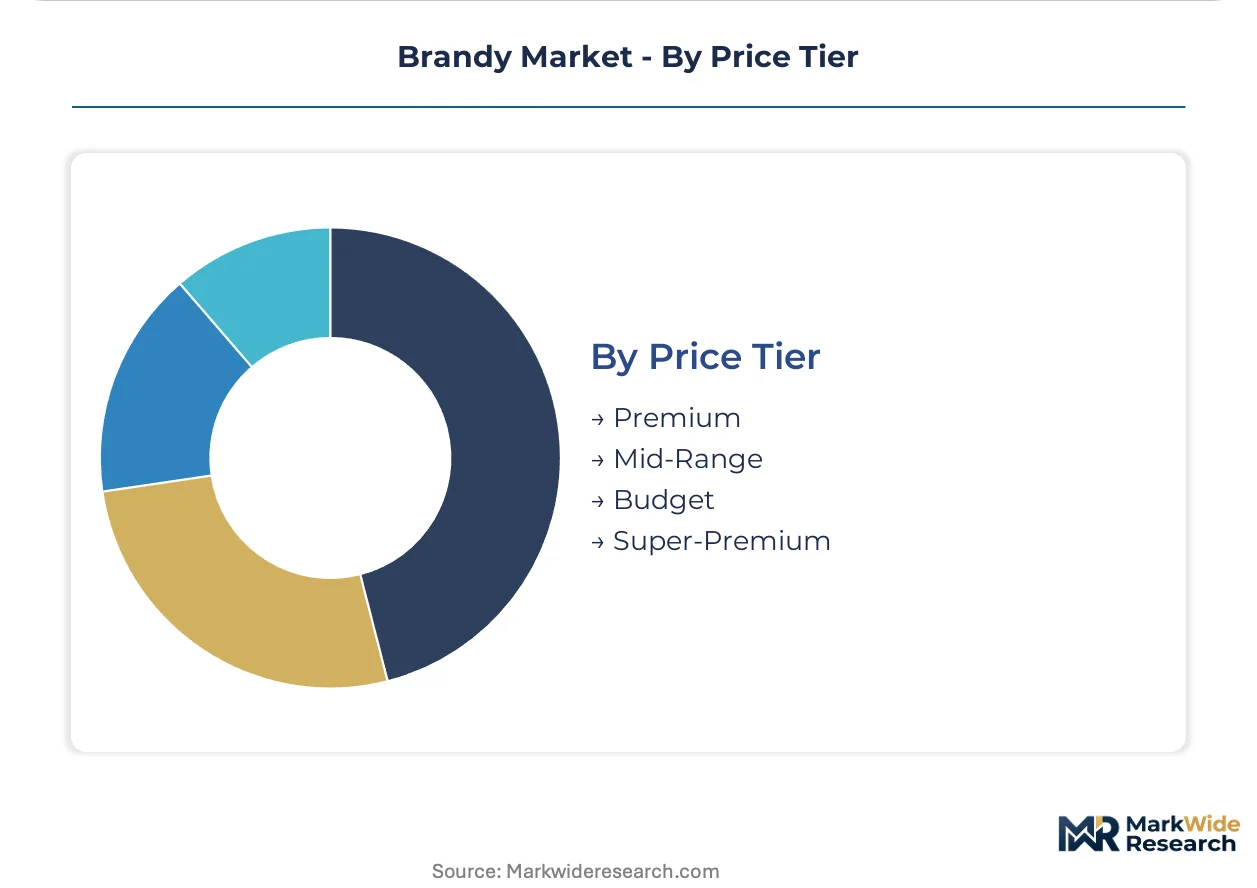
- Super-Premium:Extended aging and limited release frameworks commanding highest per-liter economics. French appellation constraints on supply growth reinforce price premiums.
- Premium:Aged expressions with verified provenance targeting metropolitan hospitality procurement.
- Mid-Range:Volume positioning for established brand households.
- Budget:Entry-level pricing for price-sensitive trial.
Capital deployment concentrates in Super-Premium. Volume scaling rests with Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Cognac appellation zone anchors global prestige-tier production through tightly controlled geographic indication rules that limit supply expansion and sustain price premiums.
France
Metropolitan cocktail bars in Paris and Lyon drive mixology-driven consumption away from traditional after-dinner sipping. EFSA ingredient disclosure mandates under EU Green Deal frameworks reshape export documentation requirements for Cognac and Armagnac houses. The Charente-Maritime cluster concentrates century-old aging inventory that sustains luxury positioning against American whiskey encroachment.
United States
TTB certification timelines create twelve-to-eighteen-month entry delays that filter smaller European exporters from premium retail placement. FDA labeling requirements govern spirits market access with granular alcohol content and origin disclosure standards. California and New York Metro hospitality procurement prioritizes versatile brandy expressions for stirred and shaken applications over age-statement bottles.
Germany
Flavored brandy variants compete with ready-to-drink cocktails for legal-age drinker trial in Berlin and Munich retail channels. REACH-compliant packaging investments satisfy EU carbon accounting mandates while reducing freight costs for exporters. The Baden-Württemberg region hosts specialized cooperage capacity serving Central European fruit brandy traditions.
Spain
Precision oak alternative technologies accelerate color and flavor development for mid-tier producers in Jerez and Penedès wine regions. CSRD sustainability reporting requirements drive granular carbon footprint disclosure across packaging and logistics operations. Barcelona's metropolitan bars anchor experience-driven consumption rotation toward bartender-created serves.
Japan
Tokyo cocktail bars displace traditional neat pours with mixology-driven occasions that expand trial among younger legal-age drinkers. METI standards govern spirits import quality certification and labeling harmonization with domestic distribution requirements. The Osaka-Kobe corridor concentrates duty-free retail velocity for aged expressions targeting Asian tourism corridors.
Brandy Market Key Industry Players
Top-tier vendors anchor the super-premium tier, while accessible-tier specialists compete on volume velocity and retail shelf space. French Cognac houses control heritage-authenticated positioning through century-old inventory reserves that lock capital for decades. Strategic archetypes include appellation-limited prestige producers, flavored-variant innovators, and duty-free channel specialists. Competitive moves concentrate on bartender education programs and REACH-compliant packaging redesign for EU market access.
Within the heritage-authenticated tier, Hennessy and Martell exemplify appellation-limited production models that constrain supply growth. E&J Brandy occupies a position within the accessible-tier volume segment, competing on consistent retail placement rather than aging infrastructure depth. These three anchors represent divergent capital deployment strategies across the margin pool.
| Leading Market Players |
|---|
| E&J Brandy |
| Martell |
| Hennessy |
| Aznauri Brandy |
| Emperador |
| Old Admiral |
| Courrier Napoleon Brandy |
| Old Kenigsberg |
| Dreher |
| Others |
Cost & Logistics Intelligence
Captive aging infrastructure in French Cognac houses anchors both supply security and pricing power across the prestige tier. Century-old inventory commitments lock working capital for decades, creating a structural moat that spot-market producers cannot replicate.
Pricing Analysis
Spot premiums for aged stock compress against extended lead-time discounts for forward-contracted inventory. Three-tier pricing structure across super-premium, premium, and accessible levels separates appellation-authenticated expressions from accelerated-maturation alternatives. Cost compression in the mid-range intensifies as American whiskey and Japanese whisky capture retail shelf space. Budget-tier buyers in German and United Kingdom supermarkets exhibit highest price sensitivity, while super-premium hospitality procurement in Tokyo and New York shows relative inelasticity.
Supply Chain Analysis
EU Green Deal local-content mandates for sustainable packaging reshape sourcing decisions across French and Spanish exporters. Supply concentrates in France, Spain, and the United States, with French oak barrel cooperage and Charente-Maritime aging cellars forming critical nodes. Production draws from grape wine distillate, French oak staves, and recycled-content glass formats. Single-source vulnerability sits with Limousin and Tronçais forest cooperage capacity. Distribution runs through three-tier wholesale systems in the United States and bonded warehouse networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained. Appellation-limited Cognac production caps volume expansion, sustaining pricing power for incumbents with deep aged reserves.
For Market Incumbents: Deepen bartender education investments to defend on-premise placement against American whiskey substitution. Expand REACH-compliant lightweight glass capacity to satisfy EU Green Deal targets and reduce freight exposure. Prioritize cellar master succession programs to mitigate generational knowledge transfer gaps threatening institutional capability.
For New Entrants and Emerging Players: Flavored brandy trialists in Germany and the United Kingdom represent the most penetrable buyer archetype for white-space entry. E-commerce direct-to-consumer channels in select United States states bypass three-tier distribution economics. Target fruit-forward formulations competing with ready-to-drink cocktails for legal-age drinker acquisition.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by heritage houses seeking flavored-variant capability or geographic footprint expansion. Five-to-ten-year viability hinges on sustainability certification differentiation and aged stock forecasting precision. Watch EFSA ingredient disclosure enforcement intensity as inflection indicator for compliance cost absorption capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Bartender Education Program Expansion | Hennessy and Martell anchor mixology-driven trial conversion in metropolitan hospitality venues. |
| REACH-Compliant Packaging Redesign | Lightweight glass investments satisfy EU Green Deal carbon accounting mandates for Nordic market access. |
| Direct-to-Consumer E-Commerce Launch | Regulatory relaxation in select United States states unlocks bypass of traditional wholesale distribution tiers. |
| Organic Vineyard Conversion | CSRD-aligned carbon-neutral distillation processes capture premium positioning in sustainability-focused retail channels. |
| Precision Oak Alternative Technology Adoption | Spanish and California producers compress maturation timelines using stave inserts and micro-oxygenation systems. |
Research Approach
Independent corroboration across master distillers, hospitality procurement directors, and regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork engaged cellar masters at French Cognac houses, category buyers at United States distributors, and sustainability officers at Spanish exporters. Secondary validation drew from EFSA disclosure filings, EU Green Deal implementation guidance, TTB certification databases, and customs trade records. Bottom-up volume triangulation against top-down value estimates anchored the analytical framework.
Comparable historical reference periods spanning pre-pandemic through travel retail recovery phases anchored the forecast window. Segmentation modeling across product type, distribution channel, end user, and price tier captured demand heterogeneity. CAGRs derived from trend extrapolation calibrated against inventory cycle dynamics and export velocity patterns. Forecast inputs incorporated French oak barrel price cycles, cooperage capacity constraints, and bartender education program expansion rates.
Revisions become necessary when EFSA enforcement intensity escalates, TTB certification timelines extend materially, or aged stock misalignment triggers write-down events. Forecasts reflect documented assumptions regarding on-premise recovery trajectories and sustainability mandate adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Europe Alcoholic Beverage Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Herbal Distillates Market