
 Drinkware, Beverageware, and Barware Market | 2026-2036
Drinkware, Beverageware, and Barware Market Size, Share, and Industry Trends Forecast 2026-2036
Drinkware, Beverageware, and Barware Market Insights
REACH compliance is broadening the cost-of-entry calculus for imported glass and ceramic drinkware across European distribution channels. YETI leverages direct-to-consumer channel control to sustain premium positioning in insulated tumblers. Libbey Inc. anchors North American foodservice supply through dedicated manufacturing scale in glassware.
Drinkware, beverageware, and barware encompasses vessels engineered for liquid containment, typically fabricated from soda-lime glass, borosilicate, food-grade stainless steel, or high-temperature ceramics with thermal shock resistance thresholds between 120°C and 180°C, serving commercial hospitality, institutional foodservice, and residential consumption. Stainless steel tumblers occupy the fastest-expanding margin pool as outdoor recreation and commute culture elevate vacuum-insulated formats. Glassware retains structural dominance in formal dining and wine service where optical clarity and rim geometry define quality perception.
FDA food-contact substance regulations and California Proposition 65 chemical disclosure mandates govern material safety and labeling protocols for products entering US retail and hospitality channels. The EU F-Gas Regulation and national extended producer responsibility frameworks in Germany and France are reshaping material selection criteria and end-of-life obligations for reusable serviceware. Stakeholders must monitor evolving chemical restriction schedules and recyclability certification requirements to preserve market access across diverging regulatory jurisdictions.
Market Dynamics
Specialty coffee chains and craft cocktail venues are accelerating procurement cycles for premium barware, compressing traditional hospitality refurbishment timelines from five-year cycles to eighteen-month refresh schedules.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility frameworks in Germany and France are mandating reusable serviceware quotas for on-premise hospitality, forcing wholesale inventory replacement.
- Vacuum insulation technology:Double-wall stainless steel manufacturing advances are lowering unit costs for insulated tumblers, opening mass-market penetration in commuter and outdoor recreation segments.
- German hospitality refurbishment acceleration:Berlin and Munich hotel renovation permits rose sharply, driving demand for coordinated glassware and ceramic sets across boutique properties.
Market Restraints
- REACH compliance cost inflation:ECHA chemical restriction schedules for cadmium and lead in ceramic glazes are raising testing and certification burdens for imported drinkware entering European distribution.
- Soda-lime glass energy intensity:Natural gas price volatility at Italian and Polish furnace operations is compressing margins for standardized glassware production.
- Single-use plastic substitution ceiling:Paper and compostable alternatives for outdoor events are capturing low-occasion drinkware demand that reusable formats cannot economically serve.
Strategic Opportunities
- India institutional foodservice expansion:FSSAI-mandated food-grade material standards for railway and airport catering contracts are creating specification-driven procurement windows for stainless steel and borosilicate suppliers.
- Thermal shock resistance convergence:Borosilicate glass formulations meeting 180°C thresholds are unifying specialty coffee and molecular cocktail applications under single SKU lines.
- Direct-to-consumer channel control:Owned e-commerce platforms are enabling premium insulated tumbler brands to bypass wholesale margin compression and capture end-user data for product iteration.
Industry Challenges
- Multi-jurisdiction chemical disclosure alignment:FDA food-contact substance notifications and California Proposition 65 warning requirements operate on conflicting evidentiary standards, forcing parallel compliance documentation.
- Furnace capacity reconfiguration lag:Converting soda-lime production to borosilicate or opal glass requires eighteen-month thermal cycling protocols that strain working capital during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drinkware, Beverageware, and Barware Market |
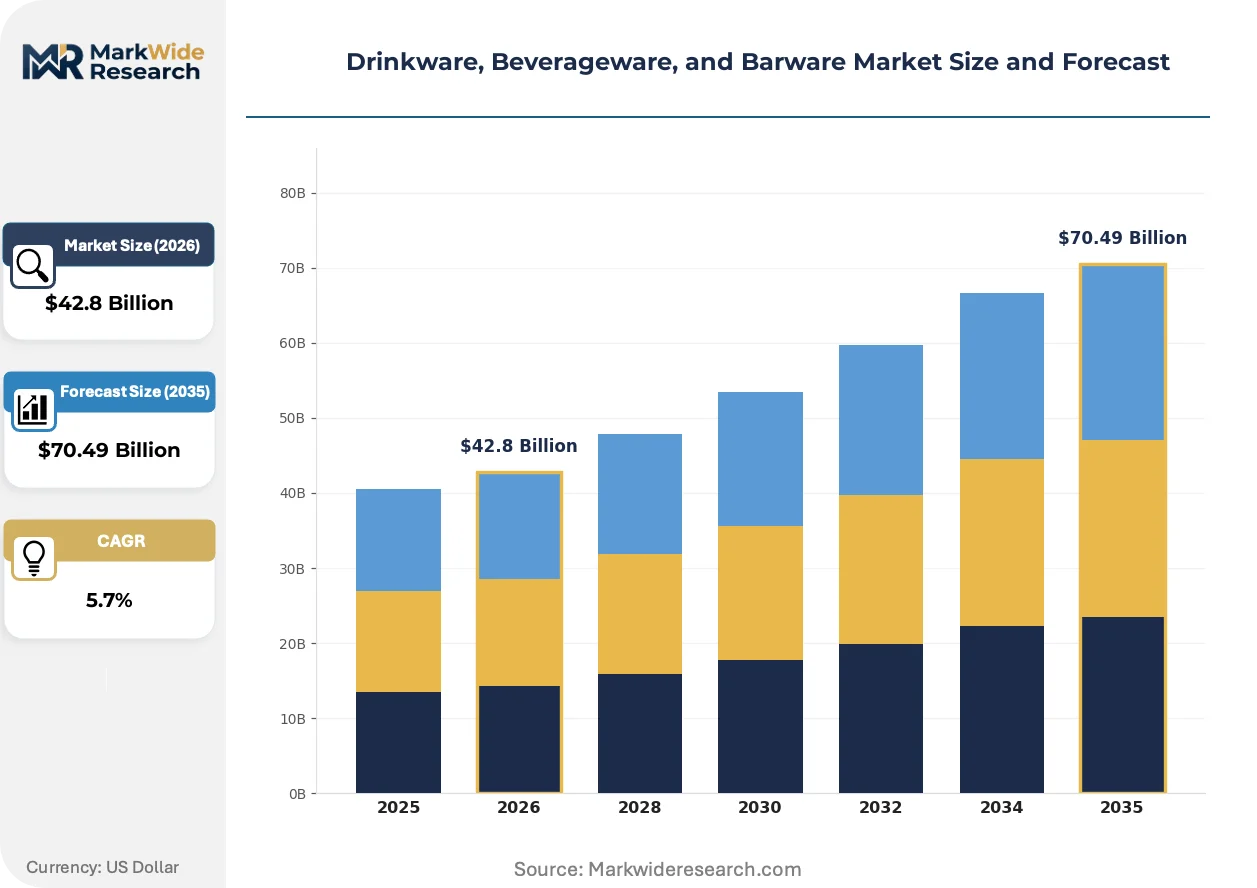
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cups, Mugs, Glasses, Tumblers Material: Plastic, Glass, Stainless Steel, Ceramic Use Case: Home, Restaurants, Cafes, Events Customer Type: Retail, Wholesale, Corporate, Hospitality |
| Companies Covered | Newell Brands, YETI, Hydro Flask, Tupperware Brands Corporation, Libbey Inc., Stanley, Corelle Brands, Bormioli Rocco, Lifetime Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drinkware, Beverageware, and Barware Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are jointly compressing traditional format boundaries, forcing convergence between thermal performance, optical clarity, and circular end-of-life design.
Advanced ceramic glazing is unifying thermal shock resistance with decorative surface durability. Specialty coffee roasters in Melbourne and Seoul are specifying these formulations for signature serveware that transitions from espresso service to high-temperature batch brewing. The technology is unifying previously separate SKU categories into single-product hospitality specifications.
REACH candidate list expansion is accelerating substitution of traditional crystal formulations. ECHA scrutiny of lead oxide content in decorative glassware is forcing Czech and Slovak manufacturers toward barium-based alternatives. Wine service programs in Paris and Vienna are responding by rewriting stemware specifications to exclude legacy crystal grades.
Buyer concentration among hospitality procurement consortia is compressing supplier negotiation leverage. Multi-property restaurant groups in London and New York are consolidating glassware and ceramic purchasing through centralized category managers. This pattern is most visible in the contract foodservice channel, where specification authority has migrated from individual chefs to corporate sustainability officers.
Drinkware, Beverageware, and Barware Market Segmentation
Drinkware procurement patterns diverge sharply across material specifications and channel economics, forcing suppliers to maintain parallel product architectures. Thermal performance, chemical compliance thresholds, and refurbishment cycle timing create distinct margin profiles within each segment axis.
Product Type:
Double-wall vacuum construction and rim geometry specifications differentiate competitive positioning across liquid containment formats.
- Cups:Handle-integrated designs in ceramic and borosilicate dominate institutional foodservice specifications. German railway catering contracts specify 180°C thermal shock thresholds for stackable cup formats.
- Mugs:Vacuum-insulated stainless steel variants with copper-lined cores are gaining share fastest in commuter and remote work segments. Melbourne specialty coffee roasters specify these for signature serveware programs.
- Glasses:Soda-lime and borosilicate formulations serve distinct optical clarity requirements in wine service and craft cocktail applications.
- Tumblers:Stemless wine and rocks formats in lead-free crystal alternatives are displacing traditional stemware in casual dining refurbishment cycles.
Mature deployment sits with Glasses. Newer deployment is concentrated in Mugs.
Material:
Cost tier alignment with end-use durability requirements determines specification authority in procurement decisions.
- Plastic:Tritan copolyester and polypropylene formats serve high-turnover event and outdoor applications where loss rates exceed economic recovery thresholds for reusable alternatives.
- Glass:Soda-lime dominates standardized hospitality procurement through Italian and Polish furnace scale. Borosilicate commands premium positioning in specialty coffee and molecular cocktail service.
- Stainless Steel:Food-grade 18/8 and 18/10 compositions with electropolished interiors are displacing ceramic in institutional foodservice contracts. FSSAI-mandated standards for Indian railway catering are accelerating specification migration.
- Ceramic:Advanced glazing formulations unifying thermal shock resistance with decorative durability are consolidating previously separate SKU categories into single-product hospitality specifications.
Volume concentration favors Glass at the commodity tier. Margin expansion is steepest in Stainless Steel.
Use Case:
Refurbishment cycle timing and specification authority migration reshape demand concentration across consumption contexts.
- Home:Direct-to-consumer channel control enables premium insulated tumbler brands to bypass wholesale margin compression and capture end-user data for product iteration.
- Restaurants:Multi-property groups in London and New York are consolidating glassware and ceramic purchasing through centralized category managers, compressing supplier negotiation leverage.
- Cafes:Specialty coffee chains are accelerating procurement cycles for premium barware, compressing traditional hospitality refurbishment timelines from five-year cycles to eighteen-month refresh schedules.
- Events:Paper and compostable alternatives are capturing low-occasion drinkware demand that reusable formats cannot economically serve.
Procurement centralization is most advanced in Restaurants. Specification autonomy persists in Cafes.
Customer Type:
Channel economics and inventory risk allocation determine margin capture and working capital intensity.
- Retail:Shelf space constraints and seasonal inventory risk favor diversified material portfolios with rapid SKU rotation capabilities.
- Wholesale:Extended producer responsibility frameworks in Germany and France are mandating reusable serviceware quotas for on-premise hospitality, forcing wholesale inventory replacement.
- Corporate:Branded merchandise programs specify insulated tumblers for employee retention and client gifting, with customization turnaround requirements compressing supplier lead times.
- Hospitality:Berlin and Munich hotel renovation permits are driving demand for coordinated glassware and ceramic sets across boutique properties.
Margin stability characterizes Wholesale. Volume volatility concentrates in Corporate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for ceramics and glassware manufacturing are concentrating export-oriented production capacity near Morbi and Firozabad, attracting multinational procurement offices seeking duty-advantaged supply origins.
United States
Specialty coffee chains in Seattle and Portland are compressing barware refresh cycles to eighteen-month intervals. FDA food-contact substance notifications govern material safety protocols for imported ceramic and glass vessels. Austin and Nashville hospitality clusters are driving vacuum-insulated tumbler specification migration across boutique hotel portfolios.
Germany
Berlin and Munich hotel renovation permits are accelerating demand for coordinated glassware and ceramic sets across boutique properties. Extended producer responsibility frameworks under the EU Green Deal mandate reusable serviceware quotas for on-premise hospitality. The North Rhine-Westphalia ceramics corridor is reconfiguring furnace operations to meet REACH compliance thresholds for cadmium-free glazes.
China
Yangtze River Delta glassware exporters are repositioning toward borosilicate formulations as REACH restrictions tighten European market access. GB standards for food-grade materials are converging with international certification requirements to preserve export competitiveness. The Shandong Peninsula furnace cluster is absorbing natural gas price volatility through scale consolidation.
India
FSSAI-mandated food-grade material standards for railway and airport catering contracts are creating specification-driven procurement windows. Morbi's ceramic tile and sanitaryware hub is extending glazing expertise into institutional drinkware formats. Gujarat's Special Economic Zones offer duty advantages for stainless steel and borosilicate exports to Middle Eastern hospitality markets.
Italy
Veneto and Lombardy furnace operations are grappling with natural gas price volatility compressing soda-lime glass margins. ECHA chemical restriction schedules are accelerating substitution of traditional crystal formulations in wine service stemware. The Tuscan ceramics district is advancing thermal shock-resistant glazing for specialty coffee roaster specifications.
Drinkware, Beverageware, and Barware Market Competitive Landscape
North American producers anchor the premium insulated tumbler tier; European specialists hold formal dining and wine service positioning through furnace-scale glassware. The vendor base organizes around three strategic archetypes: direct-to-consumer brands controlling channel economics, integrated manufacturers with captive furnace capacity, and private-label suppliers serving retail consolidation. Competitive moves concentrate on portfolio diversification into thermal-performance formats and geographic expansion through SEZ-advantaged production bases.
Among North American insulated vessel specialists, YETI and Hydro Flask exemplify direct-to-consumer channel control archetypes, while Libbey Inc. represents integrated manufacturing scale in soda-lime and borosilicate glassware. Stanley occupies a heritage-positioned tier bridging industrial utility and lifestyle premiumization. These anchors illustrate how competitive positioning diverges between thermal-performance innovation in commuter formats and optical-clarity dominance in formal hospitality procurement.
| Leading Market Players |
|---|
| Newell Brands |
| YETI |
| Hydro Flask |
| Tupperware Brands Corporation |
| Libbey Inc. |
| Stanley |
| Corelle Brands |
| Bormioli Rocco |
| Lifetime Brands |
| Others |
Pricing and Supply Chain Analysis
Natural gas furnace costs at Italian and Polish soda-lime glass operations cascade through three pricing tiers, with energy-intensive commodity glassware absorbing margin compression while borosilicate and vacuum-insulated formats command resilience through performance differentiation.
Pricing Analysis
Short lead-time premiums for coordinated hospitality glassware sets compress wholesale margins, while spot inventory of standardized tumblers trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified ceramic from legacy imports from uncertified commodity stock. Pricing pressure stems from ECHA chemical restriction schedules raising certification burdens for cadmium-free glazes. Boutique hotel procurement teams show lowest price sensitivity; event rental operators exhibit highest.
Supply Chain Analysis
Skilled furnace operator availability constrains output flexibility at Veneto and Lombardy soda-lime facilities, while Morbi ceramic glazing specialists face competing demand from tile exports. Raw material draws from German soda ash suppliers, Ukrainian silica sand deposits, and Chinese rare earth elements for vacuum insulation cores. Single-source vulnerability concentrates in Italian furnace capacity for optical-clarity wine stemware. Distribution runs through hospitality procurement consortia in London and New York, with direct-to-consumer platforms gaining share in insulated tumblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a material-transition phase as borosilicate glass and advanced ceramic glazing displace legacy soda-lime and lead-crystal formats across premium hospitality specifications.
For Market Incumbents: Hedge furnace capacity reconfiguration risk by maintaining dual-material production lines at North Rhine-Westphalia and Veneto sites, insulating against eighteen-month thermal cycling delays. Anchor procurement relationships with Berlin and Munich hotel renovation clusters through coordinated serveware set offerings. Prioritize REACH pre-certification investment to capture German wholesale replacement cycles ahead of compliance deadlines.
For New Entrants and Emerging Players: Indian railway and airport catering contractors represent the most penetrable buyer archetype, with FSSAI-mandated material standards creating specification-driven procurement windows. Target Gujarat Special Economic Zone production bases for duty-advantaged supply to Middle Eastern hospitality markets. Pursue direct-to-consumer channel control to bypass wholesale margin compression and capture end-user thermal performance preference data.
For Investors and Strategic Acquirers: ECHA candidate list expansion for lead oxide in decorative glassware is the leading indicator that Czech and Slovak crystal manufacturers face accelerated substitution timelines, compressing legacy asset valuations. Five-to-ten year viability favors integrated producers with captive borosilicate furnace capacity and established hospitality procurement consortia relationships. Watch Berlin hotel renovation permit velocity as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Borosilicate Furnace Conversion | REACH compliance at Italian and Polish facilities preserves European market access against ECHA restriction expansion. |
| Direct-to-Consumer Platform Launch | YETI and Hydro Flask channel control models demonstrate margin capture insulated from wholesale consolidation pressure. |
| India SEZ Manufacturing Footprint | Morbi and Firozabad duty advantages position exporters for Middle Eastern hospitality procurement growth. |
| Thermal Shock Resistance Certification | 180°C threshold documentation unifies specialty coffee and molecular cocktail applications under reduced SKU portfolios. |
| Hospitality Procurement Consortium Partnership | London and New York centralized category managers concentrate volume authority with preferred suppliers. |
Research Methodology
Independent corroboration across hospitality procurement directors, ceramic furnace operations managers, and regulatory compliance officers underwrites the qualitative findings. Primary interviews with category managers at multi-property restaurant groups, glazing specialists at Tuscan ceramics districts, and distribution heads at German wholesale channels combined with secondary validation from ECHA restriction schedules, FSSAI food-grade material notifications, and customs trade data for soda-lime and borosilicate glass imports. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Rate-of-change decomposition across the projection horizon separates volume growth from mix-shift effects and pricing evolution. Segmentation dimensions span material specification, use case context, and channel economics alongside thermal performance tier and chemical compliance grade. CAGRs derived from logistic adoption curves fitted to refurbishment cycle compression patterns and regulatory mandate implementation timelines. Forecast inputs incorporate natural gas price volatility assumptions at European furnace operations and FSSAI enforcement intensity for Indian institutional foodservice contracts.
Revisions become necessary when ECHA accelerates chemical restriction schedules, German extended producer responsibility quotas tighten beyond current frameworks, or Indian railway catering privatization alters procurement authority structures. Forecasts reflect documented assumptions about regulatory implementation pace and hospitality capital expenditure cyclicality. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Europe Alcoholic Beverage Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Germany Wine Coolers Market
Alcoholic Beverages
Dark Spirits Market