
 Commercial Tunnel Oven Market | 2026-2036
Commercial Tunnel Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Tunnel Oven Market Insights
The EU F-Gas Regulation is decoupling European equipment procurement from conventional gas-heated designs, compelling buyers to specify low-emission thermal systems. Middleby Corporation leverages its vertical integration in combustion technology to sustain a dominant position in hybrid oven configurations. Rational competes through precision steam-injection controls that anchor its premium positioning in high-throughput bakery segments.
A commercial tunnel oven is a continuous-belt thermal processing system engineered to move food products through controlled heating zones at speeds typically ranging from one to thirty meters per minute, achieving uniform bake profiles across high production volumes. Conveyor ovens occupy the largest installed base due to their versatility across bread, pastry, and prepared food lines, while impingement ovens represent the fastest-growing product category as quick-service chains demand accelerated cook times without quality degradation. Electric ovens command expanding share in urban installations where gas infrastructure restrictions and emissions ordinances reshape capital equipment decisions.
EMA equipment-safety directives, EPA commercial kitchen emissions standards, and ISO 22000 food-safety management frameworks collectively govern product certification, energy labeling, and hygiene design requirements across major supply destinations. These standards elevate engineering costs for new entrants while creating compliance-based differentiation for established manufacturers with in-house certification capabilities. Stakeholders must monitor evolving carbon-border adjustments and local building-code amendments that will determine which heating technologies qualify for institutional procurement contracts.
Market Dynamics
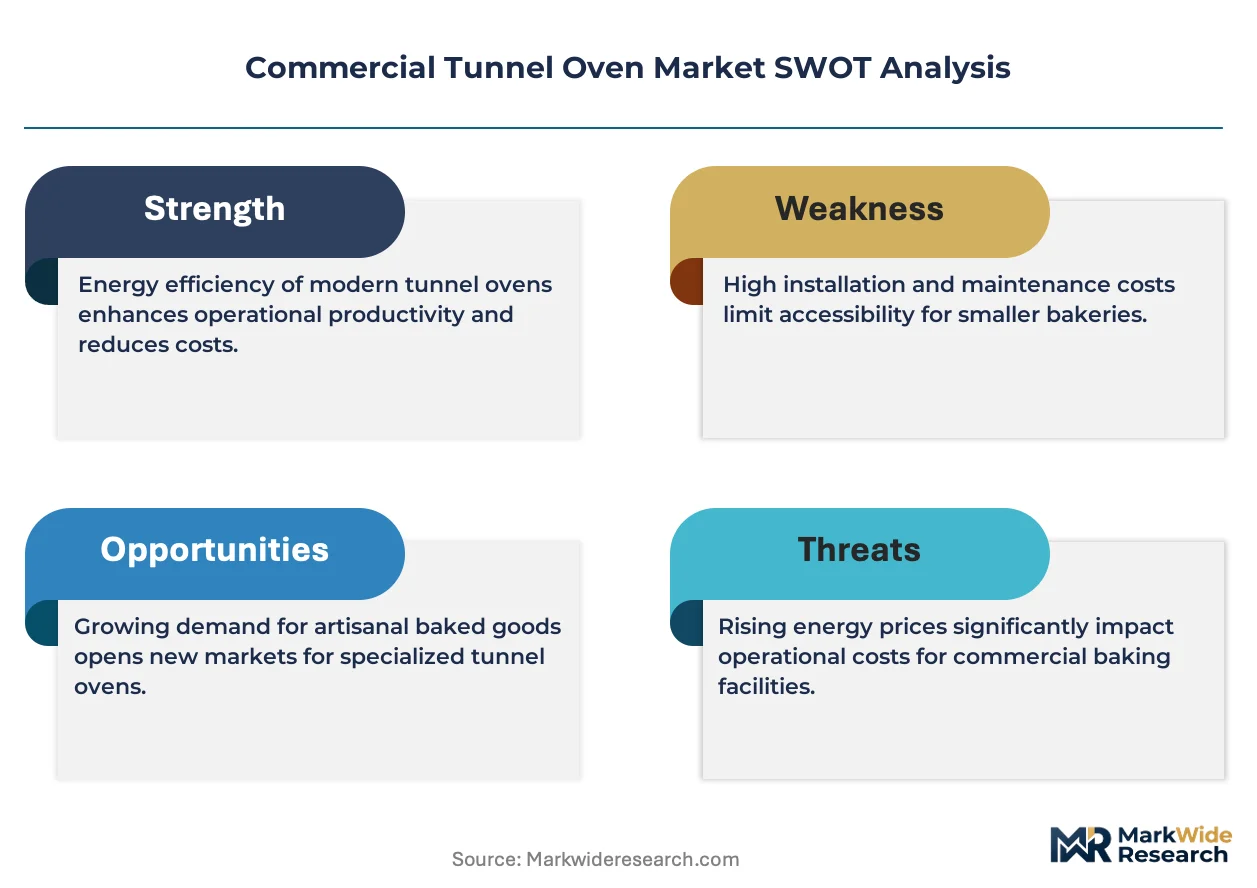
The EU F-Gas Regulation is systematically dismantling the installed base of gas-heated tunnel ovens across European artisan bakeries and industrial food processors, forcing capital replacement cycles toward electric and hybrid thermal systems before natural end-of-life.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants in thermal equipment design is mandating low-emission oven retrofits across German, French, and Italian baking clusters.
- Quick-service chain throughput demands:Impingement oven technology addresses accelerated cook-time requirements without product quality degradation in high-volume prepared food lines.
- Urban gas infrastructure restrictions:Building code amendments in dense metropolitan zones are compelling electric oven specifications for new commercial kitchen installations.
Market Restraints
- Stainless steel input volatility:Conveyor belt and chamber fabrication costs fluctuate with nickel and chromium price swings, compressing margin visibility for equipment fabricators.
- Combustion component supply concentration:Precision burner assemblies and heat exchangers concentrate among a limited supplier base in Northern Italy and Southern Germany.
- Electrical infrastructure retrofit requirements:Three-phase power upgrades in legacy bakery facilities impose capital barriers exceeding the oven unit cost itself.
Strategic Opportunities
- India commercial baking expansion:FSSAI hygiene mandates and organized retail growth are creating first-time automated oven demand in tier-two cities.
- Steam-injection precision convergence:Integration of IoT moisture sensors with traditional thermal controls enables real-time crust texture optimization for premium bread segments.
- Energy-as-a-service contracting:Utility-sponsored efficiency financing is displacing outright capital purchase in US institutional foodservice procurement.
Industry Challenges
- Thermal process engineering talent scarcity:Specialized expertise in zoned heat transfer optimization and airflow modeling is concentrating among retiring cohorts in European equipment manufacturers.
- ISO 22000 certification timeline compression:Hygiene design validation and third-party audit backlogs are extending equipment commissioning cycles by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Tunnel Oven Market |
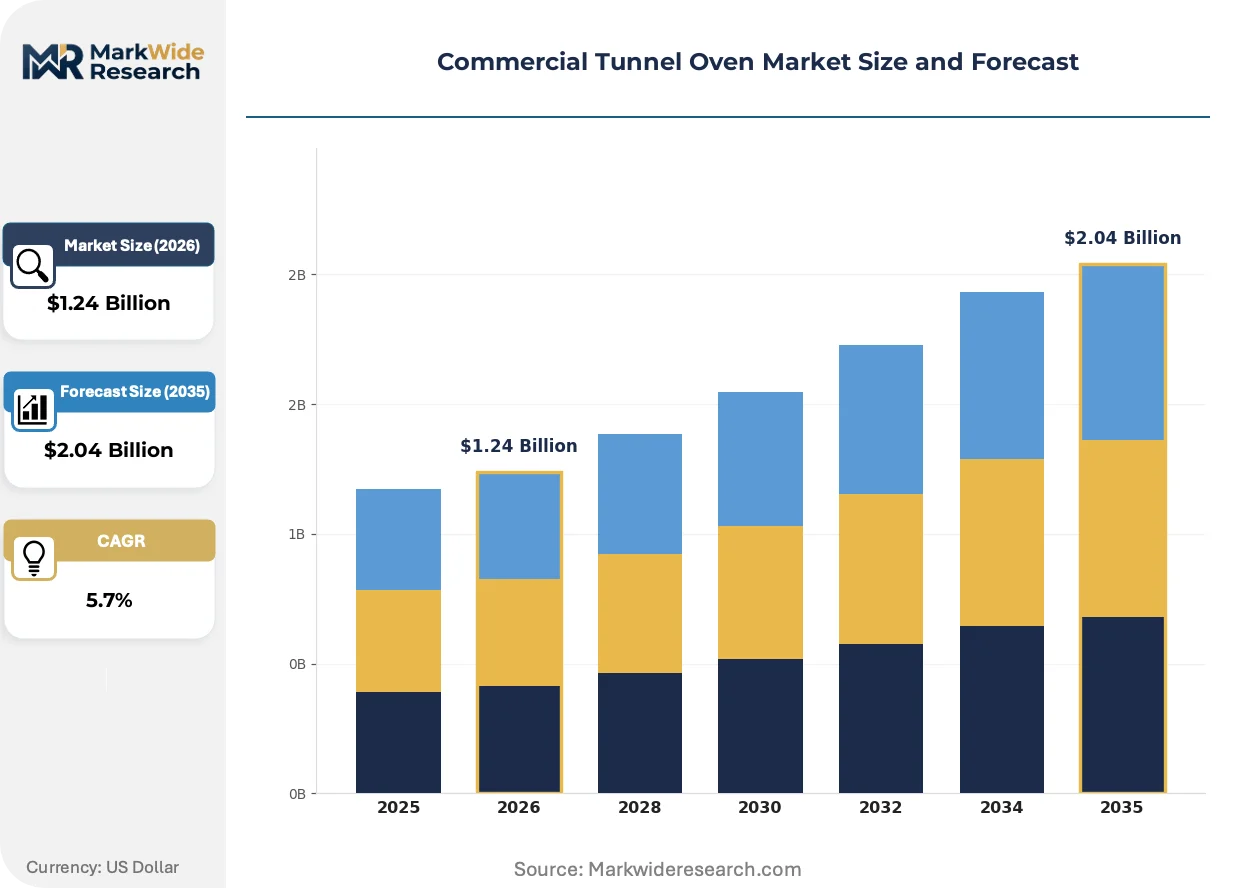
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.04 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Ovens, Rack Ovens, Impingement Ovens, Cart Ovens Application: Baking, Roasting, Drying, Toasting End User: Restaurants, Bakeries, Catering Services, Food Processing Technology: Electric Ovens, Gas Ovens, Hybrid Ovens, Infrared Ovens |
| Companies Covered | Middleby Corporation, Rational, Baker's Pride, Sveba Dahlen, BABBCO, Blodgett, Unox, Hobart, Cleveland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Tunnel Oven Market Trends and Innovations
Thermal processing architecture is pivoting from homogeneous heating zones toward modular, digitally controlled segments that adapt in real-time to product density and moisture content variations.
Induction heating modules are integrating into hybrid tunnel oven configurations to deliver precise, zone-specific thermal energy without the thermal lag inherent in gas combustion systems. Artisan bakeries in Denmark and the Netherlands are piloting these configurations to achieve consistent crust development across variable dough hydration levels. The technology is integrating predictive load-balancing algorithms that preemptively adjust power draw based on conveyor speed and product throughput, compressing energy waste during batch transitions.
REACH chemical restrictions and EU Ecodesign requirements are tightening material specifications for insulation, belt coatings, and electronic components used in commercial ovens. Manufacturers must now validate that flame-retardant additives and anti-corrosion treatments meet substance-of-very-high-concern screening thresholds. Electric oven product lines face the most intensive compliance burden, as their higher component counts trigger expanded documentation obligations under SCIP database requirements.
Food processors are consolidating vendor relationships around equipment suppliers offering integrated predictive maintenance platforms and remote diagnostics capabilities. The traditional model of reactive service contracting is yielding to multi-year performance agreements where uptime guarantees and energy efficiency benchmarks determine contract renewal. Quick-service chains in Germany and the United Kingdom are leading this consolidation, bundling oven procurement with digital monitoring subscriptions to minimize unplanned downtime in 24-hour production environments.
Commercial Tunnel Oven Market Segmentation
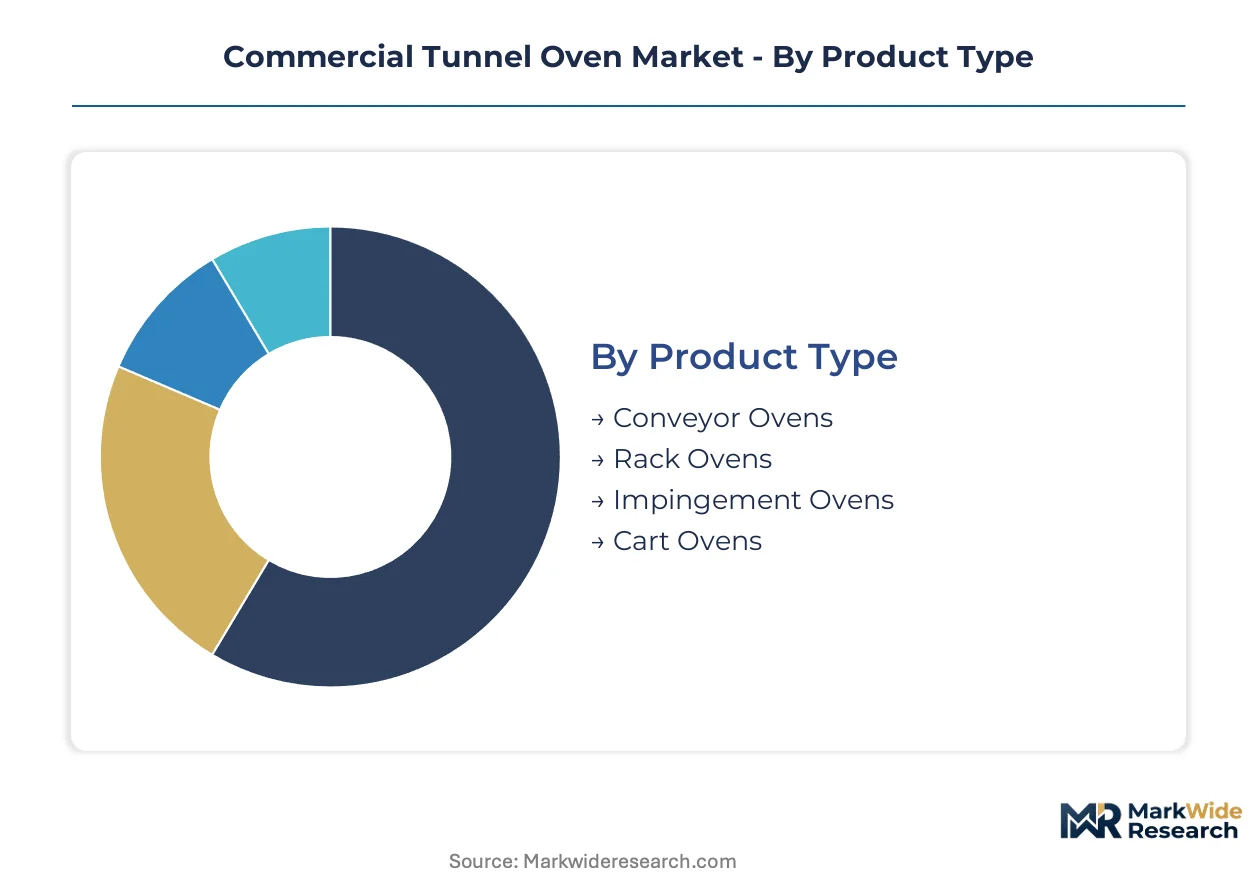
Tunnel oven procurement decisions hinge on thermal output requirements, facility infrastructure constraints, and compliance burdens that vary sharply across product configurations. Certification complexity and energy labeling obligations create divergent total-cost-of-ownership profiles that reshape buyer priorities within each segment category.
Product Type:
EMA equipment-safety directives and ISO 22000 hygiene validation impose differentiated engineering costs across oven architectures, with continuous-belt systems facing the most intensive third-party audit timelines.
- Conveyor Ovens:Continuous-belt thermal processing systems move products through zoned heating chambers at controlled speeds, achieving uniform bake profiles across high-volume bread and pastry lines. German industrial baking clusters drive replacement demand as aging gas-heated units face EU F-Gas Regulation phase-out deadlines. ISO 22000 certification for these systems extends commissioning cycles by four to eight months due to hygiene design validation backlogs.
- Impingement Ovens:High-velocity hot air jets accelerate heat transfer to product surfaces, delivering cook-time compression without quality degradation in quick-service prepared food applications. Quick-service chains in the United Kingdom and Germany specify these configurations for 24-hour production environments where throughput maximization determines equipment selection. Ecodesign compliance for impingement modules concentrates validation burden on airflow sensor and control electronics.
- Rack Ovens:Rotating tray systems accommodate batch variability in artisan bakery operations with lower capital thresholds than continuous configurations.
- Cart Ovens:Wheeled rack integration enables manual loading flexibility for catering services and small-batch food processors with intermittent production schedules.
Leading the category by volume: Conveyor Ovens. Growing fastest: Impingement Ovens.
Application:
Margin structures across thermal processing applications diverge based on temperature precision requirements and the cost of failure in finished product consistency.
- Baking:Controlled moisture extraction and crust development protocols for bread, pastry, and confectionery products demand zoned temperature management within two-degree tolerances. Artisan bakeries in Denmark and the Netherlands pilot induction-hybrid configurations to achieve consistent results across variable dough hydration levels. Steam-injection precision controls anchor premium positioning in this application segment.
- Roasting:Maillard reaction optimization for meat and vegetable products requires infrared and impingement technology integration to balance surface browning with internal temperature targets.
- Drying:Low-temperature moisture removal for ingredients and prepared foods concentrates demand in food processing facilities with energy-as-a-service contracting arrangements.
- Toasting:High-heat surface treatment for bread products and snack items occupies the lowest capital intensity tier within commercial oven applications.
Highest margin capture: Baking. Steepest expansion trajectory: Roasting.
End User:
Procurement authority and financing mechanisms fragment across customer types, with institutional foodservice gravitating toward performance-based contracting while independent operators favor outright capital purchase.
- Restaurants:Quick-service and full-service operators prioritize footprint efficiency and accelerated cook times to maximize kitchen throughput in high-rent urban locations. Urban gas infrastructure restrictions in dense metropolitan zones compel electric oven specifications for new installations. Utility-sponsored efficiency financing is displacing outright capital purchase in US institutional foodservice procurement for this segment.
- Food Processing:Industrial-scale thermal operations integrate tunnel ovens into continuous production lines with predictive maintenance platforms and remote diagnostics capabilities. Multi-year performance agreements with uptime guarantees and energy efficiency benchmarks determine vendor consolidation patterns in this segment.
- Bakeries:Artisan and industrial baking operations span the widest technology adoption spectrum from traditional gas-heated units to IoT-enabled hybrid systems.
- Catering Services:Event-based and contract catering operators favor cart and rack oven configurations for production flexibility across dispersed service locations.
Dominant procurement volume: Restaurants. Fastest contract structure innovation: Food Processing.
Technology:
Heating source selection increasingly correlates with facility electrical infrastructure capacity and local emissions ordinance stringency rather than operational preference alone.
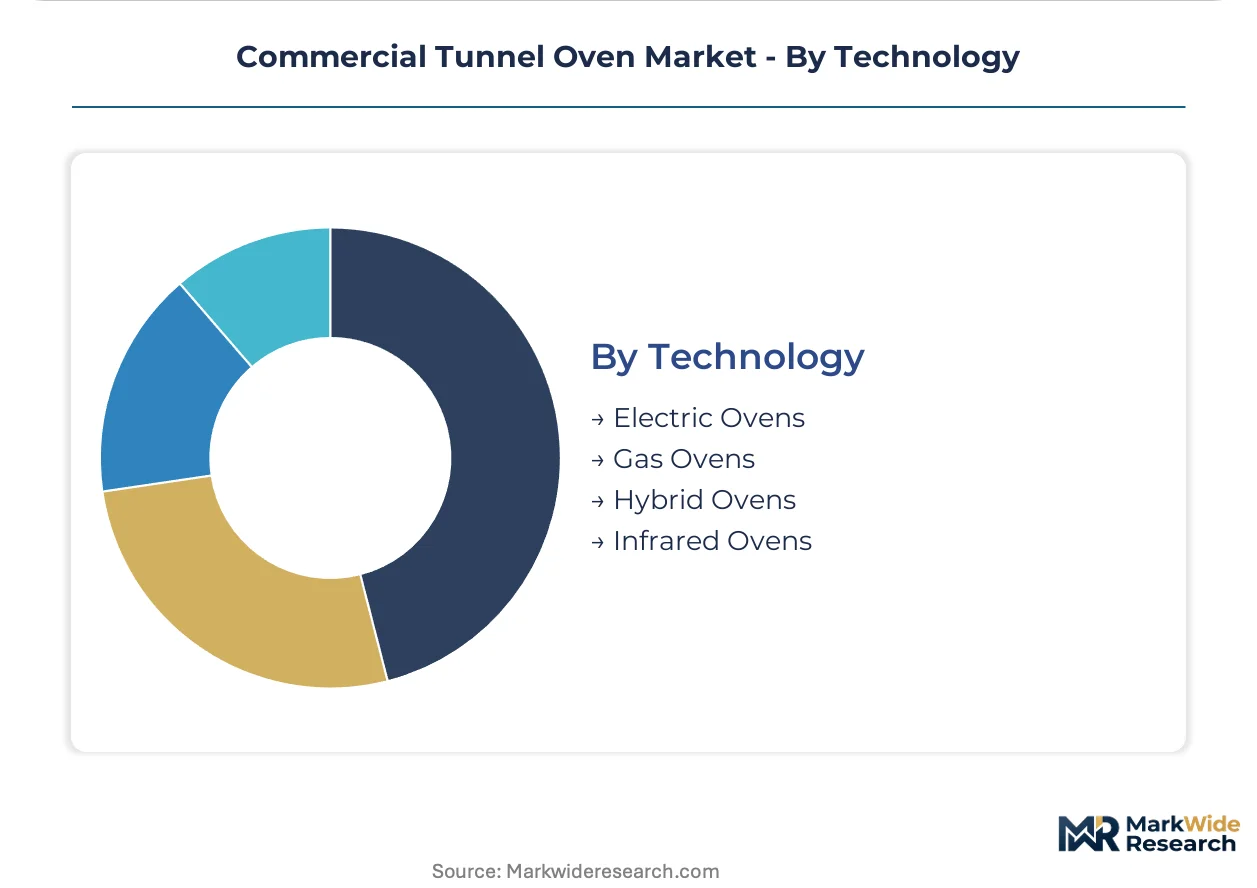
- Electric Ovens:Resistance and induction heating elements deliver precise zone-specific thermal energy without combustion byproducts, satisfying urban emissions restrictions and EU F-Gas Regulation compliance trajectories. Three-phase power upgrades in legacy bakery facilities impose capital barriers exceeding the oven unit cost itself. REACH chemical restrictions and SCIP database requirements intensify component documentation obligations for electric product lines.
- Hybrid Ovens:Dual-source configurations combine gas combustion for baseline heating with electric or infrared modules for precision zone control, bridging infrastructure transition periods. Combustion technology integration capabilities sustain competitive positioning for established manufacturers in this segment. Predictive load-balancing algorithms preemptively adjust power draw based on conveyor speed and product throughput.
- Gas Ovens:Conventional combustion heating faces systematic phase-out across European installations as F-Gas Regulation mandates accelerate replacement cycles before natural end-of-life.
- Infrared Ovens:Radiant heat transfer technology penetrates product surfaces for rapid browning applications in toasting and roasting operations with minimal preheat energy consumption.
Widest installed base: Electric Ovens. Gaining share fastest: Hybrid Ovens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Northern Italy and Southern Germany, while replacement demand concentrates in German industrial baking clusters and British quick-service chains. Consumption patterns diverge sharply between mature European markets facing regulatory phase-outs and emerging Asian markets building first-time automated capacity.
Germany
Industrial baking clusters in Lower Saxony and North Rhine-Westphalia drive replacement cycles for aging gas-heated conveyor systems. The EU F-Gas Regulation accelerates capital replacement before natural end-of-life, compelling specifications for electric and hybrid thermal configurations. Precision burner assembly suppliers in Southern Germany face order backlogs as fabricators retool production lines for low-emission designs.
United Kingdom
Quick-service chains specify impingement oven configurations for 24-hour production environments where throughput maximization determines equipment selection. EMA equipment-safety directives and evolving carbon-border adjustments reshape procurement qualification criteria. London and Birmingham foodservice hubs consolidate vendor relationships around suppliers offering integrated predictive maintenance platforms.
France
Artisan bakeries in Île-de-France and Auvergne-Rhône-Alpes pilot induction-hybrid configurations to achieve consistent crust development across variable dough hydration levels. REACH chemical restrictions tighten material specifications for insulation and belt coatings. Lyon-based equipment distributors report extended commissioning cycles due to ISO 22000 hygiene design validation backlogs.
United States
Institutional foodservice procurement gravitates toward utility-sponsored efficiency financing that displaces outright capital purchase. EPA commercial kitchen emissions standards and local building-code amendments in dense metropolitan zones compel electric oven specifications. Chicago and New York City bakery facilities face three-phase power upgrade barriers exceeding oven unit costs.
India
FSSAI hygiene mandates and organized retail growth create first-time automated oven demand in tier-two cities. The country's national food safety regulator tightens compliance timelines for commercial kitchen equipment imports. Maharashtra and Gujarat industrial zones attract fabrication joint ventures targeting domestic bakery automation needs.
Commercial Tunnel Oven Market Competitive Landscape
The competitive structure tilts toward combustion-technology specialists with captive control over precision burner assembly supply. Market concentration remains moderate, with established European manufacturers holding certification advantages and mid-scale regional fabricators competing on delivery speed. Two archetypes dominate: vertically integrated thermal engineering houses and modular-system integrators. Capacity expansion and strategic partnerships represent the primary competitive moves, as fabricators seek to secure component supply amid Northern Italian supplier concentration.
Among United States-based diversified foodservice equipment corporations, Middleby Corporation exemplifies the combustion-technology-integrated archetype, while Rational AG represents the precision-control specialist tier. Baker's Pride occupies a position within the mid-scale regional fabricator segment. These three anchors illustrate the competitive spectrum from upstream component control to modular system integration, with each archetype commanding distinct certification and financing advantages in procurement channels.
| Leading Market Players |
|---|
| Middleby Corporation |
| Rational |
| Baker's Pride |
| Sveba Dahlen |
| BABBCO |
| Blodgett |
| Unox |
| Hobart |
| Cleveland |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in Northern Italy anchor component supply for precision burner assemblies, transmitting stainless steel volatility directly into equipment pricing while constraining margin flexibility for downstream oven manufacturers.
Pricing Analysis
Margin tightening in standard conveyor configurations traces to nickel and chromium price swings that compress fabrication economics for belt and chamber suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified hybrid systems from basic electric units and legacy gas-heated equipment. Cost-down pressure on entry-tier ovens accelerates because tier-two cities in India demand first-time automation at capital thresholds below European retrofit cycles. Quick-service chains demonstrate lowest price sensitivity, prioritizing throughput guarantees and uptime commitments over unit economics.
Supply Chain Analysis
Refurbishment flows for aging gas-heated units create secondary component markets that partially offset raw material exposure for budget-conscious artisan bakeries. Equipment fabrication concentrates in Northern Italy and Southern Germany, drawing from precision-machined heat exchangers, specialized conveyor belting, and flame-retardant insulation materials. Single-source vulnerability concentrates in combustion component suppliers facing order backlogs from F-Gas Regulation-driven retooling. Distribution runs through Lyon-based equipment distributors and direct OEM relationships with industrial baking clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combustion technology integration has become the decisive vertical-integration lever as manufacturers race to captive control over precision burner assembly supply before regulatory phase-outs accelerate.
For Market Incumbents: Acquire specialized thermal engineering talent pools to offset retiring expertise in zoned heat transfer optimization. Secure backward integration into induction module supply chains before electric infrastructure mandates harden procurement specifications. ISO 22000 certification capabilities defend against emerging modular-system integrators threatening premium positioning. For New Entrants and Emerging Players: Begin with tier-two Indian cities where FSSAI hygiene mandates and organized retail expansion create first-time automated oven demand without incumbent replacement-cycle competition. Target utility-sponsored efficiency financing channels in US institutional foodservice to bypass capital purchase barriers. Position around IoT-enabled predictive maintenance platforms that quick-service chains increasingly bundle with equipment procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional fabricators in Maharashtra and Gujarat industrial zones where domestic bakery automation needs attract joint venture structures. Long-term viability hinges on compliance-advantaged manufacturers with in-house Ecodesign validation and SCIP database documentation capabilities. Monitor EU carbon-border adjustment implementation timelines as inflection indicators for electric oven specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Combustion Technology Integration | Captive control over precision burner supply secures hybrid oven positioning against F-Gas Regulation phase-outs. |
| Induction Module Manufacturing Scale-Up | In-house production of zone-specific heating elements reduces thermal lag and satisfies urban emissions restrictions. |
| IoT Predictive Maintenance Platform Launch | Real-time diagnostics capabilities anchor multi-year performance agreements with German quick-service chains. |
| ISO 22000 Certification Investment | Accelerated hygiene design validation compresses commissioning cycles against four-to-eight-month audit backlogs. |
| Joint Venture in Indian Industrial Zones | Maharashtra and Gujarat fabrication partnerships target FSSAI-mandated first-time automation demand in tier-two cities. |
Research Methodology
Trade association filings, customs and import records, and equipment registration databases formed the secondary backbone, cross-referenced with primary interviews involving thermal process engineers, bakery operations directors, OEM procurement teams, and aftermarket service heads. Bottom-up and top-down triangulation validated segmentation outputs across product configurations and heating technology categories.
Bottom-up modeling anchored volume estimates in named-country replacement cycles and first-time automation demand, while top-down constraints applied macroeconomic and regulatory boundary conditions across the projection horizon. Segmentation dimensions spanned product architecture, heating source, application thermal precision requirements, and end-user procurement authority. CAGRs derived from fitted growth curves incorporating EU F-Gas Regulation phase-out timelines, urban gas infrastructure restrictions, and energy-as-a-service financing penetration.
Underlying measurement precision varies by segment; electric and hybrid technology categories carry tighter precision than declining gas-heated configurations due to more visible regulatory trajectories. Forecasts reflect assumptions about compliance timeline adherence and infrastructure upgrade pacing. Practitioners should monitor REACH chemical restriction amendments and local building-code emissions ordinances for early signals of specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Sword Feeders Market