
 Craft Beer Market | 2026-2036
Craft Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Beer Market Intelligence
The bundling of beers into mixed-variety packs is shifting consumer purchasing behavior away from single-style bulk buys. This trend allows drinkers to sample multiple offerings, like IPAs and Lagers, in one purchase. Boston Beer Co leverages its diverse portfolio to create compelling seasonal variety packs. Sierra Nevada Brewing Co specializes in hop-forward ales and often features new experimental brews in its mixed packs, while D.G. Yuengling and Son Inc focuses on maintaining the brand strength of its core lager offerings.
Craft beer refers to beer produced by small, independent breweries using traditional or innovative brewing ingredients and methods. These breweries typically have an annual production of six million barrels of beer or less, emphasizing quality, flavor, and technique. While IPAs continue to lead product segments in volume, Lagers and Pilsners represent the fastest-growing styles due to their accessibility. In distribution, the Off-trade channel, including liquor stores and online retail, has gained significant share from the traditional On-trade channel of bars and pubs.
Regulatory frameworks governing alcohol distribution, labeling, and advertising create a complex operational environment. In the United States, the FDA enforces nutritional labeling and allergen declarations, while in Europe, bodies like the EFSA oversee ingredient safety. These regulations directly impact market access and packaging requirements for breweries. Brewers must now decide how to balance investments between expanding physical taproom footprints and scaling their direct-to-consumer e-commerce capabilities.
Market Dynamics
The craft beer market's primary dynamic is the tension between maintaining local production authenticity and achieving scalable distribution. This is driven by a consumer base that values unique, locally-sourced products while breweries seek growth through wider market access, particularly via direct-to-consumer channels.
Growth Catalysts
- Yeast & Fermentation Technology:Innovations in yeast propagation and automated fermentation control systems enable brewers to create a wider diversity of consistent, high-quality flavor profiles, attracting a broader consumer base seeking novel taste experiences.
- Metropolitan Demand Concentration:Consumer preference for unique, locally-produced beverages is highest in urban centers across the United States, Germany, and the United Kingdom, creating dense, high-value markets for craft breweries to target.
- Off-Trade Channel Expansion:The growth of specialized liquor stores and dedicated e-commerce platforms provides brewers with new, direct routes to market, reducing reliance on the traditional On-trade channel of bars and restaurants.
Market Restraints
- Input Cost Volatility:Breweries face significant margin pressure from fluctuating prices of critical raw materials, particularly specialty hops and premium malts, which are subject to agricultural and supply chain disruptions.
- Complex Distribution Regulations:The three-tier system in the United States and varied alcohol distribution laws across European Union member states create a complex and costly legal framework for brewers attempting to expand their geographic reach.
- Substitution from Adjacent Categories:Craft beer competes for consumer spending with a growing array of alternatives, including hard seltzers, ready-to-drink (RTD) cocktails, and sophisticated non-alcoholic beverages that appeal to similar demographics.
Strategic Opportunities
- Emerging Market Entry:There is significant whitespace for craft beer concepts in markets with a nascent but growing appreciation for artisanal beverages, such as in major cities in Brazil and South Korea.
- Digital Subscription Models:Direct-to-consumer subscription services and curated beer clubs offer a recurring revenue stream and a powerful channel for building brand loyalty while gathering valuable consumer data.
- Non-Alcoholic Craft Extensions:Developing high-quality, non-alcoholic versions of core beer styles, such as IPAs and Stouts, allows breweries to capture a health-conscious consumer segment without diluting their craft identity.
Industry Challenges
- Brewer and Technician Scarcity:A shortage of skilled brewers, cellar managers, and quality control technicians with expertise in microbiology and advanced brewing science limits the ability of breweries to scale production without compromising quality. *
- Capital for Scaling Operations:Transitioning from a local brewpub to a regional distribution brewery requires substantial capital investment in larger brewhouses, fermentation tanks, and automated canning or bottling lines.
- International Labeling Compliance:Brewers targeting multiple countries face the challenge of designing packaging that complies with the distinct nutritional labeling and allergen declaration rules of bodies like the US FDA and Europe's EFSA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Beer Market |
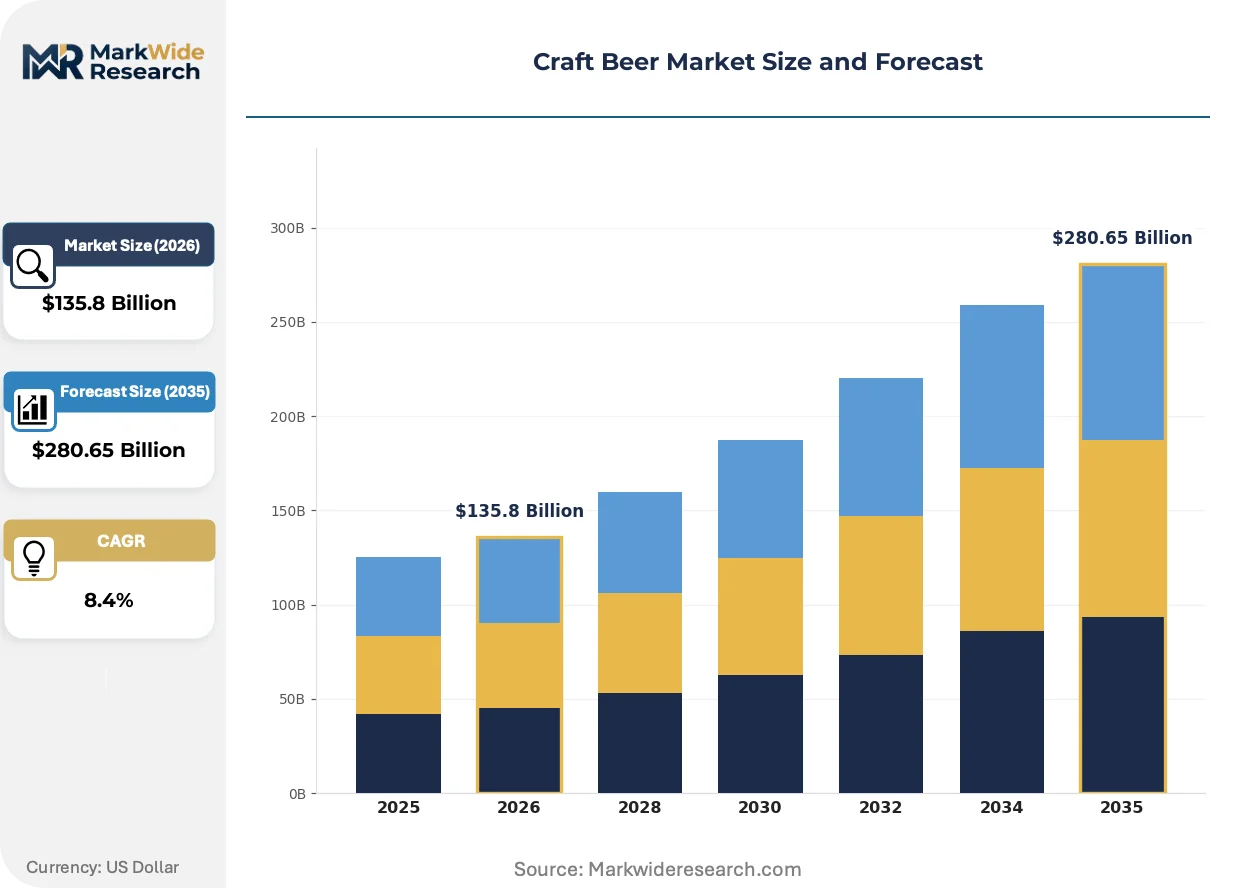
| Market Size in 2026 | $135.8 Billion |
| Market Size in 2035 | $280.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IPA, Stout, Lager, Ale, Pilsner, Porter Packaging Type: Bottle, Can, Keg, Growler, Crowler Distribution Channel: On-trade, Off-trade, Direct-to-Consumer, Online Retail, Specialty Stores End User: Bars & Pubs, Restaurants, Liquor Stores, Event Organizers, Home Brewers |
| Companies Covered | Tilray Beer Brands, Gambrinus, D.G. Yuengling and Son Inc, Athletic Brewing Company, Matt Brewing Co, Boston Beer Co, Duvel Moortgat USA, Brooklyn Brewery, Sierra Nevada Brewing Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Beer Market Strategic Shifts & Innovations
Innovation in the craft beer market centers on using technology to enhance both product differentiation and operational efficiency. These advancements allow brewers to meet evolving consumer tastes for novelty while navigating a complex production and distribution environment.
Advanced fermentation control systems utilize IoT sensors and software to monitor critical variables like temperature, pH, and specific gravity in real time. Mid-sized regional breweries are adopting these platforms to improve batch-to-batch consistency and reduce waste. This technology is unifying the artistic side of brewing with data-driven process control, enabling predictable and replicable flavor outcomes across diverse beer styles.
Evolving labeling mandates, including detailed nutritional and allergen declarations enforced by the US FDA and Europe's EFSA, are becoming more stringent. This development compels brewers to invest in laboratory analysis and more complex packaging designs, increasing overall compliance costs. Product segments like IPAs and Stouts, which often use a wide array of adjuncts, are most affected and require careful formulation review to satisfy international trade rules.
A pronounced behavioral shift sees consumers increasingly purchasing beer directly from breweries through e-commerce websites and taproom sales. This model disrupts the traditional On-trade channel of bars and pubs, which has experienced a corresponding decline in volume share. The trend is most visible in metropolitan areas throughout the United States and the United Kingdom, where local delivery infrastructure facilitates these direct transactions.
Craft Beer Market Segmentation
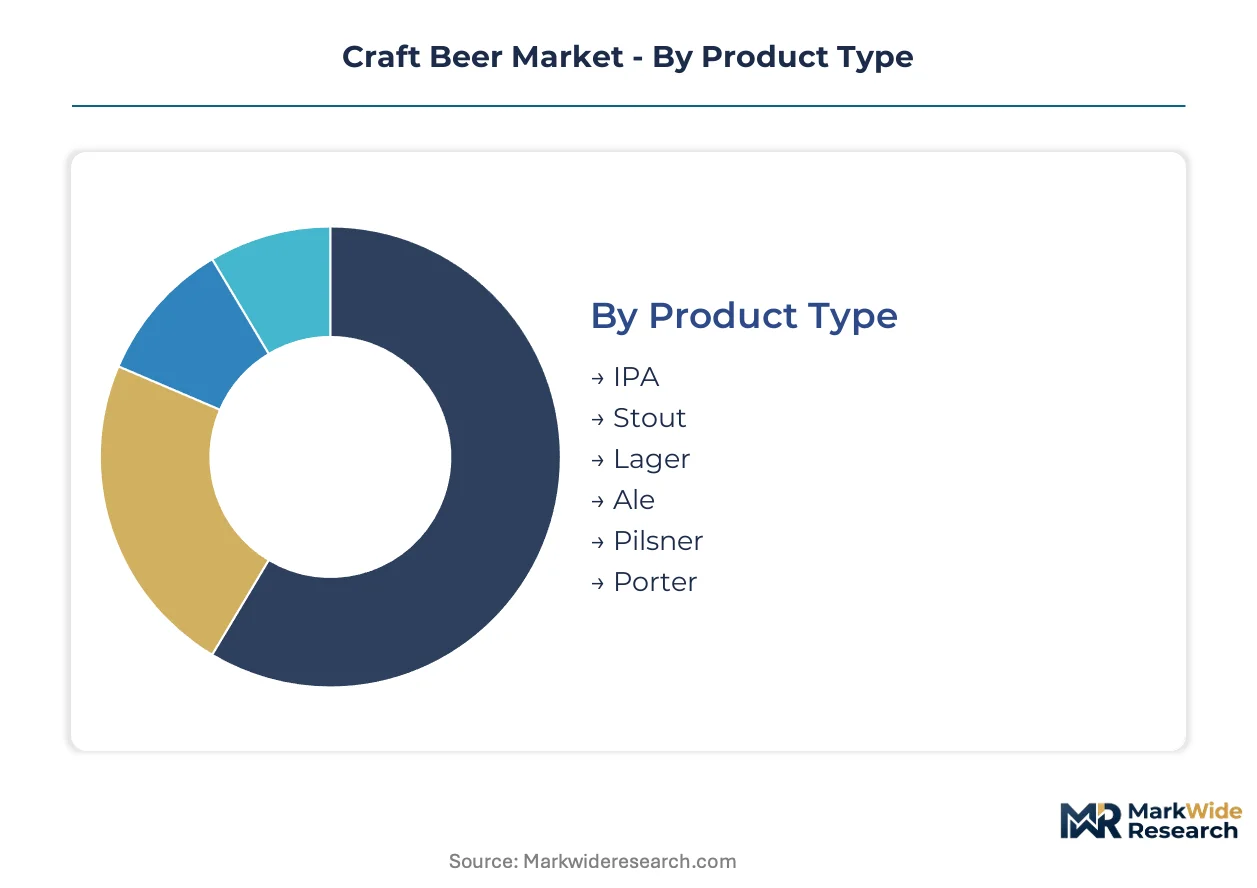
Segmentation helps define the diverse consumer preferences and operational strategies within the craft beer market. Understanding how products are categorized, packaged, distributed, and consumed provides clarity on market dynamics. This granular view assists breweries in tailoring their offerings and market approaches effectively.
Product Type:
The product type segmentation highlights the spectrum from highly customized, experimental brews to more standardized, widely accessible styles.
- IPA:India Pale Ale (IPA) features a prominent hop aroma and flavor, often showcasing citrus, pine, or tropical fruit notes from specialized hop varietals. This style sees high demand among adventurous drinkers seeking novel taste experiences in urban centers.
- Lager:Lager is fermented with bottom-fermenting yeast at colder temperatures, yielding a cleaner, crisper taste profile and lighter body. Its accessibility drives significant market expansion, particularly among consumers seeking sessionable and familiar beer options.
- Stout:Stout is a dark, top-fermented beer known for its roasted malt flavors, often featuring notes of coffee, chocolate, or caramel.
- Ale:Ale is a broad category of beer fermented with top-fermenting yeast at warmer temperatures, producing diverse flavor profiles.
- Pilsner:Pilsner is a pale lager style originating from the Czech Republic, characterized by its crisp, clean, and often hoppy taste.
- Porter:Porter is a dark beer style with a rich, malty flavor, typically exhibiting notes of chocolate, toffee, or roasted coffee.
Most installed capacity flows through IPA. Expansion is steepest in Lager.
Packaging Type:
Volume considerations heavily influence packaging choices, balancing consumer convenience with logistical efficiency and brand presentation.
- Can:Cans consist of lightweight aluminum, offering superior protection against light and oxygen, which preserves beer freshness and flavor. This format dominates the off-trade channel due to its portability and recyclability, appealing to environmentally conscious consumers.
- Bottle:Bottles, typically made of glass, provide a traditional aesthetic and are often favored for premium or specialty craft beer offerings. They maintain strong retail presence, particularly in specialty stores where visual appeal and perceived quality are paramount.
- Keg:Kegs are large containers used for bulk distribution to bars, restaurants, and events, facilitating on-premise draft beer service.
- Growler:Growlers are reusable glass or ceramic containers filled directly from a tap, allowing consumers to take fresh draft beer home.
- Crowler:Crowlers are single-use aluminum cans sealed on-site at breweries, providing a portable, fresh-to-go option for consumers.
Distribution efficiency defines success in Can packaging, while Bottle packaging caters to immediate consumption.
Distribution Channel:
Customer access points vary significantly, from traditional hospitality venues to emerging digital storefronts, each catering to distinct purchasing behaviors.
- Off-trade:The Off-trade channel includes liquor stores, supermarkets, and convenience stores, where consumers purchase beer for consumption elsewhere. This channel has gained significant share, driven by consumer preference for at-home consumption and broader product selection.
- Direct-to-Consumer:Direct-to-Consumer (DTC) involves breweries selling directly to end-users via taprooms, brewery websites, or local delivery services. This channel fosters direct customer relationships and allows for higher margin capture, particularly in markets with local delivery infrastructure.
- On-trade:The On-trade channel encompasses bars, pubs, and restaurants where beer is consumed on-premise, offering a social and experiential drinking environment.
- Online Retail:Online retail platforms facilitate convenient beer purchases through e-commerce websites, providing extensive product choices delivered directly to consumers.
- Specialty Stores:Specialty stores focus on curated selections of craft beers, catering to connoisseurs and those seeking unique or limited-edition brews.
The landscape shifts towards Direct-to-Consumer for convenience, yet On-trade retains traditional market presence.
End User:
Application-specific consumption patterns dictate the diverse end-user segments, ranging from social gathering spots to personal brewing endeavors.
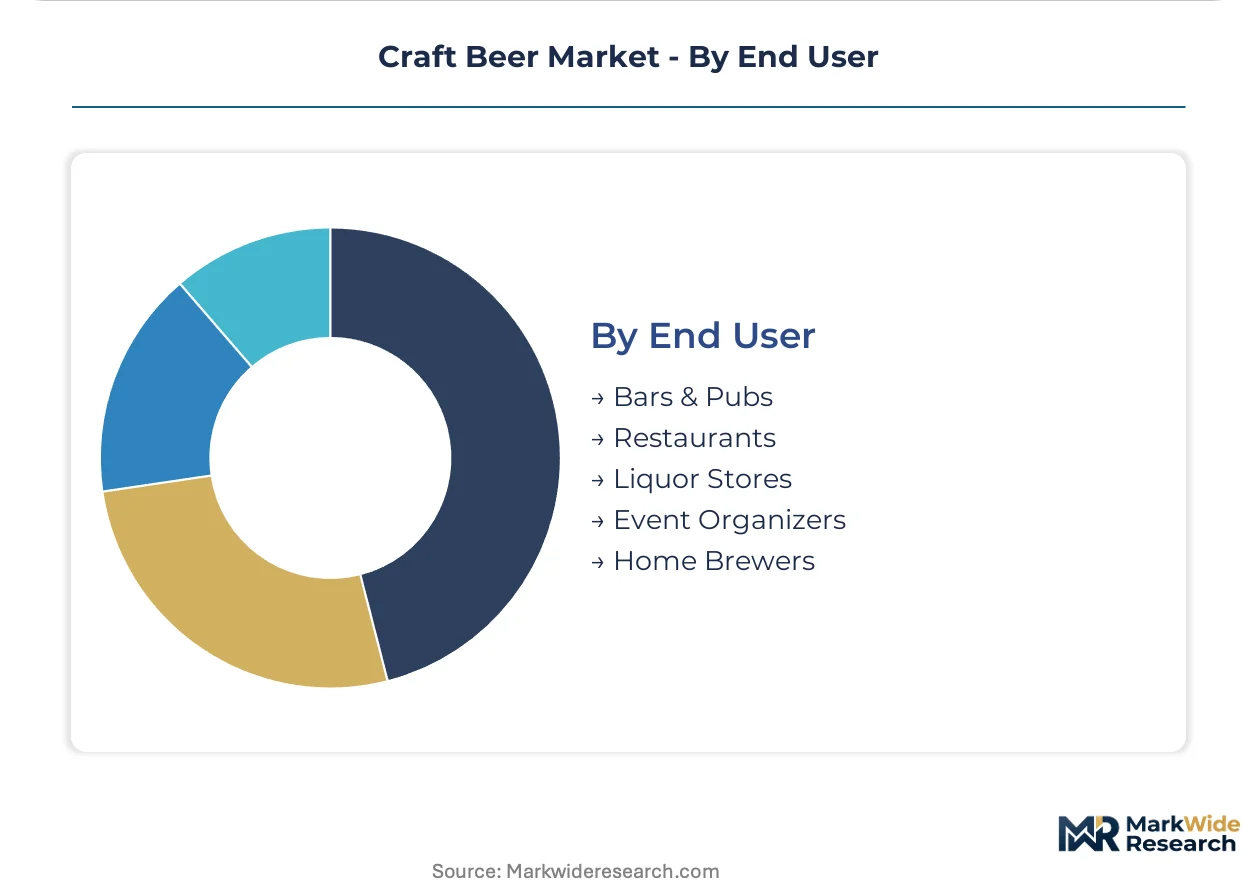
- Liquor Stores:Liquor Stores serve as primary retail points for off-premise consumption, offering a wide selection of craft beer brands and styles. They cater to consumers seeking variety and bulk purchases for at-home enjoyment.
- Bars & Pubs:Bars & Pubs represent traditional on-premise consumption venues, providing a social environment for beer enjoyment and immediate consumption. These venues remain crucial for brand visibility and introducing new craft offerings to consumers.
- Restaurants:Restaurants integrate craft beer into dining experiences, pairing specific brews with food menus to enhance customer satisfaction.
- Event Organizers:Event Organizers procure craft beer for festivals, concerts, and private functions, serving large groups in temporary settings.
- Home Brewers:Home Brewers are individuals who produce beer on a small scale for personal consumption, often experimenting with unique ingredients and techniques.
Consumer access points are diversifying, with Liquor Stores capturing impulse buys and Bars & Pubs driving experiential consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The craft beer industry traces its modern resurgence to pioneering efforts in the United States and Europe, where small-scale brewing traditions were revitalized. This foundational history established a consumer appreciation for diverse flavors and local production. Demand now concentrates in metropolitan areas globally, driving market expansion.
United States
Craft beer demand in the United States is fueled by a strong consumer preference for localized and innovative beverage options. The FDA enforces nutritional labeling and allergen declarations, impacting packaging requirements for domestic and international sales. The Pacific Northwest, especially cities like Portland, Oregon, showcases a high concentration of breweries driving experimental new styles.
Germany
German consumers increasingly seek diverse craft beer options, building upon a rich national brewing heritage. European Food Safety Authority (EFSA) regulations guide ingredient safety and production standards for all breweries. The Bavarian region, renowned for its traditional breweries, now experiences a surge in small craft operations introducing modern styles.
United Kingdom
The United Kingdom market sees strong demand for craft beer driven by its established pub culture and expanding direct-to-consumer channels. National alcohol duty regulations directly impact the operational costs and pricing strategies for British brewers. Metropolitan areas like London serve as key hubs where microbreweries thrive and consumer interest in local brews is highest.
Brazil
Brazil represents an emerging market with a nascent but growing appreciation for artisanal and unique craft beverages. ANVISA, the national health surveillance agency, enforces strict regulations on beverage production and labeling. Major urban centers such as São Paulo and Rio de Janeiro are witnessing significant growth in craft breweries and specialized retail outlets.
South Korea
South Korean consumers demonstrate an evolving preference for unique and high-quality craft beer experiences. The Ministry of Food and Drug Safety (MFDS) dictates rigorous safety and labeling standards for all alcoholic beverages. Seoul, as a major metropolitan hub, features a rapidly expanding craft beer scene, supported by local breweries and specialized bars.
Craft Beer Market Key Industry Players
The competitive structure tilts toward a blend of established regional players and numerous agile craft breweries. This market exhibits a tiered structure, from large-scale craft producers to localized microbreweries. Strategic archetypes include heritage brands focusing on core offerings, innovative brewers pushing flavor boundaries, and lifestyle brands targeting specific consumer segments. Market participants often pursue portfolio diversification and geographic expansion to capture broader consumer interest.
Within the diversified portfolio archetype, Boston Beer Co exemplifies a strategy of leveraging multiple brands to create compelling seasonal variety packs. This approach allows for broad market reach and caters to varied consumer preferences across product types. Sierra Nevada Brewing Co anchors the segment of hop-forward specialists, often featuring experimental brews in its mixed offerings and pushing flavor innovation. D.G. Yuengling and Son Inc occupies a position among heritage brands, maintaining strong brand recognition through its core lager products and emphasizing traditional appeal. These companies collectively shape the market's innovation trajectory and consumer purchasing behaviors.
| Leading Market Players |
|---|
| Tilray Beer Brands |
| Gambrinus |
| D.G. Yuengling and Son Inc |
| Athletic Brewing Company |
| Matt Brewing Co |
| Boston Beer Co |
| Duvel Moortgat USA |
| Brooklyn Brewery |
| Sierra Nevada Brewing Co |
| Others |
Cost & Logistics Intelligence
A distinct quality tier divergence exists between mass-produced lagers and artisanal craft brews, influencing both pricing strategies and ingredient sourcing. This bifurcation shapes market access and consumer expectations across the craft beer supply chain.
Pricing Analysis
Per-unit transactional pricing dominates the craft beer market, with significant premium-mid-economy pricing differentiation. Brand premium and unique flavor profiles drive higher pricing for specialty IPAs and limited-edition releases. Pricing pressure stems from input cost volatility, particularly for specialty hops and malts. Consumers seeking accessible lagers exhibit high price sensitivity, while adventurous urban drinkers show lower sensitivity to novel craft offerings.
Supply Chain Analysis
International labeling compliance, enforced by bodies like the US FDA and Europe's EFSA, directly influences packaging sourcing and ingredient declarations. Raw material sourcing draws from global specialty hop markets, primarily the Pacific Northwest (USA) and Germany, alongside premium malt suppliers from Europe. Commodity price volatility for these key agricultural inputs presents a significant structural risk. Distribution runs through a hybrid model, combining off-trade retail with expanding direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The craft beer market functions as a regulatory compounder, with evolving nutritional labeling mandates from the US FDA and Europe's EFSA driving innovation in product formulation. These regulations necessitate clear strategic responses from market participants.
For Market Incumbents: Deploy portfolio diversification to counter substitution from adjacent categories like hard seltzers. Expand physical taproom footprints while scaling direct-to-consumer e-commerce capabilities to maintain market share. Investment in advanced fermentation control technology enhances consistency and allows for broader flavor experimentation. This dual approach mitigates the threat of new entrants specializing in niche product segments.
For New Entrants and Emerging Players: A significant price-point gap exists between established premium craft offerings and more accessible, sessionable styles. Focus on developing high-quality, non-alcoholic craft extensions to capture health-conscious consumers. Target emerging markets like Brazil and South Korea, where appreciation for artisanal beverages is growing. Digital subscription models offer a direct go-to-market angle, building loyalty and recurring revenue streams.
For Investors and Strategic Acquirers: Consolidation pressure builds where smaller breweries lack capital for scaling operations and international labeling compliance. The market exhibits long-term viability over a five-to-ten-year window, driven by sustained consumer demand for unique flavors. Target acquisition archetypes include regional breweries with strong direct-to-consumer channels and innovative product portfolios. The signal to watch is the successful integration of advanced fermentation technology across mid-sized producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Brewers can capture higher margins and build strong customer relationships through e-commerce platforms. |
| Non-Alcoholic Product Development | Capturing health-conscious segments expands market reach without diluting the core craft beer identity. |
| Advanced Fermentation Technology | Enhances batch-to-batch consistency and enables diverse, replicable flavor outcomes for brewers. |
| Emerging Market Entry | Entering markets like Brazil and South Korea leverages nascent consumer appreciation for artisanal beverages. |
| Portfolio Diversification | Leveraging diverse brands allows companies like Boston Beer Co. to create compelling seasonal variety packs. |
Research Approach
Coverage spans the United States, Germany, and the United Kingdom, with primary inputs from each region. Analysts conducted interviews with brewery owners, cellar managers, and distribution channel partners. Secondary validation drew from customs/trade data, national alcohol duty reports, and food safety authority publications. This approach combined bottom-up market sizing with top-down triangulation for robust data integrity.
Market dimensions were modeled at a granular level by product type, packaging, distribution channel, and regional consumer preference across the analysis window. The analytical framework integrated historical consumption patterns with projected demographic shifts. Compound Annual Growth Rates were derived from a weighted average of segment-specific expansion rates. Brewery production capacity and regulatory changes served as key industry-specific forecast inputs.
Caveats apply where sudden shifts in input commodity prices or unforeseen regulatory changes could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Russia Tequila Market