
 Low-Alcohol Beer Market | 2026-2036
Low-Alcohol Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Alcohol Beer Market Outlook
EU organic certification for brewing inputs is collapsing the supplier base eligible for premium positioning, forcing smaller maltsters and hop brokers out of the value chain. Heineken leverages its European brewing infrastructure to dominate shelf space in controlled distribution channels. Athletic Brewing Company specializes in craft-forward flavor profiles that differentiate its portfolio from mass-market lagers.
Low-alcohol beer comprises fermented malt beverages with ethanol content typically below 2.5% ABV, produced through arrested fermentation, vacuum distillation, or reverse osmosis to preserve aromatic compounds while limiting alcohol formation. The product serves consumers seeking sensory ritual without intoxication, bridging social drinking occasions and wellness priorities. Alcohol-free beer now leads product type momentum as formulation chemistry improves taste parity, while online retail captures the fastest-growing distribution channel as direct-to-consumer subscription models bypass traditional three-tier systems. Health-conscious consumers anchor the consumer type segment, though fitness enthusiasts represent the emerging margin pool for functional additive variants.
FDA labeling oversight in the United States and EU F-Gas Regulation governing refrigeration emissions both shape production economics and cross-border compliance burdens for multinational brewers. REACH chemical safety protocols further constrain flavor additive portfolios available to European formulators. Stakeholders must monitor evolving national alcohol taxation thresholds that could reclassify low-alcohol products overnight and trigger reformulation cascades across existing SKUs.
Market Dynamics
Arrested fermentation and vacuum distillation technologies are compressing production costs while EU F-Gas Regulation and REACH protocols force simultaneous reformulation investments, creating divergent cost trajectories across European and North American manufacturing bases.
Growth Catalysts
- EU Alcohol Labeling Mandates:Tighter disclosure requirements across member states are accelerating consumer migration toward sub-2.5% ABV formats as drinkers pre-empt regulatory visibility.
- Fitness Enthusiast Segment:Post-workout social consumption rituals are expanding addressable demand beyond traditional abstention-driven purchase occasions.
- Reverse Osmosis:Improved membrane selectivity is preserving volatile aromatic compounds previously lost in dealcoholization, narrowing sensory gaps with full-strength equivalents.
Market Restraints
- Organic Malt Input Concentration:EU organic certification collapse has eliminated two-thirds of eligible small maltsters, forcing brewers toward consolidated premium suppliers in Germany and France.
- Flavor Additive Constraints:REACH chemical safety protocols restrict ester and hop oil portfolios available to European formulators, limiting taste-engineering degrees of freedom.
- Taxation Threshold Volatility:National alcohol duty bands in the United Kingdom and Germany sit at arbitrary ABV cutoffs that legislative revision could reclassify overnight.
Strategic Opportunities
- Direct-to-Consumer Subscription:Online retail bypasses three-tier distribution markups while capturing recurring revenue and consumption data for iterative formulation.
- Functional Additive Integration:Electrolyte and adaptogen fortification targets the fitness enthusiast margin pool with premium positioning distinct from mass-market lagers.
- German Pub Channel Conversion:Traditional on-premise accounts adapting to moderation trends represent underpenetrated volume within established beer-drinking culture.
Industry Challenges
- Flavor Chemist Scarcity:Formulation expertise spanning brewing science and sensory psychology remains concentrated at multinational R&D centers, constraining craft-scale innovation velocity.
- Cross-Border Compliance Burden:Divergent FDA and EU labeling oversight requires parallel SKU documentation, inflating regulatory affairs headcount for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Alcohol Beer Market |
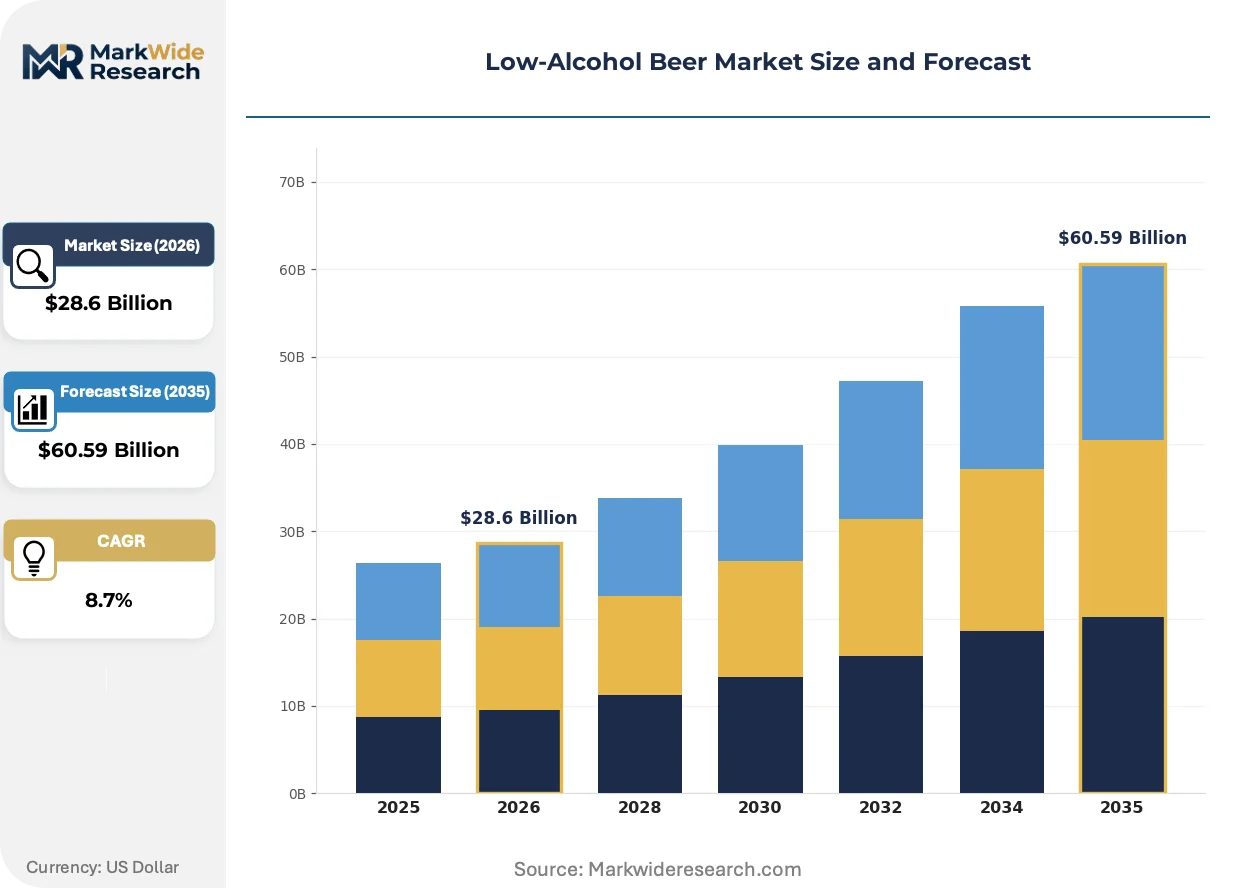
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Alcoholic, Light Beer, Low-Calorie Beer, Alcohol-Free Beer Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Consumer Type: Health-Conscious Consumers, Young Adults, Fitness Enthusiasts, Pregnant Women Flavor Profile: Citrus, Hoppy, Malty, Herbal |
| Companies Covered | Athletic Brewing Company, Asahi Breweries, Anheuser-Busch InBev, Kirin, Suntory Beer, Heineken, Molson Coors, BrewDog, Carlsberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Alcohol Beer Market Strategic Shifts
Dealcoholization technology maturation and regulatory chemistry constraints are simultaneously elevating production sophistication and compressing formulation freedom, forcing competitive differentiation toward process patenting rather than ingredient innovation.
Membrane-based selective filtration is decomposing the traditional tradeoff between alcohol removal and aromatic retention that previously forced mass-market producers toward dilution methods. Mid-sized craft brewers in the United Kingdom and Netherlands are adopting vacuum-assisted reverse osmosis at accelerated capital deployment cycles. This technological diffusion is compressing the quality-adjusted price premium that early movers commanded, forcing margin defense through proprietary yeast strain development.
REACH chemical safety protocols are systematically delisting synthetic flavor precursors from approved additive registers, constraining European formulators to natural extraction methods with higher batch variability. The industrial consequence is extended product development timelines and elevated quality control staffing. Small-batch craft producers in Belgium and Denmark are most affected, responding through backward integration into captive hop oil extraction facilities.
Pub operators in the United Kingdom are unbundling alcohol-free selections from residual category placement, creating dedicated tap handles and menu sections that signal categorical legitimacy. This channel-level reframing displaces the prior retail-dominated discovery model with on-premise trial environments. The behavioral shift is most visible in London and Manchester metropolitan clusters, where moderation-oriented demographic concentration supports dedicated alcohol-free draft rotations.
Low-Alcohol Beer Market Segmentation
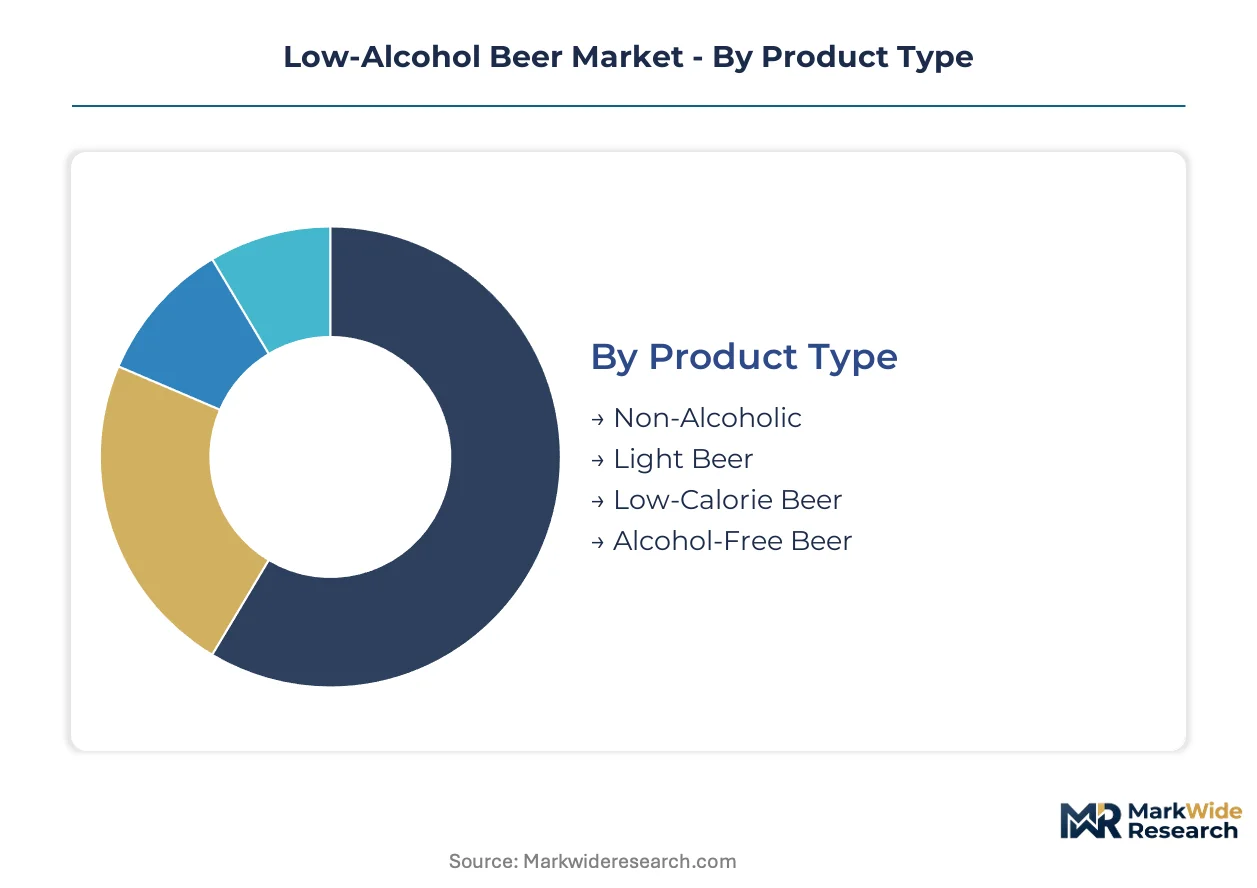
Low-alcohol beer segmentation reveals how regulatory thresholds and consumption rituals fragment addressable demand. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning across formulation and channel strategies.
Product Type:
EU F-Gas Regulation and REACH protocols differentiate production economics across alcohol-content bands, with sub-0.5% ABV formats facing distinct additive constraints versus higher-threshold light beers.
- Alcohol-Free Beer:Formulated below 0.5% ABV through vacuum distillation or reverse osmosis, this segment preserves volatile aromatic compounds previously lost to thermal methods. German and Dutch brewers concentrate capacity here as ECHA oversight tightens on synthetic flavor precursors.
- Light Beer:Typically 2.5-3.5% ABV with reduced caloric density, this format navigates arbitrary national taxation thresholds in the United Kingdom and Germany that legislative revision could reclassify overnight. British pub operators are expanding dedicated tap handles for these mid-ABV options.
- Non-Alcoholic:Interchangeably marketed with alcohol-free but often spanning 0.0-0.5% ABV depending on jurisdiction.
- Low-Calorie Beer:Prioritizes energy reduction over ABV minimization, attracting weight-management consumers rather than abstention-driven purchasers.
Alcohol-free beer handles the majority of throughput; alcohol-free beer is gaining share fastest as formulation chemistry achieves taste parity with full-strength equivalents.
Distribution Channel:
Channel cost structures diverge sharply where three-tier distribution markups collide with direct-to-consumer subscription economics and refrigerated supply chain requirements.
- Online Retail:Subscription models bypass wholesale markups while capturing recurring revenue and consumption data for iterative formulation. This channel compresses working capital cycles for craft-scale entrants lacking supermarket slotting-fee budgets.
- Supermarkets:Shelf-space concentration in the United Kingdom and Germany drives discovery for trial-stage consumers. British multiples are expanding alcohol-free facings to 8-12 SKUs per store.
- Convenience Stores:Impulse-driven purchase occasions favor single-serve formats with minimal refrigeration dwell time.
- Specialty Shops:Curated selection and staff education support premium positioning for craft-forward portfolios.
Supermarkets dominate current volume throughput; online retail is expanding most quickly as regulatory data-capture enables personalized recommendation engines.
Consumer Type:
Behavioral segmentation tracks how wellness priorities, life-stage constraints, and social rituals generate distinct price elasticity and occasion-based demand patterns.
- Health-Conscious Consumers:Adults aged 35-55 prioritizing metabolic load reduction over complete abstention. This cohort anchors mass-market volume in Germany and drives repeat purchase for established lager formats with familiar flavor signatures.
- Fitness Enthusiasts:Post-workout social consumption rituals expand addressable demand beyond traditional abstention occasions. Electrolyte and adaptogen fortification targets this emerging margin pool with premium positioning distinct from mass-market lagers.
- Young Adults:Moderation-oriented cohorts in London and Manchester metropolitan clusters support dedicated alcohol-free draft rotations in on-premise accounts.
- Pregnant Women:Zero-tolerance alcohol policy during gestation creates inelastic demand for certified 0.0% ABV products with documented dealcoholization methodology.
Health-conscious consumers command the largest installed base; fitness enthusiasts show the steepest expansion trajectory as functional additive integration deepens category relevance.
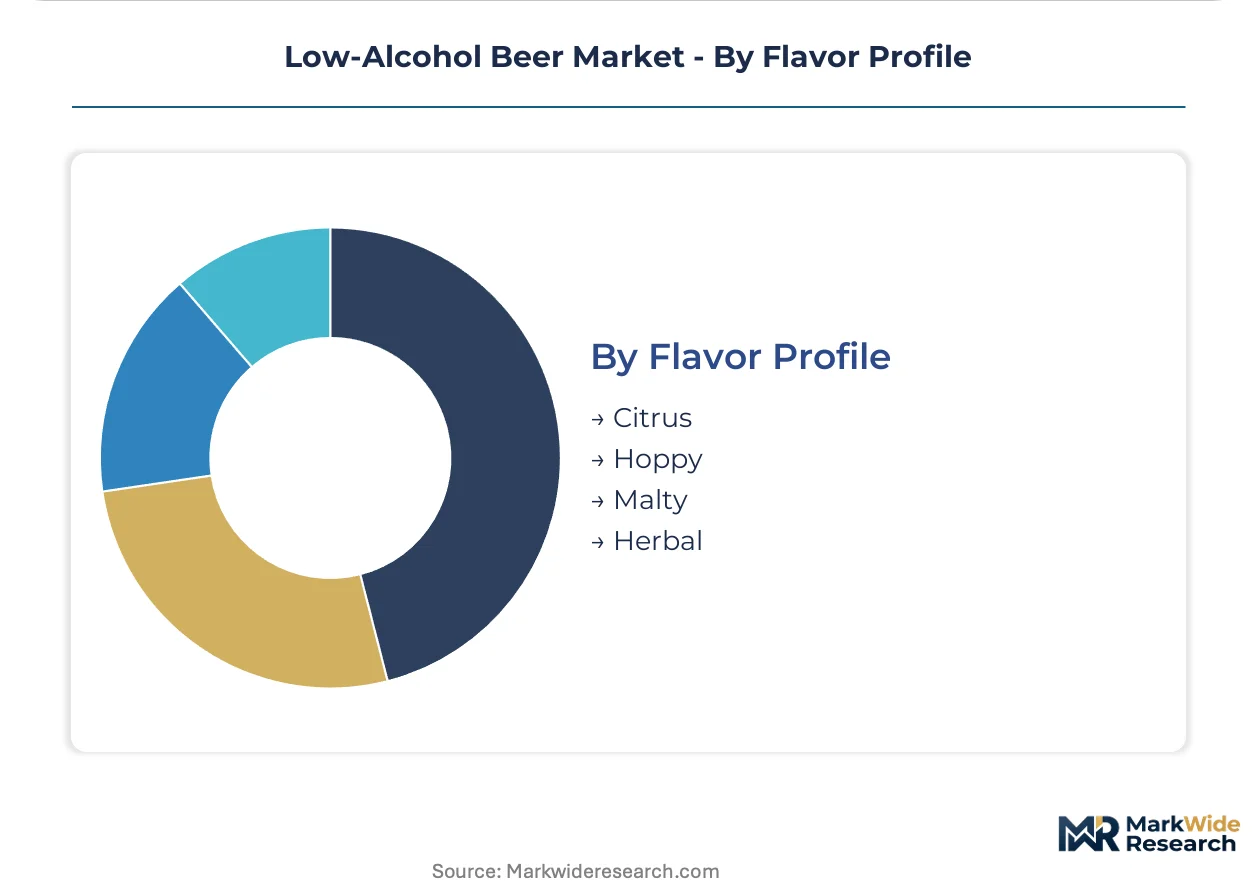
Flavor Profile:
REACH chemical safety protocols constrain synthetic ester availability, forcing differentiation toward natural extraction methods with higher batch variability and extended development timelines.
- Hoppy:Hop oil concentration delivers bitterness and aromatic complexity that masks dealcoholization-induced sweetness. Belgian and Danish craft producers are backward-integrating into captive hop oil extraction facilities to secure supply.
- Citrus:Natural peel extraction and terpene preservation require precise temperature control during membrane filtration. This profile dominates summer seasonal releases in Mediterranean markets.
- Malty:Caramel and biscuit notes from specialty malts provide body compensation for reduced ethanol mouthfeel.
- Herbal:Botanical adjuncts face divergent FDA and EU novel food approvals, complicating cross-border SKU standardization.
Hoppy profiles generate the highest margin premiums; citrus formulations are climbing the fastest as seasonal rotation strategies accelerate trial velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's tightening EU alcohol labeling mandates and pub culture moderation are accelerating low-alcohol beer migration across multiple national markets, with regulatory visibility driving pre-emptive consumer shifts toward sub-2.5% ABV formats.
Germany
Bavarian brewers dominate capacity expansion as health-conscious adults aged 35-55 drive repeat purchases for established lager formats. ECHA oversight through REACH protocols constrains synthetic flavor precursors, forcing reformulation toward natural extraction methods. Munich and Berlin metropolitan clusters host dedicated alcohol-free draft rotations as traditional on-premise accounts adapt to moderation trends.
United Kingdom
British pub operators unbundle alcohol-free selections from residual category placement, creating dedicated tap handles that signal categorical legitimacy. National alcohol duty bands at arbitrary ABV cutoffs introduce overnight reclassification risk for legislative revision. London and Manchester clusters support dedicated draft rotations where moderation-oriented demographic concentration enables premium positioning.
Netherlands
Mid-sized craft brewers accelerate capital deployment for vacuum-assisted reverse osmosis systems that preserve volatile aromatic compounds. EU F-Gas Regulation governing refrigeration emissions shapes production economics for multinational exporters. Amsterdam and Rotterdam industrial zones concentrate dealcoholization technology adoption as membrane selectivity improvements narrow sensory gaps with full-strength equivalents.
United States
FDA labeling oversight requires parallel SKU documentation for exporters, inflating regulatory affairs headcount across multinational portfolios. Fitness enthusiasts drive post-workout social consumption rituals that expand addressable demand beyond traditional abstention occasions. California and Colorado craft clusters pioneer functional additive integration with electrolyte fortification targeting premium positioning distinct from mass-market lagers.
Japan
Asahi Breweries and Kirin leverage established distribution infrastructure to capture moderation-oriented cohorts in metropolitan consumption clusters. METI standards alignment supports cross-border compliance for dealcoholized export formats. Tokyo and Osaka urban centers concentrate on-premise trial environments as younger demographics normalize alcohol-free social drinking.
Low-Alcohol Beer Market Competitive Environment
Listed leaders compete with private specialists across formulation technology and channel access dimensions, creating a tiered structure where scale advantages collide with craft-forward differentiation. Multinational brewers leverage European brewing infrastructure to dominate controlled distribution channels, while independent specialists occupy premium positioning through flavor innovation. Three archetypes define competitive positioning: integrated multinationals with shelf-space dominance, craft-scale specialists with proprietary yeast development, and private-label operators serving retail consolidation. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure membrane filtration technology and captive hop oil extraction capabilities.
Within the craft-specialist tier, Athletic Brewing Company exemplifies the flavor-forward archetype through craft-scale positioning that differentiates from mass-market lagers. Heineken anchors the multinational integrated tier with European infrastructure leverage and controlled channel penetration. Anheuser-Busch InBev occupies the scale-driven consolidation position, representing portfolio breadth across ABV thresholds and price bands. These three entities collectively illustrate how competitive positioning fragments across technology licensing, backward integration into brewing inputs, and direct-to-consumer subscription bypass of traditional three-tier systems.
| Leading Market Players |
|---|
| Athletic Brewing Company |
| Asahi Breweries |
| Anheuser-Busch InBev |
| Kirin |
| Suntory Beer |
| Heineken |
| Molson Coors |
| BrewDog |
| Carlsberg Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day organic malt procurement lead times in Germany and France compress margin buffers for craft-scale brewers while amplifying pricing power for consolidated premium suppliers. This inventory pressure concentrates cost pass-through capability among multinationals with captive supply agreements, forcing smaller producers toward contract brewing or SKU rationalization.
Pricing Analysis
Certification level under EU organic standards and ECHA REACH compliance creates the primary spread between premium and mass-market positioning. Three-tier pricing structure across premium, standard, and economy levels reflects input grade, dealcoholization technology sophistication, and channel markup layers. Cost compression in the mid-tier is intensifying because membrane filtration equipment depreciation accelerates as technology diffuses. Health-conscious consumers aged 35-55 in Germany show lowest price sensitivity, while young adult trial purchasers in British supermarkets exhibit highest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for hop oil extracts and specialized membrane filtration components. Manufacturing concentrates in Germany, the Netherlands, and the United Kingdom, with malt sourcing drawn from consolidated premium suppliers in Bavaria and northern France. Supply chain risk centers on single-source vulnerability for organic-certified brewing inputs as EU certification collapse eliminates two-thirds of eligible small maltsters. Distribution runs through three-tier wholesale systems in the United States and direct-to-retail in European markets, with online subscription models bypassing traditional markups fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse osmosis membrane selectivity breakthroughs and tightening EU alcohol labeling mandates are accelerating category disruption beyond historical moderation trends. This technological-regulatory inflection compresses incumbent reformulation timelines while opening white-space for precision-positioned entrants.
For Market Incumbents: Fortify backward integration into captive hop oil extraction to offset REACH-constrained synthetic flavor precursor availability. Secure dedicated organic malt offtake agreements with remaining certified German and French suppliers before further consolidation. Channel control through pub draft rotation partnerships in London and Manchester metropolitan clusters defends against direct-to-consumer subscription erosion.
For New Entrants and Emerging Players: Post-workout functional additive integration represents the most penetrable service-layer gap where mass-market incumbents under-serve fitness enthusiasts with electrolyte and adaptogen fortification. Target California and Colorado craft clusters for premium positioning with subscription-first go-to-market models that capture consumption data for iterative formulation. German pub channel conversion offers underpenetrated volume within established beer-drinking culture adapting to moderation trends.
For Investors and Strategic Acquirers: Long-term, this sits as a health-and-wellness platform play because low-alcohol beer bridges social ritual and metabolic load reduction across demographic cohorts. Acquisition target archetype: craft-scale specialists with proprietary yeast strain development and membrane filtration process patents. Watch for national alcohol taxation threshold revisions in the United Kingdom and Germany as the signal for overnight SKU reclassification cascades.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Preserves aromatic compounds through vacuum-assisted reverse osmosis, narrowing sensory gaps with full-strength equivalents. |
| Captive Hop Oil Extraction Facility Buildout | Secures natural flavor supply chains against REACH chemical safety protocol constraints on synthetic esters. |
| Direct-to-Consumer Subscription Launch | Bypasses three-tier distribution markups while capturing recurring revenue and iterative formulation data. |
| Functional Additive Integration Partnership | Targets fitness enthusiast margin pool with electrolyte fortification distinct from mass-market lagers. |
| EU Organic Certification Compliance Program | Maintains premium positioning eligibility as supplier base collapse eliminates uncertified maltsters. |
Study Parameters
Desk research of trade customs data, ECHA regulatory filings, and brewery capacity disclosures preceded structured interviews with R&D directors at multinational brewers, procurement leads at organic malt suppliers, pub operators in London and Manchester, and regulatory affairs specialists at flavor additive manufacturers. Primary fieldwork combined with secondary validation from EU F-Gas Regulation implementation reports and FDA labeling guidance documents. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across product type, distribution channel, consumer behavior, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation with macroeconomic consumption elasticity assumptions. Forecast inputs incorporated membrane technology adoption curves, organic certification eligibility trajectories, and national alcohol taxation threshold stability assumptions.
Forecasts assume regulatory continuity in EU REACH protocols and FDA labeling oversight; material policy shifts would require re-modeling across synthetic additive approval registers and cross-border SKU documentation requirements. Practitioners should keep alternative scenarios live as ECHA flavor precursor delisting schedules and British alcohol duty band revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Hopped Malt Extract Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Light-Flavor Liquor Market