
 Beer Stabilizers Market | 2026-2036
Beer Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Stabilizers Market Analysis
Premium lager stabilization is decoupling from commodity adjunct brewing on specification intensity and ingredient traceability. PQ Corporation leverages its silica gel expertise to anchor supply relationships with large-scale European brewers. Koninklijke DSM competes through enzymatic stabilization platforms that reduce cold-haze formation without filtration footprint expansion. Ashland differentiates via cellulose-derived clarity agents targeting craft segments demanding label-friendly ingredient decks.
Beer stabilizers comprise functional additives and processing aids engineered to prevent colloidal haze, oxidation off-flavors, and foam degradation in packaged beer, with silica hydrogels and polyvinylpolypyrrolidone representing core chemistries dosed at 20–100 grams per hectoliter depending on malt protein load. Protein stabilizers lead volume consumption due to universal relevance across lager and ale categories, while foam stabilizers command margin premiums in nitrogen-dispensed and export formats where head retention defines quality perception. Clarity agents occupy a mature growth trajectory in mainstream commercial brewing, whereas oxidation inhibitors accelerate fastest in craft and premium segments chasing extended shelf claims.
EU REACH registration requirements and EFSA food additive approvals shape ingredient market access across European formulation supply chains, with Germany's BfR issuing specific migration limits for polyvinylpolypyrrolidone residues that directly constrain dosage rates and product selection. The US FDA GRAS self-affirmation pathway and TTB labeling rules for brewing adjuncts create parallel compliance architectures that multinational stabilizer suppliers must navigate simultaneously. Stakeholders should monitor evolving alcohol beverage labeling transparency mandates and enzyme regulation reclassifications that could redraw competitive boundaries between chemical and biological stabilization approaches.
Market Dynamics
EU REACH registration requirements and EFSA food additive approvals are compressing formulation flexibility for beer stabilizer suppliers, forcing reformulation investments and supplier consolidation across European brewing supply chains.
Growth Catalysts
- Clean-label ingredient mandates:Craft breweries in Germany and Belgium seek protein stabilizers with minimal processing aids to satisfy consumer transparency demands under EU food safety frameworks.
- Enzymatic stabilization platforms:Advanced enzyme technologies reduce cold-haze formation without expanding filtration footprint, appealing to capacity-constrained mid-size brewers.
- Export format expansion:Nitrogen-dispensed and long-haul export beers require enhanced foam stabilizers to maintain head retention across extended distribution cycles.
Market Restraints
- Polyvinylpolypyrrolidone dosage limits:Germany's BfR imposes specific migration limits that constrain product selection and maximum dosing rates in premium lager formulations.
- Silica hydrogel supply concentration:Production of high-purity silica gels for protein stabilization clusters among limited specialty chemical suppliers, creating input vulnerability.
- Malt protein load variability:Inconsistent barley harvest quality forces brewers to maintain multiple stabilizer SKUs, complicating inventory and dosing precision.
Strategic Opportunities
- Cellulose-derived clarity agents:Label-friendly stabilization chemistry captures craft segments demanding recognizable ingredient decks over synthetic alternatives.
- US TTB labeling pathway:GRAS self-affirmation architecture enables faster market entry for novel biological stabilizers compared to EU additive approval timelines.
- Oxidation inhibitor acceleration:Extended shelf-life claims in premium and craft segments drive fastest uptake of antioxidant stabilization systems.
Industry Challenges
- Dual compliance architecture:Multinational suppliers must simultaneously navigate EU REACH registrations and US FDA GRAS pathways, doubling regulatory workload.
- Enzyme regulation reclassification:Evolving definitions of processing aids versus additives in European jurisdictions threaten to redraw competitive boundaries between chemical and biological approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Stabilizers Market |
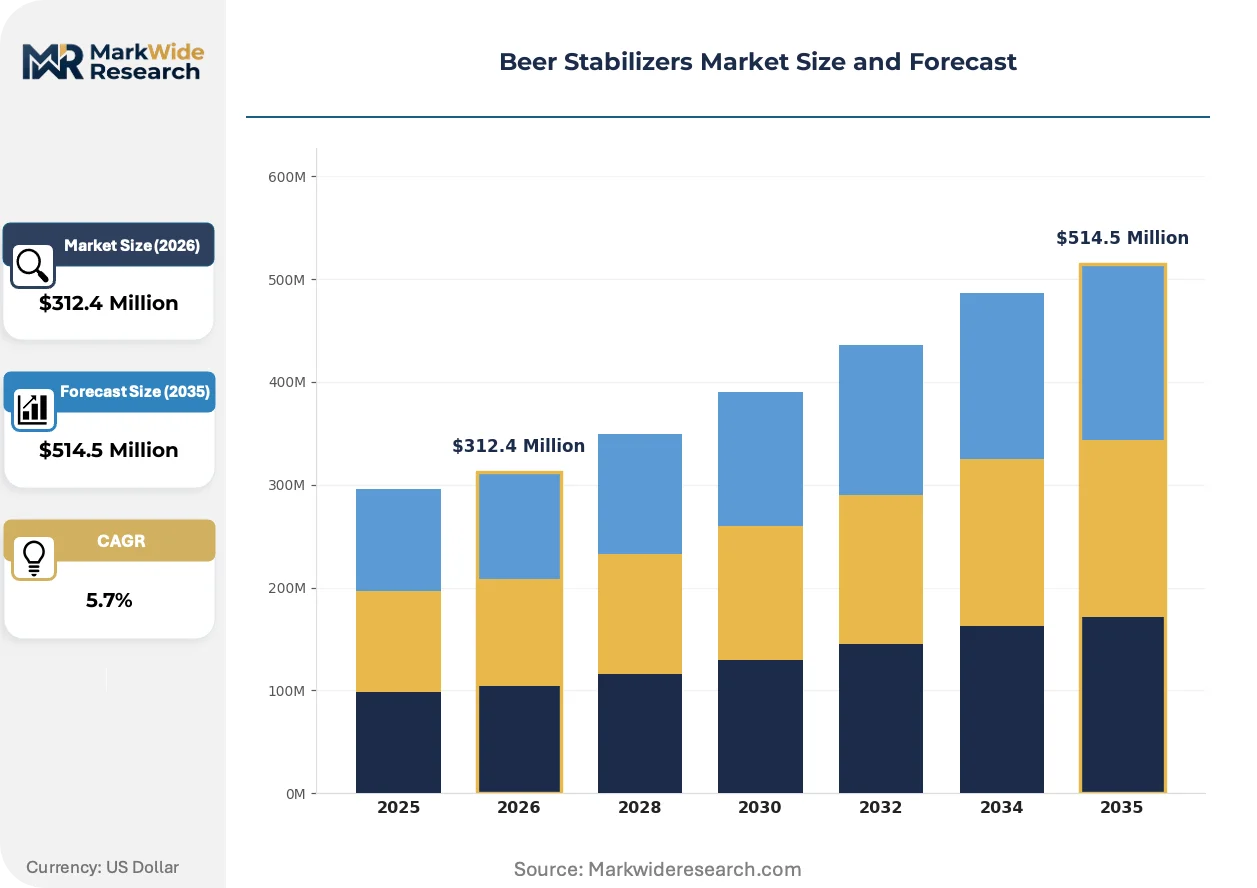
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $514.5 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidation Inhibitors, Foam Stabilizers, Clarity Agents, Protein Stabilizers Application: Craft Brewing, Commercial Brewing, Home Brewing, Carbonated Beverages End User: Brewery, Beverage Manufacturer, Food Industry, Retailer Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | PQ Corporation, Koninklijke DSM, Ashland, AEB Group, W. R. Grace, Eaton, BASF, ERBSLOH, AB Vickers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Stabilizers Market Emerging Trajectories
Brewing stabilization is bifurcating between legacy chemical approaches and biological alternatives, with regulatory pressure and consumer transparency demands forcing simultaneous investment in both pathways.
Crosslinked polyvinylpolypyrrolidone remains the workhorse for polyphenol stabilization in mainstream lager production. Large-scale European brewers continue standardizing on this chemistry despite dosage constraints. The technology is absorbing reformulation investment as suppliers develop lower-residue variants to preempt stricter migration limits.
REACH registration deadlines for existing food-contact substances are tightening disclosure requirements for silica-based stabilizers. Suppliers must submit enhanced toxicity dossiers or face market withdrawal. German and Belgian formulators are responding by accelerating enzymatic platform trials to reduce dependency on synthetic hydrogels.
Direct procurement relationships between craft breweries and specialty ingredient distributors are shortening traditional three-tier supply chains. Small-batch brewers in Belgium now source clarity agents through cooperative purchasing platforms rather than mainstream chemical distributors. This channel compression is most pronounced in heritage brewing regions where technical service relationships outweigh price sensitivity.
Beer Stabilizers Market Segmentation
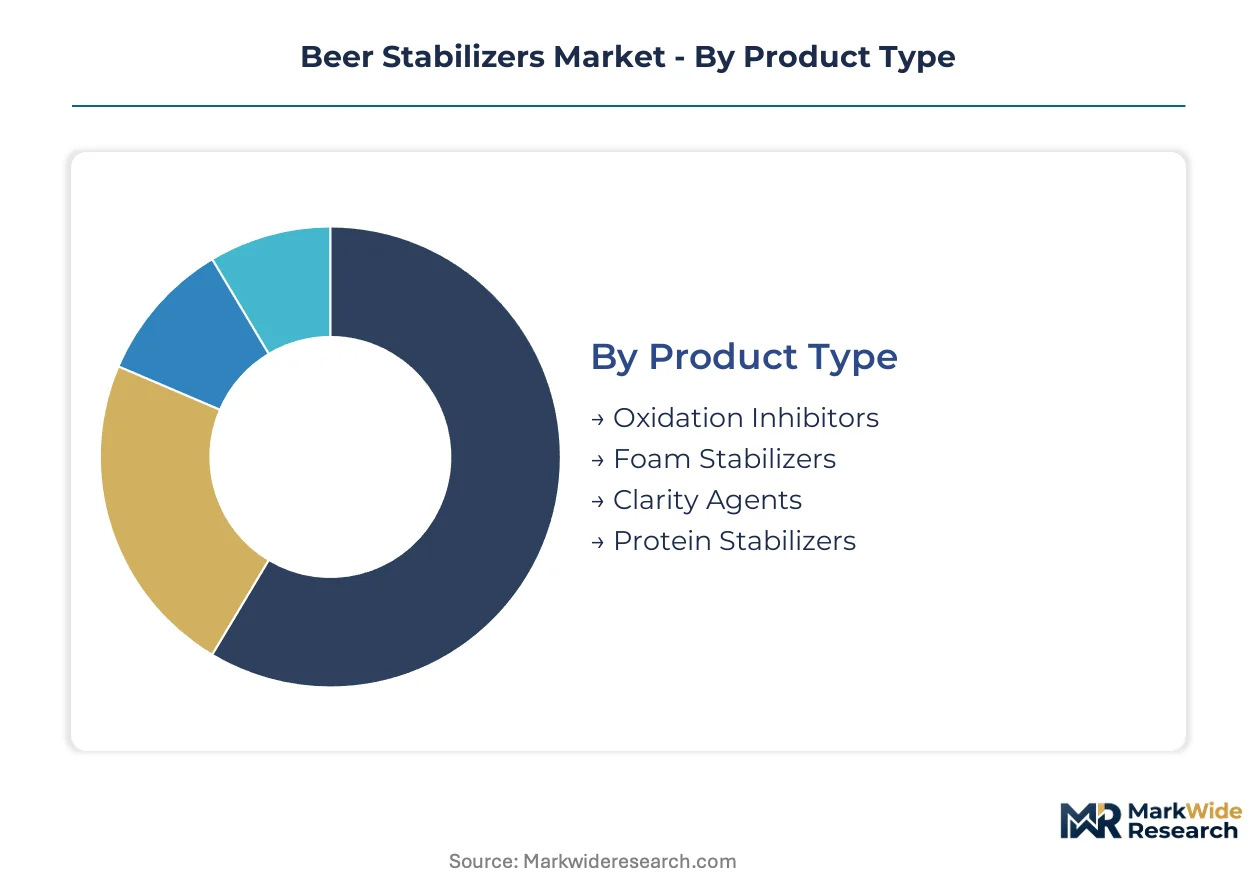
Beer stabilizer procurement varies sharply by operational scale and technical sophistication. Large-scale commercial brewers prioritize batch consistency and regulatory compliance, while craft operators trade specification intensity for formulation flexibility and label transparency.
Product Type:
Customization intensity spans from commodity silica hydrogels to engineered enzymatic platforms, with standardization pressure strongest in high-volume lager production.
- Protein Stabilizers:Silica hydrogels and polyvinylpolypyrrolidone formulations adsorb haze-active polyphenols and proteins at 20–100 grams per hectoliter. Demand concentrates in German and Belgian commercial brewing where EFSA additive approvals and BfR migration limits constrain supplier selection.
- Clarity Agents:Cellulose-derived and synthetic polymers accelerate flocculation and reduce filtration cycles. Craft breweries in heritage regions specify label-friendly cellulose variants to satisfy clean-label mandates under EU food safety frameworks.
- Foam Stabilizers:Nitrogen-dispensed formats and export beers require enhanced head retention chemistry.
- Oxidation Inhibitors:Antioxidant systems extend shelf-life claims in premium positioning.
Most installed capacity flows through protein stabilizers. Expansion is steepest in oxidation inhibitors.
Application:
Volume concentration sits with commercial brewing, though margin structure favors specialized craft and alternative beverage applications.
- Commercial Brewing:Large-scale lager and ale production demands high-volume, low-variability stabilization with documented REACH compliance. German industrial brewers anchor procurement volumes, specifying silica-based protein stabilization with certified migration profiles.
- Craft Brewing:Small-batch operators prioritize enzymatic and cellulose-derived alternatives to synthetic additives, sourcing through compressed cooperative purchasing platforms in Belgium rather than mainstream chemical distributors.
- Carbonated Beverages:Cross-category clarity and stabilization chemistry adapts to non-alcoholic formulation requirements.
- Home Brewing:Consumer-packaged stabilizers target hobbyist precision dosing.
Commercial brewing commands the majority of tonnage. Craft brewing climbs the fastest on value per hectoliter.
End User:
Procurement authority separates integrated beverage manufacturers from independent breweries with distinct technical service requirements.
- Brewery:Dedicated brewing operations specify stabilizers against malt protein load variability, maintaining multiple SKUs to compensate for inconsistent barley harvest quality.
- Beverage Manufacturer:Diversified producers apply beer stabilization chemistry across alcoholic and non-alcoholic portfolios, demanding multi-application regulatory dossiers.
- Food Industry:Adjacent processing applications repurpose clarity agents for other colloidal systems.
- Retailer:Private-label and contract brewing arrangements shift specification authority to retail procurement teams.
Breweries absorb the dominant share of stabilizer volume. Beverage manufacturers are gaining share fastest through portfolio diversification.
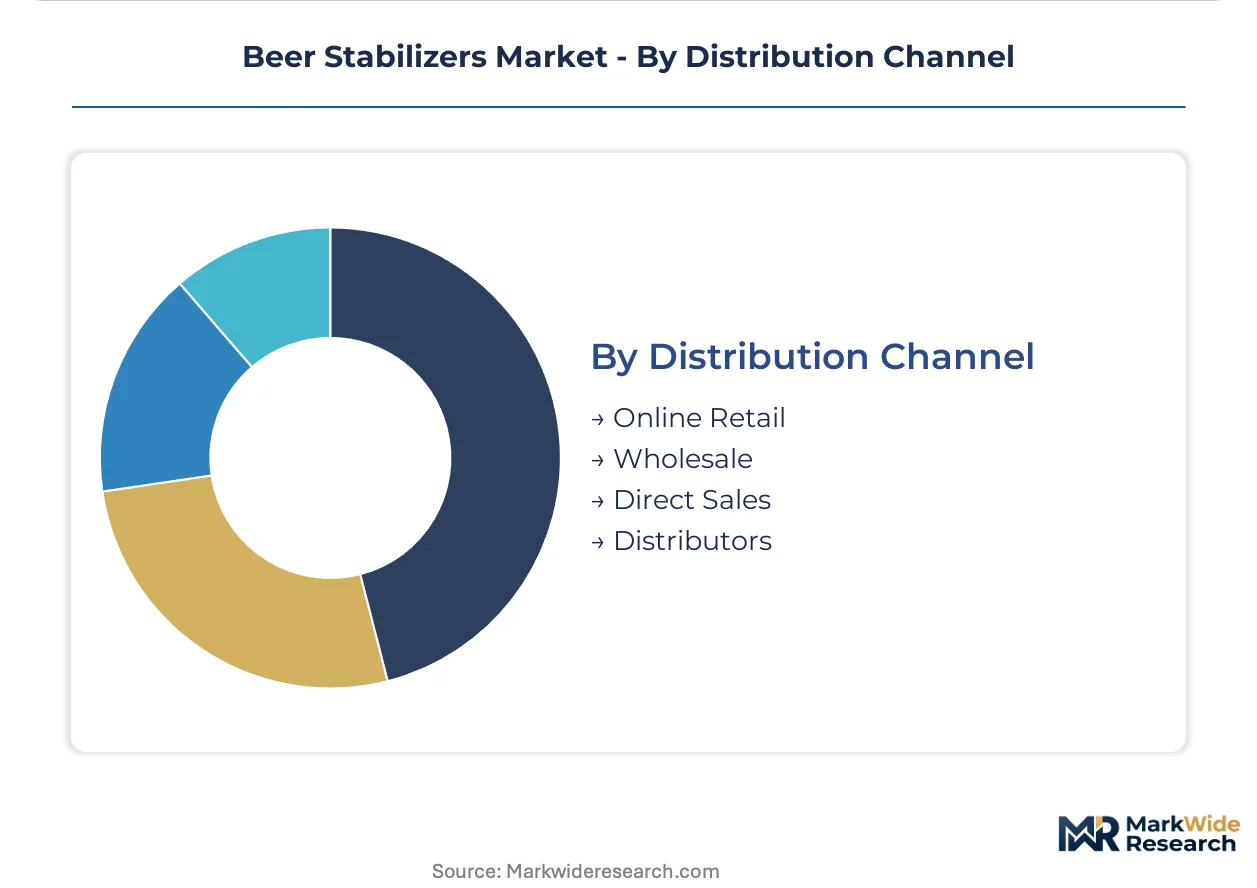
Distribution Channel:
Channel selection reflects order scale, technical support intensity, and geographic concentration of brewing clusters.
- Distributors:Specialty chemical distributors dominate large-scale commercial supply, bundling stabilizers with technical service relationships and regulatory documentation packages.
- Direct Sales:Major stabilizer suppliers maintain direct procurement relationships with multinational brewers, bypassing intermediaries for volume commitments and collaborative formulation development.
- Wholesale:Regional chemical wholesalers serve mid-tier brewers with standardized product ranges.
- Online Retail:E-commerce platforms capture craft and home brewing segments requiring small-batch packaging and rapid delivery.
Distributors handle the bulk of commercial volume. Direct sales channels are expanding most quickly among consolidated brewing groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brewing technologists and malt quality specialists concentrate in Germany and Belgium, anchoring European stabilizer demand. These talent clusters intersect with stringent EU regulatory frameworks and heritage brewing traditions. Regional procurement patterns reflect this technical workforce distribution.
Germany
Industrial lager producers in Bavaria and North Rhine-Westphalia drive silica hydrogel consumption for protein stabilization. The Federal Institute for Risk Assessment enforces polyvinylpolypyrrolidone migration limits that constrain dosage formulations. Munich-based brewing conglomerates maintain direct procurement relationships with specialty chemical suppliers for REACH-compliant stabilizer portfolios.
Belgium
Heritage abbey and craft breweries in Flanders prioritize enzymatic platforms to satisfy clean-label mandates under EFSA processing aid classifications. The country's national food safety authority coordinates with regional brewing associations on additive transparency protocols. Brussels and Leuven host cooperative purchasing platforms that compress traditional distributor channels for small-batch operators.
United States
Large-scale brewers in Wisconsin and Colorado specify oxidation inhibitors for extended shelf-life claims in premium positioning. The FDA GRAS self-affirmation pathway enables faster market entry for novel biological stabilizers compared to EU timelines. The Pacific Northwest craft brewing cluster sources cellulose-derived clarity agents through regional specialty ingredient distributors.
United Kingdom
London and Midlands-based beverage manufacturers apply beer stabilization chemistry across diversified alcoholic and non-alcoholic portfolios. Health UK coordinates with the Food Standards Agency on additive dossier requirements for cross-category ingredient deployment. Scottish distillers and brewers in the Highlands maintain technical service relationships with stabilizer suppliers for multi-application regulatory documentation.
China
State-owned brewing groups in Shandong and Guangdong provinces scale silica-based protein stabilization for mass-market lager production. The Ministry of Agriculture and Rural Affairs oversees barley quality standards that influence malt protein load variability. The Yangtze River Delta brewing corridor imports enzymatic stabilization technologies through joint ventures with European specialty chemical suppliers.
Beer Stabilizers Market Vendor Landscape
Top-tier vendors anchor high-volume commercial supply, while mid-tier specialists occupy craft and regional niches. The market structures around three to five dominant suppliers with established REACH dossiers and technical service infrastructures. Strategic archetypes include integrated chemical conglomerates, enzyme technology platforms, and cellulose-derived specialty ingredient houses. Competitive moves center on reformulation investments for lower-residue variants and compressed channel strategies targeting cooperative purchasing platforms.
Within the integrated chemical tier, PQ Corporation and BASF represent legacy silica hydrogel suppliers with established European brewer relationships. Koninklijke DSM exemplifies the enzyme technology archetype, competing through biological stabilization platforms that reduce filtration footprint. Ashland occupies a position among cellulose-derived specialists targeting label-friendly clarity agent demand in craft segments.
| Leading Market Players |
|---|
| PQ Corporation |
| Koninklijke DSM |
| Ashland |
| AEB Group |
| W. R. Grace |
| Eaton |
| BASF |
| ERBSLOH |
| AB Vickers |
| Others |
Supply Flow & Price Mechanics
Enzymatic stabilization platform adoption simultaneously compresses per-hectoliter dosing costs and concentrates supplier relationships among enzyme technology specialists with captive fermentation capacity. This shift rewards brewers with filtration footprint reduction while creating pricing power asymmetries for biological stabilizer suppliers against legacy silica hydrogel producers.
Pricing Analysis
Bundled technical service contracts dominate large-scale commercial procurement, while unbundled spot purchasing prevails among craft breweries sourcing through cooperative platforms. Three-tier pricing structure across premium enzymatic, standard silica-based, and economy-grade synthetic tiers reflects certification intensity and REACH dossier completeness. Pricing pressure stems from malt protein load variability forcing brewers to maintain redundant stabilizer inventories. Volume-scale commercial brewers exhibit lowest price sensitivity; small-batch craft operators prioritize label transparency over cost optimization.
Supply Chain Analysis
Single-source vulnerability sits with German and Belgian specialty chemical producers controlling high-purity silica hydrogel manufacturing. Raw material dependencies encompass sodium silicate feedstocks, fermentation-derived enzyme cultures, and cellulose ether precursors. Supply chain risk centers on REACH registration deadline exposure forcing formulation withdrawals. Distribution runs through specialty chemical distributors bundling regulatory documentation with technical service relationships for commercial brewers, while compressed cooperative platforms serve craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in enzymatic platform substitution and premium-tier oxidation inhibitor penetration, with cost-down drivers anchored in fermentation process optimization and dosage precision analytics.
For Market Incumbents: Acquire enzyme fermentation capacity in the Rhine-Ruhr corridor to preempt biological stabilization supply constraints. Consolidate REACH dossier maintenance through shared regulatory service consortia. Defend against cellulose-derived clarity agent displacement by accelerating lower-residue silica hydrogel reformulation. For New Entrants and Emerging Players: Direct-to-brewery digital procurement platforms offer the fastest channel penetration against legacy distributor relationships. Target Belgian craft cooperatives with label-friendly enzymatic platforms certified under EFSA processing aid classifications. Lead with subscription-based dosing optimization services rather than commodity stabilizer supply. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier cellulose-derived specialty ingredient houses with underutilized clarity agent capacity. Five-to-ten-year viability hinges on regulatory bifurcation between chemical and biological stabilization pathways. Monitor EFSA enzyme reclassification proceedings as the critical inflection signal for portfolio rebalancing between synthetic and biological stabilization exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Platform Acquisition | Biological stabilization capacity in Germany captures craft brewery procurement shifts. |
| REACH Dossier Consolidation | Shared regulatory infrastructure reduces compliance burden for silica hydrogel suppliers. |
| Cooperative Platform Partnership | Compressed channel access in Belgium bypasses legacy distributor markups for small-batch brewers. |
| Lower-Residue Reformulation | BfR-compliant polyvinylpolypyrrolidone variants defend market position against migration limit tightening. |
| Oxidation Inhibitor Scale-Up | Extended shelf-life chemistry addresses premium lager export format requirements. |
Methodological Framework
Bottom-up brewery procurement modeling reconciled against top-down specialty chemical production tracking forms the analytical core of this study. Primary interviews with brewing technologists, malt quality specialists, procurement directors at integrated beverage manufacturers, and regulatory affairs leads at stabilizer suppliers were validated against customs trade data, EFSA additive approval registers, BfR migration limit publications, and REACH registration dossiers.
Historical trendline analysis of protein stabilizer dosing rates and clarity agent adoption curves informed projection frameworks across product type, application scale, and regional regulatory cluster dimensions. CAGRs were derived from segmented volume trajectories incorporating malt protein variability indices, enzymatic platform penetration assumptions, and export format expansion rates.
Regulatory reclassification, barley harvest quality volatility, and enzyme fermentation capacity constraints are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on stabilizer substitution elasticities and compliance timeline adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Alcoholic Tea Market