
 Frozen Cocktails Market | 2026-2036
Frozen Cocktails Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Cocktails Market Analysis
Capital-intensity divergence between large-scale bottlers and craft-focused entrants is unwinding competitive stability in frozen cocktails. The Absolut Company leverages its global spirits infrastructure to secure bulk ethanol supply and flavor R&D pipelines. Claffey's Frozen Cocktails sustains a niche position through pouch-format specialization and direct-to-retail channel control. J&J Snack Foods Corp anchors its presence via frozen beverage equipment networks that lock in recurring syrup and concentrate sales.
Frozen cocktails are alcohol-infused, ready-to-freeze or pre-frozen beverage formulations typically containing distilled spirits, fruit purees, sweeteners, and stabilizers engineered to maintain texture at sub-zero temperatures; their primary commercial purpose is delivering consistent, labor-free premium bar experiences across off-premise retail and on-premise hospitality settings. Frozen Margaritas occupy the dominant volume position due to established tequila supply chains and Mexican restaurant penetration, while Frozen Pina Coladas command higher per-unit margins through coconut cream complexity and tropical positioning. The Online Stores distribution channel is expanding fastest as direct-to-consumer cold-chain logistics mature, though Bars and Restaurants still capture the largest profit pool through fountain-dispensed, high-turnover service models.
FDA labeling mandates for alcohol content and allergen disclosure shape formulation reformulation cycles across US producers, while TTB certificate-of-label approval requirements govern interstate commerce and seasonal SKU introductions. State-level ABC (Alcoholic Beverage Control) regulations create fragmented market access, with California and Texas offering more permissive retail formats than control-state jurisdictions. Stakeholders must monitor evolving refrigeration energy standards and potential sugar-tax expansions that could compress margins on fruit-forward formulations.
Market Dynamics
Hotels and resorts are aggressively expanding frozen cocktail programs across their beverage portfolios, forcing suppliers to reconcile premium positioning with labor-free operational models while navigating FDA's updated labeling mandates for alcohol content transparency.
Growth Catalysts
- On-premise venue expansion:Hotels and resorts are scaling frozen cocktail installations across pool bars, lobby lounges, and event spaces, creating pull-through demand for pre-batched formulations and equipment-locked syrup contracts.
- FDA labeling clarity:The FDA's updated alcohol content disclosure requirements are accelerating formulation standardization among US producers, reducing consumer trust barriers and enabling clearer premium positioning.
- Cold-chain logistics maturation:Direct-to-consumer refrigerated shipping infrastructure is unlocking retail channel expansion beyond traditional liquor stores, with specialized carriers now supporting frozen last-mile delivery.
Market Restraints
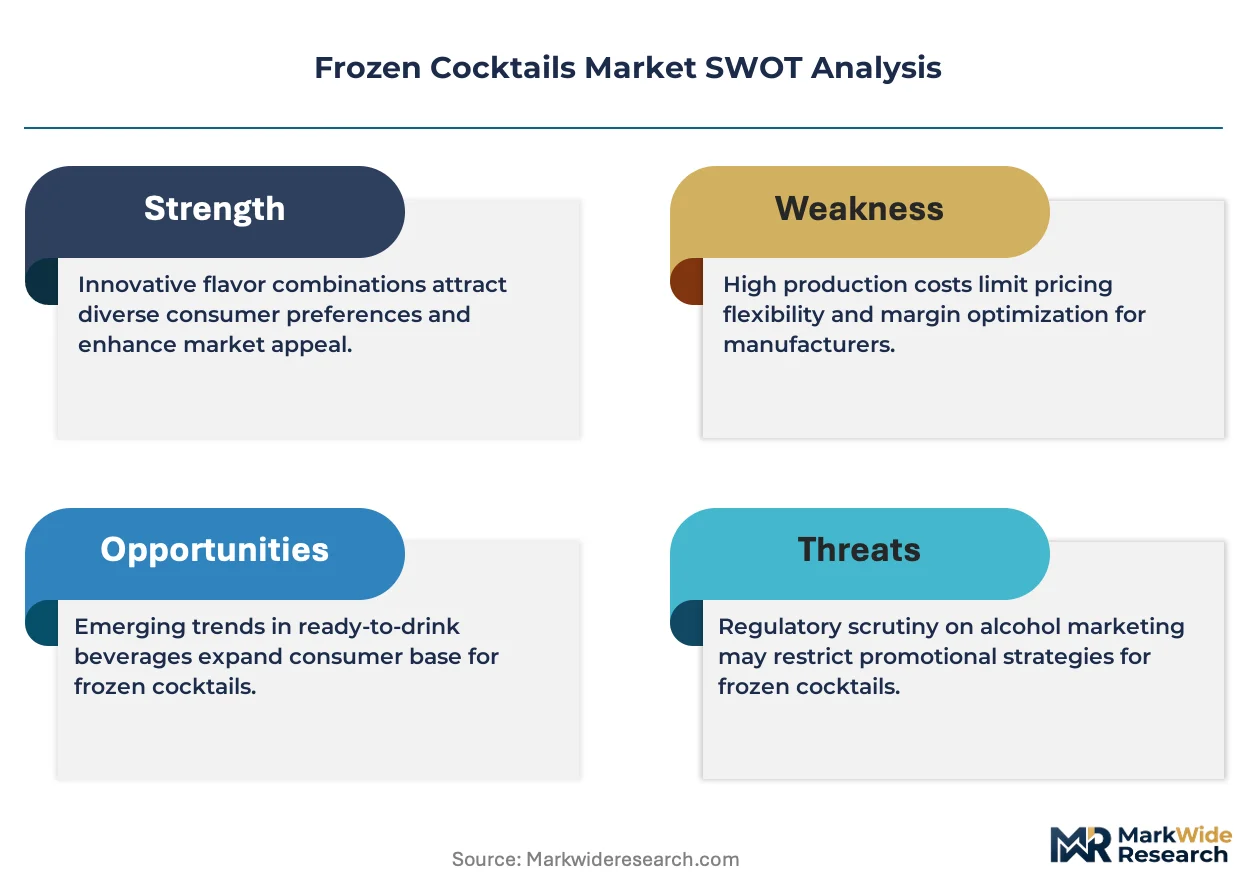
- Bulk ethanol supply concentration:Large-scale spirits infrastructure controls dominate ethanol procurement, squeezing margin flexibility for craft-focused entrants without backward integration into distillation.
- State-level ABC fragmentation:Alcoholic Beverage Control regulations vary sharply between control-state and license-state jurisdictions, forcing redundant compliance investments and limiting national SKU rollout velocity.
- Refrigeration energy standards:Evolving commercial freezer efficiency mandates are elevating equipment replacement costs for on-premise venues, compressing adoption timelines for frozen beverage fountain systems.
Strategic Opportunities
- Premium pouch format penetration:Single-serve frozen pouches remain underdeveloped in resort and cruise channels, offering white space for direct-to-retail specialists to bypass traditional three-tier distribution.
- Tropical flavor complexity:Coconut cream and exotic fruit formulations command higher per-unit margins than standard margarita bases, rewarding R&D investment in texture-stabilized tropical portfolios.
- Sugar-tax hedging:Anticipated expansions of sugar taxation in progressive jurisdictions are creating first-mover advantage for low-calorie and alternative-sweetener formulations that preempt regulatory compression.
Industry Challenges
- TTB certificate-of-label approval timelines:The Alcohol and Tobacco Tax and Trade Bureau's seasonal SKU review process creates launch-window risk, particularly for holiday-themed limited releases requiring compressed production cycles.
- Stabilizer chemistry talent scarcity:Formulation expertise in sub-zero texture maintenance—balancing alcohol depression of freezing point with mouthfeel consistency—resides in a narrow specialist pool, elevating compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Cocktails Market |
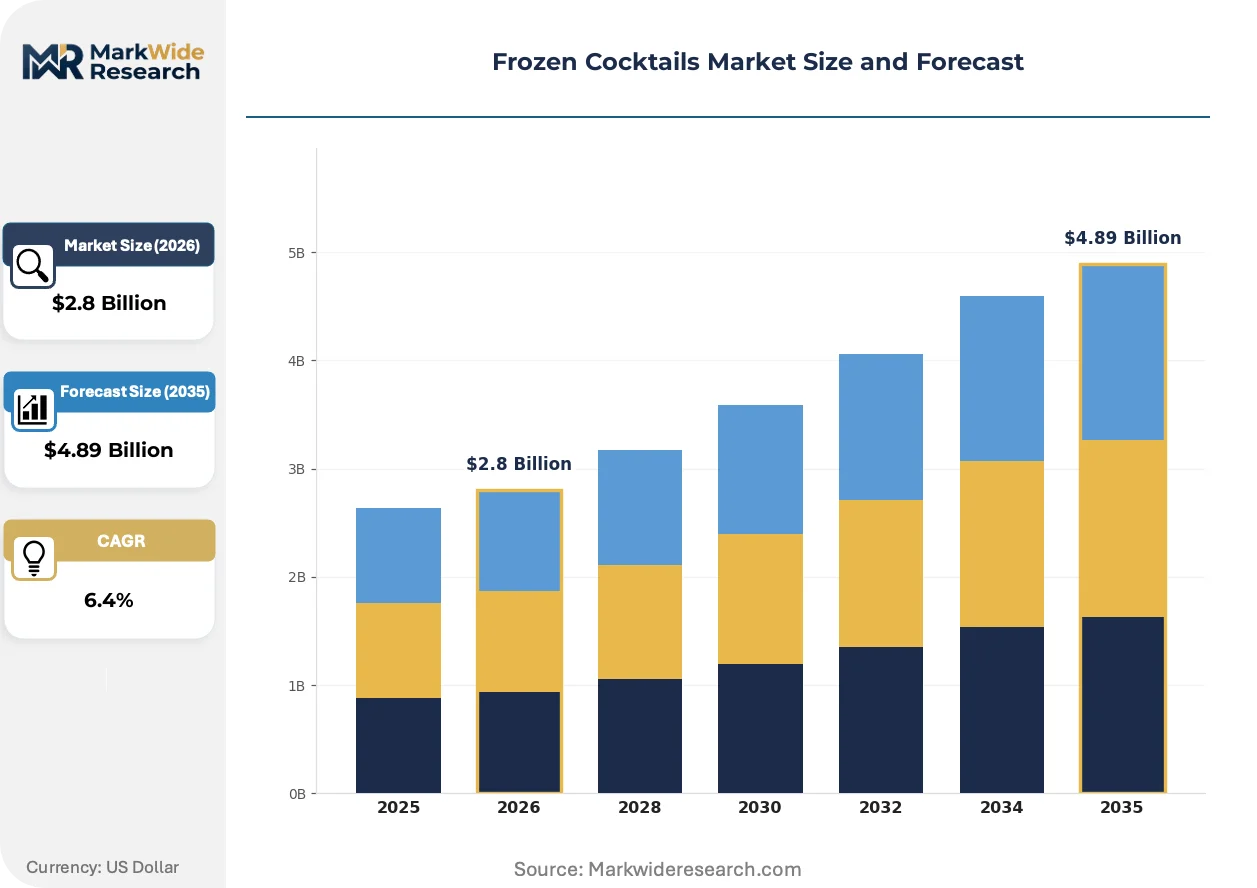
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Margaritas, Frozen Daiquiris, Frozen Pina Coladas, Frozen Mojitos Distribution Channel: Retail Stores, Online Stores, Bars, Restaurants Customer Type: Adults, Millennials, Party Organizers, Event Planners Flavor Profile: Fruit-flavored, Classic, Creamy, Spicy |
| Companies Covered | The Absolut Company, Claffey's Frozen Cocktails, Harvest Hill Beverage Company, Flavorful Beverages International Inc., 24 ICE B.V., LIC Frozen Cocktails, Cooloo, J&J Snack Foods Corp, Manchester Drinks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Cocktails Market Emerging Trajectories
Equipment miniaturization and formulation stabilization advances are collapsing the operational gap between high-volume fountain service and craft-quality frozen cocktails, while regulatory transparency mandates reshape competitive positioning around ingredient disclosure.
Countertop frozen beverage systems is miniaturizing from back-of-house industrial equipment to front-of-bar installations, enabling smaller restaurants and boutique hotels to deploy premium frozen programs without dedicated freezer rooms or specialized plumbing. Independent operators in urban hospitality clusters are adopting these compact units fastest, compressing the addressable market for traditional large-format equipment suppliers.
REACH compliance requirements for flavoring substances are forcing European suppliers to reformulate synthetic additive dependencies ahead of substance restriction timelines, accelerating natural extract substitution in coconut cream and fruit puree bases. Frozen Pina Colada formulations face the steepest reformulation burden given their reliance on complex emulsifier systems, with German and French producers already advancing clean-label alternatives.
Buyer procurement patterns are consolidating around equipment-locked concentrate contracts that bundle fountain hardware with multi-year syrup supply commitments, displacing spot purchasing of pre-mixed frozen bases. Large resort chains and casino hospitality groups are driving this shift most aggressively in Nevada and Florida, where high-throughput pool bars prioritize operational consistency over formulation flexibility.
Frozen Cocktails Market Segmentation
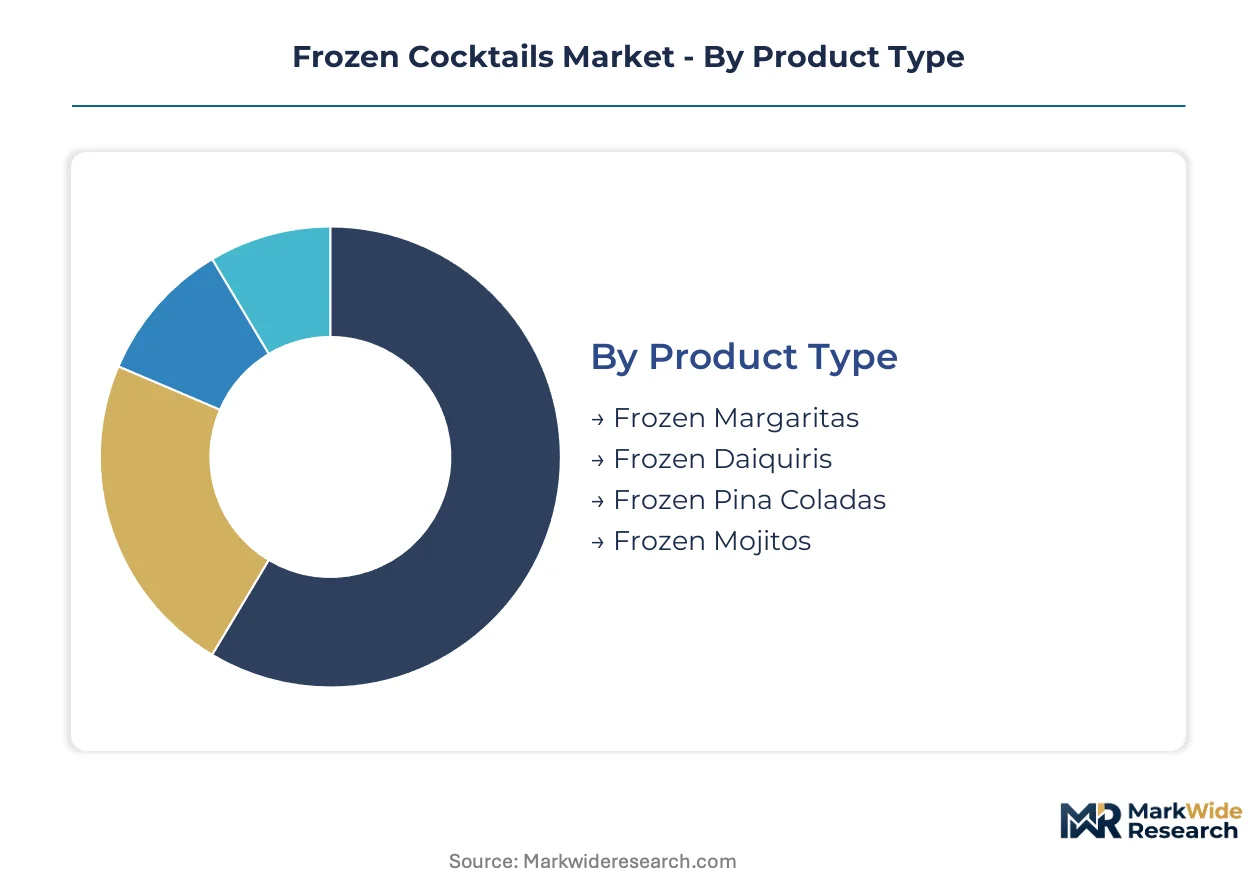
Frozen cocktail suppliers configure production lines and formulation R&D around distinct margin architectures. Each segmentation dimension carries different pricing power, regulatory exposure, and channel access requirements.
Product Type:
Margarita formats command the deepest profit pools through tequila supply chain scale and Mexican restaurant penetration, while tropical variants extract premium pricing through ingredient complexity.
- Frozen Margaritas:These formulations blend tequila, lime concentrate, and orange liqueur with stabilizers engineered for slush consistency at 28-32°F. Demand concentrates in Texas and California through casual dining chains and sports venue concession contracts, where high-turnover fountain installations prioritize supply reliability over flavor novelty.
- Frozen Pina Coladas:Coconut cream emulsions combined with rum and pineapple puree require sophisticated texture engineering to prevent fat separation during freeze-thaw cycles. Resort properties in Florida and Nevada drive procurement, paying formulation premiums for clean-label alternatives that preempt REACH substance restrictions.
- Frozen Daiquiris:Rum-based citrus formulations targeting beachfront hospitality and cruise line beverage programs.
- Frozen Mojitos:Mint-infused white rum variants with specialized aromatic preservation for hotel lobby lounge deployment.
Frozen Margaritas hold installed capacity. Frozen Pina Coladas is rotating up the share rankings.
Distribution Channel:
Channel selection determines working capital intensity and regulatory compliance burden, with on-premise venues locking in multi-year equipment contracts while direct-to-retail accelerates fastest.
- Bars:High-volume fountain systems with captive syrup supply agreements dominate urban nightlife clusters in Miami and Las Vegas. These installations generate recurring concentrate revenue but require TTB certificate-of-label approval for every seasonal SKU rotation.
- Restaurants:Casual dining and fast-casual Mexican concepts in California and Texas specify pre-batched bag-in-box formats for labor-free consistency. Procurement concentrates around equipment-locked contracts that bundle freezer hardware with multi-year syrup commitments.
- Retail Stores:Grocery and liquor store frozen aisles in license-state jurisdictions carry ready-to-freeze pouches and bottled concentrates.
- Online Stores:Direct-to-consumer cold-chain logistics now supports frozen last-mile delivery through specialized carriers, unlocking suburban markets beyond traditional liquor store footprints.
Bars hold installed capacity. Online Stores is climbing the fastest.
Customer Type:
Demographic targeting shapes formulation positioning and marketing spend allocation, with experience-driven segments commanding engagement premiums over routine purchasers.
- Millennials:This cohort drives demand for craft-authentic positioning, low-calorie alternatives, and Instagram-compatible packaging aesthetics. Urban coastal markets in California and New York show highest per-capita consumption, with procurement favoring premium pouch formats over value-tier bottled options.
- Event Planners:Corporate and wedding hospitality coordinators in Florida and Arizona specify bulk pre-mixed bases for consistent execution at scale. Their procurement prioritizes operational simplicity and liability-compliant alcohol content standardization over flavor innovation.
- Adults:Broad 35-54 demographic with established brand loyalties and routine at-home consumption patterns.
- Party Organizers:Social hosts purchasing for private gatherings, price-sensitive and volume-focused.
Adults hold installed capacity. Millennials is gaining share fastest.
Flavor Profile:
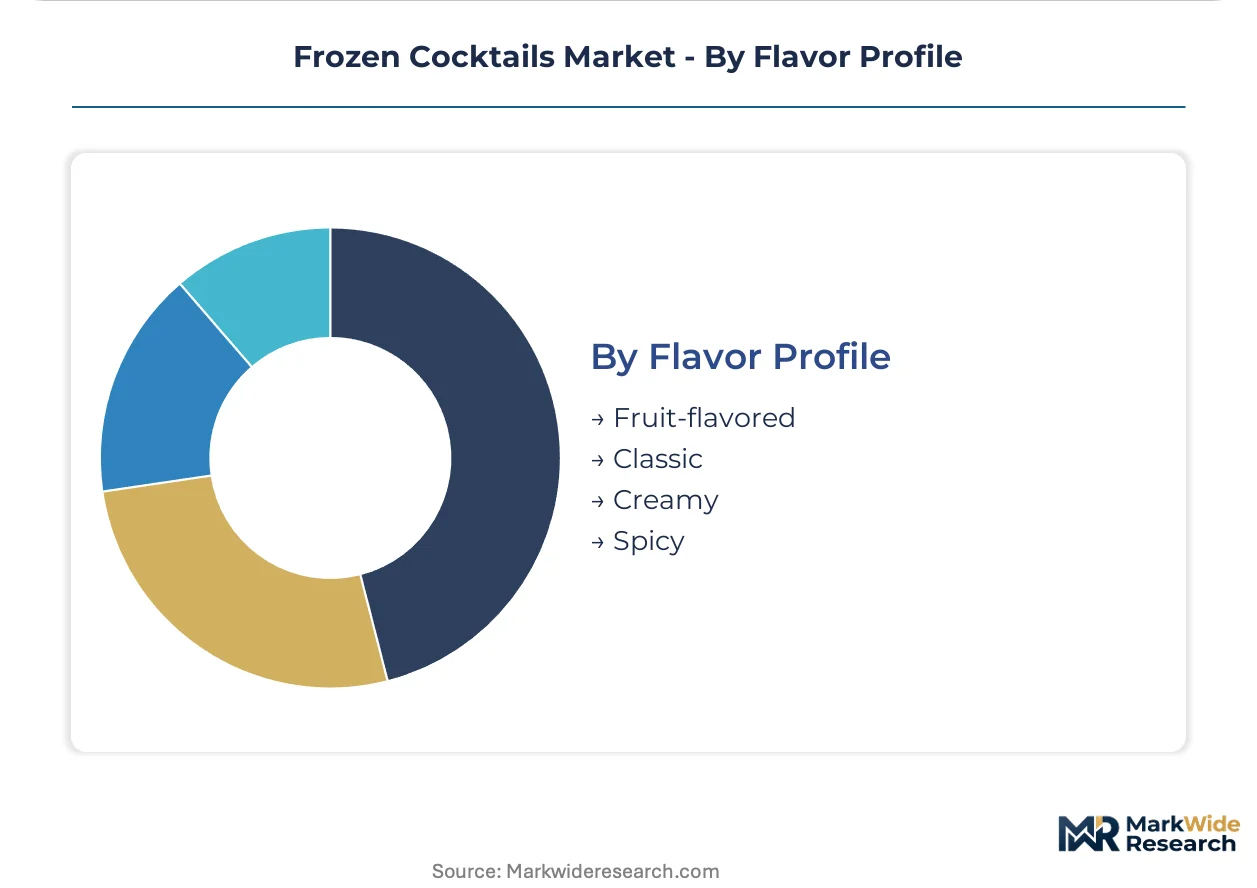
Flavor architecture determines ingredient cost structure and regulatory exposure, with natural extract formulations commanding sourcing premiums over synthetic alternatives.
- Fruit-flavored:Berry, mango, and passionfruit formulations utilizing natural puree bases and acidulants for shelf stability. Demand concentrates in health-conscious coastal markets where clean-label positioning supports price premiums, though sugar-tax exposure in progressive jurisdictions creates reformulation pressure.
- Creamy:Coconut, vanilla, and dairy-adjacent formulations requiring emulsifier expertise for freeze-thaw texture maintenance. Resort and cruise channels in Florida drive procurement, with European REACH compliance forcing accelerated natural extract substitution.
- Classic:Traditional lime, lemon, and neutral citrus profiles with established supply chains.
- Spicy:Chili-infused and tajin-rimmed variants targeting experimental hospitality concepts in Texas and Arizona.
Classic holds installed capacity. Fruit-flavored is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in resort-dependent markets show low price elasticity for premium frozen formulations, while price-sensitive segments in mature urban centers drive pouch-format commoditization.
United States
Nevada and Florida hospitality clusters anchor demand through casino resort and cruise line procurement of high-throughput fountain systems. FDA alcohol content disclosure mandates accelerate formulation standardization among domestic producers. Miami's pool bar operators and Las Vegas strip venues lock in multi-year equipment-locked syrup contracts.
Germany
REACH compliance deadlines for flavoring substances force reformulation of synthetic additive dependencies in coconut cream bases. ECHA substance restriction timelines compress R&D cycles for clean-label alternatives. Bavarian beverage distributors advance natural extract substitution ahead of regulatory enforcement.
United Kingdom
London's boutique hotel sector drives countertop equipment adoption for lobby lounge deployment. The country's national alcohol regulator maintains certificate-of-label approval requirements for seasonal SKU introductions. Manchester-based hospitality groups consolidate procurement around pre-batched bag-in-box formats.
Japan
Tokyo's izakaya chains experiment with compact frozen beverage systems for labor-constrained operations. METI refrigeration energy standards elevate equipment replacement costs for on-premise venues. Osaka's urban nightlife clusters show fastest adoption of front-of-bar miniaturized installations.
Australia
Queensland resort properties sustain demand for tropical flavor complexity through coconut cream formulations. The country's national food standards code governs allergen disclosure requirements for ready-to-freeze pouches. Sydney's coastal hospitality venues prioritize clean-label positioning to preempt sugar-tax discussions.
Frozen Cocktails Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Large-scale spirits infrastructure controls dominate ethanol procurement and flavor R&D pipelines, while craft-focused entrants specialize in format innovation and direct channel access. Three archetypes define the landscape: global spirits conglomerates with captive supply chains, pouch-format specialists with retail bypass capabilities, and equipment-locked syrup suppliers with recurring revenue models. Competitive moves concentrate on strategic partnerships for cold-chain logistics and portfolio diversification into low-calorie formulations.
Within the global spirits tier, The Absolut Company represents scale-driven infrastructure dominance. Among format specialists, Claffey's Frozen Cocktails occupies a position exemplifying pouch-format channel control. On the equipment-anchored vector, J&J Snack Foods Corp sits within the recurring revenue archetype through frozen beverage hardware networks.
| Leading Market Players |
|---|
| The Absolut Company |
| Claffey's Frozen Cocktails |
| Harvest Hill Beverage Company |
| Flavorful Beverages International Inc. |
| 24 ICE B.V. |
| LIC Frozen Cocktails |
| Cooloo |
| J&J Snack Foods Corp |
| Manchester Drinks |
| Others |
Supply Flow & Price Mechanics
Natural extract substitution for synthetic stabilizers is redrawing procurement geography toward REACH-compliant European suppliers while elevating per-unit ingredient costs across tropical formulation portfolios. This input transition simultaneously compresses margins on legacy Pina Colada recipes and creates pricing power for clean-label specialists able to command resort channel premiums.
Pricing Analysis
Equipment-locked syrup contracts generate recurring lifetime value that exceeds front-loaded hardware margins by multiples across casino and resort installations. Three-tier pricing structure across premium pouch, standard bag-in-box, and economy bottled concentrate levels separates channel control capabilities from commodity spot purchasers. Cost compression in fruit-forward formulations is intensifying because sugar-tax exposure in progressive jurisdictions forces reformulation investment. Event planners and party organizers exhibit highest price sensitivity, while Nevada and Florida resort operators absorb formulation premiums for operational consistency.
Supply Chain Analysis
Inventory cycles for coconut cream and exotic fruit purees extend lead times beyond standard citrus concentrate procurement, forcing advance commitment structures. Ethanol supply concentrates in the United States, Brazil, and Mexico, with tequila agave availability tethered to Jalisco harvest variability. Bulk spirits infrastructure draws from concentrated distillation capacity, creating single-source vulnerability for craft entrants lacking backward integration. Distribution runs through three-tier beverage alcohol systems in license states and state-controlled warehousing in ABC jurisdictions, fragmentating national SKU velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen cocktail market fragmentation creates entry niches as resort procurement consolidates around equipment-locked contracts while direct-to-retail channels bypass traditional distribution. Millennial demand for craft-authentic positioning and clean-label transparency splinters the addressable market beyond scale-driven incumbents.
For Market Incumbents: Compound installed base advantages by extending syrup contract durations and embedding countertop miniaturization programs in boutique hotel segments. Counter format specialists threaten fountain-dominant positions through pouch-format retail bypass. Deepen captive supply of natural extract pipelines to preempt REACH-driven reformulation cycles.
For New Entrants and Emerging Players: Lead with direct-to-consumer cold-chain capabilities in suburban markets beyond traditional liquor store footprints, where specialized carriers now enable frozen last-mile delivery. Cruise line and resort pouch channels remain underdeveloped relative to fountain penetration. Anchor go-to-market strategy through Instagram-compatible packaging aesthetics targeting Millennial urban coastal clusters.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors equipment-anchored recurring revenue models over format innovation bets. Long-term viability across the projection horizon hinges on cold-chain logistics partnerships and low-calorie formulation pipelines. Monitor TTB certificate-of-label approval timeline compression as inflection signal for seasonal SKU launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-Locked Contract Expansion | Casino resort operators in Nevada secure multi-year syrup commitments that displace spot purchasing. |
| Natural Extract Pipeline Investment | REACH compliance deadlines force synthetic additive substitution in coconut cream emulsion bases. |
| Direct-to-Consumer Cold-Chain Buildout | Specialized refrigerated carriers unlock suburban markets beyond traditional three-tier distribution. |
| Countertop System Miniaturization | London boutique hotels deploy front-of-bar installations without dedicated freezer room infrastructure. |
| Low-Calorie Formulation Development | Alternative sweetener portfolios preempt sugar-tax compression in progressive state jurisdictions. |
Methodological Framework
Initial hypotheses were tested against primary input from beverage development executives, resort procurement directors, TTB regulatory affairs specialists, and frozen equipment service technicians and refined through secondary validation against FDA labeling guidance documents, TTB certificate-of-label approval databases, state ABC regulatory filings, and customs import records for ethanol and flavoring substances. Bottom-up volume triangulation across channel-specific consumption patterns was cross-checked against top-down spirits industry production data.
Variance decomposition across product type, distribution channel, flavor profile, and customer demographic dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and hospitality sector expansion patterns. Forecast inputs incorporated equipment installation rates in resort properties and cold-chain logistics maturity curves for direct-to-retail channels.
The analysis sits within stated boundaries; outcomes outside sustained resort hospitality expansion or accelerated sugar-tax adoption would require recalibration. Forecasts reflect documented assumptions regarding TTB approval timelines, REACH substance restriction enforcement, and refrigeration energy standard implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Alcoholic Ice Cream Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
White Spirits Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Whey Based Vodka Market