
 United States Beer Market | 2026-2036
United States Beer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Beer Market Intelligence
Cold-chain distribution automation is tilting capital deployment toward precision fermentation and canning-line robotics. Anheuser-Busch InBev leverages its captive aluminum supply and national refrigerated logistics to dominate mainstream lager volume. Molson Coors sustains regional brewery networks that anchor Midwest distribution density. Boston Beer specializes in hard seltzer and craft-adjacent innovation, competing through flavor R&D rather than scale economics.
Beer is a fermented malt beverage brewed from cereal grains, typically barley, with hops added for bitterness, aroma, and antimicrobial stability; water chemistry and yeast strain selection determine alcohol content, which generally ranges from 3% to 12% ABV depending on style and process intent. Lager remains the volume backbone across supermarkets and mass-market channels, though margin pools have shifted toward ale and specialty stout in liquor stores and on-premise accounts. The 25-34 consumer age group drives fastest-growing demand for hoppy and fruity flavor profiles, while bars and restaurants still capture premium pricing power over off-premise supermarkets.
The Alcohol and Tobacco Tax and Trade Bureau (TTB) governs label approval, formula disclosure, and interstate commerce compliance, while FDA oversees ingredient safety and allergen declarations under FSMA; state-level three-tier distribution laws further fragment market access. OSHA standards govern brewery workplace safety around carbon dioxide exposure and pressurized vessels. Stakeholders must monitor how evolving TTB guidance on cannabis-adjacent beverages and state-level franchise law reforms reshape route-to-market economics.
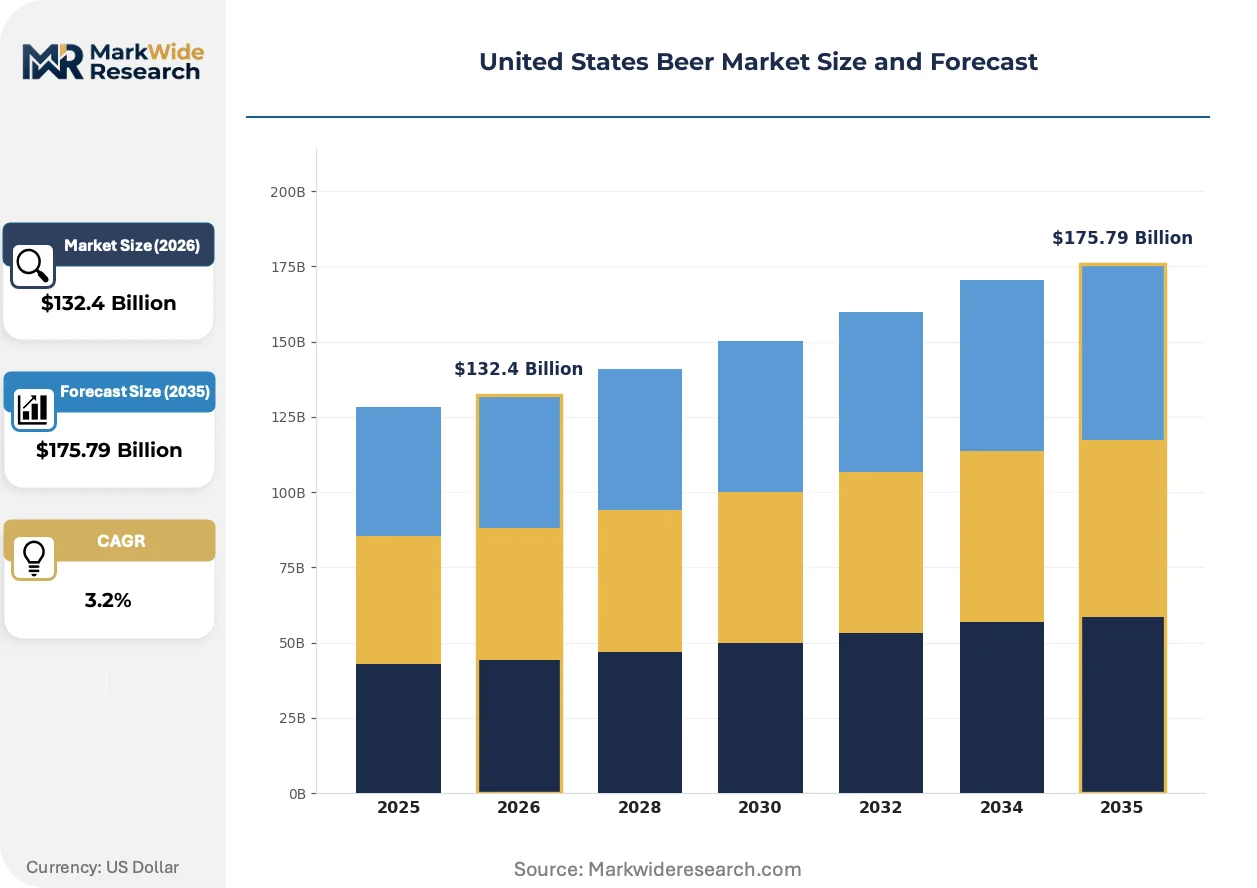
Market Dynamics
Cold-chain distribution automation is redirecting capital toward precision fermentation systems and canning-line robotics, compressing batch-to-shelf timelines for regional breweries competing against national refrigerated logistics networks.
Growth Catalysts
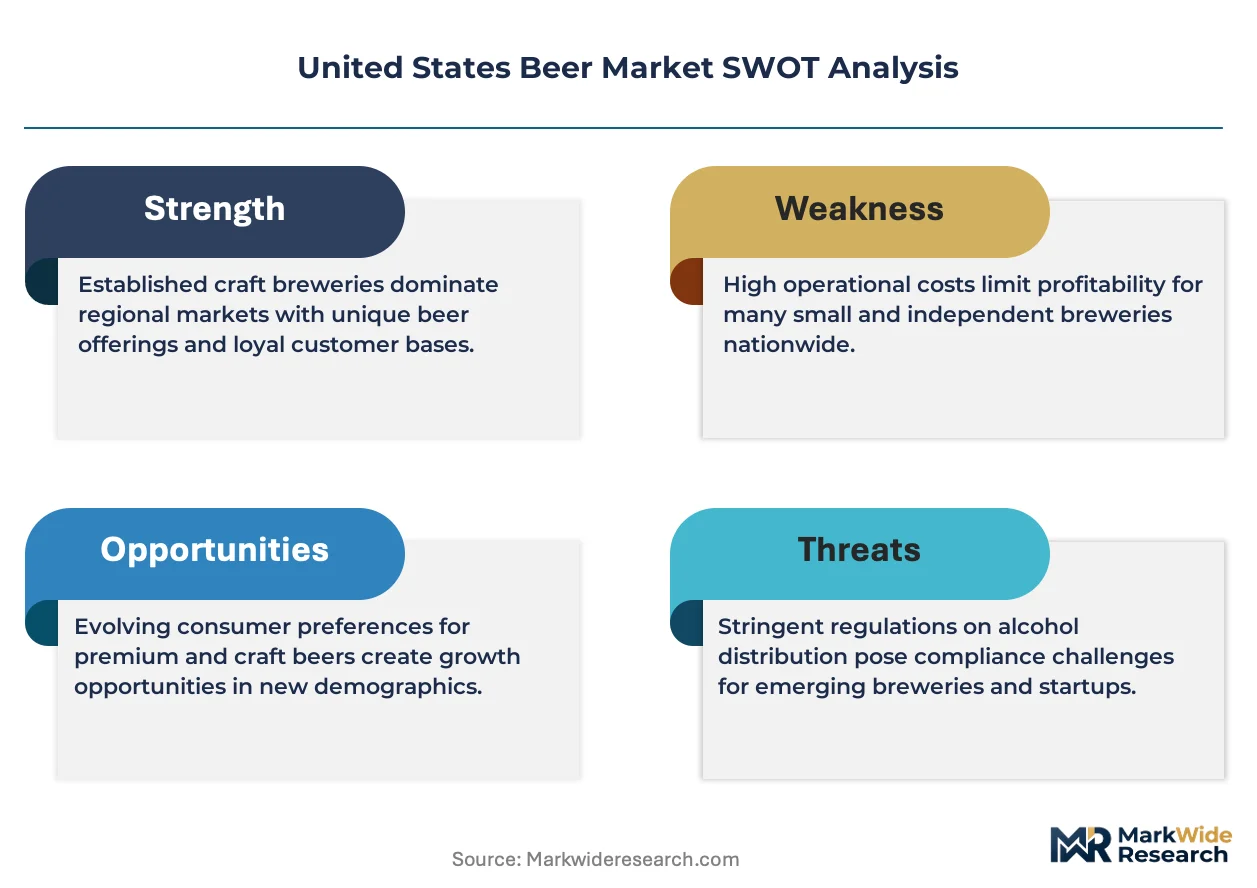
- TTB Formula Modernization:Streamlined approval pathways for novel ingredients accelerate innovation cycles in fruit-forward and hop-varietal releases.
- Specialty Liquor Channel Expansion:Independent craft breweries secure dedicated shelf space in premium off-premise accounts, bypassing supermarket slotting-fee barriers.
- Colorado and California Cluster Effects:Dense supplier ecosystems and trained brewing labor pools lower per-unit R&D costs for experimental small-batch production.
Market Restraints
- Aluminum Input Volatility:Can sheet and lid stock pricing fluctuates with smelter capacity constraints and tariff exposure, pressuring packaging cost structures.
- Three-Tier Distribution Lock-In:State-level franchise laws create exit friction for breweries seeking to restructure wholesaler relationships or build self-distribution.
- Wine and Spirits Substitution:Premiumization in RTD cocktails and low-intervention wine erodes occasion share among 25-34 demographic drinkers.
Strategic Opportunities
- Cannabis-Adjacent Beverage White Space:Evolving TTB guidance on THC-infused and CBD-positioned drinks creates first-mover positioning in compliant formulation.
- Direct-to-Consumer Subscription Models:Brewery-owned membership clubs and exclusive release programs bypass wholesale markups in permissive states.
- Non-Alcohol Ale and Lager Extension:Precision fermentation enables sub-0.5% ABV products that retain hop character, capturing wellness-oriented drinkers.
Industry Challenges
- Brewing Chemist Talent Scarcity:Shortage of trained cellar operators and quality-control specialists with wet-lab experience limits production scaling.
- FSMA Compliance Timeline Compression:FDA hazard analysis and preventive control requirements demand documentation systems that strain small-brewery administrative capacity.
- Legacy Equipment Integration Friction:Retrofitting existing brewhouses with automated fermentation monitoring creates downtime and compatibility failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Beer Market |
| Market Size in 2026 | $132.4 Billion |
| Market Size in 2035 | $175.79 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Porter Distribution Channel: Supermarkets, Liquor Stores, Bars, Restaurants Consumer Age Group: 18-24, 25-34, 35-44, 45+ Flavor Profile: Hoppy, Malty, Fruity, Spicy |
| Companies Covered | Anheuser-Busch InBev, Molson Coors, Constellation Brands, Mark Anthony, Boston Beer, Heineken USA, Pabst, Diageo Beer, Yuengling, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Beer Market Strategic Shifts & Innovations
Automation and ingredient science are compressing traditional brewing timelines while regulatory clarity and channel fragmentation reshape how beer reaches drinkers.
Precision fermentation technology is digitizing yeast strain optimization and real-time gravity monitoring. Mid-sized craft breweries in Michigan and Oregon deploy sensor networks that adjust temperature and nutrient dosing without cellar intervention. This digitizing of production control reduces batch variation and labor headcount per barrel.
FDA's evolving FSMA implementation for alcoholic beverages tightens allergen disclosure and supplier verification requirements. Breweries must now document hop and adjunct provenance through blockchain-enabled chain-of-custody systems. Small-batch producers in Vermont and Maine face disproportionate compliance costs relative to their production volumes.
On-premise accounts are unbundling draft line access from exclusive pouring contracts, allowing rotation-heavy bars to source from multiple regional breweries simultaneously. This fragmentation of taproom economics favors portfolio breadth over single-brand volume commitments. Brooklyn and Denver operators lead this shift, rotating 20-plus handles weekly.
United States Beer Market Segmentation
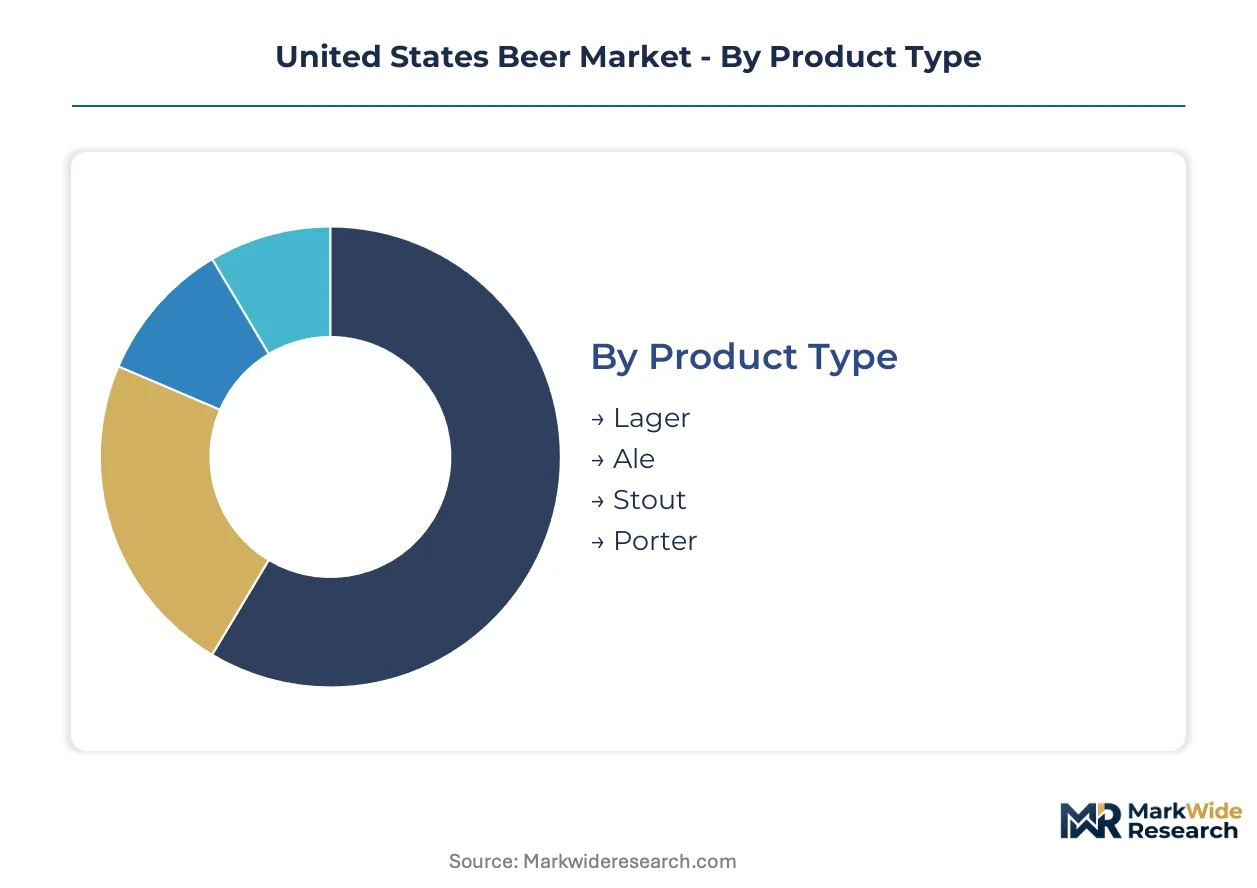
Beer segmentation in the United States reveals distinct margin architectures across product types and channel structures. Manufacturers calibrate brewing schedules and packaging formats against specific consumption occasions and state-level distribution constraints.
Product Type:
Mature styles anchor volume while emerging categories capture premium pricing and experimental demand.
- Lager:Bottom-fermented at cooler temperatures producing clean, crisp profiles with subtle hop bitterness. Supermarket chains in the Midwest and South move the highest case volumes, though slotting fees compress margins for regional entrants competing against captive aluminum supply chains.
- Ale:Top-fermented with warmer temperature regimes yielding fruit-forward ester profiles and broader stylistic range. Colorado and California craft clusters drive fastest innovation in hazy and farmhouse sub-styles, supported by dense supplier ecosystems and trained brewing labor pools.
- Stout:Dark roasted malt base with coffee and chocolate flavor compounds, typically higher gravity. Seasonal releases dominate winter on-premise accounts in the Northeast.
- Porter:Historical English style with balanced roast character and lower bitterness than stout. Specialty liquor stores in Pacific Northwest urban markets sustain small-batch production.
Lager handles the majority of throughput; Ale is expanding most quickly on share.
Distribution Channel:
Channel selection determines regulatory exposure and working capital intensity across the three-tier system.
- Supermarkets:Mass-market volume channel requiring TTB label approval and state-by-state franchise law compliance. Chains in California and Texas leverage centralized procurement to extract promotional allowances, favoring national refrigerated logistics networks over regional self-distribution.
- Liquor Stores:Premium off-premise channel with dedicated craft beer sections and rotation-heavy inventory policies. Independent operators in Denver and Brooklyn bypass supermarket slotting barriers, granting shelf access to experimental small-batch releases.
- Bars:Draft-heavy on-premise with exclusive pouring contracts fragmenting into multi-handle rotation models. Florida and Arizona operators lead unbundling trends.
- Restaurants:Food-pairing oriented with higher per-ounce pricing and curated by-the-glass programs. Fine-dining accounts in Chicago and Seattle prioritize local provenance and blockchain-enabled chain-of-custody documentation.
Supermarkets move the highest absolute volume; Liquor Stores are climbing the fastest on margin contribution.
Consumer Age Group:
Age-based demand patterns shape flavor innovation pipelines and marketing spend allocation.
- 25-34:Core growth demographic driving hoppy and fruity flavor profile demand, with highest willingness to pay for limited releases and brewery-exclusive membership programs. Colorado and Michigan operators target this cohort through direct-to-consumer subscription models.
- 18-24:Entry-level drinkers with price sensitivity and occasion experimentation, including non-alcohol ale and lager trial. California and New York campuses show wellness-oriented sub-0.5% ABV preference.
- 35-44:Established brand loyalty with occasional premium trade-up for specialty stout and barrel-aged offerings. Texas and Pennsylvania suburban markets sustain this segment.
- 45+:Traditional lager preference with lower channel-switching frequency and higher supermarket reliance. Midwest and Southeast retirement corridors concentrate this demand.
25-34 captures the steepest expansion trajectory; 45+ maintains the largest absolute base.
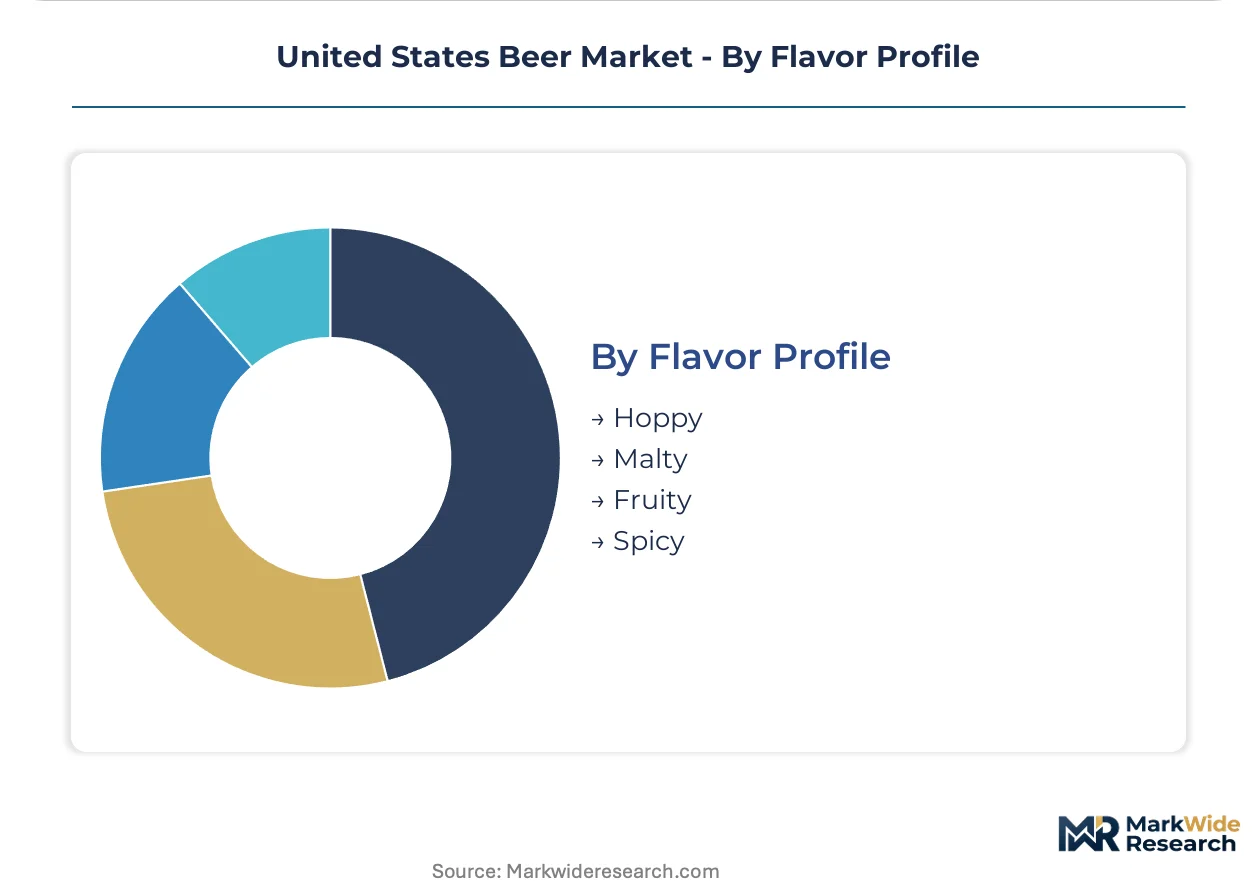
Flavor Profile:
Flavor positioning determines hop procurement strategies and adjunct sourcing complexity under FSMA documentation requirements.
- Hoppy:Elevated iso-alpha acid content from Pacific Northwest and German varietals, demanding cold-chain preservation of volatile aromatic compounds. Vermont and Oregon breweries face disproportionate compliance costs for hop provenance tracking.
- Fruity:Yeast-derived esters or adjunct puree additions requiring TTB formula modernization pathways for novel ingredient approval. Michigan and Florida operators accelerate release cycles through streamlined federal review.
- Malty:Caramel and biscuit notes from specialty kilned grains, traditional in lager and bock styles. Midwest malt houses supply this profile with shorter supply chains.
- Spicy:Phenolic yeast character or actual spice additions, common in Belgian-inspired and winter seasonal offerings. Colorado and Wisconsin winter markets sustain niche production.
Hoppy commands the highest per-barrel revenue; Fruity is gaining share fastest among experimental releases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian malt barley flows southward into Michigan and New York brewing facilities, while Mexican lager production supplies cross-border demand through Texas and Arizona distribution nodes. This North American trade architecture shapes regional capacity deployment and cold-chain infrastructure investment across the continent.
California
San Diego and Los Angeles harbor the densest craft brewing ecosystem in the nation, with over 1,200 active brewery licenses driving experimental ale production. TTB formula modernization pilot programs in this state accelerate novel ingredient approvals for fruit-forward releases. The Bay Area precision fermentation cluster supplies automated brewing systems to regional operators, compressing batch-to-shelf timelines.
Colorado
Denver and Boulder anchor the Mountain West brewing corridor, where trained cellar operator pools lower per-unit R&D costs for small-batch producers. State franchise law reforms in 2023 reduced exit friction for breweries restructuring wholesaler relationships. Fort Collins hosts concentrated canning-line robotics manufacturing, serving regional packaging automation demand.
Michigan
Grand Rapids and Detroit sustain Great Lakes brewing heritage through lager volume and seasonal stout specialization. OSHA brewery safety enforcement around carbon dioxide exposure and pressurized vessels operates at elevated intensity here. The state's malt house network supplies shorter supply chains for caramel and biscuit grain profiles.
Texas
Austin and Dallas-Fort Worth concentrate fastest-growing population cohorts aged 25-34, driving hoppy and fruity flavor profile demand. State three-tier distribution laws create working capital intensity for supermarket channel access, favoring national refrigerated logistics networks. Houston's port facilities handle imported hop varietals from Germany and New Zealand.
New York
Brooklyn and Queens lead unbundling of draft line access from exclusive pouring contracts, allowing rotation-heavy bar sourcing from multiple regional breweries. FDA FSMA compliance timelines for allergen disclosure and supplier verification strain small-brewery administrative capacity in this high-regulation environment. The Hudson Valley supplies local provenance documentation for fine-dining accounts prioritizing blockchain-enabled chain-of-custody systems.
United States Beer Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered market structure where national refrigerated logistics networks face pressure from regional self-distribution experiments. The vendor base separates into three strategic archetypes: scale-driven volume operators with captive aluminum supply, craft-adjacent innovation specialists competing through flavor R&D, and regional portfolio breadth players anchoring Midwest distribution density. Dominant competitive moves include M&A consolidation of craft brewery networks and strategic partnerships with precision fermentation technology providers.
Among scale-driven operators, Anheuser-Busch InBev and Molson Coors occupy positions defined by national refrigerated logistics infrastructure and captive supply chain control. Boston Beer exemplifies the craft-adjacent innovation archetype, competing through hard seltzer and experimental flavor pipelines rather than manufacturing scale. These three anchors represent the structural tension between volume efficiency and portfolio differentiation that shapes capital deployment across the industry.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Molson Coors |
| Constellation Brands |
| Mark Anthony |
| Boston Beer |
| Heineken USA |
| Pabst |
| Diageo Beer |
| Yuengling |
| Others |
Cost & Logistics Intelligence
Fort Collins anchors canning-line robotics manufacturing capacity that compresses regional packaging automation costs, translating into tiered pricing power for mid-sized craft breweries against national refrigerated logistics networks. This Colorado cluster dynamics directly shape how aluminum input volatility feeds downstream into margin structures across lager, ale, and stout production tiers.
Pricing Analysis
Legacy canning-line technology versus precision fermentation automation versus next-generation sensor-integrated brewing systems creates a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on TTB formula modernization compliance tiers and cold-chain preservation certification, with craft-adjacent innovation specialists capturing brand premiums. Pricing pressure stems from aluminum sheet and lid stock commodity volatility pressuring packaging economics. Supermarket channel buyers exhibit highest price sensitivity due to centralized procurement leverage, while direct-to-consumer subscription members show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and aluminum-producing trading partners dominates supply chain risk calculus for can sheet procurement. Brewing inputs draw from Canadian malt barley flows, German and New Zealand hop varietals, and domestic specialty grain kilning operations. Single-source vulnerability concentrates in Pacific Northwest aroma hop acreage and captive aluminum smelter arrangements. Distribution runs through state-level three-tier wholesaler networks fragmenting national scale economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States beer market sits in a cyclical recovery phase as post-pandemic on-premise consumption normalization and TTB regulatory clarity on novel ingredients restore innovation investment velocity.
For Market Incumbents: Pre-empt craft brewery network consolidation before specialty liquor channel shelf space locks in regional portfolio breadth players. Acquire precision fermentation technology providers to defend against automation-driven cost compression from Michigan and Oregon mid-sized operators. Anchor Midwest distribution density through Fort Collins and Grand Rapids logistics node control.
For New Entrants and Emerging Players: Establish a beachhead in non-alcohol ale and lager extensions targeting California and New York wellness-oriented 18-24 demographic campuses. Exploit direct-to-consumer subscription model permissibility in Colorado and Michigan to bypass three-tier distribution working capital intensity. Lead with blockchain-enabled chain-of-custody documentation as the go-to-market angle for fine-dining restaurant accounts.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because state franchise law reforms are reducing wholesaler relationship exit friction and enabling roll-up economics. Target regional craft breweries with automated fermentation monitoring infrastructure already deployed. Watch TTB guidance evolution on cannabis-adjacent beverage formulation as the inflection signal for first-mover positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Technology Deployment | Sensor networks from Bay Area suppliers reduce batch variation and labor headcount per barrel produced. |
| Direct-to-Consumer Subscription Launch | Brewery-owned membership clubs bypass wholesale markups in Colorado and Michigan permissive regulatory environments. |
| Canning-Line Robotics Integration | Fort Collins equipment manufacturing cluster enables regional packaging automation cost compression against national networks. |
| Non-Alcohol Product Line Extension | Sub-0.5% ABV precision fermentation captures wellness-oriented drinkers in California and New York campus markets. |
| Blockchain Chain-of-Custody Implementation | FSMA-compliant hop and adjunct provenance documentation satisfies Chicago and Seattle fine-dining account requirements. |
Research Approach
Cross-validation between TTB formula approval databases and FDA FSMA implementation guidance anchors the qualitative findings on regulatory compliance cost structures. Primary interviews with craft brewery owners, TTB regulatory affairs specialists, three-tier distribution wholesalers, and precision fermentation equipment engineers combined with secondary validation from SEC 10-K filings, customs trade data on malt barley and hop imports, and state-level brewery license databases. Bottom-up production volume estimates and top-down market value triangulation ensure analytical consistency.
Calibration against historical aluminum pricing volatility and channel shift patterns shapes the projection framework across the analysis window. Segmentation dimensions modeled include product type, distribution channel, consumer age group, and flavor profile, with regional regulatory cluster variations capturing state franchise law heterogeneity. CAGRs derive from weighted average growth contributions across these segments. Industry-specific forecast inputs include TTB formula modernization approval velocity and cold-chain infrastructure investment trajectories.
Sensitivities concentrate around aluminum tariff policy shifts, TTB guidance evolution on cannabis-adjacent beverages, and three-tier distribution law reforms in additional states. Forecasts reflect documented assumptions on consumer age group demand persistence and precision fermentation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
Wine Destemmer Market