
 Fume Extractor Market | 2026-2036
Fume Extractor Market Size, Share, and Industry Trends Forecast 2026-2036
Fume Extractor Market Analysis
The capital-intensity divergence between high-volume filter manufacturers and modular system integrators is redrawing competitive boundaries in fume extraction. Nederman leverages its captive supply of filter media to sustain margin compression in portable units. Lincoln Electric anchors its position through backward integration into welding equipment channels, creating bundled demand for source-capture systems.
A fume extractor is an engineered air-purification system that captures airborne contaminants at or near the point of generation using negative-pressure hoods, multi-stage filtration media with HEPA or activated-carbon ratings, and variable-frequency blowers. Its primary industrial purpose is to maintain worker breathing-zone concentrations below regulatory thresholds while preserving thermal process stability. Portable units dominate replacement cycles in job-shop environments where workstation mobility matters, while centralized ducted architectures command the installed base in heavy manufacturing because lifecycle filter economics favor fixed infrastructure. Electrostatic precipitators compete on low-pressure-drop efficiency in high-volume welding bays, whereas adsorption technologies capture volatile organic compounds in chemical processing where carbon bed saturation monitoring determines operating cost.
OSHA enforces permissible exposure limits for manganese and hexavalent chromium that directly mandate source-capture engineering controls ahead of personal protective equipment hierarchy. EPA National Emission Standards for Hazardous Air Pollutants extend these requirements to coating and metal finishing operations, creating compliance-driven replacement demand. Stakeholders must monitor state-level adoption of California's more stringent occupational exposure limits, as this pattern propagates eastward and reshapes product certification requirements.
Market Dynamics
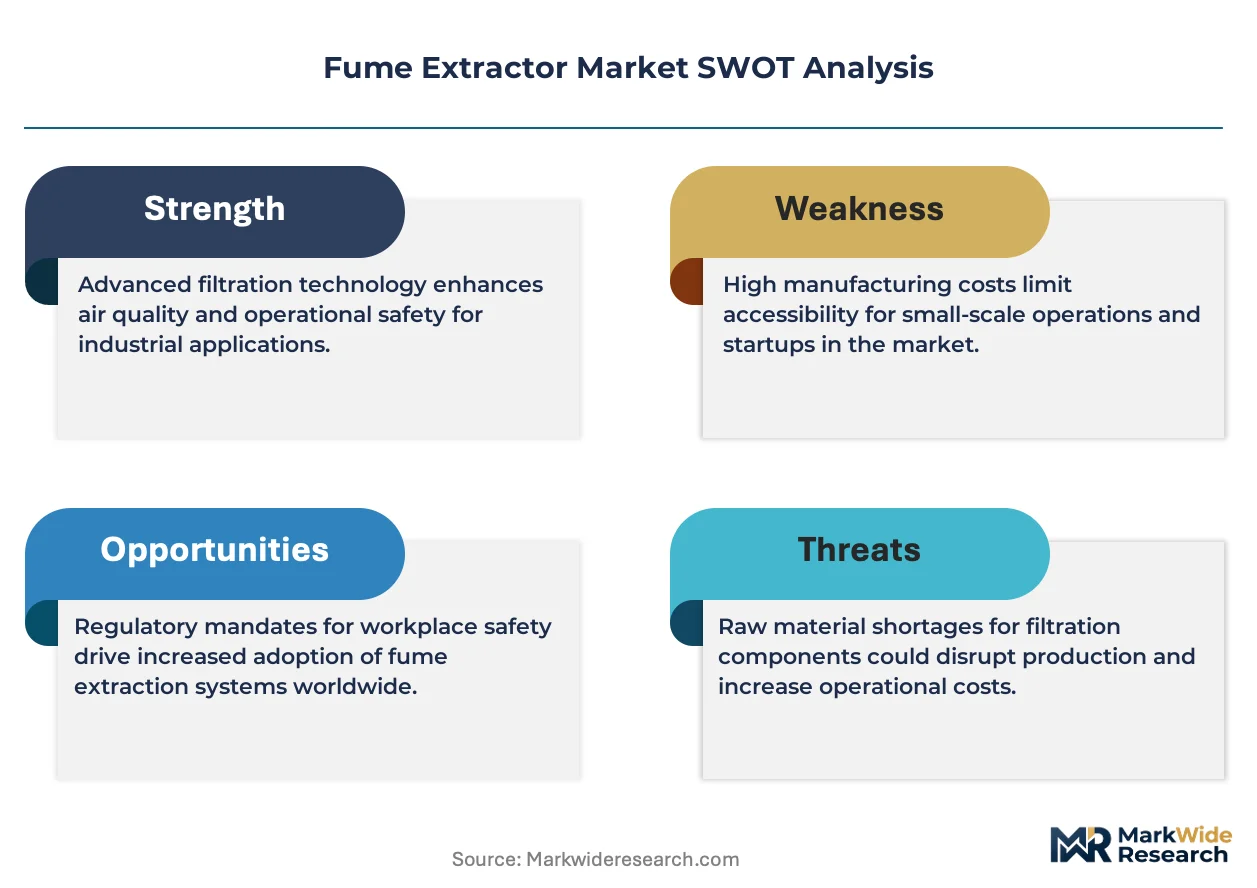
Filter media supply concentration and backward integration by welding equipment manufacturers are compressing margins for standalone fume extractor producers while raising barriers to entry for modular system integrators.
Growth Catalysts
- OSHA hexavalent chromium enforcement:Tighter permissible exposure limits in US metal fabrication shops mandate source-capture upgrades ahead of respiratory protection, driving replacement demand for legacy ambient ventilation systems.
- Automotive lightweighting:Aluminum-intensive vehicle architectures multiply welding stations per assembly plant, expanding the installed base of portable extraction arms and centralized ducted networks.
- Germany's Industrie 4.0 clusters:Metalworking concentrations in Baden-Württemberg and North Rhine-Westphalia impose municipal ventilation codes that exceed federal minimums, accelerating certified system procurement.
Market Restraints
- HEPA media supply concentration:Glass microfiber production concentrates among three European suppliers, exposing extractor manufacturers to input cost volatility and allocation rationing during demand surges.
- Electrostatic precipitator performance ceiling:Collection efficiency degrades below 0.3 microns, limiting penetration into pharmaceutical cleanroom welding where ultrafine particulate standards apply.
- REACH compliance friction:Activated carbon sourcing from coconut shell suppliers in Southeast Asia faces ECHA registration bottlenecks, delaying EU product certifications by 8-14 months.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic electric vehicle manufacturing investments create first-mover openings for source-capture vendors in Tamil Nadu and Gujarat assembly corridors.
- IoT-enabled saturation monitoring:Convergence of pressure-drop sensors with cloud analytics enables predictive filter replacement contracts, shifting revenue from hardware to recurring service streams.
- Direct-to-fabricator e-commerce:Bypassing welding distributor channels through specialized industrial marketplaces captures margin from price-sensitive job shops in Poland and Czech Republic.
Industry Challenges
- Commissioning engineer scarcity:Qualified airflow balancing technicians for centralized systems command premium wages in Germany and Austria, extending installation timelines.
- Legacy ductwork incompatibility:Retrofitting variable-frequency blowers into 1980s fixed-speed infrastructure requires custom adapter fabrication, inflating project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fume Extractor Market |
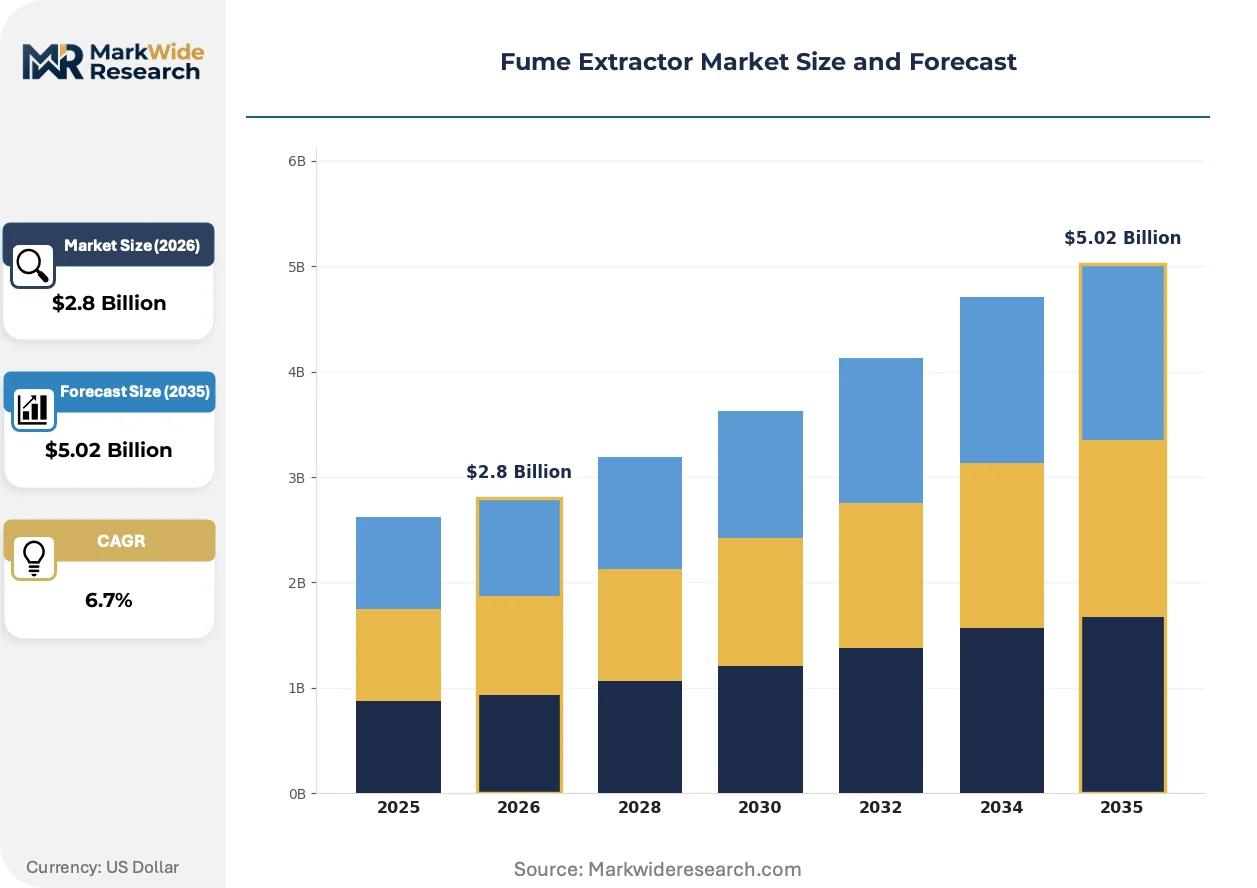
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Centralized, Mobile Technology: Electrostatic, Filtration, Ventilation, Adsorption Application: Welding, Soldering, Chemical Processing, Laboratory End User: Manufacturing, Healthcare, Education, Automotive |
| Companies Covered | Plymovent, Lincoln Electric, KEMPER, Sentry Air Systems, FUMEX, Nederman, RoboVent, Camfil, Donaldson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fume Extractor Market Emerging Trajectories
Active filtration architectures are displacing passive ambient ventilation as the default engineering control, while regulatory pressure on ultrafine particulates accelerates certification requirements for capture efficiency at the source.
Self-cleaning cartridge filters with nanofiber surface loading layers are supplanting traditional depth-loading cellulose media in high-duty-cycle welding bays. Heavy equipment manufacturers in South Korea and Japan specify these systems for 24-hour production lines. The technology is compressing filter replacement intervals from quarterly to biennial cycles, reshaping aftermarket revenue models toward monitoring hardware rather than consumables.
REACH authorization requirements for hexavalent chromium compounds are extending compliance obligations from chemical producers to downstream metal finishers using plasma cutting and welding processes. ECHA's 2023 restriction proposal forces fabricators to document source-capture effectiveness as a condition of continued substance use. German automotive suppliers have responded fastest, embedding extraction performance data into supplier quality audits.
Rental and lease-to-own arrangements for portable extraction units are displacing outright purchase in North American job shops facing capital rationing. Welding equipment distributors in Texas and Ohio now bundle monthly extraction fees with wire and gas supply contracts. The model concentrates most rapidly among collision repair networks where workstation turnover matches vehicle model cycles.
Fume Extractor Market Segmentation
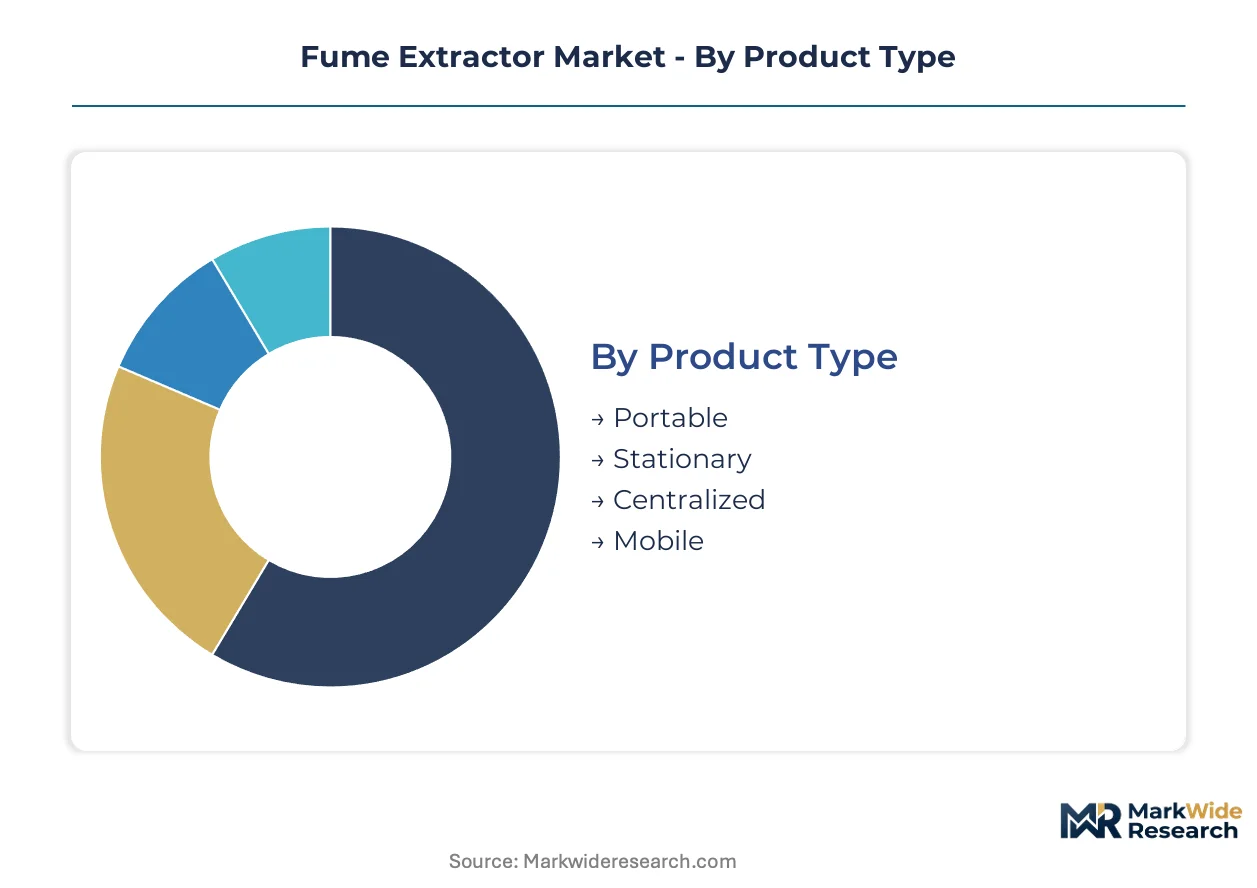
Fume extractor procurement patterns diverge sharply between mobile job-shop environments and fixed heavy-manufacturing installations. Segmentation reveals how compliance mandates and lifecycle economics reshape vendor priorities across product architectures, capture technologies, and end-use verticals.
Product Type:
Portable and mobile units dominate export flows to emerging fabrication clusters, while centralized systems anchor domestic replacement cycles in Germany and the US.
- Portable:Self-contained units with articulated extraction arms and caster-mounted frames serve job shops where workstation reconfiguration occurs weekly. OSHA hexavalent chromium enforcement in Texas and Ohio collision repair networks accelerates quarterly replacement cycles for legacy ambient systems.
- Stationary:Fixed-position cabinet systems with internal blowers and cartridge filtration anchor single-station welding bays in mid-volume metal fabrication. Demand concentrates in Baden-Württemberg automotive supplier parks where municipal ventilation codes exceed federal minimums.
- Centralized:Ducted networks with remote blower houses and manifolded hood arrays command lifecycle economics in 24-hour production environments.
- Mobile:Battery-powered or pneumatic units without permanent electrical connection serve field welding and shipyard repair applications.
Centralized architectures hold the largest share; momentum sits with portable units in capital-rationed job shops.
Technology:
Cost tiers separate premium electrostatic systems from standard filtration and economy ventilation alternatives, with adsorption commanding niche chemical-processing premiums.
- Electrostatic:Precipitator cells with ionizing wires and collection plates deliver low pressure-drop efficiency for high-volume welding bays. South Korean heavy equipment manufacturers specify these for continuous-duty lines where energy costs dominate operating economics.
- Filtration:Multi-stage media trains with nanofiber surface-loading layers and HEPA final stages capture ultrafine particulates below 0.3 microns. German automotive suppliers embed performance data into supplier quality audits under ECHA restriction proposals.
- Ventilation:Dilution-based ambient systems with roof-mounted exhaust fans serve legacy installations where source-capture retrofit costs prove prohibitive.
- Adsorption:Activated-carbon bed systems with saturation monitoring capture volatile organic compounds in chemical processing and laboratory solvent handling.
Filtration dominates installed value; adsorption climbs fastest on REACH compliance friction in coating operations.
Application:
Volume concentration tracks metal fabrication intensity, with welding commanding the heaviest unit throughput and laboratory applications driving specification premiums.
- Welding:Source-capture systems for MIG, TIG, and stick processes address manganese and hexavalent chromium exposure in automotive assembly and structural fabrication. Aluminum-intensive vehicle architectures in US and German plants multiply extraction points per assembly line.
- Soldering:Benchtop extraction for electronics assembly captures rosin flux particulates and volatile organic compounds at printed circuit board operations.
- Chemical Processing:Corrosion-resistant hood materials and specialized carbon media handle acid fumes and solvent vapors in batch reactor operations.
- Laboratory:Ductless fume hoods with filtered exhaust serve academic and pharmaceutical research where building infrastructure modifications face regulatory delays.
Welding generates the largest unit demand; laboratory specifications carry the highest margin premiums.
End User:
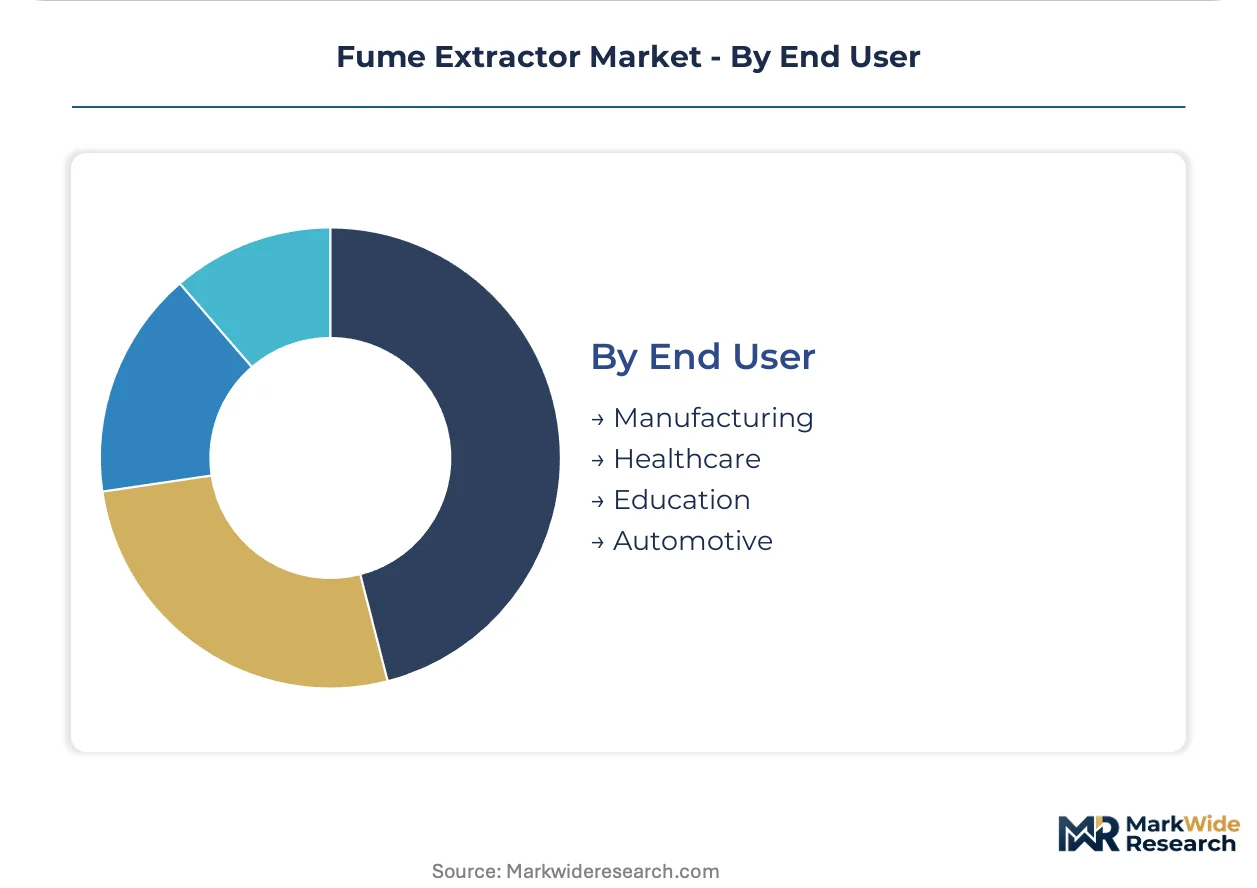
Customer type determines procurement channel—manufacturing flows through welding distributors, healthcare through facility engineering, education through capital budgets, automotive through tiered supplier mandates.
- Manufacturing:General metal fabrication, machinery production, and industrial equipment assembly drive standardized portable and stationary unit procurement. Polish and Czech job shops increasingly source through direct-to-fabricator e-commerce channels.
- Healthcare:Hospital maintenance shops and medical device manufacturing impose HEPA-grade filtration requirements with documented certification trails.
- Education:Vocational welding programs and university research facilities balance first-cost constraints against long-term service availability.
- Automotive:OEM assembly plants and tiered supplier parks mandate extraction performance as a condition of continued welding process approval under ECHA documentation requirements.
Manufacturing represents the deepest volume base; automotive commands the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command pricing premiums over Polish job shops due to tighter municipal ventilation codes and certified system mandates. This asymmetry redistributes procurement flows across Central European metalworking clusters.
United States
OSHA hexavalent chromium enforcement in Texas and Ohio collision repair networks accelerates quarterly replacement cycles for legacy ambient systems. The EPA National Emission Standards for Hazardous Air Pollutants extend source-capture requirements to coating operations. Detroit automotive assembly corridors multiply extraction points per line as aluminum-intensive vehicle architectures expand welding station density.
Germany
Baden-Württemberg and North Rhine-Westphalia municipal codes exceed federal ventilation minimums, accelerating certified system procurement among automotive tier suppliers. ECHA's 2023 restriction proposal forces fabricators to document source-capture effectiveness as a condition of continued substance use. Stuttgart supplier parks embed extraction performance data into quality audits faster than northern counterparts.
China
Domestic electric vehicle manufacturing investments in Yangtze River Delta assembly corridors create first-mover openings for source-capture vendors. MIIT industrial upgrading guidelines emphasize worker breathing-zone concentration controls in metal fabrication. Shanghai and Jiangsu province welding equipment distributors bundle extraction units with wire supply contracts.
India
PLI scheme incentives for automotive electric vehicle production concentrate new assembly investments in Tamil Nadu and Gujarat corridors. Central Electricity Authority norms for industrial ventilation compliance remain uneven across states, creating certification arbitrage opportunities. Chennai and Ahmedabad fabrication clusters source portable units through direct-to-fabricator channels bypassing traditional distributors.
Japan
METI energy efficiency standards favor electrostatic precipitator specifications in 24-hour heavy equipment production lines. JIS certification requirements for ultrafine particulate capture limit ambient ventilation retrofits in pharmaceutical-adjacent welding operations. Nagoya and Osaka industrial belts specify nanofiber surface-loading filters for biennial replacement cycles rather than quarterly consumables.
Fume Extractor Market Vendor Landscape
Concentration sits with welding equipment manufacturers who leverage backward integration into source-capture distribution channels. Filter media supply concentration among three European glass microfiber producers exposes standalone extractor manufacturers to input cost volatility. Two strategic archetypes dominate: captive filter media suppliers sustaining margin compression in portable units, and modular system integrators facing elevated barriers to entry. Competitive moves center on bundling extraction hardware with welding consumables contracts, and predictive filter replacement services shifting revenue toward recurring streams.
Among European filtration specialists, Nederman and KEMPER occupy positions anchored by regional supply chain proximity to glass microfiber producers. Lincoln Electric exemplifies the welding equipment archetype, with channel control through distributor networks creating bundled demand for source-capture systems. These three represent distinct competitive vectors: media supply integration, regional certification expertise, and downstream channel ownership.
| Leading Market Players |
|---|
| Plymovent |
| Lincoln Electric |
| KEMPER |
| Sentry Air Systems |
| FUMEX |
| Nederman |
| RoboVent |
| Camfil |
| Donaldson |
| Others |
Supply Flow & Price Mechanics
Nanofiber surface-loading layers replacing traditional cellulose depth-loading media are simultaneously shifting procurement geography toward Japanese and South Korean filter specialists and compressing replacement-cycle economics from quarterly to biennial intervals. This substitution dynamic redistributes value capture from consumables suppliers toward monitoring hardware providers while reshaping how German automotive suppliers negotiate long-term service contracts.
Pricing Analysis
Configured-to-order pricing for centralized ducted systems with custom hood geometry and variable-frequency blower matching commands 40-60% premiums over standard portable unit list prices. Three-tier pricing structure across premium certified systems, standard industrial units, and economy ventilation alternatives separates buyers by compliance mandate stringency rather than capture technology alone. Cost compression in economy tiers is intensifying because Polish and Czech job shops increasingly source through direct-to-fabricator e-commerce channels that bypass traditional welding distributor markups. Collision repair networks in Texas and Ohio show highest price sensitivity, while German automotive tier suppliers accept premium positioning to satisfy ECHA documentation requirements.
Supply Chain Analysis
Germany and the Czech Republic anchor glass microfiber HEPA media production, with three European suppliers concentrating supply of this critical input. Filter media supply draws from coconut shell activated carbon sources in Southeast Asia, creating REACH registration bottlenecks that delay EU product certifications. Single-source vulnerability in HEPA media exposes extractor manufacturers to allocation rationing during demand surges in automotive lightweighting cycles. Distribution runs through welding equipment distributor networks that bundle extraction hardware with wire and gas supply contracts, though direct-to-fabricator channels are gaining share in capital-rationed job shop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA hexavalent chromium enforcement and ECHA restriction proposals are accelerating a regulatory inflection that transforms fume extraction from discretionary capital equipment into mandated compliance infrastructure. This disruption expands addressable market boundaries while compressing margins for undifferentiated ambient ventilation alternatives.
For Market Incumbents: Consolidate filter media supply positions through captive production or long-term offtake agreements with European glass microfiber suppliers to defend against input cost volatility. Deepen backward integration into welding equipment distribution channels to preserve bundled demand against modular system integrators, while embedding IoT-enabled saturation monitoring to shift revenue toward recurring service streams that lock in replacement cycles.
For New Entrants and Emerging Players: Differentiate on predictive maintenance analytics and cloud-based filter lifecycle management rather than hardware capture efficiency alone. Target India's PLI scheme corridors in Tamil Nadu and Gujarat where domestic electric vehicle assembly investments create first-mover openings for source-capture vendors ahead of incumbent channel establishment. Pursue direct-to-fabricator e-commerce routes in Poland and Czech Republic to capture margin from price-sensitive job shops that traditional distributors underserve.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed modular system integrators lacking captive filter media supply or welding equipment channel control. Five-to-ten year viability hinges on regulatory ratchet effects that make source-capture compliance irreversible across US and EU metal fabrication. Watch for state-level adoption of California's more stringent occupational exposure limits as the signal indicating accelerated replacement demand propagation eastward.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive HEPA supply insulates margin compression from European glass microfiber allocation rationing. |
| IoT-Enabled Predictive Maintenance | Pressure-drop sensor convergence shifts revenue from hardware sales toward recurring monitoring service contracts. |
| Direct-to-Fabricator E-Commerce | Bypassing welding distributor channels captures margin from price-sensitive Polish and Czech job shops. |
| Certification Pre-Positioning for REACH | ECHA documentation requirements favor vendors with established EU regulatory compliance infrastructure. |
| Geographic Expansion into PLI Corridors | Tamil Nadu and Gujarat electric vehicle assembly investments create first-mover source-capture procurement openings. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at automotive assembly facilities, welding distributor procurement heads, aftermarket service managers, and regulatory compliance officers at metal fabrication shops. Secondary validation drew from OSHA enforcement databases, ECHA restriction proposal documentation, SEC filings of welding equipment manufacturers, and customs trade data on filter media imports. Bottom-up unit demand estimates by product architecture and capture technology were triangulated against top-down market value reconstruction from reported segment revenues.
Across the analysis window, volume and value outputs reflect segmentation modeling by product type, capture technology, end-use vertical, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical replacement cycle data against compliance mandate adoption curves, with specific inputs including aluminum-intensive vehicle architecture penetration rates and municipal ventilation code escalation patterns in German industrial belts.
Forecasts assume regulatory continuity in OSHA permissible exposure limit enforcement and ECHA authorization frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include HEPA media supply disruption from European producer consolidation, accelerated state-level adoption of California exposure limits, or breakthrough electrostatic precipitator efficiency gains below 0.3 microns. Recalibration cycles align with material shifts in hexavalent chromium enforcement intensity and automotive lightweighting investment trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Fans and Blowers Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Global Temperature Control Units (TCU) Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Anti-Vibration Mounts Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Photography Panoramic Tripod Heads Market