
 Global Industrial Dispensing System and Equipment Market | 2026-2036
Global Industrial Dispensing System and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Dispensing System and Equipment Market Intelligence
Advanced polymer formulations are pivoting away from solvent-heavy chemistries toward UV-curable and hot-melt platforms that reduce volatile emissions and shorten cure cycles. Nordson Corporation leverages its melt delivery expertise to anchor high-throughput packaging lines across North America. Graco Inc. competes through modular pump architectures that sustain field upgradeability for chemical processors. Dymax Corporation differentiates via light-curing system integration that dominates electronics micro-assembly applications.
Industrial dispensing systems and equipment encompass precision fluid handling machinery engineered to deposit adhesives, sealants, lubricants, and coatings at controlled volumes, pressures, and repeatability tolerances typically measured in microliters or milligrams per cycle. These systems integrate programmable motion controllers, positive-displacement pumps or valves, and vision feedback to execute automated material placement across continuous production environments. Automation systems lead equipment investment as manufacturers prioritize throughput consistency and labor reduction in high-mix assembly. Servo motor technology occupies the fastest-expanding pump control category, displacing pneumatic alternatives where positional accuracy determines bond line quality. Adhesive bonding applications command the largest share of end-use demand, driven by structural joining requirements in electric vehicle battery pack assembly and consumer electronics miniaturization.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that constrain solvent-based dispensing processes in US manufacturing facilities. ECHA administers REACH authorization lists that restrict Substances of Very High Concern in European adhesive formulations, redirecting procurement toward compliant material portfolios. FDA cGMP regulations govern fluid contact surfaces and cleaning validation protocols for pharmaceutical producers deploying dosing equipment. Stakeholders must monitor evolving chemical restriction schedules across multiple jurisdictions to preempt supply chain disruption and secure product registration timelines.
Market Dynamics
Automotive lightweighting mandates and precision electronics miniaturization are converging to force dispensing equipment toward sub-microliter accuracy at cycle speeds exceeding 500 deposits per minute. This technical compression is restructuring supplier capabilities across all geographies.
Growth Catalysts
- Electric vehicle battery pack assembly:Structural adhesive bonding replaces mechanical fasteners in pouch cell and module construction, requiring volumetric dispensing systems with closed-loop pressure control.
- REACH authorization timelines:ECHA restriction lists on hexavalent chromium and certain isocyanates redirect European formulators toward compliant hot-melt and UV-curable platforms that demand precision temperature and irradiance management.
- Servo motor pump architectures:Positional accuracy below 0.5% variance enables micro-dot dispensing in semiconductor underfill and display lamination applications across South Korean and Taiwanese manufacturing corridors.
Market Restraints
- Specialized ceramic and tungsten carbide supply concentration:Wear-resistant pump components depend on Chinese and German raw material processors subject to export licensing volatility.
- Fluoropolymer seal compatibility constraints:Aggressive reactive chemistries degrade standard elastomers, forcing extended validation cycles for perfluoroelastomer alternatives.
- EPA NESHAP compliance costs:Solvent capture and thermal oxidizer requirements add capital burden to US facilities running legacy pneumatic systems.
Strategic Opportunities
- Czech Republic precision manufacturing corridor:Automotive electronics clustering near Ostrava and Brno creates demand for integrated vision-guided dispensing cells with sub-50-micron placement repeatability.
- ISO 14644 cleanroom convergence:Semiconductor and pharmaceutical dispensing specifications are merging, enabling platform reuse across historically siloed end-use verticals.
- India PLI scheme for electronics manufacturing:Contract assembly incentives in Noida and Sriperumbudur attract dispensing system deployment for smartphone and component production.
Industry Challenges
- Multi-axis motion programming expertise:Shortage of technicians capable of integrating dispensing paths with SCARA and Cartesian robot controllers extends commissioning timelines.
- FDA cGMP cleaning validation:Pharmaceutical fluid contact surfaces require documented elimination of prior material residues, complicating rapid product changeover protocols.
- Legacy pneumatic-to-servo retrofit integration:Existing production lines face mechanical incompatibility when upgrading to closed-loop displacement control without full line reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Dispensing System and Equipment Market |
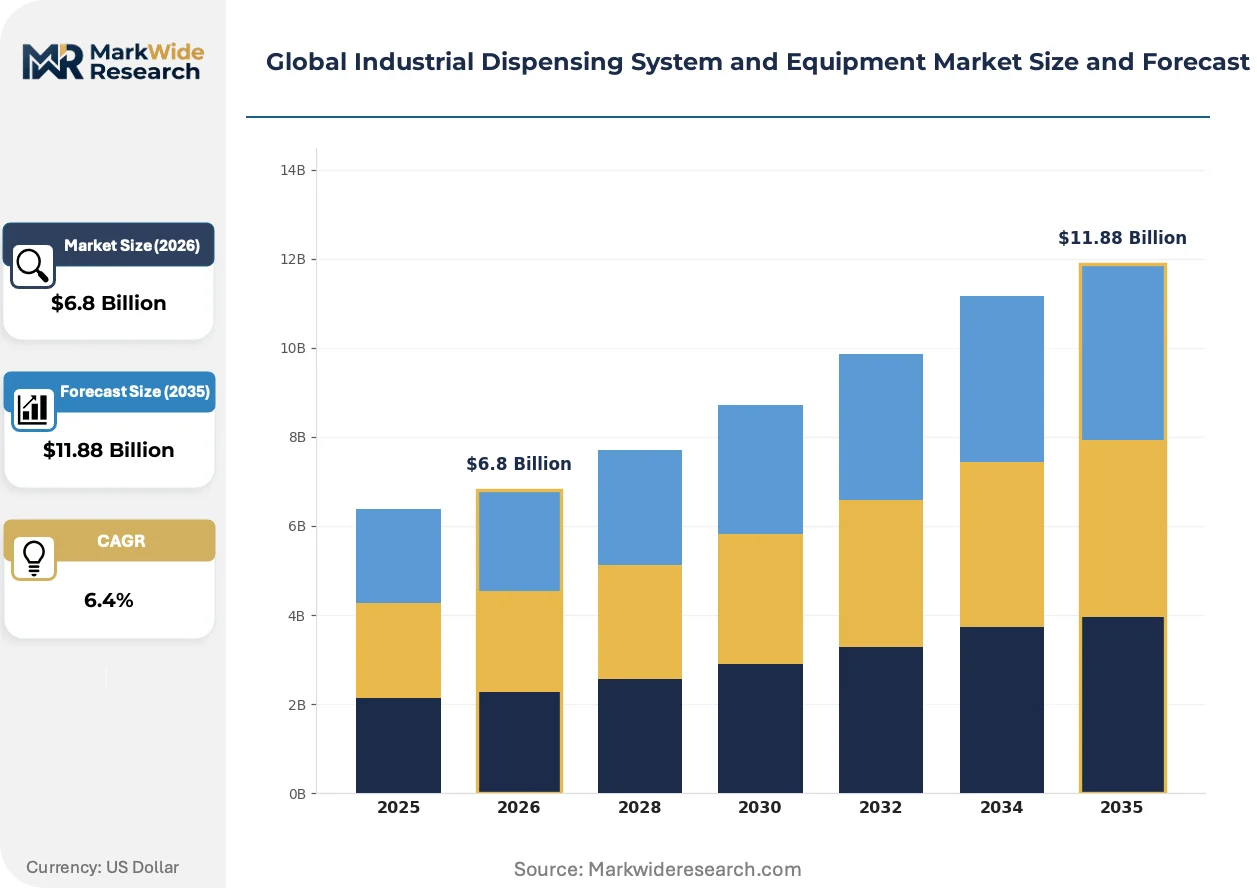
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispensers, Pneumatic Dispensers, Electric Dispensing Guns, Metering Pumps, Automation Systems Technology: Servo Motor, Reciprocating Pump, Peristaltic Pump, Diaphragm Pump, Gear Pump, Progressive Cavity Pump Application: Adhesive Bonding, Lubrication, Sealant Application, Fluid Transfer, Coating, Dosing End User: Electronics Manufacturers, Aerospace Assemblers, Food Packaging Plants, Chemical Processors, Pharmaceutical Producers |
| Companies Covered | Nordson Corporation, Graco Inc., Dymax Corporation, Fisnar Inc., DELO, ViscoTec, Hernon Manufacturing Inc., Hitachi High-Tech Corporation, GPD Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Dispensing System and Equipment Market Strategic Shifts & Innovations
Three distinct vectors are compressing equipment development cycles: precision hardware miniaturization, regulatory chemistry constraints, and buyer procurement model rationalization. Each vector demands concurrent engineering responses from incumbent suppliers.
Jet valve technology with piezoelectric actuation is automating non-contact dispensing for fragile substrates in flexible printed circuit and micro-LED assembly. Display manufacturers in Taiwan and South Korea are deploying these systems at line speeds previously reserved for contact-needle architectures. The elimination of Z-axis travel is compressing cycle times while reducing mechanical wear on dispensing components.
REACH authorization procedures for Substances of Very High Concern are forcing European adhesive formulators to eliminate solvent-based systems ahead of scheduled sunset dates. Industrial end-users in Germany and the Czech Republic are qualifying UV-curable and moisture-cure platforms that require irradiance and humidity control modules not present in legacy equipment. This chemistry pivot is accelerating capital refresh cycles among tier-one automotive suppliers.
Contract electronics manufacturers are consolidating supplier relationships from multiple regional distributors toward direct OEM partnerships with integrated service agreements. Tier-one assemblers in Mexico and Vietnam now demand predictive maintenance telemetry and remote diagnostics as standard procurement terms rather than premium add-ons. This channel compression is favoring equipment vendors with captive software and field service organizations over component-centric distributors.
Global Industrial Dispensing System and Equipment Market Segmentation
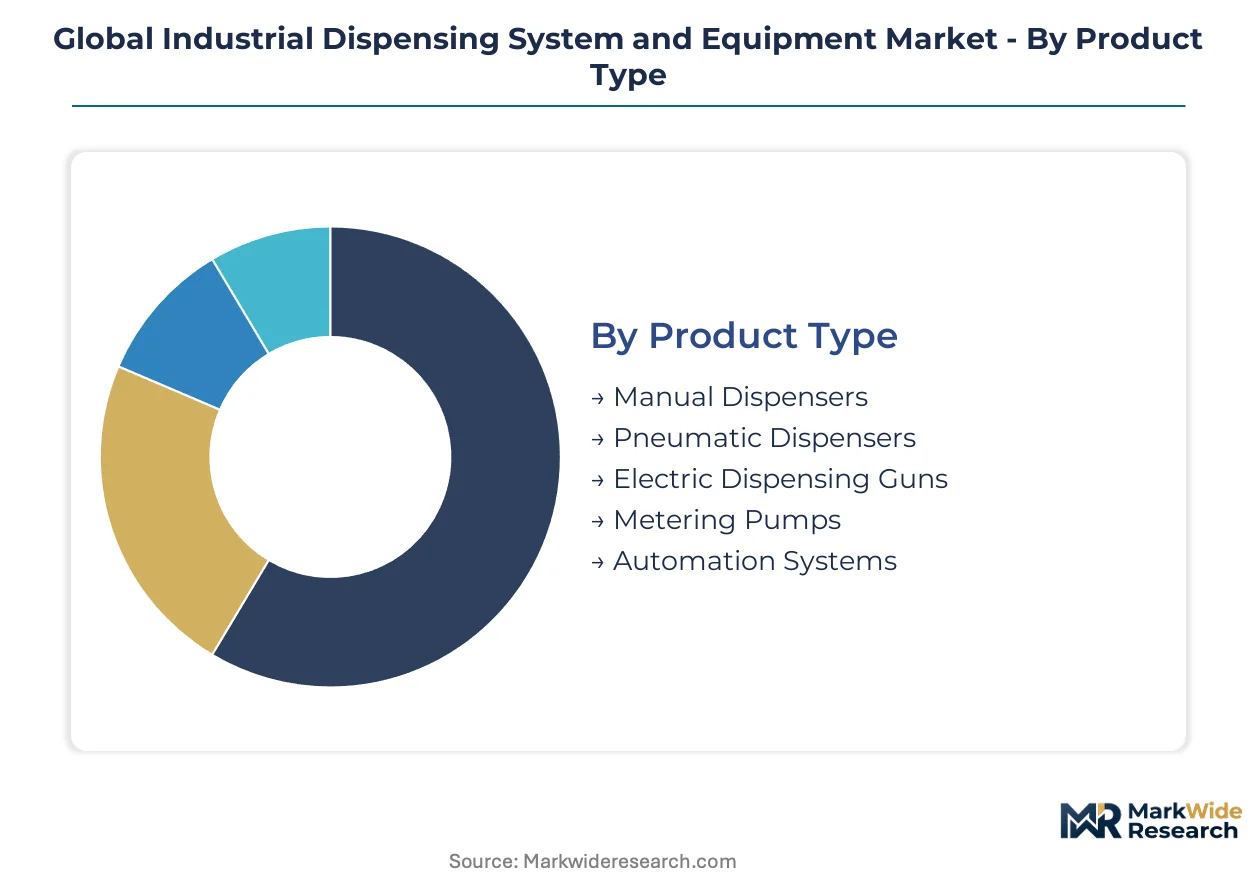
Equipment specifications diverge sharply between high-volume automotive lines requiring sub-microliter repeatability and batch pharmaceutical operations governed by FDA cGMP validation protocols. Segmentation reveals how pump architecture, control technology, and end-use compliance requirements partition supplier capabilities and buyer procurement criteria across manufacturing verticals.
Product Type:
Customization intensity spans from handheld units for prototype shops to fully integrated cells demanding six-month commissioning cycles, with standardization concentrated in mid-tier pneumatic platforms.
- Automation Systems:Multi-axis Cartesian and SCARA-integrated cells execute vision-guided deposition paths with closed-loop feedback. Electric vehicle battery pack assembly in Germany and South Korea drives demand for volumetric dispensing modules with real-time pressure compensation and traceable cycle data logging.
- Metering Pumps:Positive-displacement architectures with ceramic or tungsten carbide internals deliver abrasive sealants and thermal interface materials at controlled ratios. Chemical processors in the Czech Republic and Texas deploy these for two-component reactive systems where mix ratio variance compromises bond integrity.
- Pneumatic Dispensers:Compressed-air actuation dominates legacy packaging and construction applications where capital constraints outweigh precision requirements.
- Electric Dispensing Guns:Battery-powered portability serves field service and MRO environments lacking compressed air infrastructure.
- Manual Dispensers:Hand-actuated syringe barrels and squeeze bottles persist in low-volume electronics rework and dental laboratory applications.
Most installed capacity flows through Pneumatic Dispensers. Expansion is steepest in Automation Systems.
Technology:
Cost tiers separate commodity pump architectures from precision motion platforms, with servo motor systems commanding 3-4x the unit economics of pneumatic alternatives.
- Servo Motor:Closed-loop rotary encoders enable positional accuracy below 0.5% variance for micro-dot semiconductor underfill. Display lamination corridors in Taiwan and South Korea specify these systems for sub-50-micron placement repeatability at cycle speeds exceeding 500 deposits per minute.
- Peristaltic Pump:Roller-occlusion mechanisms eliminate fluid contact with mechanical components, satisfying FDA cGMP cleaning validation for pharmaceutical dosing. Biologics producers in Massachusetts and North Carolina favor these for sterile single-use fluid paths that reduce cross-contamination risk.
- Gear Pump:Meshing precision gears meter consistent volumes of medium-viscosity adhesives and coatings in automotive assembly.
- Diaphragm Pump:Pneumatically or electrically actuated membranes isolate aggressive chemistries from drive mechanisms in chemical processing.
- Reciprocating Pump:Piston-based displacement handles high-pressure sealant injection in construction and marine applications.
- Progressive Cavity Pump:Helical rotor-stator geometry conveys shear-sensitive and abrasive materials in food and mining operations.
Volume concentration sits with Gear Pumps across general industrial applications. Servo Motor architectures are climbing the fastest as electronics miniaturization demands escalate.
Application:
Application maturity correlates with chemistry evolution—adhesive bonding commands established process knowledge while dosing applications face emerging regulatory complexity.
- Adhesive Bonding:Structural joining of dissimilar materials replaces mechanical fasteners in lightweighting programs. REACH authorization timelines for hexavalent chromium and isocyanate restrictions in Europe redirect German and Czech automotive suppliers toward UV-curable platforms requiring irradiance control modules.
- Dosing:Volumetric accuracy for pharmaceutical active ingredients and biologics demands FDA-validated fluid contact surfaces with documented cleaning elimination of prior residues. Injectable drug producers in New Jersey and Switzerland specify perfluoroelastomer seals and electropolished 316L stainless steel flow paths.
- Sealant Application:Gap-filling and environmental protection in transportation and construction assemblies.
- Coating:Thin-film deposition for conformal protection and aesthetic finishing across electronics and consumer goods.
- Lubrication:Controlled grease and oil delivery in bearing assembly and maintenance operations.
- Fluid Transfer:Bulk material movement between process vessels with less stringent precision requirements.
Revenue scale peaks in Adhesive Bonding. Dosing applications are gaining share fastest on biologics capacity expansion.
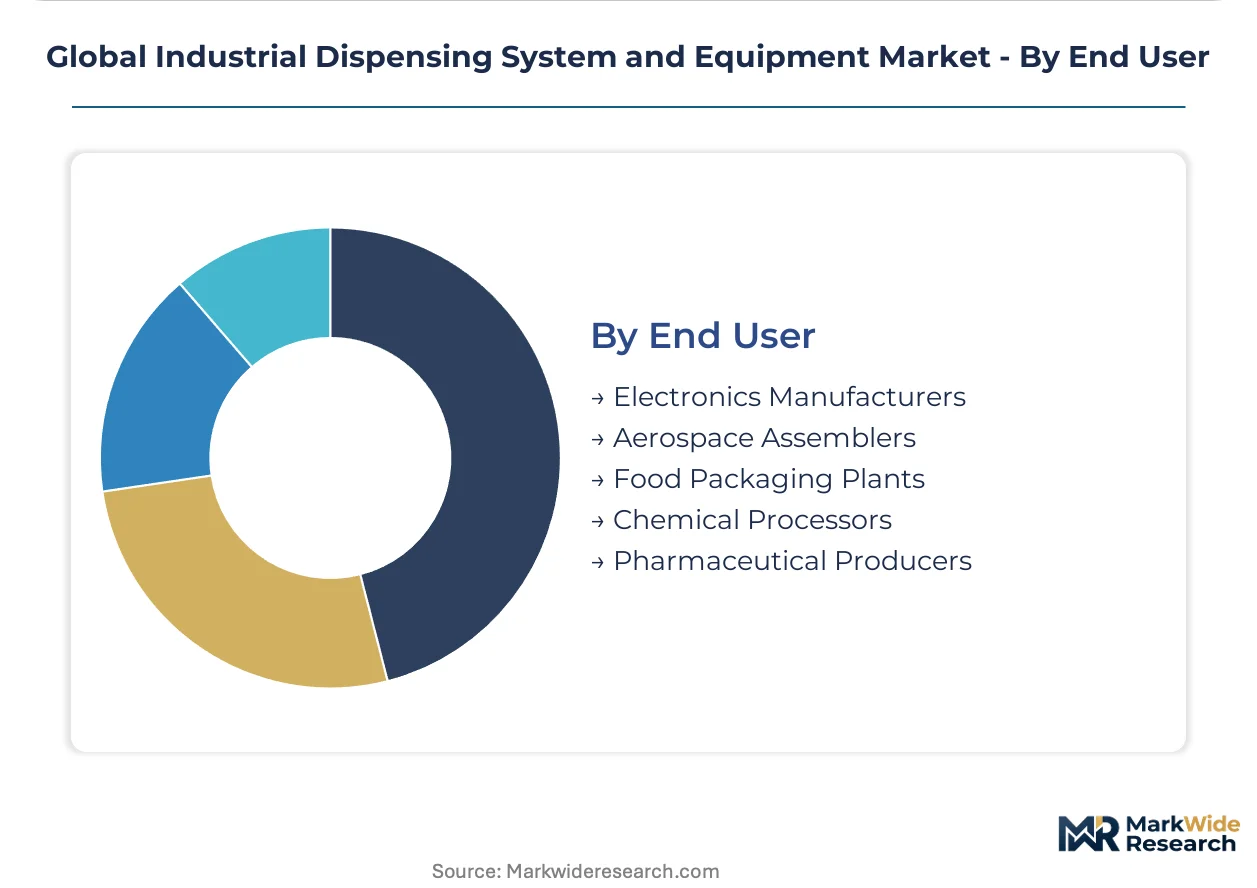
End User:
Customer type determines procurement modality—electronics assemblers consolidate toward direct OEM partnerships while food packaging relies on regional distributor networks.
- Electronics Manufacturers:Contract assemblers in Mexico and Vietnam now mandate predictive maintenance telemetry and remote diagnostics as standard procurement terms. Smartphone production clusters in Noida and Sriperumbudur under India's PLI scheme attract integrated vision-guided dispensing cells with sub-50-micron repeatability.
- Pharmaceutical Producers:FDA cGMP regulations govern fluid contact surfaces, cleaning validation protocols, and batch record documentation for dosing equipment. Sterile fill-finish operations in Ireland and Singapore require ISO 14644 cleanroom convergence with semiconductor-grade particulate control.
- Aerospace Assemblers:Structural adhesive bonding for airframe and engine components with NADCAP and AS9100 quality system requirements.
- Chemical Processors:Modular pump architectures sustaining field upgradeability for aggressive reactive chemistries.
- Food Packaging Plants:Hygienic design standards with 3-A Sanitary and EHEDG certification for edible oil and condiment dispensing.
Equipment density concentrates in Electronics Manufacturers. Pharmaceutical Producers are expanding most quickly on biologics manufacturing investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive corridors anchor precision dispensing demand as lightweighting programs accelerate adhesive bonding adoption across European manufacturing.
United States
EPA NESHAP enforcement tightens solvent capture requirements for automotive and electronics manufacturers in Michigan and Texas. FDA cGMP protocols govern pharmaceutical dispensing equipment deployed across New Jersey and Massachusetts biologics clusters. Contract electronics assemblers in Mexico border zones now mandate predictive maintenance telemetry as standard procurement terms.
Germany
ECHA REACH authorization timelines for hexavalent chromium redirect automotive suppliers toward UV-curable adhesive platforms. KBA vehicle safety standards reinforce structural bonding validation requirements for electric vehicle battery packs. Industrial dispensing system deployment concentrates in Stuttgart and Munich automotive electronics corridors.
South Korea
MFDS pharmaceutical regulations converge with semiconductor-grade cleanroom standards for biologics manufacturing investment. Display lamination and micro-LED assembly in Gyeonggi Province specify servo motor pump architectures with sub-50-micron placement repeatability. Samsung and LG supply chain localization drives domestic dispensing equipment qualification.
China
MEE emission standards and dual carbon goals compress solvent-based process adoption in Yangtze River Delta manufacturing. NMPA pharmaceutical regulations govern fluid contact surface validation for dosing equipment in Jiangsu and Zhejiang provinces. Domestic pump component suppliers in Shenzhen and Suzhou challenge German and Japanese import dominance.
India
PLI scheme incentives for electronics manufacturing attract dispensing system deployment to Noida and Sriperumbudur smartphone assembly clusters. BIS certification requirements for industrial machinery create compliance barriers for European and Japanese equipment imports. Tamil Nadu and Karnataka precision manufacturing corridors drive demand for vision-guided dispensing cells.
Global Industrial Dispensing System and Equipment Market Key Industry Players
Strategic partnerships dominate the current landscape as equipment vendors integrate software and service capabilities to meet consolidated procurement demands from tier-one contract manufacturers. The vendor base separates into three functional tiers: integrated motion platform specialists, precision pump component fabricators, and chemistry-agnostic system integrators. Geographic expansion and technology licensing represent the two primary competitive vectors, with European and North American incumbents licensing servo control architectures to Asian manufacturing partners.
Among North American platform specialists, Nordson Corporation exemplifies the integrated motion tier through its melt delivery expertise anchoring high-throughput packaging lines. Graco Inc. occupies the modular pump architecture segment where field upgradeability sustains chemical processor relationships. Dymax Corporation represents the light-curing system specialization that dominates electronics micro-assembly applications across Taiwanese and South Korean manufacturing corridors.
| Leading Market Players |
|---|
| Nordson Corporation |
| Graco Inc. |
| Dymax Corporation |
| Fisnar Inc. |
| DELO |
| ViscoTec |
| Hernon Manufacturing Inc. |
| Hitachi High-Tech Corporation |
| GPD Global |
| Others |
Cost & Logistics Intelligence
Contract electronics manufacturers in Mexico and Vietnam now mandate predictive maintenance telemetry and remote diagnostics as standard procurement terms, forcing equipment vendors to absorb software development costs and compress hardware margins across all tiers. This buyer-driven specification convergence is restructuring supplier economics toward bundled service contracts and away from discrete equipment sales.
Pricing Analysis
Ceramic and tungsten carbide pump component costs pass through directly to end-user pricing, with Chinese and German raw material processors subject to export licensing volatility that amplifies quote uncertainty. Three-tier pricing structure across premium, standard, and economy levels separates servo motor automation systems from pneumatic dispensers and manual units. Pricing pressure stems from contract manufacturers consolidating supplier relationships toward direct OEM partnerships with integrated service agreements. Electronics assemblers in high-volume corridors exhibit lowest price sensitivity due to throughput consistency requirements, while prototype shops and MRO environments face acute capital constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from tier-one contract manufacturers, displacing regional distributor networks in Mexico, Vietnam, and India. Manufacturing concentration centers on Germany, Japan, and China for precision motion controllers, positive-displacement pumps, and vision feedback systems. Supply chains draw from specialized ceramic and tungsten carbide processors in China and Germany, perfluoroelastomer seal fabricators, and servo motor component suppliers. Single-source vulnerability in wear-resistant pump materials exposes equipment lead times to export licensing disruptions. Distribution runs through integrated OEM partnerships with captive field service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge from regulatory compliance cost differentials between EPA NESHAP-constrained US facilities and India's PLI scheme-subsidized electronics corridors, where capital equipment depreciation allowances compress total cost of ownership.
For Market Incumbents: Cement market position through backward integration into ceramic and tungsten carbide pump component supply and predictive maintenance software platforms. Capacity addition in India's Tamil Nadu and Karnataka precision manufacturing corridors captures PLI scheme inflows. Certification investment in FDA cGMP and ISO 14644 cleanroom protocols defends against modular pump architecture competitors. For New Entrants and Emerging Players: Enter via underserved pharmaceutical dosing segments in India and Southeast Asia where FDA cGMP validation expertise concentrates among incumbent specialists. White-space targets include peristaltic pump systems for biologics manufacturing and field-upgradeable metering pump architectures for Czech Republic chemical processors. Go-to-market through direct OEM partnerships with integrated service agreements rather than distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with servo motor control specialists possessing software-defined dispensing platforms and established cleanroom equipment footprints. Long-term viability over the next decade hinges on chemistry-agnostic system architectures that pivot between adhesive bonding and pharmaceutical dosing applications. Acquisition target archetype: mid-cap precision pump fabricators with tungsten carbide processing capabilities and existing automotive electronics customer relationships. Signal to watch: REACH authorization timeline acceleration forcing European formulator capital refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Components | Captive supply of wear-resistant pump internals insulates against Chinese and German export licensing volatility. |
| Predictive Maintenance Platform Launch | Remote diagnostics capabilities satisfy Mexico and Vietnam contract assembler procurement mandates. |
| Cleanroom Convergence Certification | ISO 14644 validation enables platform reuse across semiconductor and pharmaceutical dispensing verticals. |
| Joint Venture in Indian Electronics Corridors | PLI scheme access in Noida and Sriperumbudur captures smartphone assembly equipment demand. |
| UV-Curable Chemistry Integration | Irradiance control modules address REACH-driven European automotive supplier capital refresh cycles. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners. Secondary validation draws from SEC 10-K filings, customs and trade data, industry association reports, and regulatory filing databases. Bottom-up equipment shipment analysis and top-down manufacturing value-added estimates were triangulated to establish market sizing.
Rate-of-change decomposition across the analysis window isolates volume growth from price-mix effects and technology substitution patterns. Segmentation dimensions modeled include equipment type, pump control technology, application chemistry, end-use vertical, and regional production cluster. CAGRs were derived from trend extrapolation of historical shipment data, adjusted for regulatory-driven replacement cycle acceleration and buyer consolidation effects. Forecast inputs incorporate REACH authorization timelines, EPA NESHAP enforcement schedules, and PLI scheme incentive disbursement patterns.
Inputs from plant engineers and procurement leads were available through the study window; gaps in real-time pricing data from distributor channels introduce uncertainty bands around pneumatic dispenser segment estimates. Forecasts reflect assumptions regarding regulatory compliance cost pass-through rates and contract manufacturer consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Jet Dispenser Market
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Fluid Dispensing Equipment Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Industrial Lasers Systems Market