
 Cartridge Heaters Market | 2026-2036
Cartridge Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Cartridge Heaters Market Analysis
China is reconfiguring regional supply dynamics through expanded stainless steel fabrication capacity serving thermal component OEMs. Watlow leverages vertically integrated sensor-heater architectures across North American plastics markets. Chromalox sustains technical leadership in high-temperature Incoloy designs for aerospace test rigs. Tutco anchors European demand through localized production of custom watt-density configurations.
A cartridge heater is a cylindrical electric heating element, typically 0.25 to 1.0 inch in diameter, comprising a nickel-chromium resistance wire embedded in magnesium oxide insulation and sheathed in stainless steel or Incoloy, designed to deliver concentrated heat transfer into metal blocks, dies, or process equipment. Standard cartridge heaters dominate volume shipments across general industrial warming applications, while high-temperature cartridges command premium positioning in aerospace component curing where sustained operation above 1400°F is required. Custom cartridge configurations capture specialized margin pools as medical device manufacturers specify tight thermal uniformity tolerances for diagnostic instrument heating zones.
OSHA electrical safety standards and the EU Machinery Directive shape product certification requirements, compelling manufacturers to validate insulation resistance and dielectric strength before market entry. The EPA's energy efficiency guidelines for industrial equipment nudge end users toward cartridge heaters with optimized watt density profiles that reduce parasitic heat loss. Stakeholders must monitor how evolving semiconductor equipment thermal specifications redirect precision heater demand toward sub-miniature geometries with integrated thermocouple feedback loops.
Market Dynamics
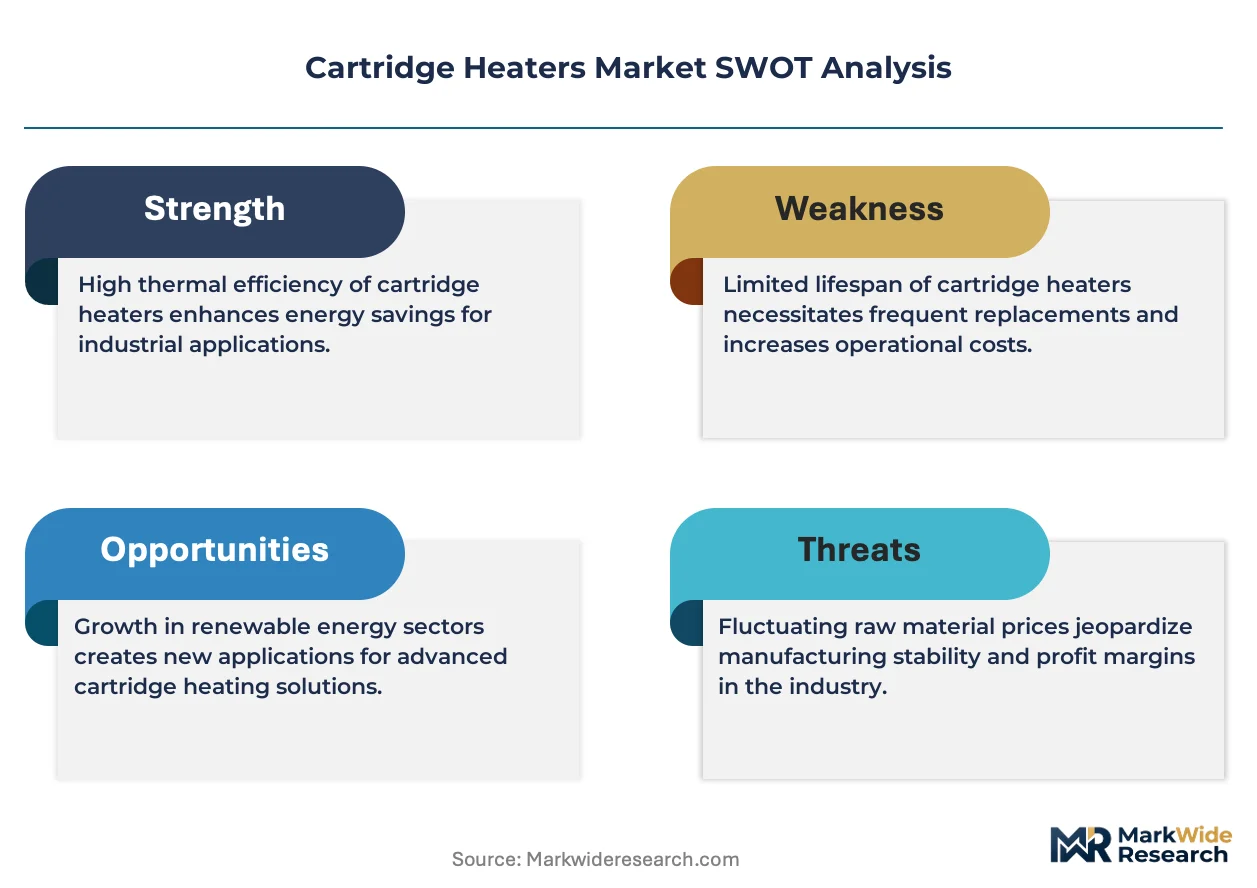
Plastics processing equipment manufacturers are modernizing extrusion and injection molding lines, creating concentrated demand for precision thermal components with tighter watt-density tolerances and faster thermal response profiles.
Growth Catalysts
- EU F-Gas Regulation:OEMs across Germany's industrial manufacturing corridor are accelerating adoption of electrically heated solutions to comply with thermal emission reduction mandates, favoring cartridge heaters over gas-fired alternatives.
- Semiconductor equipment specifications:Thermal engineering for wafer processing is demanding sub-miniature heater geometries with integrated thermocouple feedback loops, pulling innovation investment toward precision cartridge architectures.
- Aerospace component curing:Sustained operation above 1400°F requirements for composite bonding and curing applications is expanding the addressable market for high-temperature Incoloy-sheathed cartridges.
Market Restraints
- Nickel-chromium wire supply concentration:Resistance wire sourcing depends on a narrow supplier base concentrated in stainless steel fabrication clusters, exposing OEMs to raw material availability volatility.
- Magnesium oxide insulation purity standards:Dielectric strength validation requirements under OSHA electrical safety standards create certification bottlenecks that extend time-to-market for new product introductions.
- Induction heating substitution:Non-contact thermal solutions are capturing share in high-temperature metal processing applications where rapid heat cycling reduces cartridge heater lifecycle economics.
Strategic Opportunities
- Medical device thermal uniformity:Diagnostic instrument manufacturers are specifying tight temperature tolerances for heating zones, creating specialized margin pools for custom cartridge configurations with zone-controlled watt density.
- China stainless steel fabrication expansion:Regional supply dynamics are reconfiguring as expanded domestic capacity serving thermal component OEMs reduces import dependency and shortens lead times.
- EPA energy efficiency guidelines:Industrial equipment standards are nudging end users toward optimized watt density profiles that reduce parasitic heat loss, favoring premium cartridge designs over commodity alternatives.
Industry Challenges
- Thermal engineering talent scarcity:Precision heater design requires specialized expertise in heat transfer modeling and materials science that outpaces current vocational training pipeline output.
- Legacy die integration complexity:Retrofitting existing metal blocks and process equipment with modern cartridge configurations often requires custom machining that extends deployment timelines and elevates project risk.
- REACH compliance documentation:Material substance declarations for magnesium oxide insulation and sheath alloys create administrative burden that smaller manufacturers struggle to resource adequately.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cartridge Heaters Market |
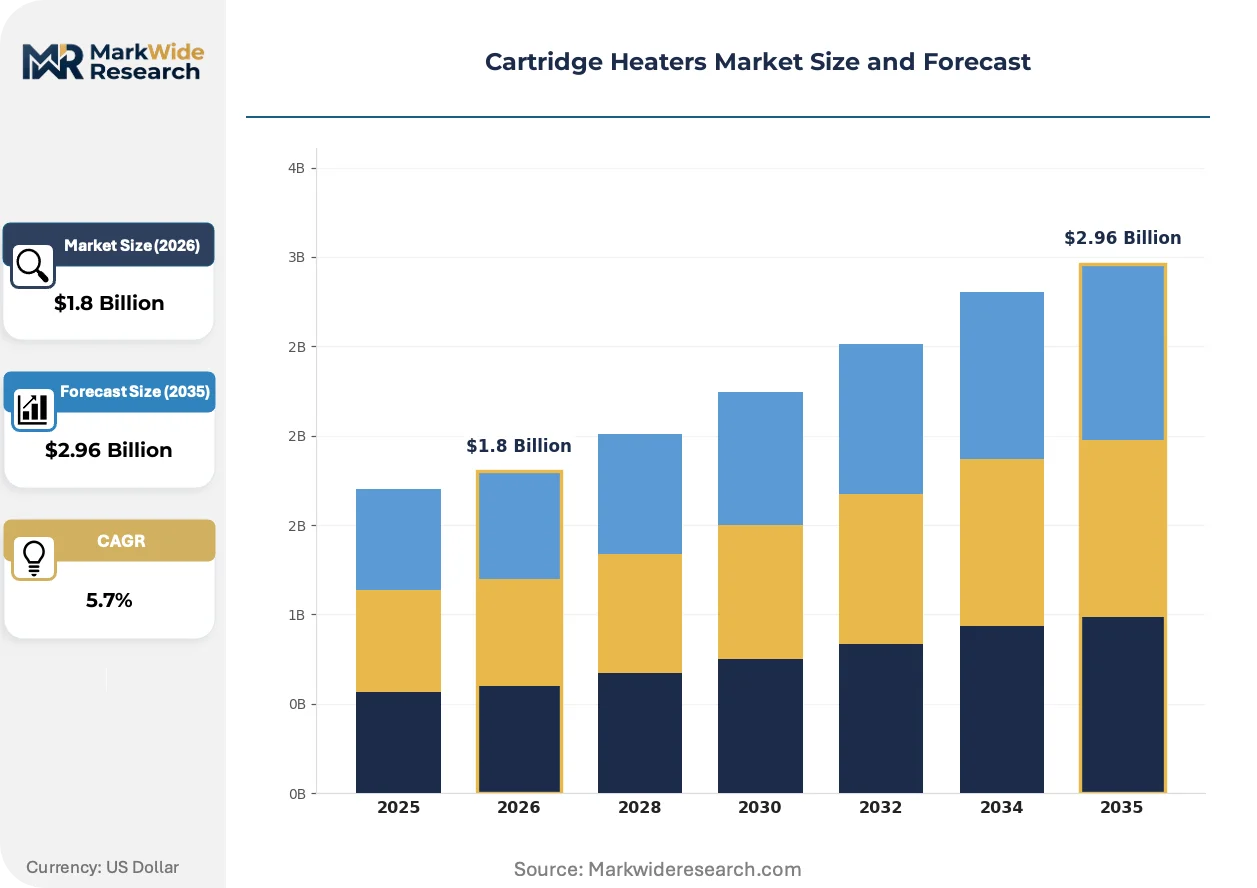
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cartridge, Thermocouple Cartridge, High-Temperature Cartridge, Custom Cartridge Material: Stainless Steel, Brass, Incoloy, Aluminum Application: Plastics Processing, Packaging Machinery, Medical Devices, Aerospace Components End User: Manufacturers, Research Institutions, Aftermarket Providers, OEMs |
| Companies Covered | Watlow, Chromalox, Backer Hotwatt, Tutco, Tempco, Hotset, Dalton Electric, Spirax Sarco, OMEGA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cartridge Heaters Market Emerging Trajectories
Digital thermal management architectures are displacing analog control systems across precision heating applications, compressing specification cycles and elevating buyer expectations for integrated sensor-heater performance validation.
Embedded thermocouple cartridge heaters with distributed temperature sensing is virtualizing the traditional separation between heating elements and control instrumentation. Medical device manufacturers in Switzerland and diagnostic instrument OEMs in Germany are specifying these architectures for multi-zone thermal uniformity requirements. The technology is virtualizing aftermarket service revenue streams as predictive maintenance algorithms replace scheduled replacement protocols.
REACH substance restrictions on hexavalent chromium coatings are forcing sheath material transitions toward nickel-plated or passivated stainless steel finishes. Surface treatment suppliers are requalifying corrosion resistance performance under accelerated salt spray protocols. Aerospace test rig specifications in France and semiconductor equipment builders in the Netherlands are driving fastest adoption of compliant surface engineering.
Consolidated procurement through integrated thermal subsystem suppliers is compressing direct heater sourcing relationships. Plastics processing OEMs in Italy and packaging machinery builders in Spain are bundling cartridge heater specifications within larger thermal module contracts. The shift is most visible among mid-cap extrusion line manufacturers who lack in-house thermal engineering capabilities and prefer single-source accountability for heating performance guarantees.
Cartridge Heaters Market Segmentation
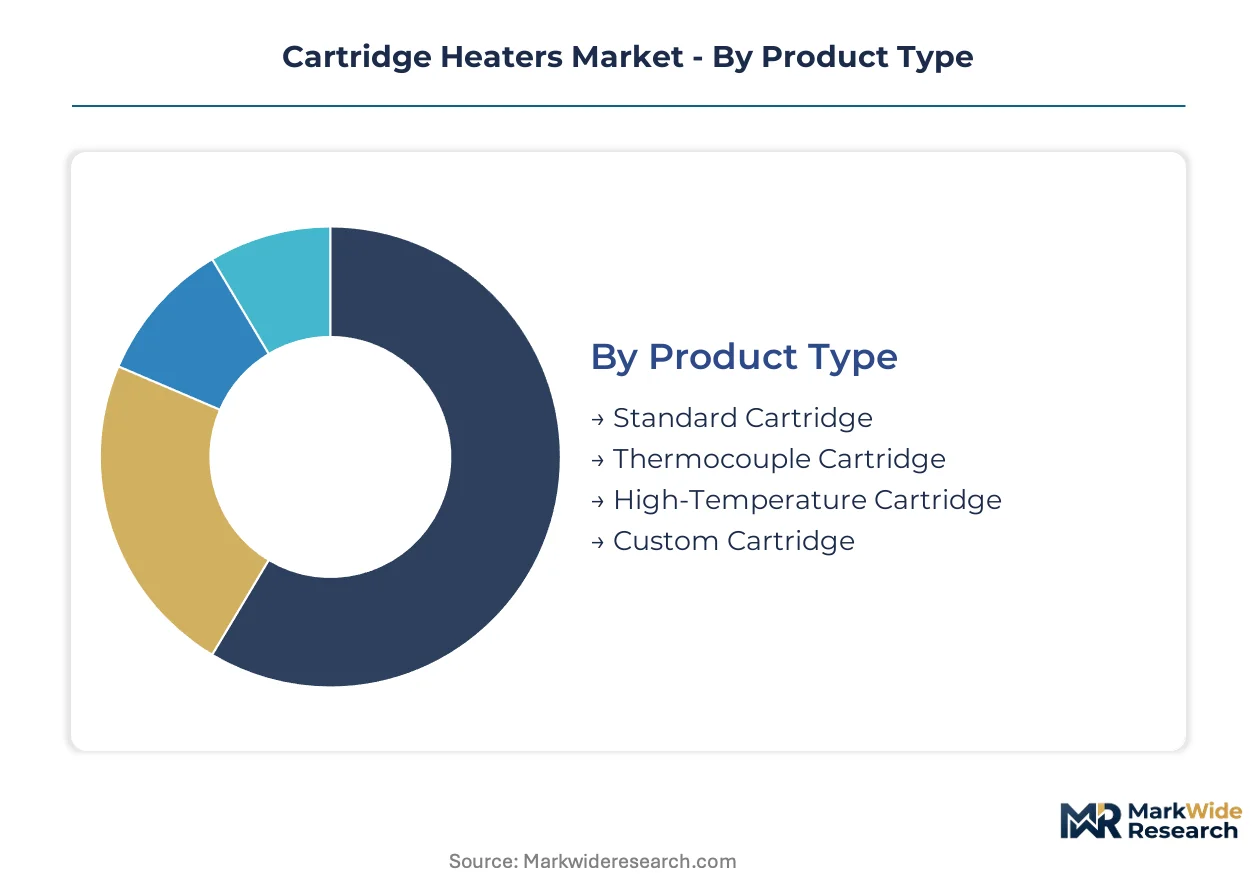
Cartridge heater specifications diverge sharply across thermal load requirements and regulatory exposure zones. Understanding these segment boundaries clarifies where engineering investment concentrates versus where commoditization pressures dominate procurement negotiations.
Product Type:
Cost tier determines specification depth and margin structure across cartridge heater architectures.
- Standard Cartridge:Nickel-chromium resistance wire in magnesium oxide insulation sheathed in 304 stainless steel serves general industrial warming applications. Plastics processing equipment manufacturers in Germany's industrial corridor drive volume procurement for extrusion and injection molding lines.
- Thermocouple Cartridge:Embedded distributed temperature sensing virtualizes the separation between heating elements and control instrumentation. Medical device manufacturers in Switzerland specify these architectures for multi-zone thermal uniformity in diagnostic instruments, pulling innovation investment toward precision feedback loops.
- High-Temperature Cartridge:Incoloy-sheathed designs sustain operation above 1400°F for aerospace composite curing applications in France.
- Custom Cartridge:Zone-controlled watt density configurations capture specialized margin pools from tight tolerance requirements.
Standard cartridges hold installed capacity. Thermocouple cartridges are rotating up the share rankings.
Material:
Application temperature ceiling and corrosion exposure dictate sheath alloy selection.
- Stainless Steel:304 and 316 grades dominate general industrial applications with moderate thermal cycling. China's expanded domestic fabrication capacity is shortening lead times for thermal component OEMs across Asia-Pacific supply chains.
- Incoloy:Nickel-iron-chromium alloys withstand sustained high-temperature oxidation in aerospace test rigs and semiconductor wafer processing equipment. REACH substance restrictions on hexavalent chromium coatings are accelerating nickel-plated surface treatment transitions.
- Brass:Lower cost option for packaging machinery heating zones with limited thermal stress exposure.
- Aluminum:Lightweight sheath material for portable diagnostic instruments requiring rapid thermal response.
Stainless steel commands volume share. Incoloy is climbing the fastest in premium positioning.
Application:
End-use thermal specifications create divergent engineering requirements and certification burdens.
- Plastics Processing:Extrusion and injection molding lines demand precision watt-density tolerances and fast thermal response profiles. OEMs across Italy and Spain are bundling heater specifications within integrated thermal module contracts.
- Medical Devices:Diagnostic instrument heating zones require tight temperature uniformity tolerances that virtualize aftermarket service through predictive maintenance algorithms.
- Packaging Machinery:Moderate thermal loads favor standardized cartridge configurations with shorter procurement cycles.
- Aerospace Components:Composite bonding and curing applications in France and the Netherlands specify sustained high-temperature operation with REACH-compliant surface engineering.
Plastics processing anchors current demand. Medical devices are expanding most quickly in value contribution.
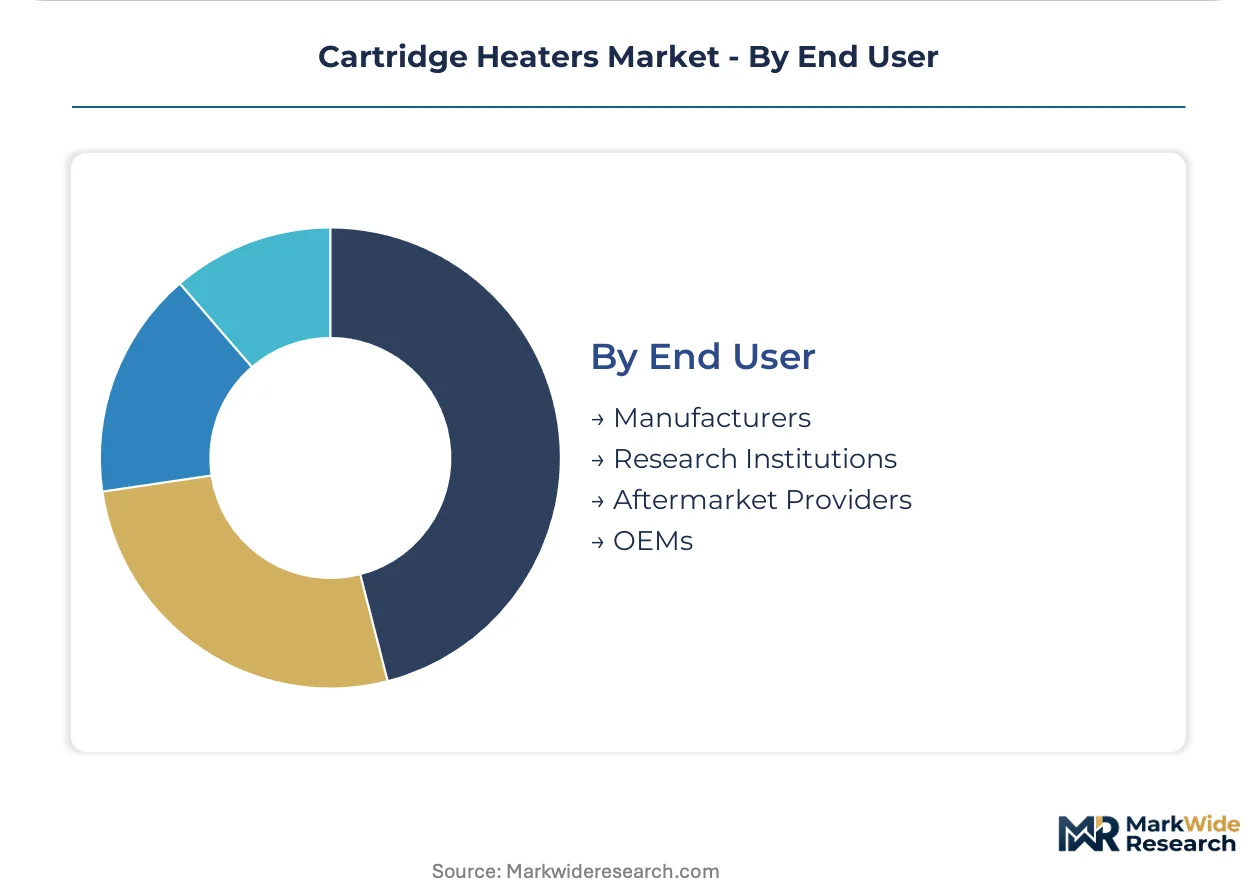
End User:
Procurement sophistication and technical integration depth separate buyer categories.
- Manufacturers:Industrial equipment builders with in-house thermal engineering capabilities specify direct heater relationships for performance guarantees.
- OEMs:Integrated thermal subsystem suppliers compress direct sourcing as mid-cap extrusion line manufacturers prefer single-source accountability.
- Research Institutions:Aerospace and semiconductor test facilities drive custom specification volumes for experimental thermal architectures.
- Aftermarket Providers:Service networks replace scheduled cartridge replacement protocols with predictive maintenance algorithm deployments.
Manufacturers hold legacy procurement relationships. OEMs are consolidating specification control fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel fabrication clusters in China and precision thermal engineering corridors in Germany concentrate supply capacity for cartridge heater OEMs. Demand disperses across plastics processing hubs in Italy, semiconductor equipment builders in the Netherlands, and aerospace test facilities in France.
United States
Plastics processing OEMs in Ohio and Illinois drive precision watt-density specifications for extrusion line modernization. OSHA electrical safety standards mandate dielectric strength validation before market entry. Watlow anchors North American demand through vertically integrated sensor-heater architectures serving injection molding markets.
Germany
Automotive supply chains and packaging machinery builders in Bavaria and North Rhine-Westphalia specify tight thermal uniformity tolerances. The EU F-Gas Regulation accelerates electrically heated solution adoption over gas-fired alternatives. Tutco localizes production of custom watt-density configurations for European industrial corridors.
China
Expanded domestic stainless steel fabrication capacity serving thermal component OEMs shortens lead times across Asia-Pacific supply chains. The country's dual carbon goals push industrial equipment toward energy-efficient electrically heated solutions. Yangtze River Delta clusters reconfigure regional supply dynamics for export-oriented cartridge heater production.
France
Aerospace composite curing applications in Toulouse and Paris-Saclay specify sustained operation above 1400°F for Incoloy-sheathed cartridges. REACH substance restrictions on hexavalent chromium coatings force sheath material transitions toward nickel-plated finishes. ANSM compliance documentation creates administrative burden for magnesium oxide insulation suppliers.
Netherlands
Semiconductor equipment builders in Eindhoven demand sub-miniature heater geometries with integrated thermocouple feedback loops for wafer processing. The EU Machinery Directive shapes product certification requirements for dielectric performance. Philips corridor technology clusters pull innovation investment toward precision cartridge architectures.
Cartridge Heaters Market Vendor Landscape
Vertically integrated thermal specialists and regional fabrication houses split the market between specification-driven premium tiers and cost-optimized volume segments. The vendor base concentrates around three strategic archetypes: sensor-integrated solution providers, high-temperature alloy specialists, and custom watt-density configurators. Competitive moves center on backward integration into resistance wire supply and geographic expansion through localized production facilities.
Among North American sensor-integrated providers, Watlow exemplifies the vertically integrated archetype through captive thermocouple and control system capabilities. Chromalox occupies a position within the high-temperature alloy specialist tier, with company nomenclature suggesting thermal process equipment heritage. Tutco anchors European demand fulfillment through localized fabrication positioning.
| Leading Market Players |
|---|
| Watlow |
| Chromalox |
| Backer Hotwatt |
| Tutco |
| Tempco |
| Hotset |
| Dalton Electric |
| Spirax Sarco |
| OMEGA |
| Others |
Supply Flow & Price Mechanics
China's expanded stainless steel fabrication clusters concentrate raw material supply for thermal component OEMs, anchoring margin pools in precision watt-density configurations and REACH-compliant surface engineering tiers downstream. Nickel-chromium wire sourcing from this regional base feeds directly into pricing power differentials between standard industrial cartridges and aerospace-grade Incoloy designs.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across cartridge heater architectures, separating nickel-plated sheath finishes from legacy hexavalent chromium coatings through certification cost differentials. Three-tier pricing structure across premium, standard, and economy levels reflects dielectric strength validation under OSHA electrical safety standards and EU Machinery Directive compliance burdens. Cost compression in standard stainless steel cartridges is intensifying because China's domestic capacity expansion shortens lead times and compresses procurement cycles. Tier 1 automotive suppliers in Germany exhibit lowest price sensitivity due to thermal uniformity guarantees, while packaging machinery builders in Spain drive commodity-tier negotiations hardest.
Supply Chain Analysis
Dual-use technology export controls on precision thermal management systems limit sub-miniature heater geometries with integrated sensor feedback from reaching certain semiconductor equipment builders. Manufacturing concentrates in China for stainless steel sheaths, Germany for custom watt-density configurations, and the United States for vertically integrated sensor-heater architectures. Raw material flows draw from magnesium oxide insulation suppliers in Asia-Pacific, nickel-chromium resistance wire fabricators in stainless steel clusters, and Incoloy alloy producers serving aerospace specifications. Single-source vulnerability concentrates in high-purity magnesium oxide for medical device applications. Distribution runs through integrated thermal subsystem suppliers that compress direct heater relationships for mid-cap plastics processing OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded thermocouple architectures are reconfiguring cartridge heaters toward platform economics, where predictive maintenance algorithms virtualize aftermarket revenue and bind diagnostic instrument OEMs into ongoing service relationships.
For Market Incumbents: Build captive sensor-heater integration moats by deepening backward integration into thermocouple manufacturing and expanding localized production in Germany's industrial corridor. Induction heating substitution in high-temperature metal processing threatens legacy cartridge positions in aerospace test rigs. Certification investment in REACH-compliant nickel-plated surface treatments anchors margin defense against regulatory displacement. For New Entrants and Emerging Players: Pursue medical device thermal uniformity specifications in Switzerland and diagnostic instrument zones in the Netherlands, where tight tolerance requirements and zone-controlled watt density create specialized margin pools. Custom cartridge configurations for multi-zone sensing represent the most penetrable segment. Go-to-market positioning through integrated thermal subsystem partnerships bypasses direct OEM procurement barriers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated thermal specialists with captive sensor architectures and established aerospace test rig relationships, where platform economics sustain long-term viability across replacement-cycle virtualization. The signal to watch is semiconductor equipment thermal specification shifts toward sub-miniature geometries, which would redirect precision heater demand and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermocouple Manufacturing | Watlow's captive sensor capabilities anchor North American plastics market positions against modular competitors. |
| Localized Production Expansion | Tutco's German fabrication footprint shortens lead times for EU F-Gas Regulation compliance-driven conversions. |
| REACH-Compliant Surface Engineering Transition | Nickel-plated sheath finishes from French aerospace test rig suppliers displace hexavalent chromium coatings under ECHA restrictions. |
| Predictive Maintenance Algorithm Development | Swiss medical device manufacturers virtualize service revenue through embedded thermocouple feedback loops. |
| Custom Watt-Density Configuration Platforms | Zone-controlled thermal architectures capture specialized margins from diagnostic instrument OEMs in the Netherlands. |
Methodological Framework
Desk research of customs trade data, SEC filings from thermal component suppliers, and EU regulatory submission databases preceded structured interviews with plastics processing equipment procurement leads, aerospace test rig thermal engineers, medical device manufacturing directors, and cartridge heater aftermarket service managers. Primary fieldwork with OEM specification teams and secondary validation against ECHA substance restriction timelines and OSHA electrical safety standard revision histories anchored demand-side calibration. Bottom-up shipment analysis triangulated against top-down industrial equipment production forecasts.
Assumptions held fixed include EU F-Gas Regulation enforcement timelines and semiconductor equipment thermal specification trajectories, while magnesium oxide insulation purity standards and nickel-chromium wire availability were treated as sensitivity variables across the analysis window. Segmentation modeling incorporated product type, sheath material alloy, end-use application intensity, and buyer procurement sophistication tiers. CAGRs derived from regression against industrial production indices and equipment modernization cycle data, with aerospace composite curing demand and medical device diagnostic instrument growth as industry-specific volume drivers.
Sensitivities concentrate around REACH substance restriction expansion to additional sheath alloys and semiconductor capital expenditure cyclicality. Forecasts reflect documented assumptions on regulatory compliance cost pass-through rates and thermal engineering talent pipeline expansion. Material shifts in EPA energy efficiency guideline stringency or induction heating cost-performance ratios would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Contour Measuring Machines Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Global Electro Hydraulic Servo Valve Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Small Harmonic Reducer Market