
 Global High Speed Dispenser Market | 2026-2036
Global High Speed Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Speed Dispenser Market Analysis
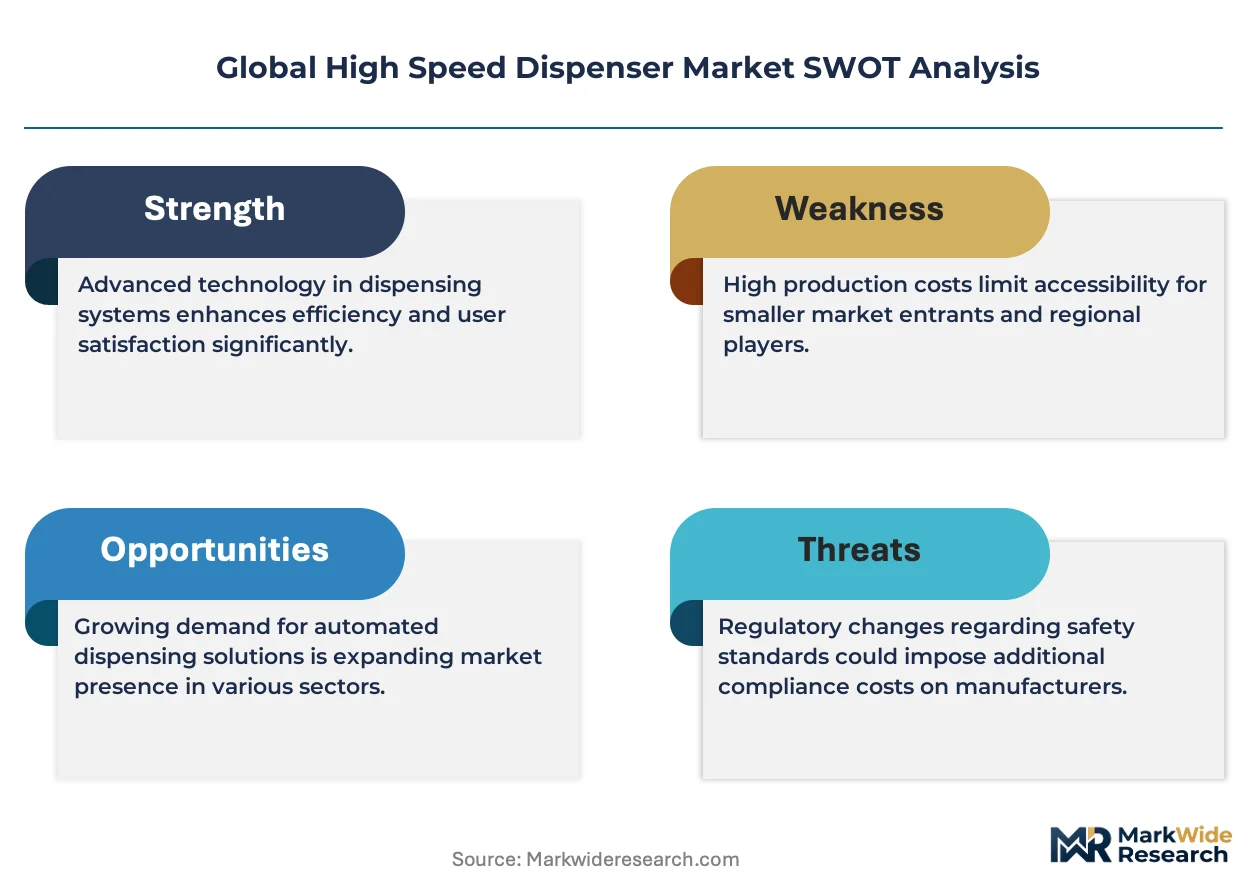
ISO 14644 cleanroom qualification is bifurcating the competitive landscape into certified and non-certified supplier tiers. Nordson leverages its precision fluid management heritage to dominate semiconductor and medical device segments. Graco Inc anchors its position through backward integration into pump and metering technologies that reduce third-party component dependency. Dover Corporation sustains multi-industry coverage across food safety and industrial automation applications with distributed service networks.
A high speed dispenser is an automated or semi-automated machine engineered to deposit adhesives, sealants, lubricants, or viscous media at cycle times exceeding 500 parts per minute with repeatability tolerances below one percent. These systems integrate servo-driven volumetric pumps, vision-guided positioning, and programmable logic controllers to achieve consistent material placement in high-throughput manufacturing environments. Electronic dispensers command premium positioning due to closed-loop feedback requirements in microelectronics assembly, while pneumatic technology retains cost advantages in automotive sealing operations where throughput outweighs absolute precision. Pressure dispensers serve mature food and beverage bottling lines with standardized container geometries, whereas volumetric configurations capture pharmaceutical liquid filling where batch integrity regulations mandate traceable dose verification.
FDA cGMP guidelines govern pharmaceutical filling validation protocols in the United States, while REACH and RoHS frameworks in the European Union restrict hazardous substance content in dispensed materials and wetted components. The EPA monitors volatile organic compound emissions from solvent-based adhesive dispensing in industrial coating applications, creating compliance costs that favor electric and hybrid technology transitions. Stakeholders must monitor evolving semiconductor packaging roadmaps and regional substance restriction timelines to align R&D allocation with addressable demand pools.
Market Dynamics
Semiconductor packaging roadmaps in Taiwan and South Korea are compressing pitch geometries below 50 microns, forcing adhesive deposition systems to achieve sub-microliter repeatability at cycle speeds exceeding 800 parts per minute. This precision-performance tension is restructuring supplier qualification hierarchies and capital allocation patterns across electronics manufacturing clusters.
Growth Catalysts
- FDA cGMP validation protocols:Pharmaceutical filling operations in the United States mandate traceable dose verification, driving volumetric dispenser upgrades in sterile injectable manufacturing.
- REACH substance restrictions:ECHA frameworks in the European Union restrict hazardous content in wetted components, creating replacement demand for compliant adhesive deposition systems.
- Miniaturization in consumer electronics:Smartphone and wearable manufacturers in East Asian clusters require finer pitch adhesive control, accelerating automated dispenser deployment.
Market Restraints
- Precision component supply concentration:Servo-driven volumetric pumps and vision systems rely on specialized suppliers concentrated in Japan and Germany, creating input bottlenecks.
- Cleanroom qualification costs:ISO 14644 certification for semiconductor-grade dispensing systems requires capital-intensive facility validation that excludes mid-tier entrants.
- Hybrid electric transition friction:EPA volatile organic compound regulations favor electric dispensing technology, but pneumatic system installed bases in automotive sealing create conversion inertia.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO regulatory alignment with international standards is attracting contract filling operations that require cGMP-validated liquid dispensing systems.
- AI-guided deposition convergence:Machine vision integration with real-time viscosity compensation is opening precision gaps that closed-loop feedback systems can capture in microelectronics assembly.
- Brazilian medical device localization:ANVISA import substitution policies incentivize domestic dispenser assembly for regional catheter and diagnostic device production.
Industry Challenges
- Mechatronics skill scarcity:Servo pump calibration and vision-guided positioning integration require specialized technicians that contract manufacturers struggle to recruit.
- Legacy system interoperability:Programmable logic controller architectures from mature food and beverage bottling lines resist integration with modern traceability databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Speed Dispenser Market |
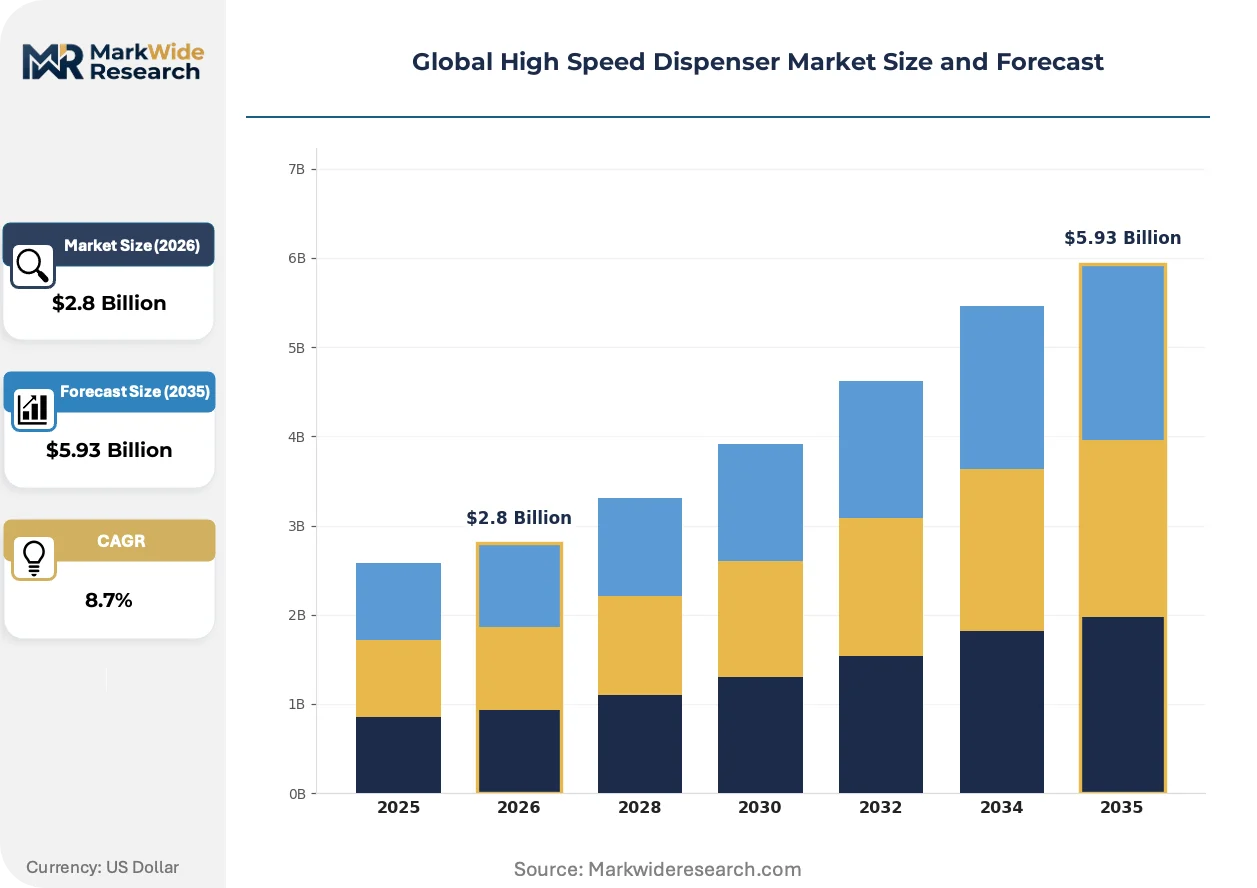
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Dispensers, Pressure Dispensers, Volumetric Dispensers, Electronic Dispensers Technology: Pneumatic, Electric, Mechanical, Hybrid Application: Food & Beverage, Automotive, Pharmaceuticals, Personal Care End User: Manufacturers, Wholesalers, Retailers, Workshops |
| Companies Covered | Dover Corporation, Graco Inc, Essemtec, Nordson, Netzsch Grinding & Dispersing, ROSS, SATO Holdings Corporation, DOPAG, FLUKO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Speed Dispenser Market Emerging Trajectories
Adhesive deposition technology is bifurcating between closed-loop precision systems for microelectronics and cost-optimized pneumatic configurations for automotive sealing, with regulatory compliance emerging as the decisive selection criterion across both tiers.
Jet dispensing technology is decomposing traditional needle-based deposition in semiconductor underfill applications. Taiwan-based packaging houses are adopting piezoelectric actuation at scale to achieve non-contact material placement below 100-micron pad pitches. This shift is decomposing the historical throughput-precision tradeoff that favored pneumatic systems in mid-tier electronics assembly.
EMA Annex 1 revisions on sterile manufacturing are tightening environmental monitoring requirements for pharmaceutical filling lines. European liquid dose manufacturers must now demonstrate continuous viable particle control during adhesive and sealant deposition operations. Aseptic processing facilities in Germany and Switzerland are retrofitting isolator-integrated dispensing systems to preempt regulatory inspection findings.
Service unbundling is fragmenting traditional dispenser procurement patterns. Electronics contract manufacturers in South Korea are separating hardware acquisition from validation and maintenance contracts, treating after-sales support as a competitive bidding category distinct from capital equipment. This purchasing model shift is most pronounced in multi-site semiconductor packaging operations where standardization across facilities reduces supplier switching costs.
Global High Speed Dispenser Market Segmentation
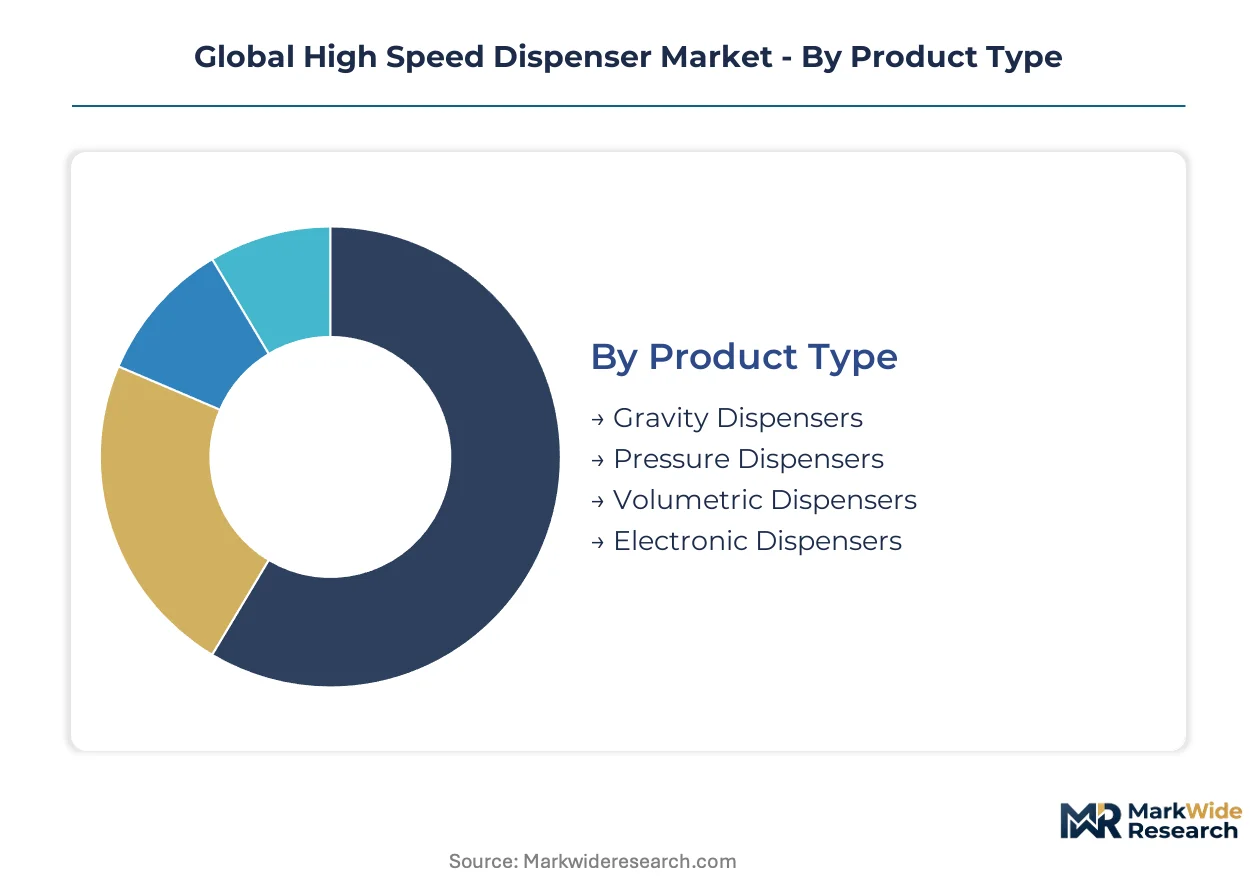
Segmentation in high speed dispensing equipment reveals how regulatory frameworks and precision requirements fragment procurement patterns across end-use industries. Equipment specifications diverge sharply between semiconductor packaging lines requiring ISO 14644 cleanroom qualification and automotive sealing operations where throughput economics dominate selection criteria.
Product Type:
Regulatory differentiation separates pharmaceutical-grade volumetric systems from industrial pneumatic configurations, with FDA cGMP and EMA Annex 1 standards mandating traceable dose verification that gravity-based alternatives cannot satisfy.
- Electronic Dispensers:Closed-loop feedback architectures integrate servo-driven pumps with real-time viscosity compensation for sub-microliter deposition. Taiwan and South Korea semiconductor packaging houses deploy these systems for underfill applications below 50-micron pitch geometries where repeatability tolerances must stay below one percent.
- Volumetric Dispensers:Positive-displacement pump mechanisms deliver measurable dose volumes with batch integrity documentation required by FDA cGMP protocols. Sterile injectable manufacturers in the United States and Germany retrofit these systems to preempt regulatory inspection findings on traceable filling validation.
- Pressure Dispensers:Compressed air-driven reservoirs deposit medium-viscosity sealants in automotive body-in-white operations where cycle speed exceeds absolute precision requirements.
- Gravity Dispensers:Simple head-pressure feed systems serve mature food and beverage bottling lines with standardized container geometries and minimal regulatory burden.
Pressure dispensers handle the majority of throughput across automotive and food processing lines; electronic dispensers are climbing the fastest on share as semiconductor packaging roadmaps compress pitch geometries.
Technology:
Cost tier stratification positions electric actuation at premium price points against pneumatic alternatives, with EPA volatile organic compound regulations accelerating hybrid transitions in solvent-based adhesive applications.
- Electric:Servo motor-driven actuation eliminates compressed air dependency while enabling programmable deposition profiles with closed-loop position feedback. Electronics contract manufacturers in South Korea specify electric systems for multi-site standardization programs that reduce supplier switching costs.
- Pneumatic:Compressed air cylinders deliver cost advantages in high-volume automotive sealing where installed base inertia resists conversion despite regulatory pressure. Tier-1 sealing suppliers in Germany retain pneumatic fleets for body shop operations where throughput economics outweigh precision premiums.
- Mechanical:Cam-driven and gear-based actuation serves low-speed personal care filling with minimal maintenance requirements and capital expenditure constraints.
- Hybrid:Combined pneumatic-electric architectures balance speed and precision in pharmaceutical liquid dose manufacturing where EMA Annex 1 environmental monitoring requirements demand flexible control strategies.
Pneumatic technology retains the largest installed base; electric systems are expanding most quickly as semiconductor and medical device manufacturers prioritize closed-loop feedback capabilities.
Application:
Application segmentation tracks how end-use regulatory intensity determines equipment specification tiers, with pharmaceutical and personal care operations facing stricter material compatibility validation than industrial sealing applications.
- Pharmaceuticals:Sterile filling operations require isolator-integrated dispensing with continuous viable particle monitoring under EMA Annex 1 and FDA cGMP frameworks. German and Swiss aseptic processing facilities drive replacement demand for REACH-compliant wetted components.
- Automotive:Structural adhesive and seam sealing applications prioritize cycle speed over absolute precision, with pneumatic systems dominating body-in-white and paint shop operations.
- Food & Beverage:Standardized container handling and lower regulatory burden compared to pharmaceuticals permit simpler pressure-based dispensing configurations in high-volume bottling lines.
- Personal Care:Viscous cream and lotion filling balances throughput with cosmetic quality standards, typically employing mechanical or basic pneumatic systems without cleanroom qualification requirements.
Automotive applications generate the highest equipment unit volumes; pharmaceutical operations command the steepest expansion trajectory as regulatory alignment tightens across CDSCO, ANVISA, and MFDS jurisdictions.
End User:
Customer type segmentation reflects procurement model fragmentation, with large manufacturers separating hardware acquisition from validation contracts while smaller workshops prioritize bundled service offerings.
- Manufacturers:Original equipment producers and contract manufacturers operate multi-site dispensing fleets requiring standardized maintenance protocols and traceable calibration records. South Korean electronics packaging houses unbundle after-sales support into competitive bidding categories distinct from capital equipment procurement.
- Workshops:Small-scale repair and prototyping facilities favor portable pneumatic dispensers with minimal setup complexity and lower capital barriers.
- Wholesalers:Distribution intermediaries stock mid-tier pressure and gravity systems for regional resale to food processing and personal care operations without direct OEM relationships.
- Retailers:Point-of-sale dispensing for customized product formulation serves niche personal care and specialty beverage segments with low-throughput, high-flexibility requirements.
Manufacturers represent the dominant procurement channel by value; workshops are gaining share fastest as distributed repair networks and prototyping services expand in emerging manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Original equipment manufacturers and contract electronics assemblers cluster in East Asian industrial corridors, with pharmaceutical filling operations concentrating in Western Europe and North American sterile manufacturing hubs.
Taiwan
Semiconductor packaging houses in Hsinchu Science Park and Taichung Precision Machinery Park deploy sub-microliter deposition systems for flip-chip underfill applications. The National Development Council prioritizes advanced packaging capacity expansion under the Six Core Strategic Industries initiative. Kaohsiung-based OSAT facilities are retrofitting jet dispensing lines to handle 50-micron pitch geometries for smartphone processor substrates.
South Korea
Samsung and SK Hynix memory packaging operations drive volumetric dispenser demand for stacked die adhesive lamination. MFDS pharmaceutical manufacturing guidelines align with FDA cGMP standards, accelerating sterile injectable filling system upgrades. Pyeongtaek and Yongin biotech clusters are installing isolator-integrated dispensing systems for monoclonal antibody production.
Germany
Bavarian and Baden-Württemberg automotive sealing operations retain pneumatic system fleets for body-in-white throughput economics. EMA Annex 1 revisions on sterile manufacturing force aseptic processing facilities in Hesse and North Rhine-Westphalia to retrofit continuous particle monitoring. Frankfurt-Rhine-Main pharmaceutical contract manufacturers specify REACH-compliant wetted components for adhesive deposition systems.
United States
FDA cGMP validation protocols mandate traceable dose verification in sterile injectable manufacturing across Massachusetts and North Carolina biotech corridors. EPA volatile organic compound regulations accelerate electric dispensing transitions in solvent-based adhesive applications. Minneapolis-St. Paul precision fluid management specialists serve medical device OEMs with cleanroom-qualified deposition systems.
India
CDSCO regulatory alignment with international standards attracts contract filling operations to Gujarat and Maharashtra pharmaceutical manufacturing zones. PLI scheme incentives for electronics manufacturing push Tamil Nadu and Karnataka assembly plants toward automated adhesive deposition. Hyderabad vaccine producers are qualifying volumetric dispensers for sterile liquid dose packaging under WHO prequalification pathways.
Global High Speed Dispenser Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with precision fluid management heritage, creating tiered competition between certified cleanroom specialists and cost-optimized pneumatic suppliers. The structure concentrates around three strategic archetypes: precision electronics specialists, multi-industry diversified manufacturers, and regional pump technology integrators. Competitive moves center on backward integration into metering component production and geographic expansion through distributed service networks.
Within the diversified industrial tier, Dover Corporation and Graco Inc exemplify multi-segment coverage strategies spanning food safety, automotive sealing, and medical device applications. Nordson occupies a position as a precision fluid management anchor in semiconductor and medical device segments. These three companies represent contrasting approaches to technology portfolio breadth versus vertical specialization in high-throughput deposition systems.
| Leading Market Players |
|---|
| Dover Corporation |
| Graco Inc |
| Essemtec |
| Nordson |
| Netzsch Grinding & Dispersing |
| ROSS |
| SATO Holdings Corporation |
| DOPAG |
| FLUKO |
| Others |
Supply Flow & Price Mechanics
Piezoelectric actuator substitution for pneumatic cylinders in jet dispensing modules simultaneously shifts component sourcing toward Japan and Germany while compressing price premiums in the sub-50-micron precision tier. Semiconductor packaging houses in Taiwan and South Korea now specify closed-loop electric architectures that sever cost advantages historically held by compressed-air system suppliers.
Pricing Analysis
Cost-plus contracts with semiconductor foundries index servo pump and vision system inputs to specialized supplier pricing in Japan and Germany. Three-tier pricing structure across ISO 14644-certified cleanroom systems, standard industrial configurations, and economy pneumatic units separates pharmaceutical validation tiers from automotive throughput tiers. Pricing pressure stems from South Korean electronics manufacturers unbundling hardware procurement from validation and maintenance contracts. Contract manufacturers exhibit highest price sensitivity; sterile injectable producers accept premium positioning for traceable dose verification systems.
Supply Chain Analysis
Japan and Germany produce precision servo-driven volumetric pumps and machine vision systems that anchor high-speed dispenser performance specifications. Taiwan and South Korea assemble complete deposition systems for semiconductor packaging lines. Supply chains draw from specialized component suppliers concentrated in East Asia and Central Europe, creating single-source vulnerability in piezoelectric actuator and high-resolution camera module categories. Tariff exposure runs through precision component trade flows between Japan, Germany, and final assembly locations. Distribution runs through OEM direct sales for large manufacturers and regional distributors serving mid-tier food processing and personal care operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validation and maintenance contract unbundling in South Korean electronics manufacturing expands aftermarket service revenue faster than hardware unit growth. This service-attach dynamic restructures procurement patterns toward recurring revenue relationships.
For Market Incumbents: Shield semiconductor market share by deepening captive production of servo pump subassemblies that reduce dependency on Japanese and German precision component suppliers. Accelerate ISO 14644 certification investments to maintain cleanroom tier pricing premiums against emerging pneumatic-electric hybrid challengers. Consolidate multi-site service contracts with South Korean packaging houses to resist competitive bidding fragmentation.
For New Entrants and Emerging Players: Aftermarket calibration and recertification services for installed pneumatic bases in automotive sealing represent the most penetrable white-space where incumbents under-serve legacy fleet operators. Target German Tier-1 body shop operations with hybrid electric retrofit kits that bridge EPA volatile organic compound compliance without full system replacement. Pursue validation-only contracts with Indian pharmaceutical contract manufacturers seeking CDSCO-aligned documentation without capital equipment procurement.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors precision component specialists with captive servo pump or vision system capabilities. Long-term viability centers on backward integration depth that insulates margin structures from East Asian supply concentration. Watch semiconductor packaging roadmaps from Taiwan and South Korea for pitch geometry compression below 30 microns as the inflection signal accelerating jet dispensing adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Pump Manufacturing | Reduces dependency on Japanese and German precision component suppliers while protecting semiconductor-tier margins. |
| ISO 14644 Cleanroom Certification Expansion | Creates regulatory moat against non-certified competitors in pharmaceutical and medical device segments. |
| Validation Service Unbundling | Captures recurring revenue from South Korean electronics manufacturers separating hardware from compliance contracts. |
| Hybrid Electric-Pneumatic System Development | Bridges EPA volatile organic compound compliance for automotive sealing installed bases resisting full conversion. |
| Indian Pharmaceutical Manufacturing Partnership | Positions for CDSCO-aligned contract filling expansion in Gujarat and Maharashtra zones. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with semiconductor packaging engineers, pharmaceutical filling line managers, automotive sealing procurement leads, and aftermarket service directors at precision fluid management specialists. Secondary validation drew from FDA cGMP guidance documents, EMA Annex 1 revision drafts, EPA volatile organic compound regulations, SEC filings from diversified industrial conglomerates, and trade flow data for precision pump and vision system components. Bottom-up equipment shipment analysis triangulated against top-down end-use industry capital expenditure patterns.
Across the analysis window, volume and value outputs reflect segment-level modeling across product type, technology, application, and end-user dimensions with semiconductor pitch geometry compression as an additional industry-specific driver. CAGRs were derived from equipment replacement cycles, regulatory compliance timelines, and foundry capacity expansion announcements. Forecast inputs incorporated MFDS pharmaceutical manufacturing guideline alignment, CDSCO regulatory harmonization progress, and EPA enforcement patterns for solvent-based adhesive applications.
Underlying assumptions cover semiconductor packaging roadmap adherence, regulatory timeline stability, and precision component supply continuity, with deviation risk concentrated in mechatronics technician availability and tariff disruption to East Asian trade flows. Recalibration cycles align with material shifts in semiconductor node transitions and sterile manufacturing guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Machine Mounts Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Fiber Laser Coding System Market