
 Snowrator Market | 2026-2036
Snowrator Market Size, Share, and Industry Trends Forecast 2026-2036
Snowrator Market Analytics
Dealer networks and direct municipal procurement channels are reshaping how snow removal equipment reaches end users. Douglas Dynamics leverages its established distribution footprint across North American snow-belt states to sustain contractor loyalty. The Toro Company anchors its position through integrated service agreements that bundle fleet management with equipment sales. Aebi Schmidt Holding AG competes in European municipal segments with specialized chassis-integrated systems.
A snowrator is a self-propelled or towable snow removal machine engineered with rotating auger-and-impeller assemblies capable of processing snow at throughput rates exceeding conventional walk-behind units, designed for clearing parking lots, airport aprons, and roadway shoulders. Gas-powered snowrators still occupy the majority of commercial fleet installations due to runtime reliability in sub-zero conditions, though electric variants are gaining traction where overnight depot charging infrastructure exists. Municipal application budgets concentrate replacement spending in Q3 procurement cycles, while contractor end users navigate seasonal cash-flow constraints that favor lease-to-own arrangements over outright purchase.
EPA Phase III emissions standards and OSHA winter workplace safety directives constrain engine specifications and operator protection requirements for commercial-grade equipment. The EU F-Gas Regulation and CE machinery directives shape import eligibility for European municipal tenders. Stakeholders must monitor battery energy density improvements and charging infrastructure buildouts to calibrate product portfolio transitions between combustion and electric platforms.
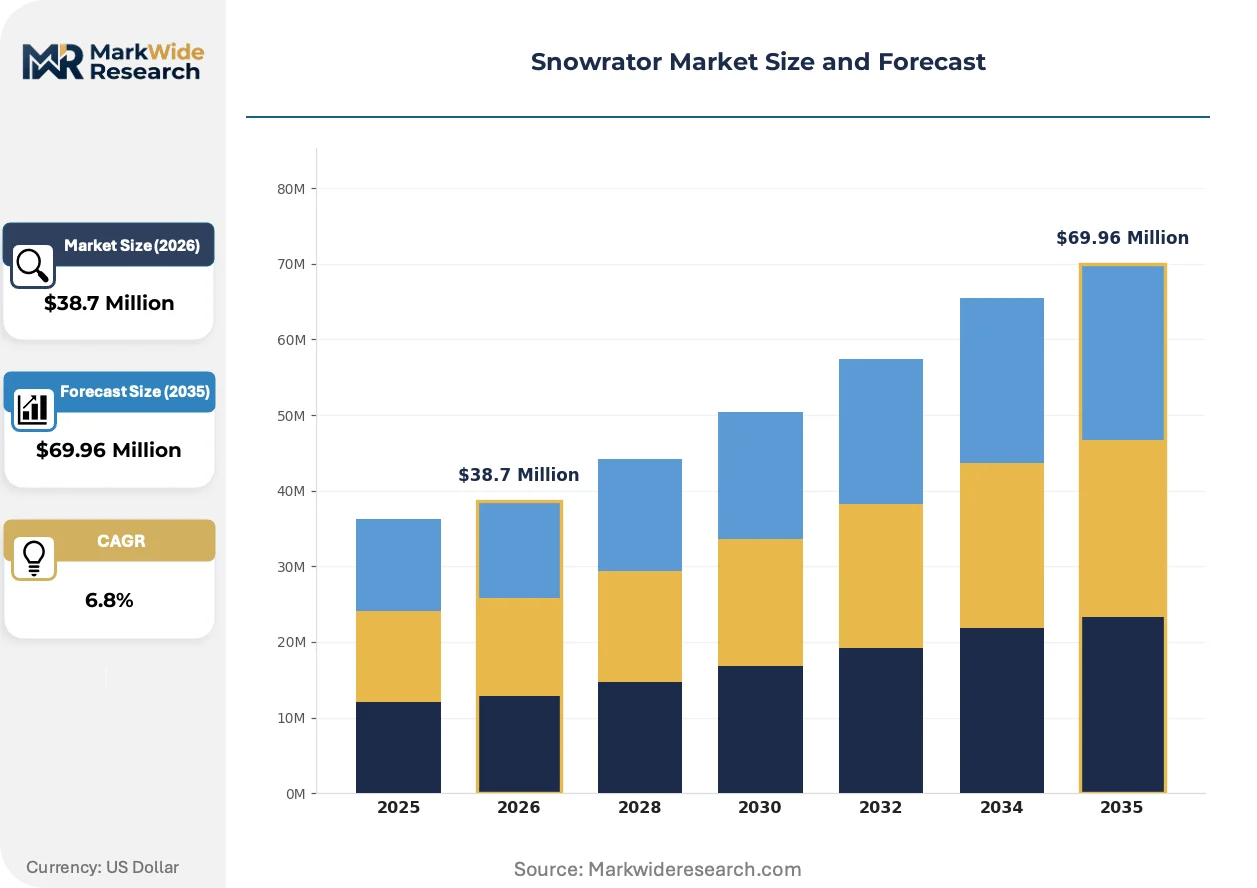
Market Dynamics
Municipal fleet electrification mandates and EPA Phase III emissions standards are forcing manufacturers to recalibrate powertrain architectures while maintaining runtime reliability in sub-zero operating conditions.
Growth Catalysts
- OSHA Winter Workplace Safety Directives:Tightening operator protection requirements accelerate replacement cycles for aging commercial fleets in high-snowfall regions.
- Airport Infrastructure Modernization:Apron and de-icing pad expansion projects drive demand for chassis-integrated snow removal systems with higher throughput specifications.
- Battery Energy Density Improvements:Lithium-ion cell chemistry advances enable electric snowrators to achieve practical runtime thresholds for overnight depot charging operations.
Market Restraints
- Diesel Engine Supply Concentration:Tier 4 Final powertrain sourcing depends on a limited supplier base concentrated in industrial Midwest manufacturing corridors.
- Steel and Aluminum Input Volatility:Chassis and auger fabrication costs fluctuate with commodity index movements, compressing margin visibility on multi-year municipal contracts.
- Technical Limitation in Cold-Weather Battery Performance:Lithium-ion capacity degradation below negative twenty degrees Fahrenheit constrains electric variant deployment in northern tier states.
Strategic Opportunities
- EU F-Gas Regulation Compliance:European municipal tender requirements for low-emission equipment create import eligibility for electric and hybrid platform manufacturers.
- Lease-to-Own Channel Innovation:Contractor segments facing seasonal cash-flow constraints favor equipment financing structures over capital purchase.
- Telematics and Fleet Management Convergence:Integration of GPS tracking, usage metering, and predictive maintenance software creates recurring revenue attachment opportunities.
Industry Challenges
- Certification Timeline Compression:EPA and CE machinery directive approval cycles for new powertrain variants extend product launch windows.
- Integration Complexity with Legacy Municipal Fleets:Mixed-vendor maintenance protocols and parts standardization gaps increase total cost of ownership for procurement departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snowrator Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Snowrator, Electric Snowrator, Gas-Powered Snowrator, Hybrid Snowrator Application: Residential, Commercial, Municipal, Industrial End User: Homeowners, Contractors, Government Agencies, Property Managers Technology: Augmented Reality, Autonomous Operation, GPS Navigation, Smart Controls |
| Companies Covered | Douglas Dynamics, The Toro Company, Arctic Snow and Ice Products, Aebi Schmidt Holding AG, Henke Manufacturing Corporation, Metal Pless, Meyer Products, KAGE Innovation, Buyers Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snowrator Market Evolving Landscape
Powertrain diversification and connected fleet management capabilities are redefining equipment specifications and procurement evaluation criteria across municipal and commercial buyer segments.
Electric traction systems are migrating from niche demonstration projects to validated municipal deployments. Airport authorities in Minnesota and Wisconsin pilot battery-powered units for overnight apron clearing where charging infrastructure exists. This migration from combustion-dominant specifications is compressing the traditional ten-year fleet replacement cycle in favor of technology refresh intervals.
EPA Phase III emissions standards tighten nitrogen oxide and particulate matter thresholds for commercial off-road diesel engines. Engine manufacturers must deploy selective catalytic reduction and diesel particulate filter systems that add cost and complexity. Municipal procurement departments in New York, Massachusetts, and Illinois weight emissions compliance scores more heavily in Q3 bidding evaluations.
Service contract unbundling separates equipment purchase from maintenance and parts provisioning. Large contractor fleets negotiate direct relationships with regional service providers, bypassing traditional dealer intermediaries. This pattern concentrates in the Upper Midwest where multi-location operators seek cost transparency across dispersed equipment pools.
Snowrator Market Segmentation
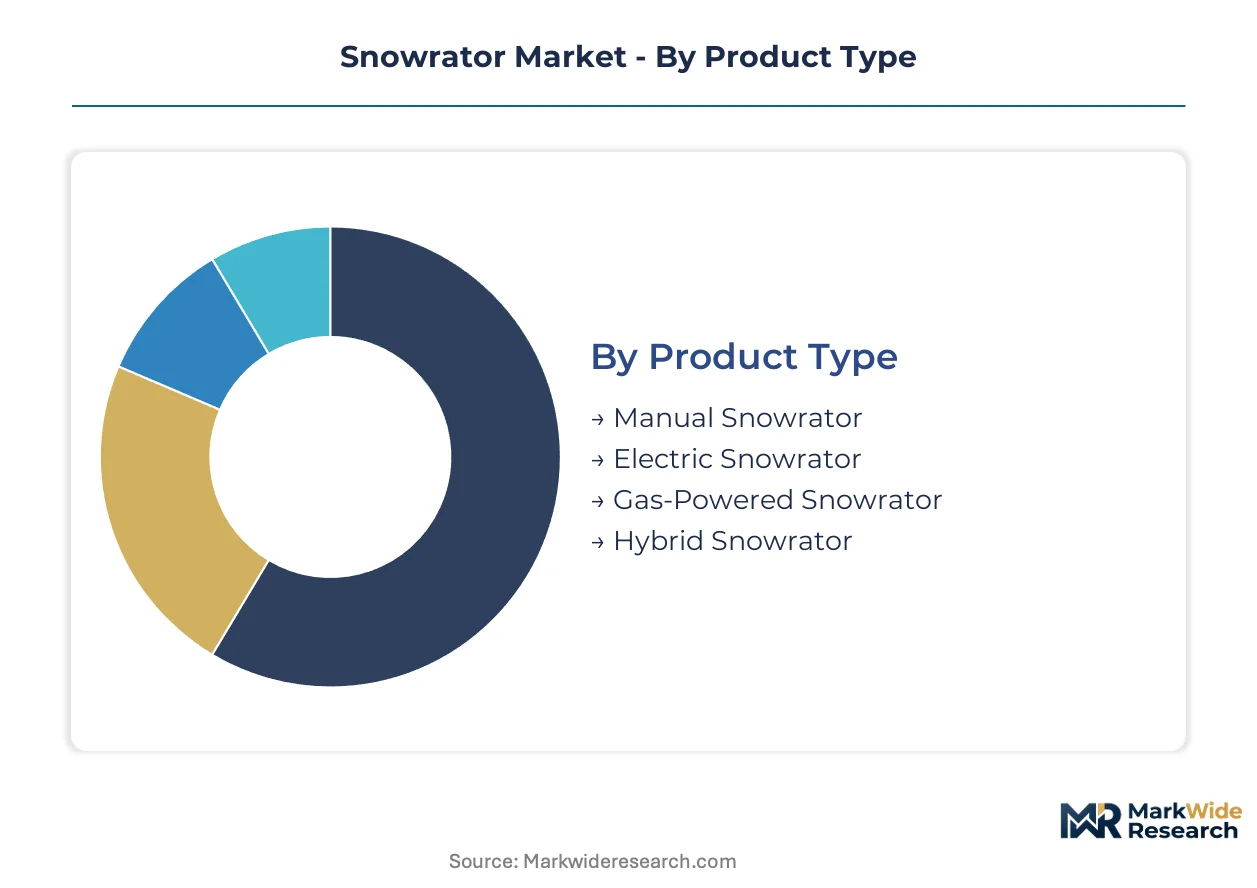
Snowrator procurement cycles vary dramatically by segment, with municipal fleets operating on decade-long replacement schedules while contractor segments refresh equipment every four to six seasons based on utilization intensity. Understanding these velocity differentials helps manufacturers calibrate inventory positioning and service contract structures across buyer categories.
Product Type:
Gas-powered platforms turn over slowest due to mechanical durability in sub-zero conditions, while electric variants refresh fastest as battery chemistry advances compress obsolescence windows.
- Manual Snowrator:Human-propelled units with fixed-angle auger assemblies require physical operator effort for snow discharge. Demand clusters in rural Vermont and New Hampshire residential markets where driveway lengths fall below motorized equipment economic thresholds.
- Electric Snowrator:Battery-powered traction and auger systems with lithium-ion cell packs rated for cold-weather discharge profiles. Minneapolis-St. Paul airport authorities pilot overnight charging depot configurations for apron clearing operations where EPA emissions compliance scores weigh heavily in procurement evaluations.
- Gas-Powered Snowrator:Internal combustion engines ranging from 200cc to 800cc displacement power commercial-grade auger-and-impeller assemblies. Wisconsin and Michigan municipal fleets favor these units for roadway shoulder clearing where runtime reliability exceeds twelve hours between refueling.
- Hybrid Snowrator:Parallel powertrain architectures combining diesel prime movers with electric traction motors for load-dependent efficiency optimization. Emerging deployments in Illinois tollway maintenance yards where idle-reduction mandates from state environmental regulators constrain pure combustion specifications.
Gas-powered snowrators dominate installed base. Electric snowrators are where expansion concentrates.
Application:
Municipal contracts carry the longest equipment lifecycles and most stringent certification requirements, while commercial segments prioritize throughput specifications over longevity.
- Residential:Single-family driveway and walkway clearing with compact chassis dimensions under 30 inches width. Upper Midwest homeowners in Minnesota and North Dakota replace units every seven to nine seasons following average snowfall accumulation patterns.
- Commercial:Parking lot and retail pad clearing requiring continuous runtime capability across multi-acre surface areas. Chicago-area property management firms bundle snowrator procurement with seasonal service contracts that specify equipment availability clauses.
- Municipal:Roadway shoulder, sidewalk, and auxiliary infrastructure maintenance with integrated chassis mounting systems. New York State Department of Transportation specifications require Tier 4 Final emissions compliance and OSHA winter workplace safety certification for all new fleet additions.
- Industrial:Airport apron, railyard, and port terminal operations demanding corrosion-resistant materials and explosion-proof electrical classifications. Cleveland Hopkins International Airport specifications drive demand for specialized stainless steel auger assemblies in de-icing chemical environments.
Municipal applications anchor manufacturer revenue stability. Commercial applications are climbing the fastest.
End User:
Government agencies operate on fixed fiscal year procurement calendars with extended vendor qualification periods, while contractors navigate seasonal cash-flow asymmetries that compress decision timelines.
- Homeowners:Individual consumers purchasing through retail dealer networks or direct online channels with financing arrangements spanning 24 to 48 months. Michigan and Ohio markets show concentration of replacement demand following severe winter damage to aging equipment.
- Contractors:Multi-location snow removal operators managing dispersed equipment pools across municipal and commercial contract portfolios. Minnesota-based regional operators increasingly negotiate direct service relationships bypassing traditional dealer intermediaries for parts and maintenance provisioning.
- Government Agencies:State departments of transportation, county highway departments, and municipal public works divisions with formal bidding processes and multi-year fleet replacement schedules. Massachusetts and Illinois procurement departments weight emissions compliance scores heavily in Q3 evaluation cycles.
- Property Managers:Commercial real estate operators and homeowners associations outsourcing snow removal to contracted service providers or maintaining captive equipment for in-house operations. Chicago condominium associations favor lease-to-own structures that align equipment payments with seasonal assessment collections.
Contractors represent the largest volume channel. Government agencies are gaining share fastest.
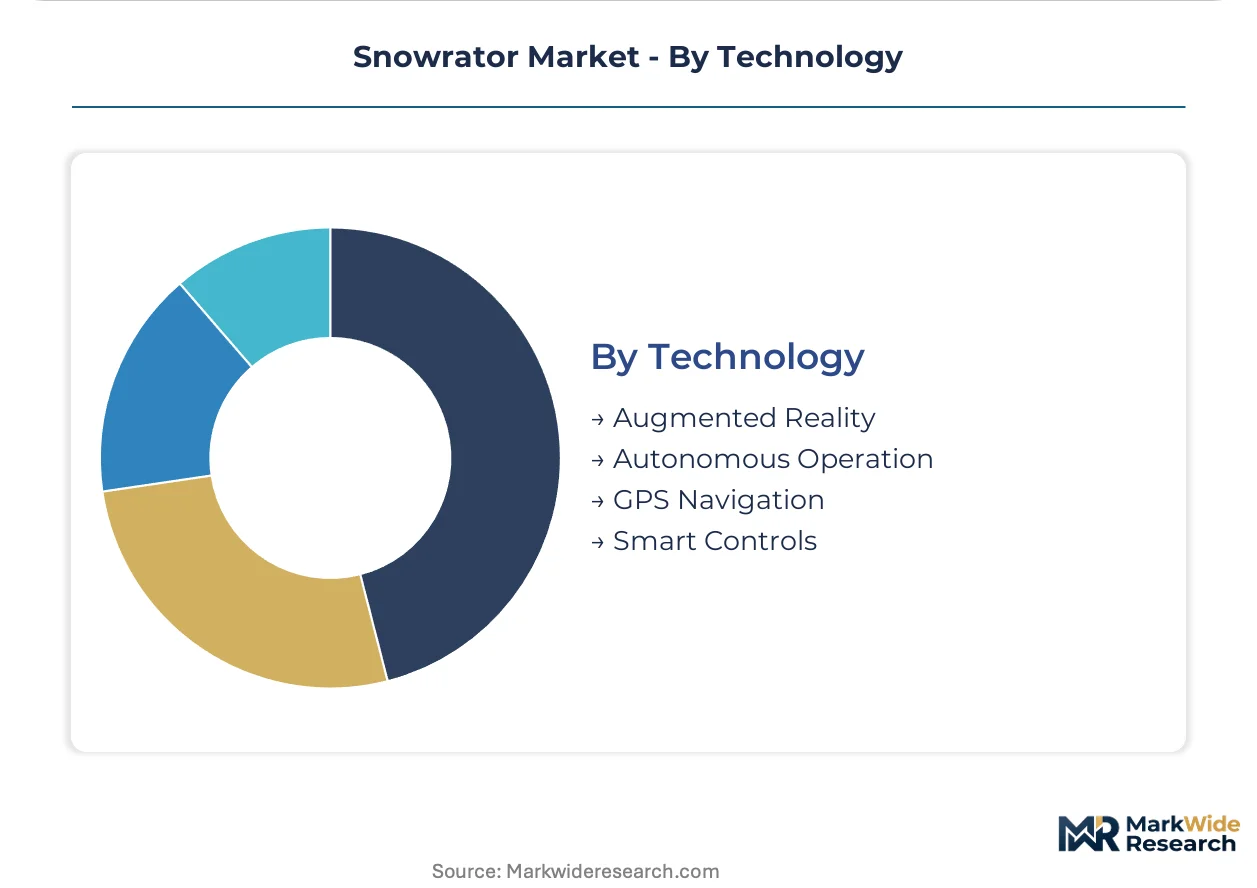
Technology:
Smart control integration is accelerating replacement cycles as fleet management software becomes standard in municipal specifications, while autonomous operation remains in extended pilot phases.
- Augmented Reality:Operator head-up displays projecting snow depth mapping and obstacle detection overlays through helmet-mounted or cab-integrated screens. Early deployments in Wisconsin airport ground operations where visibility constraints from blowing snow create safety-critical navigation challenges.
- Autonomous Operation:Lidar and camera-based navigation systems enabling perimeter-defined clearing without continuous operator presence. Minneapolis-St. Paul pilot programs test overnight apron clearing with remote monitoring from central dispatch facilities.
- GPS Navigation:Fleet tracking and route optimization systems documenting equipment location, utilization hours, and service intervals. Michigan Department of Transportation mandates GPS integration for all new snowrator acquisitions to support performance-based contracting with regional maintenance providers.
- Smart Controls:IoT-enabled auger speed modulation and traction management responding to real-time snow density sensors and surface condition feedback. Chicago-area commercial fleets adopt these systems to reduce fuel consumption and blade wear across variable storm intensity profiles.
GPS navigation dominates current installations. Autonomous operation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saint Lawrence Seaway and Great Lakes port network underwrites North American snowrator distribution logistics, connecting Upper Midwest manufacturing clusters to Atlantic coastal demand centers.
United States
Minnesota and Wisconsin municipal fleets drive replacement demand through airport apron modernization and tollway shoulder clearing programs. EPA Phase III emissions standards constrain diesel engine specifications for Illinois and New York Department of Transportation procurements. Minneapolis-St. Paul airport authorities pilot overnight charging depot configurations for electric snowrator trials.
Canada
Ontario and Quebec provincial highway departments maintain decade-long fleet replacement schedules tied to Trans-Canada Highway winter maintenance contracts. Environment Canada federal emissions guidelines align with EPA Tier 4 Final standards for cross-border equipment interoperability. Toronto Pearson International Airport specifications drive demand for corrosion-resistant stainless steel auger assemblies in heavy de-icing chemical environments.
Germany
Bavarian municipal tender requirements prioritize EU F-Gas Regulation compliance and CE machinery directive certification for low-emission equipment eligibility. Winter service vehicle procurement in Baden-Württemberg concentrates replacement spending in Q3 budget cycles. Munich airport ground operations test chassis-integrated snow removal systems with hybrid powertrain architectures.
Japan
Hokkaido prefectural governments manage snow removal equipment fleets for rural roadway networks facing extreme snowfall accumulation. METI industrial standards shape domestic manufacturer specifications for cold-weather battery performance thresholds. Sapporo metropolitan area trials autonomous navigation systems for overnight sidewalk clearing operations.
China
Beijing-Tianjin-Hebei municipal authorities accelerate fleet electrification under dual carbon policy mandates for state-owned winter service operations. MIIT equipment certification requirements govern import eligibility for foreign snowrator manufacturers. Harbin airport infrastructure expansion drives demand for high-throughput auger-and-impeller systems in sub-zero operating conditions.
Snowrator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in auger fabrication and traction motor supply. The vendor base stratifies across three tiers: diversified outdoor power equipment conglomerates, dedicated snow removal equipment fabricators, and regional chassis-integrated system specialists. Strategic moves concentrate on lease-to-own channel innovation and telematics-enabled fleet management service bundling.
Among North American diversified equipment manufacturers, Douglas Dynamics and The Toro Company exemplify platform integrators with established distribution footprints across snow-belt states. Aebi Schmidt Holding AG occupies a position within the European municipal specialist tier, representing chassis-integrated system architecture for airport and roadway applications. These three anchors illustrate divergent geographic concentration and procurement channel strategies across municipal and commercial buyer segments.
| Leading Market Players |
|---|
| Douglas Dynamics |
| The Toro Company |
| Arctic Snow and Ice Products |
| Aebi Schmidt Holding AG |
| Henke Manufacturing Corporation |
| Metal Pless |
| Meyer Products |
| KAGE Innovation |
| Buyers Products Company |
| Others |
Value Network & Pricing Analysis
Undercapacity in Tier 4 Final diesel engine fabrication across the industrial Midwest is compressing supplier pricing power while accelerating electric powertrain substitution decisions among municipal procurement departments.
Pricing Analysis
Volume-discount tiering structures separate municipal fleet contracts from commercial contractor purchases, with the former capturing standard-tier pricing through multi-unit bidding and the latter facing premium-tier quotes for single-unit reliability guarantees. Price differentiation rests on EPA certification grade and after-sales service bundling, where Tier 4 Final compliance adds cost and predictive maintenance contracts command margin. Cost compression in the gas-powered tier is intensifying because steel and aluminum input volatility erodes visibility on multi-year municipal contracts. Contractor segments exhibit highest price sensitivity due to seasonal cash-flow asymmetries, while airport authorities demonstrate lowest sensitivity given throughput-critical operational requirements.
Supply Chain Analysis
Export-control regime restrictions on lithium-ion cell technology limit battery pack sourcing flexibility for North American electric snowrator assemblers, constraining supply chain reconfiguration options. Manufacturing concentration centers on the United States, Germany, and China, with auger fabrication drawing from domestic metalworking clusters and traction motor production anchored in East Asian electronics corridors. Single-source vulnerability in selective catalytic reduction componentry creates procurement risk for diesel powertrain variants. Distribution runs through Saint Lawrence Seaway port networks connecting Great Lakes manufacturing to Atlantic coastal demand centers, with dealer networks competing against direct municipal procurement channels for fleet contract access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity justified by telematics-enabled fleet management software expanding faster than hardware unit sales across municipal and commercial buyer segments.
For Market Incumbents: Insulate core municipal relationships by deepening captive supply of auger-and-impeller assemblies through backward integration into Midwest metalworking capacity, while accelerating certification investment for hybrid powertrain variants ahead of Illinois idle-reduction mandates. Electric entrant pressure and EPA Phase III compliance cost escalation threaten legacy diesel portfolio margins without defensive repositioning.
For New Entrants and Emerging Players: Establish a beachhead in the electric snowrator segment by targeting Minneapolis-St. Paul airport pilot programs where overnight charging infrastructure exists and emissions compliance scores dominate procurement evaluations. Lease-to-own channel innovation offers the most penetrable go-to-market angle for contractor segments navigating seasonal cash-flow constraints.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-powered platform development, shifting viability assessment toward software-enabled recurring revenue attachment rather than pure hardware scale. Acquisition targets should display integrated telematics capabilities and established municipal qualification status. The signal to monitor is lithium-ion energy density improvement trajectories crossing cold-weather performance thresholds for northern tier state deployment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | GPS tracking and predictive maintenance software create recurring revenue attachment beyond equipment sale. |
| Hybrid Powertrain Development | Parallel diesel-electric architectures satisfy Illinois idle-reduction mandates while preserving runtime reliability. |
| Lease-to-Own Channel Expansion | Equipment financing structures align contractor cash-flow patterns with seasonal revenue collection cycles. |
| Stainless Steel Auger Sourcing | Corrosion-resistant materials meet Cleveland Hopkins and Toronto Pearson de-icing chemical environment specifications. |
| Overnight Charging Depot Partnership | Airport authority collaboration validates electric variant runtime thresholds for apron clearing operations. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with municipal fleet managers, snow removal contractors, airport ground operations directors, and aftermarket service providers; and secondary validation through EPA emissions filings, OSHA workplace safety directives, municipal procurement databases, and trade customs records. Bottom-up unit demand estimation triangulated against top-down market sizing across powertrain type, application tier, and end-user category.
Forecast inputs considered replacement cycle velocity differentials between municipal decade-long schedules and contractor four-to-six season refresh patterns, battery chemistry improvement trajectories, and regulatory compliance timeline compression across the projection horizon. Segmentation modeling captured product type, application, end user, and technology dimensions with CAGRs derived from historical procurement pattern analysis and forward-looking fleet electrification mandate assessment.
Sensitivities concentrate around lithium-ion cold-weather performance thresholds, steel and aluminum commodity index movements, and EPA certification timeline extensions for new powertrain variants. Forecasts reflect documented assumptions regarding infrastructure buildout pace and regulatory enforcement intensity. Material shifts in battery energy density improvement rates or municipal electrification mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
PCB Punching Machine Market