
 Diaphragm Coupling Market | 2026-2036
Diaphragm Coupling Market Size, Share, and Industry Trends Forecast 2026-2036
Diaphragm Coupling Market Analysis
Multi-source procurement is realigning how major energy and industrial OEMs qualify diaphragm coupling suppliers. Rexnord Corporation leverages its integrated disc pack manufacturing to sustain delivery reliability for North American power projects. Siemens Energy anchors European demand through turbine aftermarket contracts. John Crane competes on API 671 certification depth across Middle Eastern refinery installations.
A diaphragm coupling transmits torque through a flexible metallic disc pack while accommodating angular, parallel, and axial misalignment between rotating shafts; laser-welded stainless steel disc stacks achieve fatigue lives exceeding ten million cycles under balanced load conditions. Metal diaphragm variants dominate margin pools in oil and gas and power generation applications due to temperature tolerance and zero-backlash precision. Composite diaphragm configurations are gaining fastest in robotics and aerospace where weight reduction intersects with torsional stiffness requirements.
API 671 governs refinery and petrochemical coupling specifications in the United States, while EU machinery directives enforced by national regulators mandate fail-safe design documentation for industrial rotating equipment. China's GB standards and SAMR quality certification shape market access for imported flexible coupling assemblies. Stakeholders must monitor evolving material traceability rules and welding qualification protocols as procurement specifications tighten across energy and marine end users.
Market Dynamics
Laser-welded disc pack manufacturing is compressing fatigue tolerance thresholds while API 671 alignment standards tighten procurement qualification cycles across oil and gas turbomachinery installations.
Growth Catalysts
- API 671 Standards:Refinery operators in the United States mandate certified flexible couplings for critical rotating equipment, forcing specification upgrades across supplier bases.
- China:SAMR quality certification and GB standards for industrial couplings accelerate import substitution programs in domestic energy infrastructure builds.
- Laser Welding:Automated disc stack fabrication extends fatigue life beyond ten million cycles, enabling longer maintenance intervals in offshore platform applications.
Market Restraints
- Nickel Alloy Volatility:Inconel and stainless steel price swings compress margin buffers for disc pack manufacturers serving project-based procurement cycles.
- German Supplier Concentration:Precision machining capacity for high-torque diaphragm couplings clusters in Baden-Württemberg and Bavaria, creating single-source vulnerability.
- Gear Coupling Substitution:Lower-cost gear-type flexible couplings retain share in non-critical auxiliary machinery where backlash tolerance permits.
Strategic Opportunities
- India:CEA mandates for grid stability equipment and PLI scheme incentives for domestic manufacturing create entry paths for certified coupling suppliers.
- Robotics Integration:Composite diaphragm configurations address torsional stiffness requirements in collaborative robot joints where metal variants exceed mass budgets.
- EU Green Deal:Carbon border adjustment mechanisms favor local European disc pack production over imported assemblies from carbon-intensive supply chains.
Industry Challenges
- Welding Qualification Bottlenecks:ASME Section IX and ISO 15614-1 procedure qualifications for laser-welded disc stacks extend supplier onboarding timelines by six to twelve months.
- Legacy Turbine Retrofit Compatibility:API 671-compliant diaphragm couplings require shaft modification protocols that conflict with original equipment dimensional tolerances in 1980s-era installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaphragm Coupling Market |
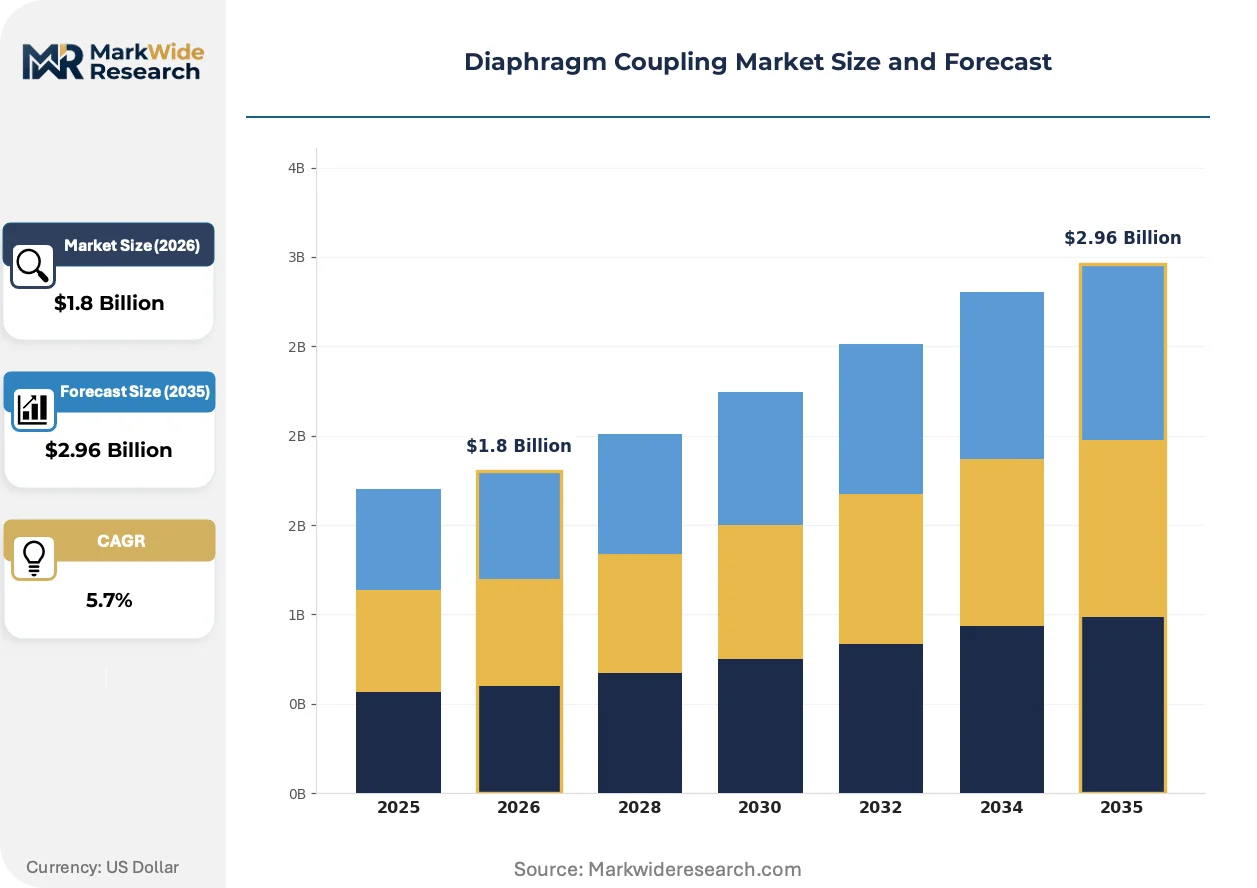
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Diaphragm, Rubber Diaphragm, Composite Diaphragm, Spring Diaphragm Application: Industrial Machinery, Robotics, Automotive, Aerospace End User: Manufacturing, Oil & Gas, Power Generation, Marine Size: Small, Medium, Large, Extra Large |
| Companies Covered | Altra Industrial Motion, Voith GmbH, Rexnord Corporation, KOP-FLEX, John Crane, Siemens Energy, Eagle Industry Co., Ltd., KTR Corporation, SKF Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaphragm Coupling Market Emerging Trajectories
Additive manufacturing of disc pack spacers is compressing lead times for prototype validation while digital twin integration enables predictive maintenance contracts. These shifts are reconfiguring how coupling suppliers monetize hardware versus service relationships.
Thin-walled maraging steel disc stacks is overtaking conventional stainless steel configurations in next-generation gas turbine couplings. Siemens Energy and Mitsubishi Heavy Industries specify these alloys for combined-cycle plants above 400 megawatts. The material transition is overtaking established supplier qualification frameworks and forcing recertification of welding procedures.
REACH substance restrictions on hexavalent chromium coatings are compelling surface treatment migration to trivalent alternatives or plasma nitriding for corrosion protection. German coupling manufacturers face the tightest compliance deadlines under ECHA enforcement timelines. Marine propulsion applications in Northern European shipyards show the fastest coating technology turnover.
Buyer consolidation among integrated oil companies is compressing approved vendor lists from twelve to four qualified diaphragm coupling sources per major project. Engineering-procurement-construction firms now mandate sole-source accountability for rotating train packages. This concentration is most visible in Middle Eastern refinery expansions where Saudi Aramco and ADNOC coordinate procurement specifications.
Diaphragm Coupling Market Segmentation

Segmentation in the diaphragm coupling market reveals how material science, torque requirements, and regulatory environments partition demand across incompatible specification tiers. Procurement teams in oil and gas, power generation, and advanced manufacturing each operate within distinct technical and commercial boundaries that reshape supplier qualification priorities.
Product Type:
Laser-welded disc pack geometries and fatigue tolerance thresholds differentiate performance classes across torque transmission applications.
- Metal Diaphragm:Stainless steel or Inconel disc stacks welded into laminated packs deliver torque capacity above 500 kNm with angular misalignment tolerance to 1.5 degrees. API 671 certification requirements in United States refinery expansions concentrate procurement of these variants for critical turbomachinery trains.
- Composite Diaphragm:Carbon fiber-reinforced polymer laminates bonded to metallic hubs achieve 40-60% mass reduction versus all-metal equivalents. Aerospace actuator manufacturers and collaborative robotics OEMs specify these configurations where torsional stiffness must coexist with strict payload limits.
- Rubber Diaphragm:Elastomeric membranes molded with fabric reinforcement absorb vibration in lower-torque pump and compressor drives where temperature exposure stays below 120°C.
- Spring Diaphragm:Coiled spring elements integrated into disc packs provide extended axial travel for applications with significant thermal expansion differentials between coupled shafts.
Metal Diaphragm leads on scale; Composite Diaphragm leads on momentum.
Application:
Precision requirements and duty cycle intensity determine which coupling architectures penetrate specific machinery categories.
- Industrial Machinery:Continuous process equipment in chemical plants and steel mills demands maintenance-free operation across decade-long service intervals. German machinery OEMs specify laser-welded metal disc packs for rolling mill drives and extruder lines.
- Aerospace:Fuel pump couplings and auxiliary power unit drives must survive thermal cycling between -55°C and 300°C. FAA certification protocols and EASA CS-25 airworthiness standards govern material traceability for flight-critical installations.
- Robotics:Six-axis articulated arms require zero-backlash torque transmission with minimal reflected inertia. Composite diaphragm configurations from Japanese and South Korean suppliers dominate collaborative robot joint designs.
- Automotive:Test stand dynamometers and electric vehicle motor test cells employ medium-duty metal diaphragm couplings for high-speed shaft connection.
Industrial Machinery commands the largest installed base; Aerospace exhibits the steepest specification escalation.
End User:
Project-based procurement cycles and regulatory exposure create divergent margin structures across vertical markets.
- Oil & Gas:Offshore platform operators and Middle Eastern refinery developers mandate API 671 compliance with full material certification packages. Saudi Aramco and ADNOC procurement specifications compress approved vendor lists to four qualified sources per major project.
- Power Generation:Combined-cycle gas turbine OEMs specify maraging steel disc stacks for units above 400 megawatts. Siemens Energy and Mitsubishi Heavy Industries drive alloy transitions that force welding procedure recertification across supplier bases.
- Marine:Classification society rules from Lloyd's Register and DNV govern coupling selection for propulsion shafts and auxiliary machinery. Northern European shipyards show fastest coating technology turnover under REACH hexavalent chromium restrictions.
- Manufacturing:General industrial automation and machine tool builders prioritize delivery reliability and standard catalog configurations over custom engineering.
Oil & Gas concentrates the highest specification premiums; Power Generation is expanding most quickly through turbine aftermarket contracts.
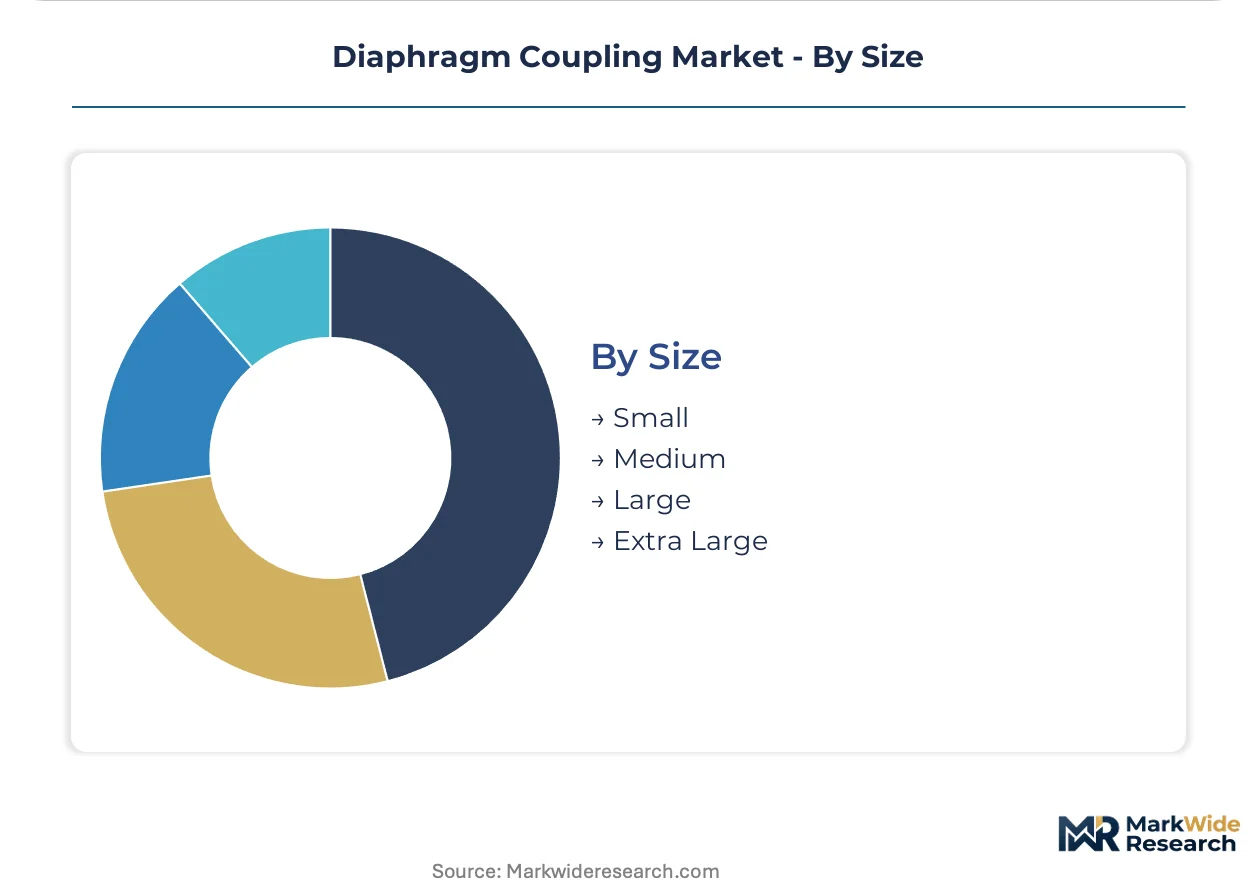
Size:
Torque density and shaft diameter ranges segment manufacturing capabilities and supplier specialization.
- Large:Disc packs exceeding 400mm outer diameter require five-axis machining of hub forgings and specialized heat treatment furnaces. Baden-Württemberg precision machining clusters in Germany dominate this tier.
- Extra Large:Custom-engineered couplings for hydroelectric turbines and steel mill roughing stands demand project-specific finite element validation and on-site installation supervision.
- Medium:Standardized catalog offerings serve the broadest cross-section of industrial pump, compressor, and generator applications with six-to-eight-week delivery cycles.
- Small:Miniature diaphragm couplings below 50mm diameter address precision instrumentation, medical devices, and small servo motor connections.
Large size dominates revenue concentration; Extra Large climbs the fastest through infrastructure megaproject pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping diaphragm coupling manufacturing footprints as REACH compliance costs in Germany push some disc pack fabrication toward Eastern European precision machining clusters and Chinese laser-welding facilities with lower environmental remediation burdens.
United States
API 671 certification mandates from refinery operators in Texas and Louisiana concentrate procurement of metal diaphragm couplings for critical turbomachinery trains. EPA enforcement of air quality standards around Houston's petrochemical corridor tightens material traceability requirements for offshore platform suppliers. The Permian Basin expansion drives demand for high-torque couplings in gas compression stations.
Germany
Baden-Württemberg and Bavaria host precision machining clusters that dominate large-diameter disc pack manufacturing for European power generation OEMs. ECHA enforcement of REACH hexavalent chromium restrictions accelerates coating technology migration toward plasma nitriding alternatives. Siemens Energy's turbine aftermarket contracts anchor regional demand for maraging steel coupling configurations.
China
SAMR quality certification and GB standards for industrial couplings accelerate domestic substitution programs in Yangtze River Delta energy infrastructure builds. MIIT dual carbon goals pressure steel mill operators to upgrade rolling mill drives with maintenance-free diaphragm couplings. Shanghai and Jiangsu province fabrication clusters expand laser-welding capacity for export-oriented disc pack production.
India
CEA mandates for grid stability equipment and PLI scheme incentives for domestic manufacturing create entry paths for certified coupling suppliers in Maharashtra and Gujarat. BIS standards alignment with API specifications enables refinery procurement localization for Reliance Industries and Indian Oil installations. Tamil Nadu's power equipment manufacturing corridor attracts joint venture partnerships for turbine coupling fabrication.
Saudi Arabia
Saudi Aramco procurement specifications compress approved vendor lists to four qualified diaphragm coupling sources per major refinery expansion in the Eastern Province. SFDA-equivalent industrial quality enforcement through SASO standards governs material certification for rotating equipment in Jubail Industrial City. NEOM infrastructure megaprojects drive specification premiums for API 671-compliant coupling packages.
Diaphragm Coupling Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue composite material specializations for robotics and aerospace applications. The supplier base concentrates around three strategic archetypes: integrated industrial conglomerates with captive disc pack manufacturing, precision machining specialists serving project-based energy procurement, and materials-science-driven innovators targeting weight-critical applications. Competitive moves center on welding procedure recertification for maraging steel alloys and sole-source accountability contracting for rotating train packages.
Among Germany-based precision engineering groups, Voith GmbH and KTR Corporation exemplify the machining-specialist archetype with concentrated capabilities in Baden-Württemberg fabrication clusters. Rexnord Corporation represents the North American integrated producer model with in-house disc pack manufacturing sustaining delivery reliability for power project procurement cycles. John Crane occupies a position within the premium-tier certification depth segment, anchoring Middle Eastern refinery vendor lists through API 671 compliance breadth.
| Leading Market Players |
|---|
| Altra Industrial Motion |
| Voith GmbH |
| Rexnord Corporation |
| KOP-FLEX |
| John Crane |
| Siemens Energy |
| Eagle Industry Co., Ltd. |
| KTR Corporation |
| SKF Group |
| Others |
Supply Flow & Price Mechanics
Captive disc pack manufacturing by Rexnord Corporation and Siemens Energy anchors supply security for project-based turbomachinery procurement, translating welding procedure mastery into pricing power over spot-market-dependent competitors. API 671 certification depth and laser-welding automation compress cost structures for integrated producers while forcing margin erosion on specification-lagging suppliers.
Pricing Analysis
Distributor margins for standard catalog couplings run 15-25 points above direct-to-OEM project pricing, with EPC contractors capturing volume discounts through rotating train package bundling. Three-tier pricing structure across premium, standard, and economy levels separates API 671-certified marine-grade configurations from industrial machinery catalog items. Cost compression in standard metal diaphragm tiers intensifies because Chinese laser-welding capacity expands export-oriented production. Refinery operators in Saudi Arabia and the United States exhibit lowest price sensitivity due to failure-cost exposure, while general manufacturing buyers in India prioritize catalog availability over certification depth.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore enable hub-and-spoke patterns for emergency replacement orders, compressing field service response times for offshore platform operators. Manufacturing gravity centers on Germany for large-diameter precision machining, China for laser-welding capacity expansion, and the United States for API-certified assembly integration. Inconel 718 and maraging steel feedstock sourcing draws from specialty alloy producers in the United States and Japan. Single-source vulnerability concentrates in Baden-Württemberg machining clusters for extra-large coupling forgings. Distribution runs through authorized service networks for certified installations and direct-ship channels for standard industrial replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in diaphragm couplings rests on laser-welding automation cost-down trajectories and specification premium capture in API 671 marine and refinery tiers.
For Market Incumbents: Anchor welding procedure recertification capabilities for maraging steel alloys to defend against emerging entrants with composite material specializations. Deepen backward integration into Inconel alloy sourcing to buffer nickel price volatility exposure. Compress approved vendor list positioning through sole-source accountability contracting for Saudi Aramco and ADNOC megaprojects. For New Entrants and Emerging Players: Capture collaborative robotics and aerospace actuator white-space where composite diaphragm configurations outperform metal variants on mass-stiffness ratios. Penetrate India's PLI-incentivized domestic manufacturing corridor through BIS-API alignment certification. Lead with rapid prototype validation using additive-manufactured disc pack spacers to bypass incumbent tooling lead times. For Investors and Strategic Acquirers: Roll-up economics work for precision machining specialists because welding qualification bottlenecks create durable moats around certified supplier bases. Target mid-cap German and Japanese fabrication assets with captive maraging steel process knowledge. Watch laser-welding equipment utilization rates at Yangtze River Delta clusters as inflection indicator for Chinese export pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Maraging Steel Welding Recertification | Siemens Energy and Mitsubishi Heavy Industries specifications force procedure reinvestment across supplier bases. |
| Composite Diaphragm R&D Partnership | Collaborative robot OEMs in Japan and South Korea demand mass-reduced configurations for joint actuation. |
| API 671 Certification Depth Expansion | Middle Eastern refinery procurement compresses vendor lists to four qualified sources per project. |
| India PLI Manufacturing Localization | CEA grid stability mandates and BIS alignment create entry paths for certified coupling fabrication. |
| REACH-Compliant Coating Migration | ECHA enforcement accelerates plasma nitriding adoption at German marine propulsion suppliers. |
Methodological Framework
Direct dialogue with turbomachinery procurement directors, API certification auditors, laser-welding equipment specialists, and refinery maintenance engineers grounded qualitative assessment of specification evolution and supplier qualification dynamics. Secondary validation drew from API 671 documentation repositories, SAMR certification registries, ECHA substance restriction timelines, and customs trade data for Inconel and stainless steel alloy flows. Bottom-up unit economics for disc pack fabrication integrated with top-down energy infrastructure investment pipelines to triangulate demand projections.
Segmentation-level outputs across metal, composite, rubber, and spring diaphragm configurations, torque capacity tiers, and end-use verticals were modeled across the projection horizon. CAGRs were derived from elasticity-adjusted equipment procurement cycles tied to refinery expansion timelines and gas turbine aftermarket patterns. Forecast inputs incorporated welding procedure qualification bottlenecks, nickel alloy price volatility assumptions, and REACH compliance cost trajectories for European coating migration.
Refinery project delays, nickel alloy supply disruptions, and composite material qualification breakthroughs are the dominant revision risks that could compress or extend stated growth trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Pin Insertion Machine Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Global Linear Bearings Market