
 Semiconductor Pyrometers Market | 2026-2036
Semiconductor Pyrometers Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Pyrometers Market Insights
A shortage of metrology engineers trained in sub-micron thermal characterization is redrawing competitive boundaries across the supply base. Advanced Energy leverages its R&D intensity to anchor North American demand for high-precision optical systems. AMETEK Land sustains manufacturing scale across European wafer fabrication facilities through established channel partnerships. CHINO Corporation dominates Asian markets with localized service networks and region-specific calibration protocols.
Semiconductor pyrometers are non-contact temperature measurement instruments that detect infrared radiation emitted from silicon wafers and process chambers, typically operating across spectral ranges from 0.5 to 14 micrometers to monitor thermal budgets during epitaxy, annealing, and chemical vapor deposition. Their primary purpose is preventing thermal runaway and ensuring within-die temperature uniformity during advanced node manufacturing. Infrared pyrometers lead product category revenue due to their compatibility with vacuum chamber environments and immunity to electromagnetic interference from plasma tools. Smart sensors represent the fastest-growing technology segment as foundries integrate AI-driven predictive maintenance into thermal process control loops. Quality control applications command premium pricing margins because device yield sensitivity to temperature variation intensifies at nodes below seven nanometers.
EPA clean air standards and OSHA workplace safety mandates in the United States shape pyrometer specifications by requiring sealed optical paths and remote monitoring capabilities in hazardous process environments. REACH substance restrictions and RoHS compliance frameworks in Europe limit mercury-based detector materials, accelerating indium gallium arsenide and pyroelectric alternative adoption. Semiconductor manufacturers must monitor how FDA device-quality traceability requirements and evolving ISO 17025 calibration standards reshape supplier qualification timelines and aftermarket service obligations.
Market Dynamics
The migration toward three-nanometer and below process nodes is compressing thermal budget tolerances to sub-five-degree margins, forcing foundries to replace legacy thermocouple arrays with multi-wavelength infrared pyrometry across diffusion and etch chambers.
Growth Catalysts
- EPA Clean Air Act Amendments:Emissions monitoring mandates in US semiconductor fabrication plants are accelerating non-contact pyrometer deployment for sealed chamber temperature verification without probe penetration.
- Silicon carbide power device manufacturing:Wide-bandgap substrate processing requires pyrometers operating above 1,600°C, creating specialized demand from automotive and renewable energy component suppliers.
- Hsinchu-Taichung corridor expansion:Taiwan's concentrated foundry buildout is driving localized calibration service infrastructure and region-specific spectral response protocols.
Market Restraints
- Indium gallium arsenide detector costs:Mercury-free alternatives compliant with REACH substance restrictions carry 40-60% raw material premiums versus legacy detector technologies.
- East Asian supply concentration:Critical optical component fabrication concentrates in Japanese and South Korean specialty glass manufacturers, exposing buyers to single-source vulnerability.
- Optical path contamination sensitivity:Pyrometer accuracy degrades exponentially with chamber deposition residue accumulation, requiring frequent recalibration cycles that interrupt production throughput.
Strategic Opportunities
- India's semiconductor mission:The country's PLI scheme for domestic chip fabrication is creating greenfield demand for process temperature monitoring infrastructure without incumbent vendor lock-in.
- AI-driven predictive maintenance convergence:Machine learning integration with pyrometer data streams enables real-time thermal drift prediction, opening software-anchored service revenue models.
- EU Green Deal carbon accounting:Embedded energy traceability requirements are pushing European device manufacturers toward pyrometer-verified process efficiency certifications as competitive differentiation.
Industry Challenges
- Sub-micron thermal metrology expertise scarcity:The shortage of engineers trained in emissivity compensation algorithms for patterned wafer surfaces is extending commissioning timelines for advanced node installations.
- ISO 17025 calibration standard evolution:Shifting international accreditation requirements for thermal radiation reference standards are forcing suppliers to maintain parallel certification tracks across regional accreditation bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Pyrometers Market |
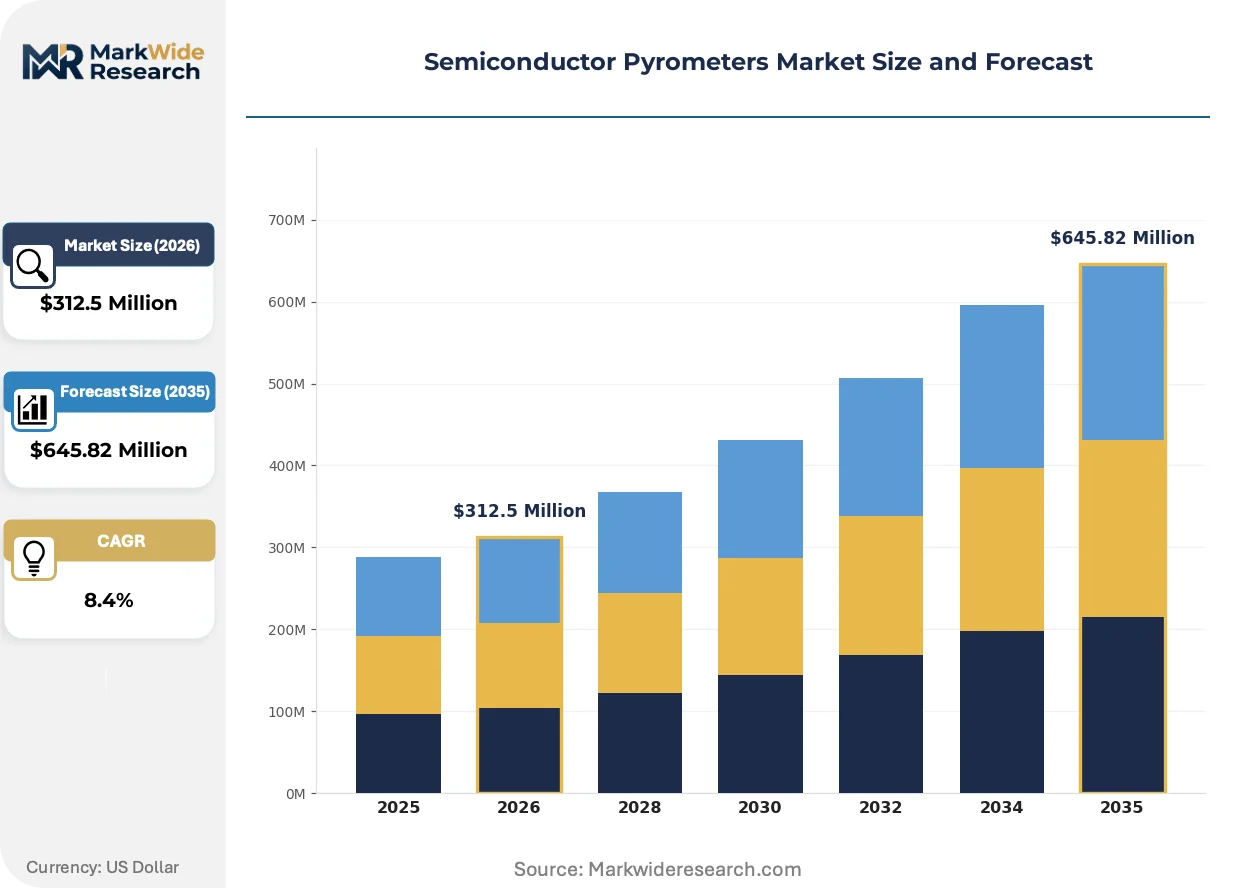
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Pyrometers, Optical Pyrometers, Digital Pyrometers, Laser Pyrometers Technology: Non-Contact Measurement, Contact Measurement, Dual-Function Technology, Smart Sensors Application: Manufacturing Processes, Quality Control, Research & Development, Temperature Profiling End User: Electronics, Automotive, Aerospace, Pharmaceuticals |
| Companies Covered | Keller ITS, AMETEK Land, Advanced Energy, CI Semi, k-Space Associates, DIAS Infrared, Optris, CHINO Corporation, Fluke Process Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Pyrometers Market Trends and Innovations
Multi-spectral pyrometry architectures are displacing single-wavelength legacy designs as process complexity outstrips conventional measurement fidelity, while regulatory chemical bans and AI integration are rewriting hardware specifications and service delivery models simultaneously.
Short-wave infrared pyrometry spanning 1.0 to 2.5 micrometers is fragmenting the established near-infrared product hierarchy. Memory manufacturers in South Korea are adopting these systems for high-aspect-ratio etch profile monitoring where longer wavelengths suffer optical interference. The technology is fragmenting vendor R&D roadmaps as incumbents face pressure to maintain parallel spectral product lines rather than consolidate around dominant architectures.
REACH Annex XVII restrictions on mercury-containing substances are eliminating cadmium-mercury-telluride detectors from European supply chains by 2027. Equipment suppliers are accelerating indium gallium arsenide and quantum dot alternative qualification to maintain CE marking eligibility. Pyroelectric and thermopile architectures are capturing incremental share in lower-precision applications where spectral selectivity requirements relax.
Foundry procurement organizations are unbundling pyrometer hardware from integrated service contracts, separating capital equipment acquisition from calibration and predictive analytics subscriptions. Taiwan-based buyers are driving this disaggregation, pressuring vendors to disclose algorithmic drift compensation methodologies as condition of technical evaluation. The shift concentrates pricing leverage with buyers possessing in-house metrology capabilities while marginalizing smaller fabs dependent on turnkey vendor relationships.
Semiconductor Pyrometers Market Segmentation
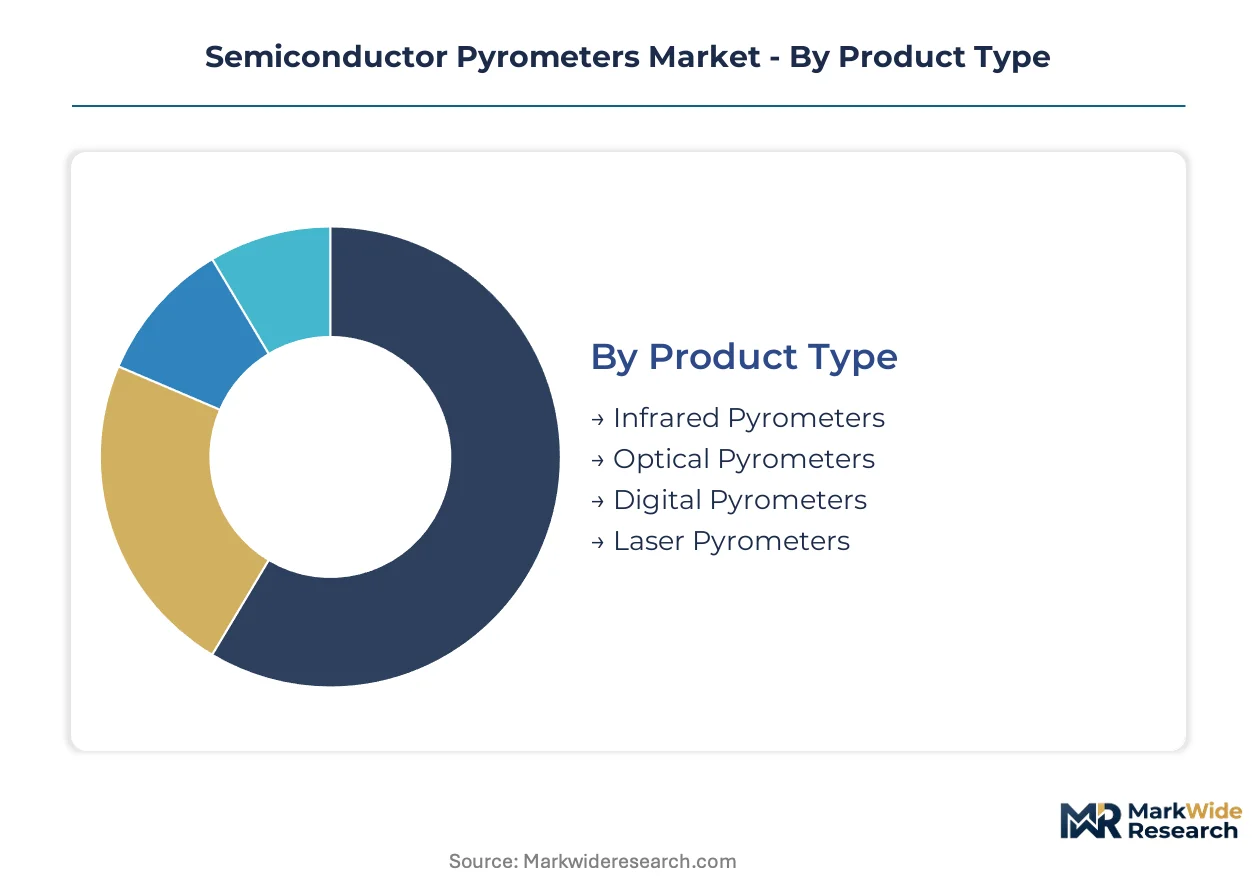
Semiconductor pyrometers serve distinct thermal monitoring requirements across fabrication workflows, with spectral range and measurement modality determining compatibility with specific process chambers. Substitution pressures from alternative temperature sensing technologies reshape competitive dynamics within each segment category.
Product Type:
Infrared pyrometers face intensifying substitution pressure from fiber-optic thermometry in high-electromagnetic-interference environments, while optical variants confront displacement by multi-spectral architectures.
- Infrared Pyrometers:These instruments detect thermal radiation across 0.5 to 14 micrometer spectral bands using photodetectors or thermal sensors. Taiwan's Hsinchu-Taichung corridor drives concentrated procurement for vacuum-compatible infrared systems as foundries expand 3nm node capacity.
- Optical Pyrometers:Operating on visible light intensity comparison principles, these systems suit high-temperature silicon carbide processing above 1,600°C. Automotive power device manufacturers in Germany's Saxony cluster specify optical pyrometry for wide-bandgap substrate thermal monitoring.
- Digital Pyrometers:Signal processing units with embedded emissivity compensation algorithms.
- Laser Pyrometers:Coherent light-based systems for specialized etch chamber applications.
Infrared pyrometers retain volume leadership; smart sensors hold the steepest expansion curve.
Technology:
Cost tier differentiation separates premium non-contact architectures from commodity contact alternatives, with dual-function systems bridging mid-market price points.
- Non-Contact Measurement:Infrared and optical detection methods eliminate physical probe interference with sensitive wafer surfaces. South Korean memory manufacturers in the Seoul metropolitan area prioritize non-contact systems for high-aspect-ratio etch profile monitoring where probe contact risks pattern damage.
- Smart Sensors:AI-embedded units with predictive drift compensation and cloud-connected calibration tracking. These systems command premium pricing in quality-critical applications where device yield sensitivity intensifies below 7nm nodes.
- Contact Measurement:Thermocouple-based systems for legacy equipment compatibility and cost-constrained facilities.
- Dual-Function Technology:Hybrid architectures combining contact backup with primary non-contact measurement.
Non-contact measurement dominates revenue contribution; smart sensors gain share fastest.
Application:
Application scope correlates directly with margin structure, with quality control commanding premium pricing and manufacturing processes driving volume throughput.
- Quality Control:Final verification of within-die temperature uniformity and thermal budget compliance. EPA Clean Air Act monitoring mandates in US fabrication plants accelerate pyrometer deployment for sealed chamber emissions verification without probe penetration.
- Manufacturing Processes:Real-time thermal monitoring during epitaxy, annealing, and chemical vapor deposition. India's PLI scheme for domestic semiconductor fabrication creates greenfield demand for process-integrated temperature monitoring infrastructure.
- Research & Development:Experimental thermal characterization for next-generation node development.
- Temperature Profiling:Mapping thermal gradients across wafer surfaces during transient heating cycles.
Manufacturing processes anchor volume demand; quality control delivers the steepest margin expansion.
End User:
End-user concentration in East Asian electronics manufacturing creates geographic demand clustering, with automotive and aerospace representing emerging diversification targets.
- Electronics:Semiconductor foundries and memory manufacturers constitute the core demand base. REACH Annex XVII mercury restrictions are eliminating cadmium-mercury-telluride detectors from European electronics supply chains by 2027, accelerating indium gallium arsenide alternative adoption.
- Automotive:Silicon carbide power device fabrication for electric vehicle inverters and charging infrastructure. Wide-bandgap substrate processing requirements above 1,600°C create specialized pyrometer demand from automotive component suppliers.
- Aerospace:Radiation-hardened component manufacturing and high-reliability thermal verification.
- Pharmaceuticals:Precision thermal control for biopharmaceutical process equipment and medical device manufacturing.
Electronics commands revenue concentration; automotive climbs the fastest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Taiwan and South Korea deploy pyrometers primarily for sub-7nm node thermal budget control, while Germany and the United States emphasize wide-bandgap substrate processing above 1,600°C for automotive power electronics.
Taiwan
Foundries in the Hsinchu-Taichung corridor drive concentrated procurement of vacuum-compatible infrared systems as 3nm capacity expands. The National Development Council's semiconductor advancement initiative funds localized calibration infrastructure. Taichung's precision machinery cluster hosts region-specific spectral response protocol development centers serving TSMC and UMC supply chains.
South Korea
Memory manufacturers in the Seoul metropolitan area prioritize non-contact systems for high-aspect-ratio etch profile monitoring where probe contact risks pattern damage. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program subsidizes thermal metrology equipment for Pyeongtaek and Yongin fab complexes. Samsung and SK Hynix operations in Suwon anchor specialized short-wave infrared adoption.
United States
Silicon carbide power device fabricators and radiation-hardened component manufacturers create dual-demand streams for extreme-temperature and high-reliability pyrometry. EPA Clean Air Act Amendments mandate sealed chamber temperature verification without probe penetration. Arizona's Phoenix-Tucson corridor and New York's Albany nanotech cluster host emerging fab construction driving greenfield equipment procurement.
Germany
Automotive power device manufacturers in Saxony specify optical pyrometry for wide-bandgap substrate thermal monitoring in electric vehicle inverter production. REACH Annex XVII mercury restrictions accelerate indium gallium arsenide detector adoption by 2027. Dresden's Silicon Saxony cluster integrates pyrometer-verified process efficiency into EU Green Deal carbon accounting frameworks.
Japan
Specialty glass and optical component fabricators supply critical pyrometer subsystems to foundries across East Asia. METI's semiconductor equipment localization incentives support domestic detector alternative development. Kyushu's Kumamoto and Miyazaki prefectures concentrate thermal sensor manufacturing serving both captive demand and export markets.
Semiconductor Pyrometers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the semiconductor pyrometers market. The upper tier combines captive optical component supply with multi-regional service networks, while specialists concentrate on single spectral ranges or geographic niches. Three archetypes dominate: R&D-intensive precision instrument developers, manufacturing-scale infrared system fabricators, and localized calibration service providers. Competitive moves center on backward integration into detector materials and strategic partnerships with foundry equipment OEMs.
Within the integrated tier, Advanced Energy and AMETEK Land occupy positions spanning North American and European demand respectively. CHINO Corporation exemplifies the Asia-Pacific archetype with localized service density. These three entities anchor competitive dynamics without exclusive segment control, as specialists in short-wave infrared and silicon carbide-specific temperature ranges retain viable positions in sub-niches.
| Leading Market Players |
|---|
| Keller ITS |
| AMETEK Land |
| Advanced Energy |
| CI Semi |
| k-Space Associates |
| DIAS Infrared |
| Optris |
| CHINO Corporation |
| Fluke Process Instruments |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Japanese specialty glass manufacturers sits above ninety percent, compressing detector substrate availability and anchoring price floors for indium gallium arsenide alternatives. This scale concentration feeds directly into procurement leverage for Taiwan-based foundries while forcing smaller European fabs toward extended lead-time contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement for advanced node foundries, while spot purchasing persists for legacy equipment retrofits. Three-tier pricing structure across premium smart sensors, standard infrared systems, and economy contact thermometers reflects certification grade and spectral range complexity. Cost compression in economy tiers is intensifying because REACH-compliant mercury-free detector materials carry raw material premiums. Memory manufacturers in South Korea exhibit the highest price sensitivity due to volume procurement scale, whereas aerospace radiation-hardened component suppliers accept premium pricing for traceability documentation.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, while Japan supplies critical optical substrates and detector materials. Pyrometer assembly draws from indium phosphide wafers, germanium lenses, and precision thermopile arrays. Single-source vulnerability concentrates in Kyushu-based specialty glass manufacturers serving infrared optical path components. Distribution runs through foundry equipment OEM channel partnerships rather than direct fab sales, with calibration service contracts increasingly unbundled from hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Node migration below three nanometers fragments demand across spectral architectures, creating specialist niches where generalized incumbents lack emissivity algorithm depth.
For Market Incumbents: Consolidate backward integration into detector material supply to offset Japanese substrate bottlenecks. Deepen captive calibration infrastructure in the Hsinchu-Taichung corridor to defend against Taiwan-based buyers unbundling service contracts. Prioritize ISO 17025 accreditation investment as shifting international standards extend supplier qualification timelines. For New Entrants and Emerging Players: Predictive analytics service layers represent the most penetrable white space, as incumbents resist disclosing algorithmic drift compensation methodologies. Target India's greenfield semiconductor fabrication facilities, where PLI scheme incentives create demand without entrenched vendor relationships. Lead with AI-embedded smart sensor offerings positioned against legacy hardware-centric portfolios. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among calibration service providers with captive foundry relationships, offering visibility across the analysis window. Acquisition candidates with indium gallium arsenide detector qualification and regional accreditation tracks present superior long-term viability. Monitor EPA enforcement intensity on Clean Air Act Amendments as inflection signal for non-contact pyrometer replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Materials | Secures indium gallium arsenide supply chains against REACH-driven mercury detector phaseouts. |
| AI-Driven Predictive Maintenance Platform | Captures software-anchored revenue from foundries integrating thermal drift prediction into process control. |
| Regional Calibration Infrastructure Expansion | Localizes service density in Taiwan's Hsinchu-Taichung corridor to match TSMC and UMC procurement requirements. |
| Short-Wave Infrared Product Line Extension | Addresses South Korean memory manufacturer demand for high-aspect-ratio etch profile monitoring. |
| India Market Entry Partnership | Positions for PLI scheme-driven greenfield fabrication demand without incumbent vendor displacement costs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with process integration engineers, metrology equipment procurement managers, fab operations directors, and thermal characterization specialists; and secondary validation against SEC equipment supplier filings, SEMI industry statistics, EPA regulatory dockets, and ISO accreditation body records. Bottom-up unit demand modeling across foundry capacity expansions triangulated with top-down equipment spending forecasts from semiconductor capital expenditure disclosures.
Across the analysis window, projections incorporate spectral range segmentation, measurement modality, node-specific thermal budget requirements, and regional regulatory compliance tiers. CAGRs derive from installed base replacement cycles, greenfield capacity additions, and technology substitution elasticities. Forecast inputs include foundry equipment utilization rates, REACH Annex XVII enforcement timelines, and AI integration adoption curves in predictive maintenance applications.
Forecasts assume regulatory continuity in EPA Clean Air Act, REACH substance restrictions, and ISO 17025 calibration standards; material policy shifts would require re-modeling chamber emissions verification requirements or detector material compliance pathways. Specific risks include indium supply constraints, East Asian logistics disruptions, and sub-micron thermal metrology expertise scarcity extending commissioning timelines. Recalibration cycles align with material shifts in node migration schedules, regulatory enforcement intensity, and foundry procurement unbundling trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Microsensor Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Torque Sensor Market