
 Global Refrigeration Compressor Market | 2026-2036
Global Refrigeration Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refrigeration Compressor Market Outlook
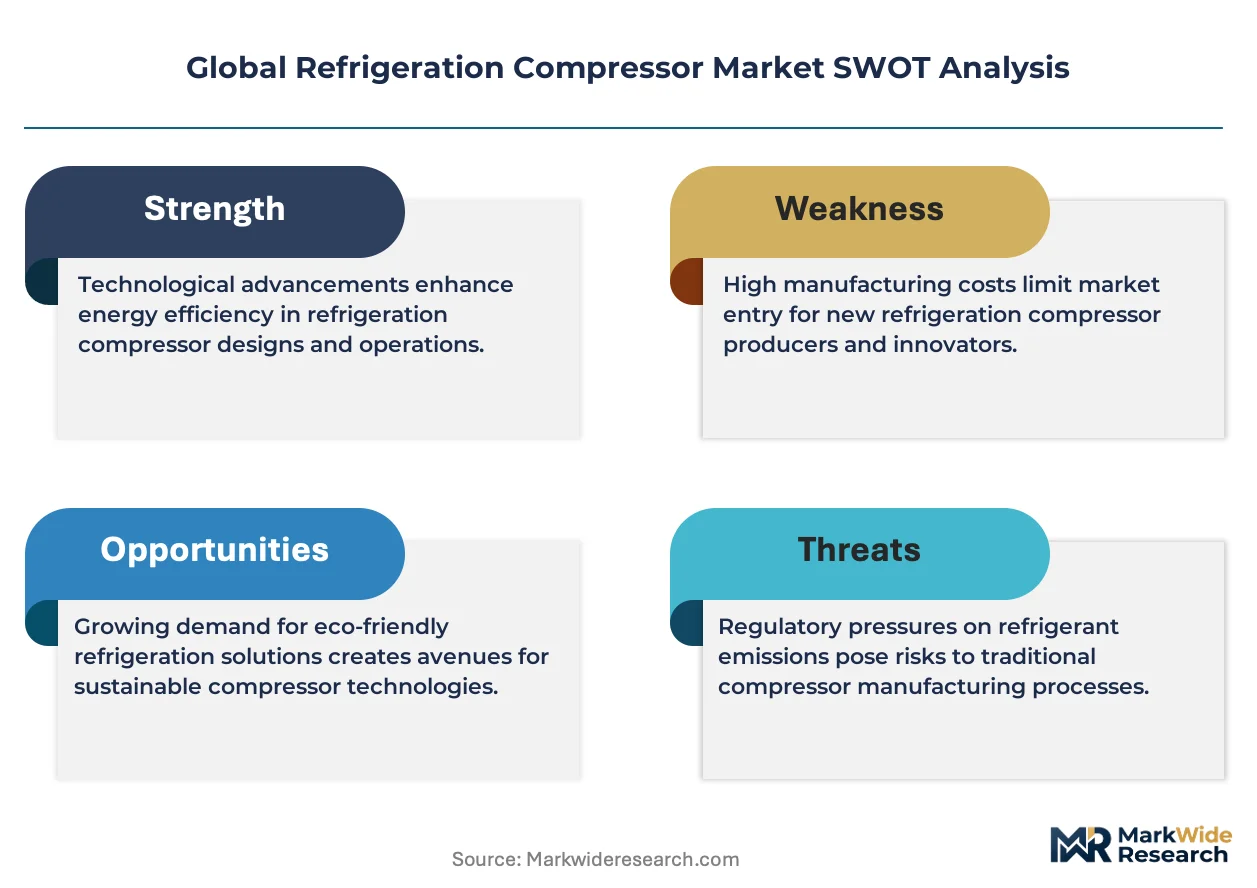
The capital-intensity divergence between scroll specialists and reciprocating incumbents is collapsing as variable-speed manufacturing scales commoditize core components. Copeland (Emerson) leverages its captive semiconductor sourcing to control inverter costs across the scroll segment. Bitzer sustains German engineering premiums in industrial screw compressors for ammonia systems. Danfoss anchors Nordic market share through deep integration with CO2 transcritical rack architectures.
A refrigeration compressor is a mechanical device that raises refrigerant vapor pressure to enable heat rejection through condensation, typically operating across suction pressures from 0.5 to 15 bar and discharge temperatures up to 160°C depending on refrigerant class. Scroll compressors dominate the commercial segment where part-load efficiency requirements from Ecodesign regulations in Europe favor continuous modulation over fixed-speed cycling. Variable speed drive technology is capturing margin pools as inverter penetration rises in transport refrigeration applications. Smart technology adoption remains concentrated among fleet operators seeking predictive maintenance capabilities for refrigerated trucks.
The EPA SNAP program in the United States restricts high-GWP refrigerant approvals, while the EU F-Gas Regulation mandates stepped HFC phase-down quotas through 2030. China's GB standards enforce energy efficiency minimums for compressors sold domestically. Stakeholders must monitor refrigerant transition timelines and efficiency tier migrations to align product portfolios with diverging regional compliance deadlines.
Market Dynamics
The Kigali Amendment's HFC phase-down timeline is compressing equipment replacement cycles as operators accelerate retrofits ahead of refrigerant availability cliffs. This regulatory forcing function is restructuring procurement priorities across cold chain infrastructure investments.
Growth Catalysts
- EU F-Gas Regulation phase-down quotas:Mandated refrigerant transitions are pulling forward compressor replacement demand in European commercial cold storage facilities ahead of 2030 compliance deadlines.
- China's domestic food processing capacity scaling:State-supported expansion of frozen food manufacturing clusters is concentrating demand for industrial screw and reciprocating compressor systems.
- Variable-speed drive technology maturation:Inverter cost curves are enabling part-load efficiency compliance in transport refrigeration units previously locked into fixed-speed architectures.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing bottlenecks from Chinese processing facilities are constraining permanent magnet motor production for high-efficiency scroll compressors.
- Ammonia system certification complexity:ASHRAE and IIAR safety code compliance timelines extend project development cycles for industrial refrigeration installations by 8-14 months.
- CO2 transcritical system first-cost premiums:High-pressure component requirements and specialized oil management systems impose capital barriers against conventional HFC retrofits in small-format retail.
Strategic Opportunities
- India's cold chain infrastructure deficit:Post-harvest loss reduction mandates under the National Cold Chain Grid are opening procurement windows for modular compressor rack systems in agricultural processing zones.
- Natural refrigerant convergence with predictive maintenance:IoT-enabled compressor monitoring is creating service revenue pools for CO2 system operators managing transcritical pressure fluctuations.
- US EPA SNAP approval pathways:Emerging low-GWP refrigerant listings are enabling product line extensions for compressor OEMs with pre-certified A2L-compatible architectures.
Industry Challenges
- Refrigerant transition skill scarcity:Technician certification gaps for flammable refrigerant handling are extending commissioning timelines and inflating field service costs.
- Legacy control system integration friction:Variable-speed compressor retrofits into existing building management systems require protocol bridging that complicates warranty coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refrigeration Compressor Market |
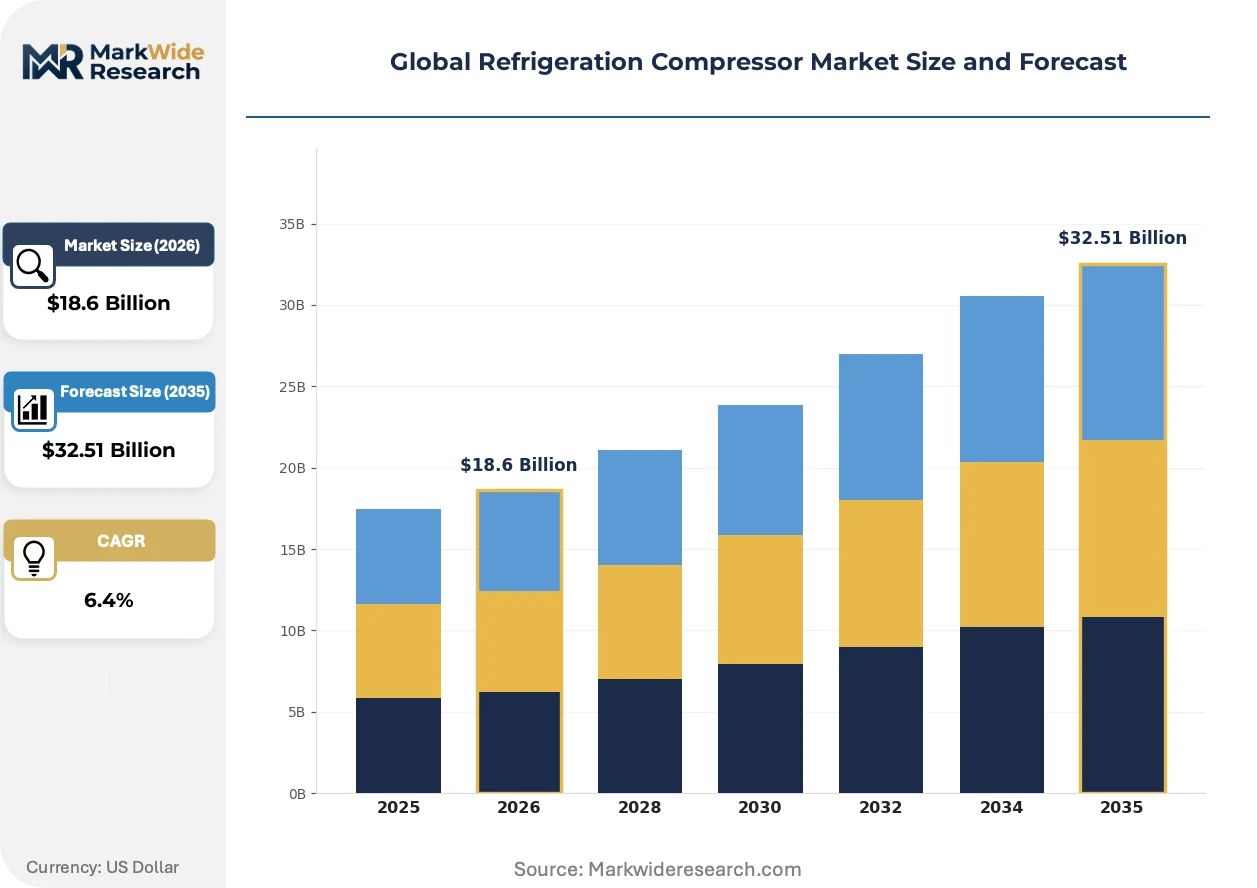
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $32.51 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scroll, Reciprocating, Centrifugal, Screw Technology: Variable Speed Drive, Fixed Speed, Smart Technology, Eco-friendly Refrigerants Application: Commercial Refrigeration, Industrial Refrigeration, Transport Refrigeration, Refrigerated Display End User: Food & Beverage, Pharmaceuticals, Chemical, HVAC |
| Companies Covered | Mitsubishi Electric Corporation, LG Electronics, Copeland (Emerson), Johnson Controls, Panasonic Corporation, Bitzer, Carrier Global Corporation, Nidec (Embraco), Danfoss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refrigeration Compressor Market Strategic Shifts
Digital compressor diagnostics and refrigerant chemistry advances are converging to redefine equipment lifecycle economics. The analysis window reveals three distinct vectors reshaping competitive positioning.
Permanent magnet synchronous motors paired with advanced inverter controls are displacing induction motor architectures in commercial scroll applications. Supermarket operators in Germany and the Netherlands are specifying these configurations for transcritical CO2 racks to capture Ecodesign bonus efficiency tiers. The technology is displacing conventional fixed-speed tandem arrangements that previously dominated mid-capacity commercial refrigeration.
REACH restrictions on PFAS-based lubricants are forcing reformulation of compressor oils compatible with next-generation hydrofluoroolefins. European OEMs are accelerating qualification programs for polyolester alternatives that maintain miscibility with lower-GWP refrigerant blends. Transport refrigeration manufacturers face the most compressed compliance timeline as trailer fleet operators seek cross-border operational flexibility.
Fleet operators are unbundling compressor maintenance from equipment procurement contracts. Large cold chain logistics providers in the United States are negotiating outcome-based service agreements that transfer uptime risk to OEM service divisions. This procurement model shift is most visible in refrigerated trucking where predictive analytics platforms enable condition-based overhaul scheduling.
Global Refrigeration Compressor Market Segmentation
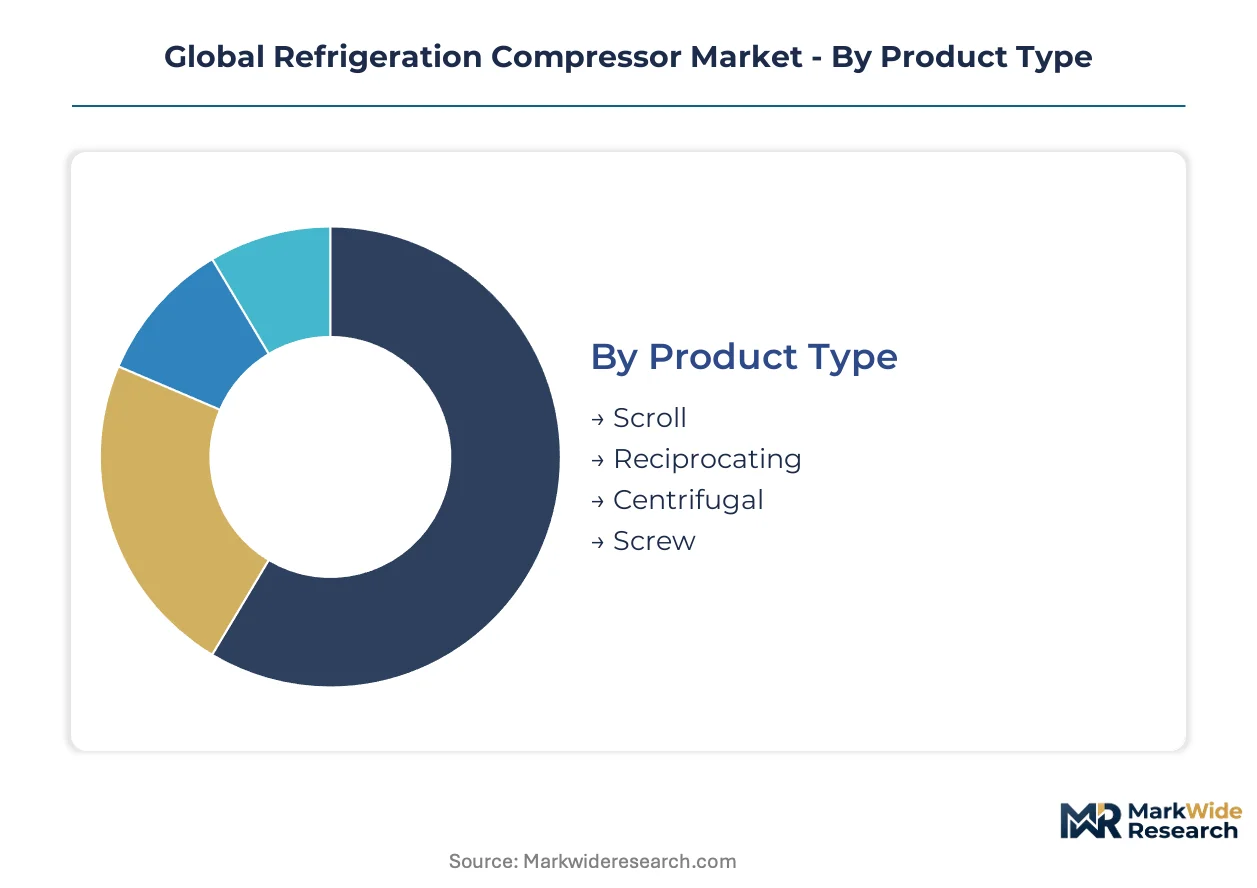
Compressor selection across the global refrigeration market follows distinct procurement pathways. Product type determines OEM channel relationships, while technology tiering separates retrofit demand from new-build specifications.
Product Type:
Scroll and screw compressors flow through specialized distribution networks serving commercial and industrial contractors, whereas reciprocating units reach end-users through broader HVAC wholesale channels.
- Scroll:Orbiting spiral plates compress refrigerant vapor with near-silent operation and superior part-load efficiency. Demand concentrates in European supermarket chains retrofitting transcritical CO2 systems ahead of EU F-Gas Regulation deadlines.
- Screw:Twin helical rotors handle large refrigerant volumes across industrial ammonia installations. Chinese frozen food processing clusters are scaling procurement of these systems as state-supported capacity expansion accelerates.
- Reciprocating:Piston-driven compression serves small-format commercial applications through established HVAC distribution networks.
- Centrifugal:High-speed impeller designs address district cooling and large-scale industrial refrigeration with multi-megawatt capacity requirements.
Scroll compressors dominate installed base. Screw systems are where expansion concentrates.
Technology:
Technology tiers separate capital expenditure profiles, with variable-speed configurations commanding price premiums that fixed-speed alternatives cannot match in efficiency-regulated markets.
- Variable Speed Drive:Inverter-controlled permanent magnet motors modulate capacity to match thermal load in real-time. Transport refrigeration fleets across Germany and the Netherlands are retrofitting these systems to capture Ecodesign bonus efficiency tiers.
- Smart Technology:IoT-enabled diagnostics and predictive maintenance algorithms compress overhaul intervals. Cold chain logistics operators in the United States are unbundling compressor procurement from uptime-guaranteed service contracts.
- Fixed Speed:Conventional on-off cycling architectures persist in price-sensitive small commercial installations.
- Eco-friendly Refrigerants:Compressor designs optimized for CO2, ammonia, and hydrofluoroolefin blends address Kigali Amendment compliance trajectories.
Fixed-speed units retain volume leadership. Variable-speed drive configurations are climbing the fastest.
Application:
Application segments align with distinct regulatory jurisdictions and replacement cycle timing, from European commercial cold storage retrofits to Asia-Pacific transport fleet expansion.
- Commercial Refrigeration:Supermarket rack systems and cold storage facilities require continuous-duty compressors with part-load optimization. EU F-Gas Regulation phase-down quotas are pulling forward replacement demand in German and Dutch retail chains.
- Transport Refrigeration:Trailer and truck-mounted units face severe weight and vibration constraints. Indian agricultural logistics operators are procuring modular compressor systems under National Cold Chain Grid mandates to reduce post-harvest losses.
- Industrial Refrigeration:Large-scale food processing and chemical plants specify heavy-duty screw and reciprocating configurations.
- Refrigerated Display:Self-contained cases in retail environments demand compact, low-noise scroll and reciprocating solutions.
Commercial refrigeration commands the largest installed base. Transport refrigeration is gaining share fastest.
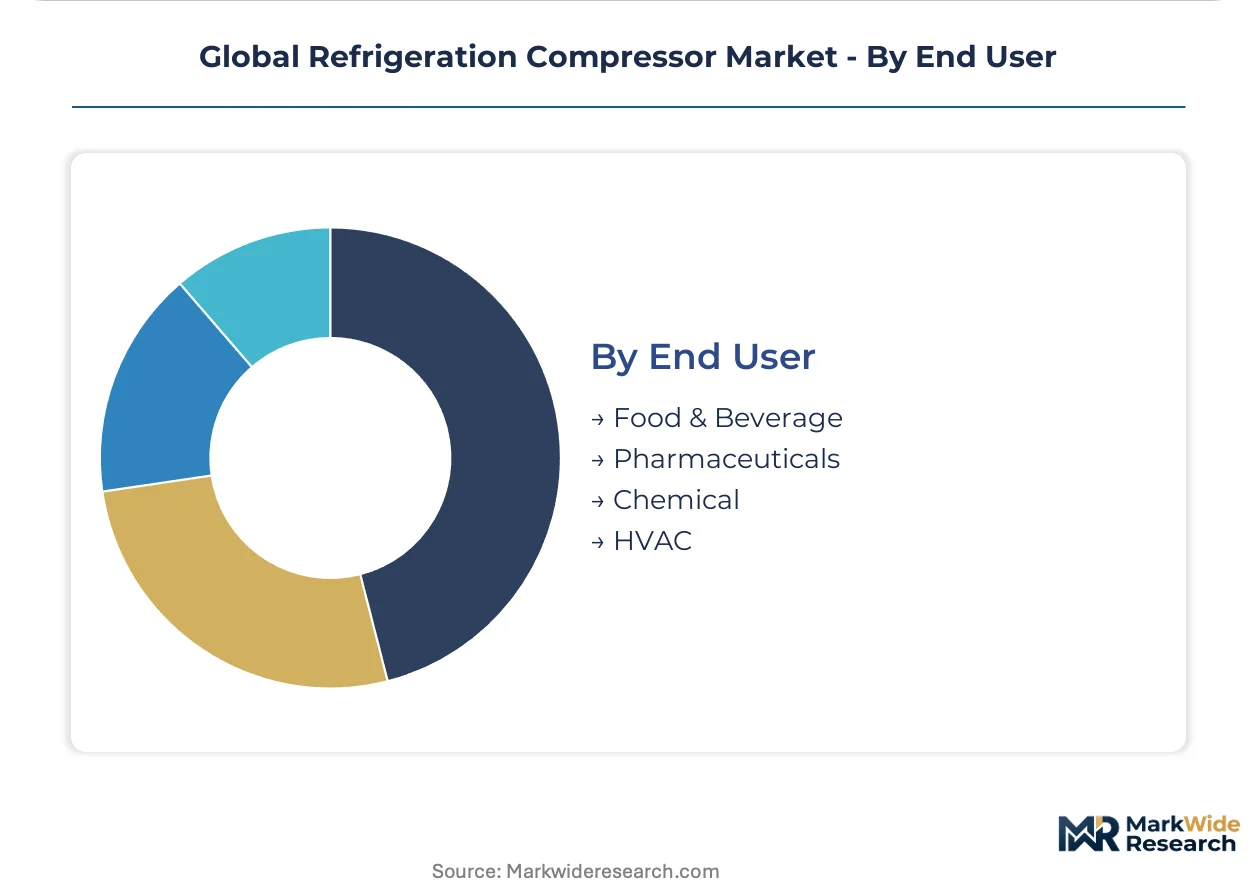
End User:
End-user concentration varies by regulatory exposure, with food and beverage processors facing the most compressed refrigerant transition timelines.
- Food & Beverage:Frozen food manufacturers and cold storage operators require 24/7 reliability with minimal temperature excursion. China's state-supported processing cluster expansion is concentrating demand for industrial screw compressor systems.
- Pharmaceuticals:Vaccine and biologics cold chains demand validated temperature documentation and redundant compressor configurations.
- Chemical:Petrochemical and specialty chemical processors specify corrosion-resistant materials for aggressive refrigerant chemistries.
- HVAC:Building climate control applications favor standardized scroll and reciprocating units through established mechanical contractor networks.
Food and beverage dominates procurement volume. Pharmaceuticals represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys industrial screw compressors for state-backed frozen food clusters, while Germany retrofits supermarket CO2 racks under EU F-Gas deadlines. India procures modular transport units for agricultural cold chains, and the United States shifts fleet maintenance to outcome-based contracts.
China
Domestic food processing capacity expansion concentrates demand for heavy-duty screw and reciprocating systems. GB standards enforce energy efficiency minimums for compressors sold domestically. Shandong and Jiangsu provinces host frozen food manufacturing clusters scaling industrial refrigeration procurement.
Germany
Supermarket operators retrofit transcritical CO2 rack systems to capture Ecodesign bonus efficiency tiers. EU F-Gas Regulation phase-down quotas pull forward compressor replacement demand ahead of 2030 deadlines. The Rhine-Ruhr industrial corridor sustains engineering premiums for ammonia-compatible screw compressors.
United States
Cold chain logistics providers unbundle compressor procurement from uptime-guaranteed service contracts. EPA SNAP program restrictions on high-GWP refrigerant approvals reshape equipment replacement cycles. California and Texas lead refrigerated trucking fleet retrofits with predictive maintenance platform adoption.
India
Agricultural logistics operators procure modular compressor rack systems under National Cold Chain Grid mandates to reduce post-harvest losses. FSSAI cold chain regulations tighten temperature compliance requirements for perishable distribution. Maharashtra and Gujarat processing zones concentrate transport refrigeration deployment.
Netherlands
Retail chains specify variable-speed scroll configurations for transcritical CO2 installations to meet stepped HFC phase-down quotas. REACH restrictions on PFAS-based lubricants force compressor oil reformulation for hydrofluoroolefin compatibility. The Rotterdam port cluster anchors cold storage retrofit activity for re-export logistics.
Global Refrigeration Compressor Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the global refrigeration compressor market. Japanese and Korean electronics conglomerates leverage captive semiconductor sourcing to control inverter cost curves across scroll segments. European engineering houses sustain premiums in industrial screw configurations for ammonia systems. Competitive moves concentrate on backward integration into permanent magnet motor supply and predictive maintenance platform development.
Among diversified industrial conglomerates, Mitsubishi Electric Corporation and LG Electronics represent the integrated electronics archetype with semiconductor-adjacent capabilities. German engineering specialists exemplify the premium industrial tier. Danish and American diversified industrials anchor the CO2 transcritical and transport refrigeration vectors respectively.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| LG Electronics |
| Copeland (Emerson) |
| Johnson Controls |
| Panasonic Corporation |
| Bitzer |
| Carrier Global Corporation |
| Nidec (Embraco) |
| Danfoss |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation phase-down quotas gate compressor qualification and simultaneously stratify price tiers across European commercial retrofits. Buyers face stepped compliance deadlines that compress procurement timelines while suppliers leverage certification scarcity to sustain margin premiums on CO2-compatible architectures.
Pricing Analysis
Long-term offtake agreements dominate industrial screw compressor procurement for Chinese frozen food clusters, while spot purchasing persists in small-format commercial retrofits. Three-tier pricing structure across premium, standard, and economy levels reflects efficiency certification tier, with Ecodesign bonus-rated units commanding substantial premiums over baseline fixed-speed alternatives. Cost compression in standard-tier scroll compressors is intensifying because inverter cost curves are democratizing variable-speed access. Fleet operators exhibit lowest price sensitivity due to outcome-based contracting that transfers uptime risk to OEM service divisions.
Supply Chain Analysis
China dominates rare earth magnet processing for permanent magnet motors, while Germany and Japan anchor precision screw compressor manufacturing. Neodymium and dysprosium sourcing, copper winding supply, and specialized steel forgings for high-pressure CO2 components constitute critical input dependencies. Single-source vulnerability concentrates in Chinese rare earth processing facilities subject to export licensing volatility. Distribution runs through specialized HVAC wholesale channels for commercial scroll units and direct OEM-contractor relationships for industrial ammonia systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain logistics consolidation is shifting procurement leverage toward fleet operators capable of demanding uptime-guaranteed service contracts. This buyer concentration fragments pricing power among compressor OEMs competing for multi-year fleet agreements.
For Market Incumbents: Secure captive semiconductor sourcing pathways to control inverter cost curves against Japanese and Korean electronics conglomerates. Defend scroll segment margins through backward integration into permanent magnet motor supply chains. Capacity addition in India addresses National Cold Chain Grid procurement windows before regional specialists establish local assembly presence. For New Entrants and Emerging Players: Differentiate on IoT-enabled predictive maintenance platforms targeting US refrigerated trucking fleets unbundling service from equipment procurement. India's agricultural processing zones represent the most penetrable geography given infrastructure deficit mandates and limited incumbent service networks. Joint venture structures with established cold chain operators accelerate fleet validation and referenceability. For Investors and Strategic Acquirers: The Kigali Amendment's 2030 refrigerant availability cliffs reshape the acquisition landscape toward OEMs with pre-certified natural refrigerant architectures. Five-to-ten year viability hinges on compliance-ready product portfolios rather than legacy HFC-dependent revenue streams. Acquisition target archetype: mid-cap specialists with transcritical CO2 system qualification and installed base service contracts. Monitor EPA SNAP approval velocity for A2L refrigerant listings as inflection indicator for US market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures permanent motor sourcing against Chinese export licensing volatility for scroll compressor production. |
| Predictive Maintenance Platform Development | Enables outcome-based contracting with US cold chain logistics providers seeking uptime guarantees. |
| CO2 Transcritical System Certification Investment | Positions for EU F-Gas Regulation retrofit demand in German and Dutch supermarket chains. |
| India Local Assembly Capacity | Captures National Cold Chain Grid procurement under post-harvest loss reduction mandates. |
| A2L Refrigerant-Compatible Architecture Pre-Certification | Accelerates EPA SNAP pathway access for US market product line extensions. |
Study Parameters
Operator-level perspectives from cold chain fleet managers, supermarket engineering directors, industrial refrigeration contractors, and compressor OEM product strategists anchored the qualitative base. Primary fieldwork combined with secondary validation from EPA SNAP filings, EU F-Gas Regulation implementation reports, Chinese GB standard documentation, and customs trade data for compressor component flows. Bottom-up installed base modeling and top-down macroeconomic triangulation cross-verified volume and value estimates.
Sensitivity analysis tested forecast robustness across refrigerant transition timeline scenarios and rare earth supply disruption assumptions. Segmentation dimensions spanned product type, technology tier, application vertical, and regional regulatory cluster throughout the forecast period. CAGRs derived from equipment replacement cycle modeling, cold chain infrastructure investment trajectories, and efficiency regulation compliance deadlines. Industry-specific inputs included HFC phase-down quota schedules and frozen food processing capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside synchronized global refrigerant transition timelines or sustained rare earth supply concentration would require recalibration. Forecasts reflect documented assumptions regarding technician certification scalability and fleet operator procurement model durability. Recalibration cycles align with material shifts in Kigali Amendment implementation pace and EPA SNAP approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
TIG Torch Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Electric Actuator Market
Industrial Equipment
Europe Fans and Blowers Market