
 Global Linear Bearings Market | 2026-2036
Global Linear Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Linear Bearings Market Outlook
The skilled precision-machinist labor pool is collapsing across industrialized manufacturing bases, forcing bearing suppliers to automate grinding and raceway finishing lines. THK Co., Ltd. leverages captive ceramic-ball processing to sustain margin structure amid wage inflation. SKF competes through predictive-maintenance-integrated linear systems that anchor long-term service contracts. Bosch Rexroth AG differentiates via mechatronic module bundling, positioning linear guides as subsystems rather than commodity components.
Linear bearings are mechanical elements that constrain motion to a single degree of freedom along a shaft or rail, typically manufactured from hardened bearing steel with surface hardness exceeding 58 HRC and dimensional tolerances within ISO tolerance grades IT3-IT5 for precision classes. These components translate rotary motor output into controlled linear displacement for positioning tables, pick-and-place mechanisms, and CNC axes. Ball bearing technology dominates installed base volume due to established recirculation architectures and repairability, while crossed roller bearing configurations capture premium positioning in semiconductor lithography stages where moment-load rigidity commands price multiples. Plain bearing and dry liner segments occupy replacement-intensive niches in contaminated environments where sealed recirculating systems fail prematurely.
FDA equipment validation requirements for diagnostic instrument positioning stages shape US demand for traceable calibration protocols and ISO 3408 test documentation. EMA machinery directives and REACH substance restrictions on lubricant chemistry compel European suppliers to certify halogen-free greases and cobalt-free raceway coatings. China's GB standards and SAMR equipment-safety filings add parallel compliance layers for imported precision rail assemblies. Stakeholders must monitor how divergent lubricant chemistry regulations fragment global product platforms and force regional SKU proliferation.
Market Dynamics
The precision-machinist labor collapse across industrialized manufacturing bases is forcing bearing suppliers to automate grinding and raceway finishing lines, compressing production economics and reshaping competitive positioning between captive-process specialists and mechatronic bundlers.
Growth Catalysts
- EU chip subsidies:Semiconductor equipment builders in Germany's automation corridor are scaling orders for precision motion components as performance thresholds tighten under EU chip subsidies.
- Crossed roller bearing configurations:These capture premium positioning in semiconductor lithography stages where moment-load rigidity commands price multiples over ball bearing alternatives.
- China's NMPA equipment certification:Tighter certification standards for medical equipment are filtering demand toward traceable, ISO 3408-documented linear rail assemblies.
Market Restraints
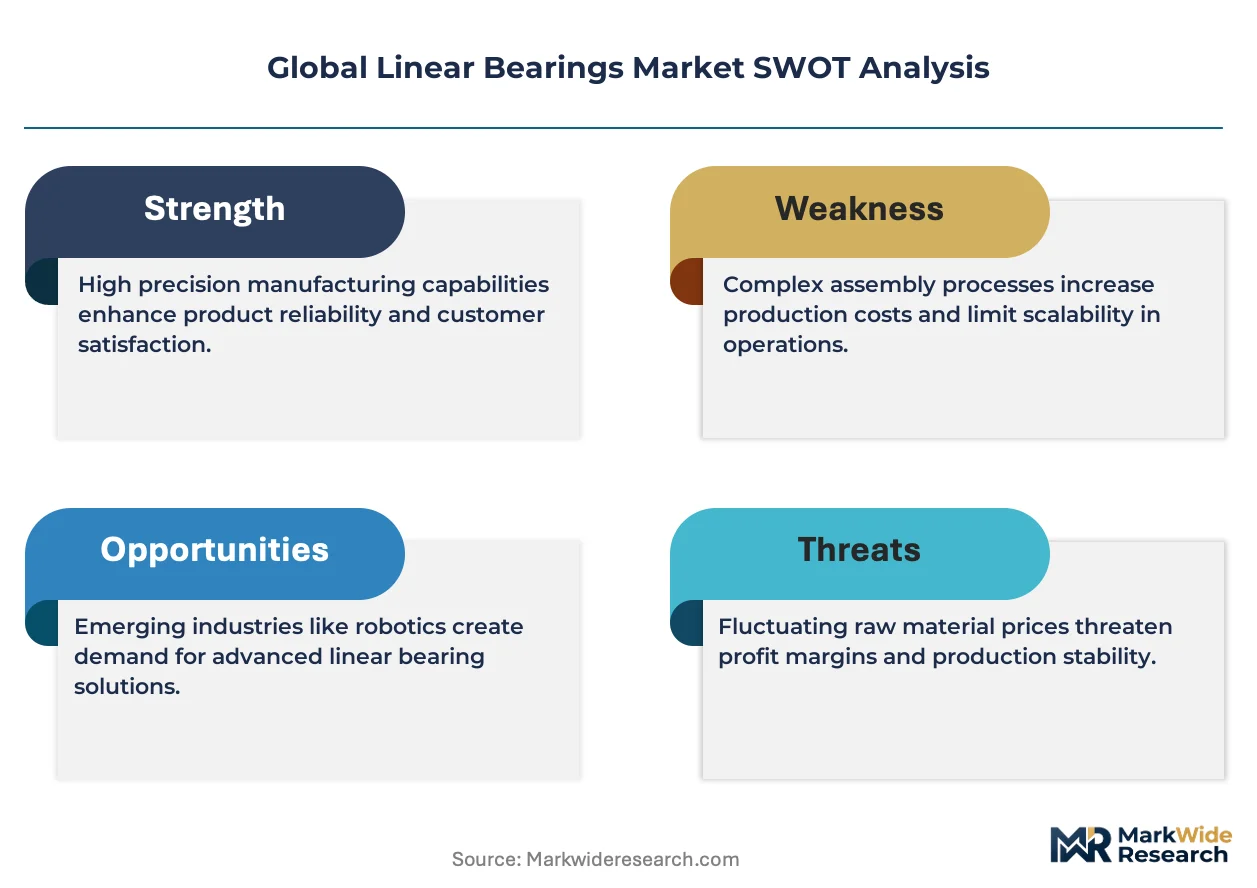
- Hardened bearing steel input costs:Surface hardness requirements exceeding 58 HRC tie margin stability to volatile alloy steel pricing and energy-intensive heat treatment economics.
- REACH substance restrictions:European lubricant chemistry regulations compel halogen-free grease certification and cobalt-free raceway coating validation, fragmenting global product platforms.
- Sealed recirculating system failure rates:Contaminated environments in heavy manufacturing prematurely degrade ball recirculation architectures, limiting addressable market in replacement-intensive niches.
Strategic Opportunities
- India's PLI scheme for automation:Production-linked incentives for advanced manufacturing equipment create import substitution demand for precision linear motion subsystems.
- Predictive-maintenance integration:Sensor-embedded linear guides enable long-term service contracts that anchor customer relationships beyond component sales.
- Mechatronic module bundling:Positioning linear guides as integrated subsystems rather than commodity components opens value capture in robotics and medical diagnostics.
Industry Challenges
- ISO 3408 test documentation:FDA equipment validation requirements for diagnostic instrument positioning stages demand traceable calibration protocols that extend certification timelines.
- GB standards compliance:China's SAMR equipment-safety filings add parallel documentation layers for imported precision rail assemblies, complicating market entry workflows.
- Ceramic-ball processing scale-up:Captive supply of ceramic balls requires capital-intensive furnace capacity and quality control infrastructure that mid-scale suppliers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Linear Bearings Market |
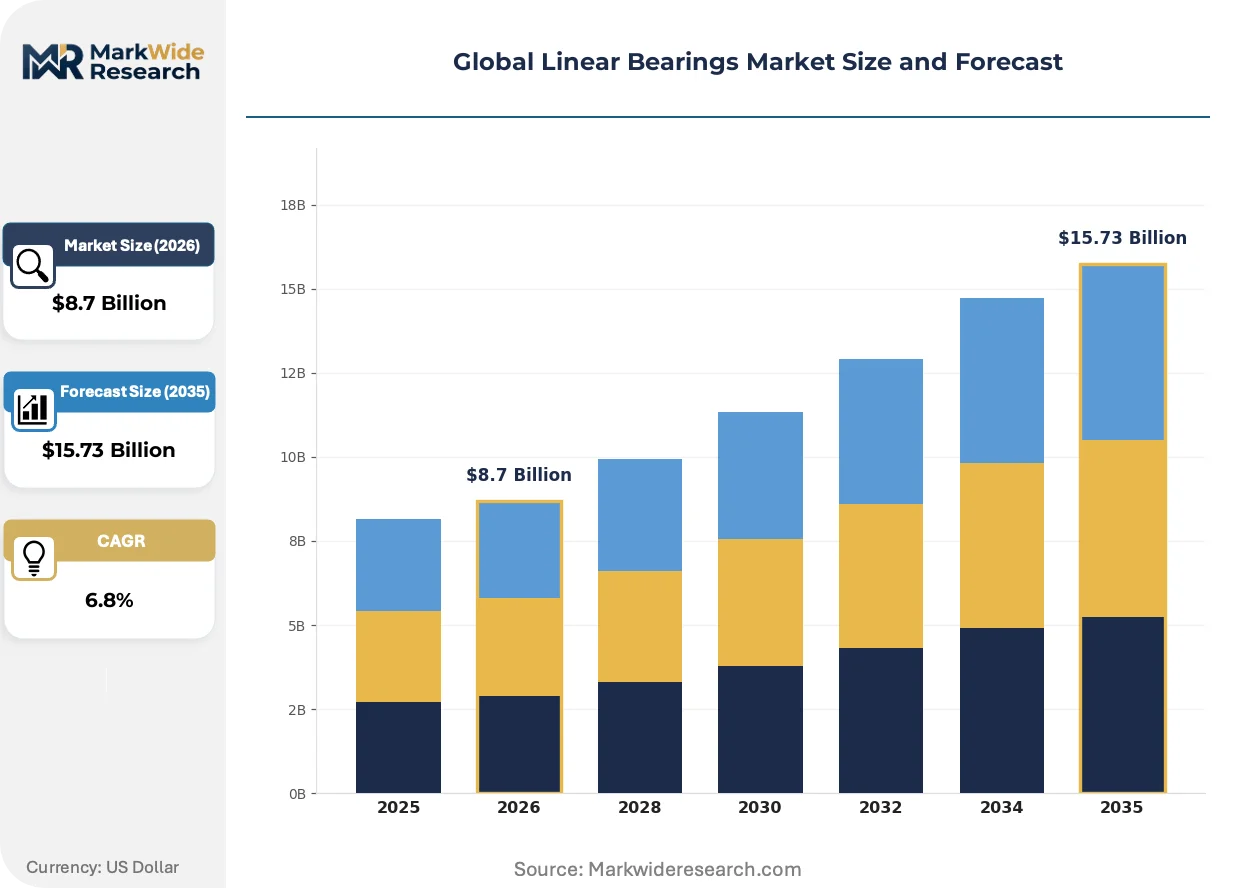
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearing, Plain Bearing, Roller Bearing, Crossed Roller Bearing Technology: Recirculating Ball, Bushed, Profile Rail, Dry Liners Application: Machine Tools, Robotics Equipment, Semiconductor Manufacturing, Packaging Machinery End User Industry: Aerospace Firms, Electronics Producers, Heavy Equipment Manufacturers, Precision Instrument Makers |
| Companies Covered | NTN Corporation, Hiwin Corporation, SKF, Bosch Rexroth AG, Schaeffler Group, THK Co., Ltd., Thomson Industries Inc., PBC Linear, NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Linear Bearings Market Strategic Shifts
Precision motion technology is bifurcating between commoditized ball recirculation architectures and premium crossed-roller configurations, with regulatory chemistry mandates and procurement model evolution accelerating the split.
Ceramic ball technology is bifurcating the installed base as semiconductor lithography stages and medical imaging gantries adopt silicon nitride balls for thermal stability and corrosion resistance. Equipment builders in Germany and Japan are specifying ceramic-ball linear guides for sub-micron positioning repeatability. This material shift is compressing the viable market for standard steel-ball precision classes while expanding service-contract attach rates for ceramic-component suppliers.
REACH substance restrictions on lubricant chemistry are forcing reformulation of bearing greases across European supply chains. Halogen-free and cobalt-free alternatives now require separate validation testing under ECHA guidance, extending product development cycles. Medical device manufacturers exporting to Europe are responding by dual-sourcing lubricant-qualified rail assemblies from certified suppliers.
Buying patterns among automation integrators are compressing switching cycles as mechatronic module bundling displaces component-level sourcing. System houses in China's Yangtze River Delta now specify linear-motion subsystems with pre-integrated motor mounts and sensor channels, bypassing traditional distributor channels. This consolidation is most visible in battery production equipment procurement, where turnkey subsystem accountability reduces commissioning risk.
Global Linear Bearings Market Segmentation
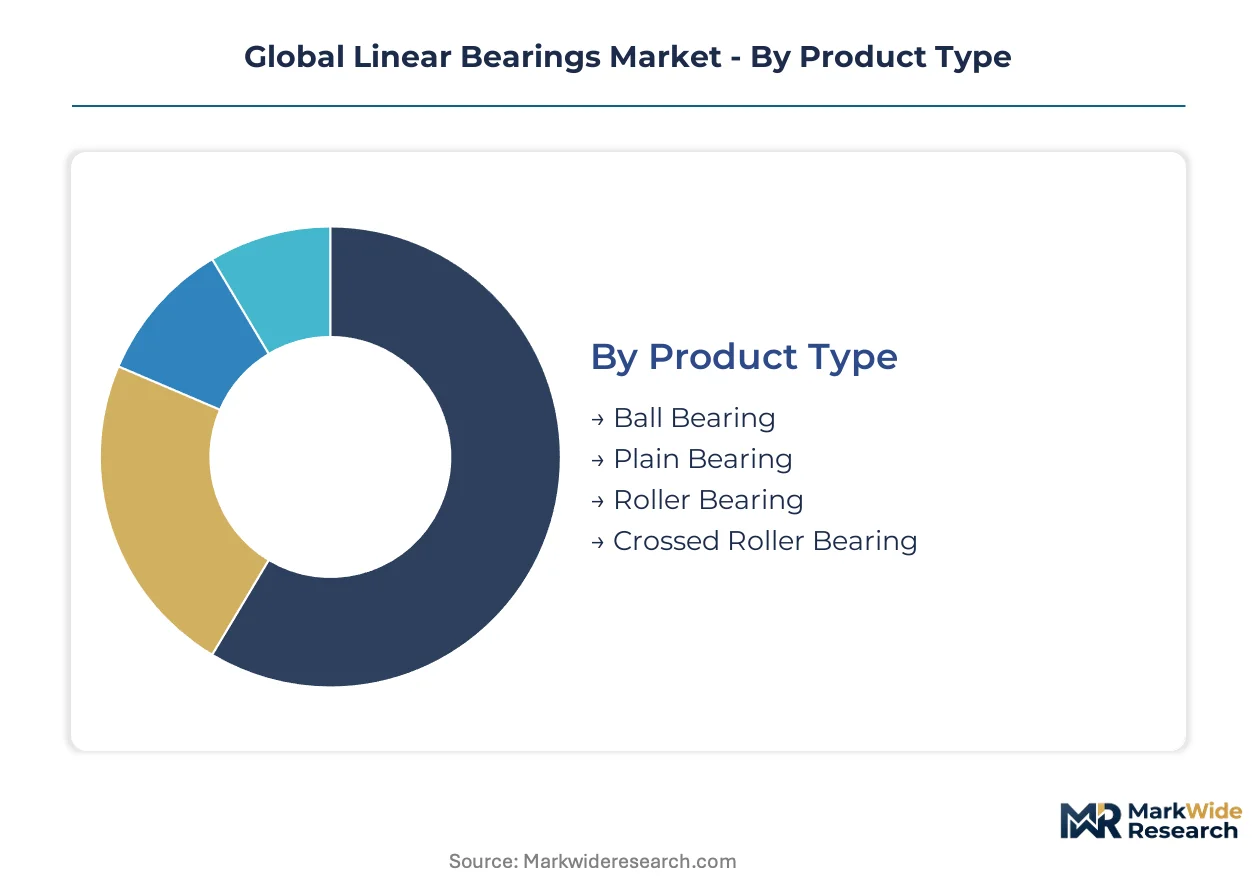
Linear bearing segmentation maps directly to performance certification tiers and regulatory documentation burdens. Procurement specifications in semiconductor lithography and FDA-validated medical equipment diverge sharply from heavy manufacturing replacement cycles.
Product Type:
REACH substance restrictions and FDA validation protocols split product platforms by material traceability requirements.
- Ball Bearing:Recirculating steel-ball architectures dominate installed base volume due to established repairability and ISO 3408 test documentation availability. Demand concentrates in Germany's automation corridor where Bosch Rexroth and Schaeffler anchor regional supply chains for CNC axes and pick-and-place mechanisms. EU chip subsidies are scaling orders as performance thresholds tighten.
- Crossed Roller Bearing:Moment-load rigidity commands price multiples in semiconductor lithography stages requiring sub-micron positioning repeatability. Equipment builders in Japan and Germany specify these for thermal stability under silicon nitride ball configurations.
- Plain Bearing:Dry-running polymer liners occupy replacement-intensive niches in contaminated environments where sealed recirculating systems fail prematurely.
- Roller Bearing:Cylindrical roller configurations handle heavy radial loads in machine tool linear guides with less precision than crossed-roller alternatives.
Ball bearing handles the majority of throughput; crossed roller bearing is expanding most quickly on share.
Technology:
Cost tier separation follows automation integration depth and captive process investment.
- Recirculating Ball:Dominant architecture with hardened bearing steel raceways exceeding 58 HRC surface hardness and dimensional tolerances within ISO tolerance grades IT3-IT5. THK Co., Ltd. leverages captive ceramic-ball processing to sustain margin structure amid wage inflation.
- Profile Rail:Integrated motor mounts and sensor channels enable mechatronic module bundling that system houses in China's Yangtze River Delta now specify for battery production equipment.
- Bushed:Sintered bronze or polymer-lined sleeves serve low-speed, high-contamination applications with minimal maintenance access.
- Dry Liners:Self-lubricating polymer composites eliminate grease compliance burdens under REACH and ECHA halogen-free mandates.
Recirculating ball captures the volume base; profile rail is gaining share fastest through subsystem bundling.
Application:
Customer procurement models compress switching cycles differently across equipment types.
- Semiconductor Manufacturing:EUV lithography stages and wafer handling robotics demand crossed-roller precision with traceable calibration protocols. China's NMPA equipment certification and EU chip subsidies are filtering demand toward ISO 3408-documented assemblies.
- Robotics Equipment:Collaborative robot joints and Cartesian gantries specify linear-motion subsystems with pre-integrated sensor channels, bypassing traditional distributor channels in the Yangtze River Delta.
- Machine Tools:CNC axes and positioning tables translate rotary motor output into controlled linear displacement using ball bearing technology.
- Packaging Machinery:High-cycle pick-and-place mechanisms prioritize repairability and steel-ball recirculation over ceramic premium tiers.
Semiconductor manufacturing commands the premium tier; robotics equipment is climbing the fastest on subsystem integration.
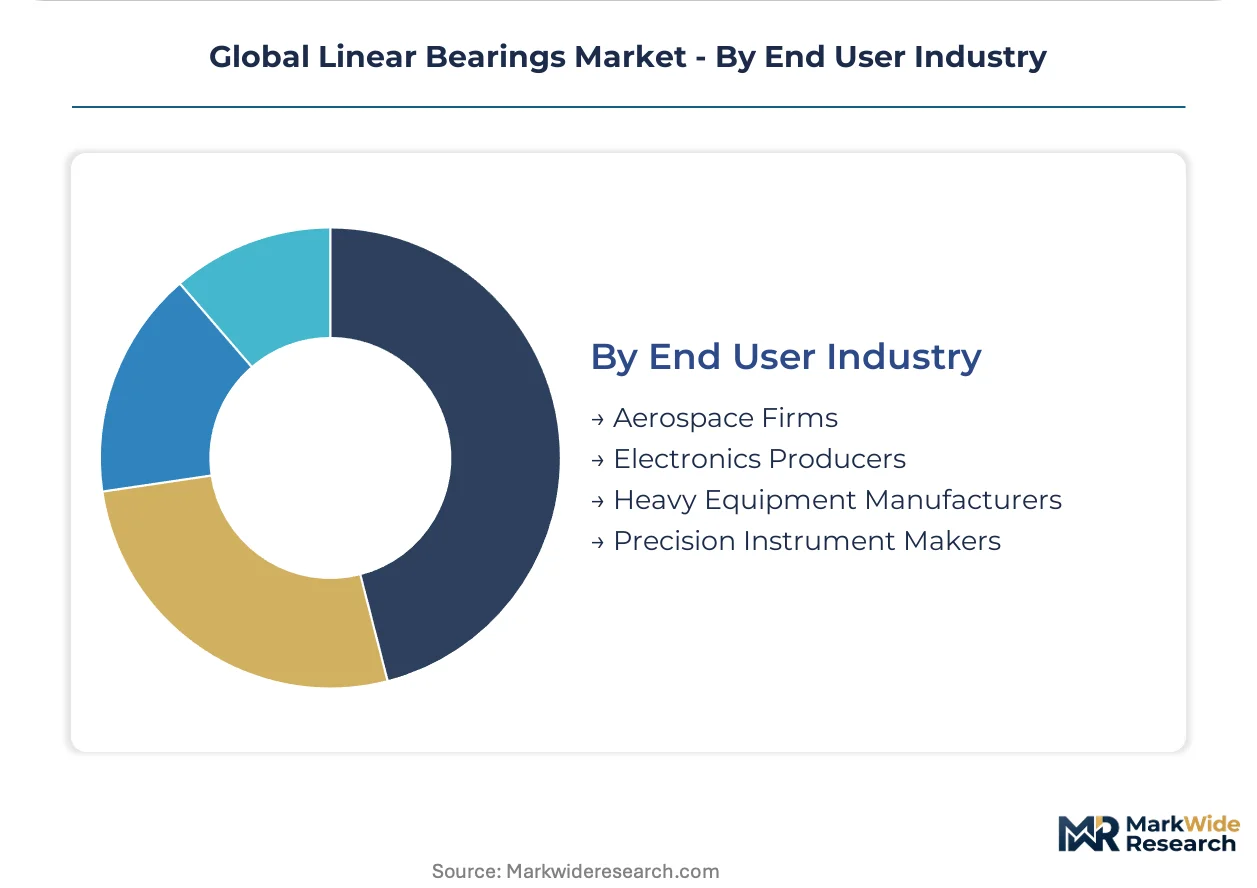
End User Industry:
Margin structure varies with validation documentation depth and service-contract attach rates.
- Electronics Producers:Semiconductor equipment builders scale orders for precision motion components as performance thresholds tighten under multiple regulatory regimes.
- Precision Instrument Makers:FDA equipment validation requirements for diagnostic instrument positioning stages shape US demand for traceable calibration protocols.
- Aerospace Firms:Flight control surface actuation and landing gear systems specify corrosion-resistant configurations with extended service intervals.
- Heavy Equipment Manufacturers:Contaminated environments in mining and construction prematurely degrade sealed recirculating systems, limiting addressable market.
Electronics producers drive the volume premium; precision instrument makers are the steepest expansion trajectory on regulatory compliance attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA machinery directives and REACH substance restrictions compel European suppliers to certify halogen-free greases and cobalt-free raceway coatings, while China's GB standards and SAMR equipment-safety filings add parallel compliance layers for imported precision rail assemblies.
Germany
Semiconductor equipment builders in Germany's automation corridor scale orders for precision motion components as EU chip subsidies tighten performance thresholds. EMA machinery directives mandate traceable calibration protocols for diagnostic instrument positioning stages. Bosch Rexroth and Schaeffler anchor regional supply chains in Stuttgart and Schweinfurt for CNC axes and pick-and-place mechanisms.
China
System houses in China's Yangtze River Delta specify linear-motion subsystems with pre-integrated motor mounts and sensor channels for battery production equipment. NMPA equipment certification filters demand toward traceable, ISO 3408-documented linear rail assemblies. Shanghai and Suzhou clusters concentrate procurement for robotics and medical diagnostics manufacturing.
United States
FDA equipment validation requirements shape demand for diagnostic instrument positioning stages with traceable calibration protocols. EPA and OSHA regulations intersect with medical device manufacturing standards in precision motion applications. Boston and San Francisco Bay Area clusters drive procurement for semiconductor lithography and life sciences equipment.
Japan
Equipment builders specify crossed-roller configurations with silicon nitride balls for sub-micron positioning repeatability in semiconductor lithography stages. METI industrial policy supports captive ceramic-ball processing infrastructure for thermal stability applications. Nagoya and Osaka manufacturing belts concentrate precision motion component production for export markets.
India
Production-linked incentives for advanced manufacturing equipment create import substitution demand for precision linear motion subsystems. BIS standards alignment and CDSCO medical device regulations shape certification requirements for diagnostic equipment positioning stages. Gujarat and Maharashtra industrial corridors attract subsystem integrators for automation and robotics manufacturing.
Global Linear Bearings Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the linear bearings market. The upper tier commands premium positioning through captive ceramic-ball processing and mechatronic module bundling, while mid-scale competitors struggle to fund capital-intensive furnace capacity. Three archetypes dominate: integrated motion subsystems providers, captive-process specialists with backward control over ceramic supply, and regional fabricators serving replacement-intensive niches. Competitive moves concentrate on predictive-maintenance integration for service-contract anchoring and profile rail subsystem bundling to bypass traditional distribution.
Within the integrated subsystem tier, Bosch Rexroth AG and THK Co., Ltd. exemplify divergent strategic positioning. Bosch Rexroth represents the German mechatronic bundling archetype, while THK occupies the Japanese captive-process specialist position with in-house ceramic-ball production. SKF anchors the predictive-maintenance-integrated systems approach that enables long-term service contracts beyond component sales.
| Leading Market Players |
|---|
| NTN Corporation |
| Hiwin Corporation |
| SKF |
| Bosch Rexroth AG |
| Schaeffler Group |
| THK Co., Ltd. |
| Thomson Industries Inc. |
| PBC Linear |
| NSK Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German automation OEMs and Japanese ceramic-ball suppliers lock in both supply access and price visibility for precision linear motion components, insulating tier-one buyers from alloy steel volatility while compressing margins for spot-market participants.
Pricing Analysis
Geographic price spreads of 15-25% separate German-engineered crossed-roller assemblies from Chinese profile-rail alternatives, with three-tier pricing structure across precision, standard, and economy levels anchored by ISO 3408 certification grade and ceramic-ball material specification. Price differentiation hinges on REACH-compliant lubricant chemistry and captive heat-treatment capacity, with cost compression in standard ball-bearing tiers intensifying due to wage inflation in precision-machining labor pools. Automotive battery equipment builders in China's Yangtze River Delta exhibit highest price sensitivity, while EU semiconductor lithography OEMs prioritize moment-load rigidity over unit cost.
Supply Chain Analysis
Strategic stockpiling of hardened bearing steel billets and silicon nitride powder dominates inventory strategy among tier-one suppliers, buffering against alloy price volatility and ceramic-ball furnace capacity constraints. Manufacturing concentrates in Germany, Japan, and China, with supply chains drawing from Swedish specialty steel mills, Japanese ceramic powder producers, and Chinese rare-earth processing for magnetic encoder integration. Single-source vulnerability in ceramic-ball furnace capacity poses structural risk, while distribution runs through OEM direct channels and specialized automation integrators bypassing traditional industrial distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory certification entrenchment and embedded switching costs in precision equipment designs protect incumbent positions against commodity competition.
For Market Incumbents: Secure captive ceramic-ball processing capacity through furnace infrastructure investment or long-term supply agreements with Japanese powder metallurgy specialists, defending against margin erosion from emerging Chinese profile-rail bundlers. Deepen backward integration into heat-treatment and raceway finishing automation to offset collapsing precision-machinist labor availability in Germany and Japan. Prioritize predictive-maintenance sensor integration to anchor long-term service contracts beyond component sales. For New Entrants and Emerging Players: Differentiate on dry-liner polymer formulations that eliminate REACH lubricant compliance burdens for replacement-intensive heavy manufacturing niches in India and Southeast Asia. Target India's PLI-scheme automation corridor with localized profile-rail subsystem assembly, bypassing established German-Japanese supply chains. Pursue hospital-system partnerships for FDA-validated diagnostic instrument positioning stages where traceable calibration protocols create procurement friction for commodity suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive-maintenance-integrated linear system providers with embedded sensor channels and long-term service contracts. Five-to-ten-year viability favors suppliers with demonstrated ceramic-ball processing scale and ISO 3408 documentation depth rather than pure-play fabricators. Watch for inflection when EU chip subsidy disbursement accelerates German semiconductor equipment procurement beyond current order backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Ball Furnace Capacity Expansion | Captive silicon nitride processing secures margin structure against wage inflation and supply scarcity. |
| Mechatronic Module Bundling | Pre-integrated motor mounts and sensor channels displace component-level sourcing in China's battery equipment procurement. |
| REACH-Compliant Lubricant Reformulation | Halogen-free grease certification opens European medical device and semiconductor equipment markets. |
| Predictive-Maintenance Sensor Integration | Embedded condition monitoring anchors long-term service contracts beyond transactional component sales. |
| India PLI Localization Partnership | Production-linked incentives for automation equipment create import substitution demand for precision motion subsystems. |
Study Parameters
The analysis maps ball bearing, crossed roller, plain bearing, and roller bearing sub-sectors, each validated through interviews with OEM procurement managers, automation integrators, precision-machining plant engineers, and aftermarket service heads. Primary fieldwork combined with secondary validation against SEC filings of listed motion-component suppliers, Japanese METI industrial production statistics, German VDMA order intake data, and Chinese customs trade records. Bottom-up demand modeling from equipment installation bases triangulated against top-down supply-side capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions spanning product architecture, precision grade, application equipment type, and regional regulatory cluster. CAGRs derived from equipment capital expenditure trajectories and replacement-cycle analysis, incorporating semiconductor capital intensity ratios, medical device FDA submission pipelines, and battery production equipment deployment schedules as industry-specific forecast inputs.
Material uncertainties — alloy steel price volatility, ceramic-ball furnace capacity constraints, and divergent lubricant chemistry regulations — sit outside the modeled envelope. Forecasts reflect assumptions about sustained EU chip subsidy execution and NMPA certification pathway stability. Revision becomes warranted when semiconductor capital expenditure crosses thresholds that alter precision motion component procurement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
CO2 Laser Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Laser Cleaning Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Electric Actuator Market