
 Pigmented Paper Market | 2026-2036
Pigmented Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Pigmented Paper Market Intelligence
Pigment chemist shortages across European paper mills are redrawing competitive boundaries for high-opacity formulations. Omya AG leverages its vertical integration into calcium carbonate reserves to sustain margin stability against raw material volatility. Imerys anchors its position through specialized kaolin processing capabilities that dominate brightness-critical segments. Kemira Oyj differentiates via polymer expertise that controls retention efficiency in alkaline papermaking environments.
Pigmented paper denotes substrate engineered with mineral fillers and colorants dispersed throughout the fiber matrix, typically achieving ISO brightness levels above 85% and grammages ranging from 60 to 400 gsm depending on end-use performance requirements. Specialty Paper commands premium positioning in archival and security applications where fade resistance and dimensional stability justify elevated pricing. Uncoated Paper occupies volume leadership in business communication channels, though Digital Paper represents the fastest-expanding structural category as inkjet-optimized surface engineering displaces legacy offset stocks in short-run commercial printing.
EMA and ECHA frameworks govern pigment migration limits in food-contact applications, while EU Green Deal directives on packaging recyclability are forcing reformulation away from non-separable polymer coatings. F-Gas Regulation indirectly constrains drying energy profiles in coated paper production, elevating capital requirements for thermal efficiency compliance. Stakeholders must monitor evolving titanium dioxide hazard classifications and their cascading impact on supplier liability structures and insurance underwriting across the value chain.
Market Dynamics
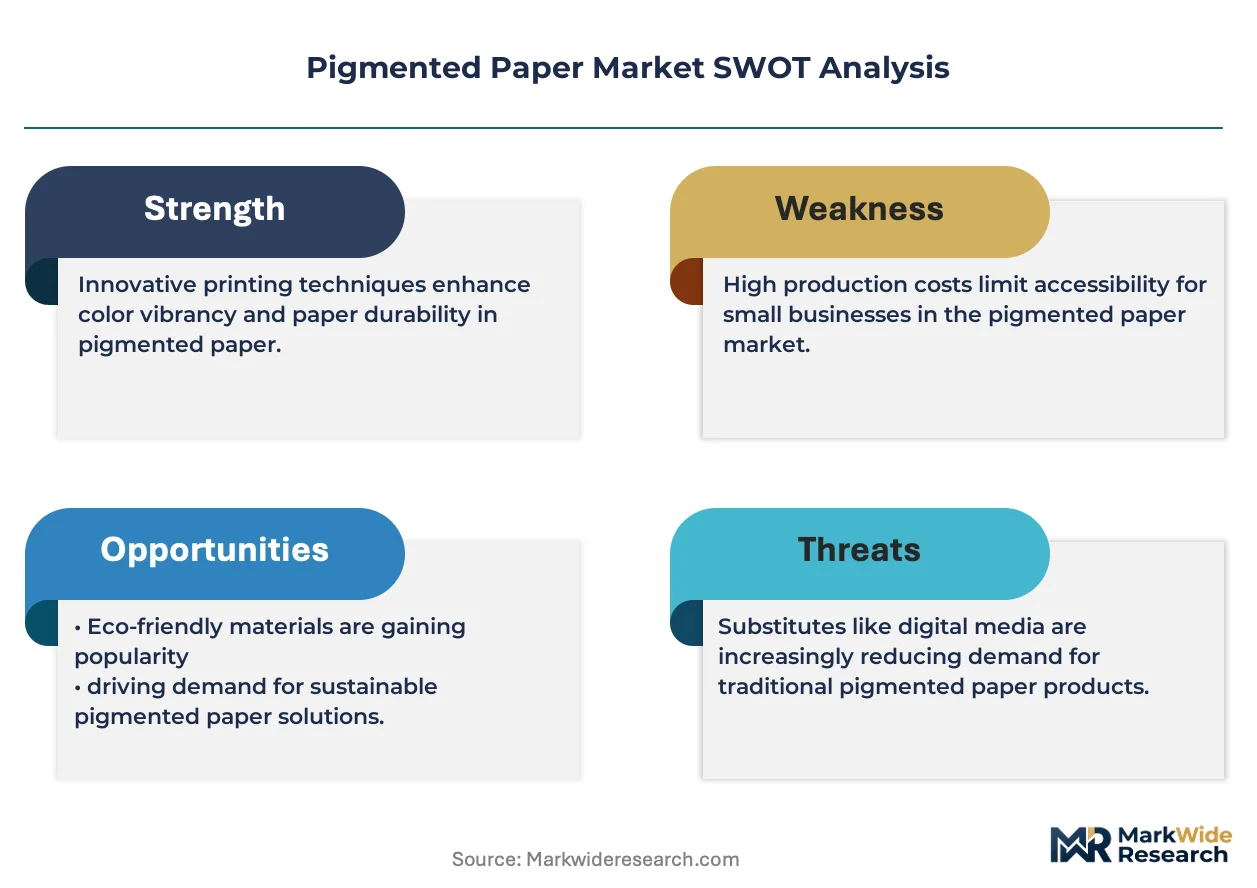
REACH compliance on titanium dioxide pigment classifications is forcing European specialty packaging converters to requalify entire supplier bases, compressing procurement timelines and elevating compliance costs across high-opacity coated paper supply chains.
Growth Catalysts
- EU Green Deal packaging recyclability mandates:Food-grade coated paper demand accelerates as brand owners abandon non-separable polymer laminates for mineral-pigmented alternatives that satisfy single-stream recovery protocols.
- Germany's Rhineland packaging cluster:Concentrated converting infrastructure draws upstream pigment formulation investment, creating localized supply efficiency for premium brightness specifications.
- Inkjet-optimized surface engineering:Digital printing adoption across short-run commercial channels pulls specialized pigmented substrates engineered for rapid drying and dot gain control.
Market Restraints
- Titanium dioxide feedstock volatility:Ilmenite and rutile ore price swings transmit directly to formulation costs, eroding margin stability for non-integrated pigment compounders.
- Pigment chemist scarcity:European paper mills face acute talent shortages in high-opacity formulation science, constraining capacity expansion for brightness-critical security paper segments.
- F-Gas Regulation thermal constraints:Drying energy profiles in coated paper production face escalating capital requirements for thermal efficiency compliance, disadvantaging smaller coating operations.
Strategic Opportunities
- Benelux converting hub expansion:Antwerp and Rotterdam logistics infrastructure supports just-in-time pigment delivery for flexible packaging converters seeking regional supply security.
- Archival and security paper applications:Fade resistance and dimensional stability specifications command premium positioning as government document modernization programs accelerate.
- Alkaline papermaking polymer innovation:Retention efficiency chemistry converges with mineral filler optimization to reduce fiber consumption per ton of finished substrate.
Industry Challenges
- Pigment migration testing protocols:EMA and ECHA food-contact compliance timelines extend qualification cycles, delaying new product introductions by 8-14 months.
- Legacy coating line retrofit requirements:Thermal drying system upgrades demand capital deployment that mid-tier converters struggle to finance under current interest rate conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigmented Paper Market |
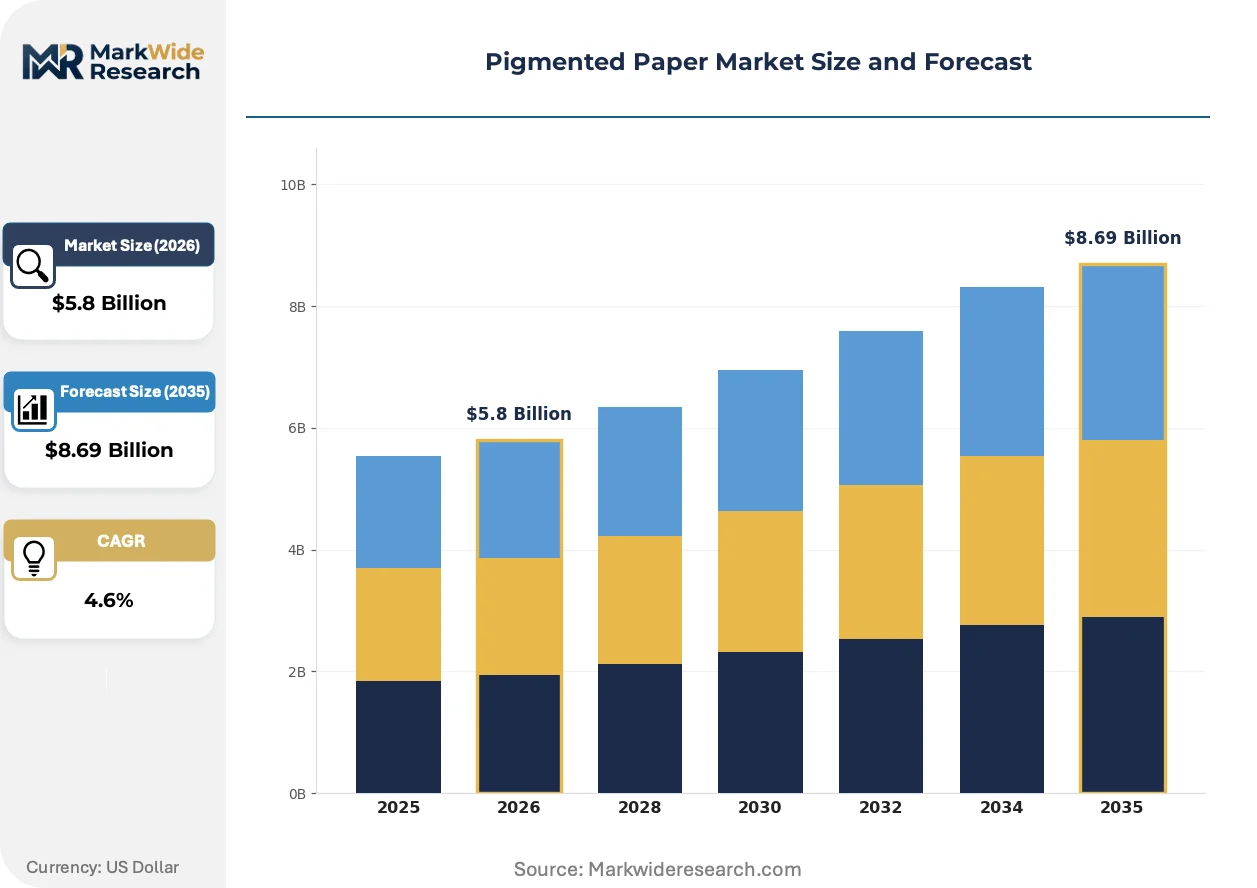
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Digital Paper End Use: Publishing, Packaging, Stationery, Labeling Application: Printing, Writing, Art and Craft, Business Communication Technology: Inkjet Printing, Offset Printing, Laser Printing, Heat Transfer |
| Companies Covered | Omya AG, Imerys, Minerals Technologies Inc., BASF SE, Cabot Corporation, Kemira Oyj, J.M. Huber Corporation, KaMin LLC, Mondi Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigmented Paper Market Strategic Shifts & Innovations
Surface engineering chemistry and regulatory chemistry are converging to redefine competitive advantage in pigmented paper, with mineral filler optimization and compliance-driven reformulation dominating R&D allocation.
Nano-structured calcium carbonate surface treatments are miniaturizing pigment particle distribution to achieve gloss uniformity previously requiring thicker coating weights. Security printing and high-end cosmetic packaging converters adopt these formulations aggressively. The technology is miniaturizing coating layer thickness requirements while maintaining ISO brightness thresholds above 90%.
ECHA's evolving titanium dioxide hazard classification framework is forcing pigment suppliers to maintain dual formulation tracks for regulated and non-regulated end-uses. Insurance underwriters now require substance volume tracking that smaller compounders cannot operationalize. Food-contact and toy packaging segments in Germany and France face the steepest compliance cost escalation.
Brand owner sustainability scorecards now weight recyclability certification above unit cost in coated paper selection criteria. Major FMCG procurement teams in the Netherlands and Belgium unbundle legacy polymer-laminated stocks in favor of mineral-pigmented alternatives with established fiber recovery pathways. This preference shift concentrates demand among converters with established EMAS environmental management certification.
Pigmented Paper Market Segmentation
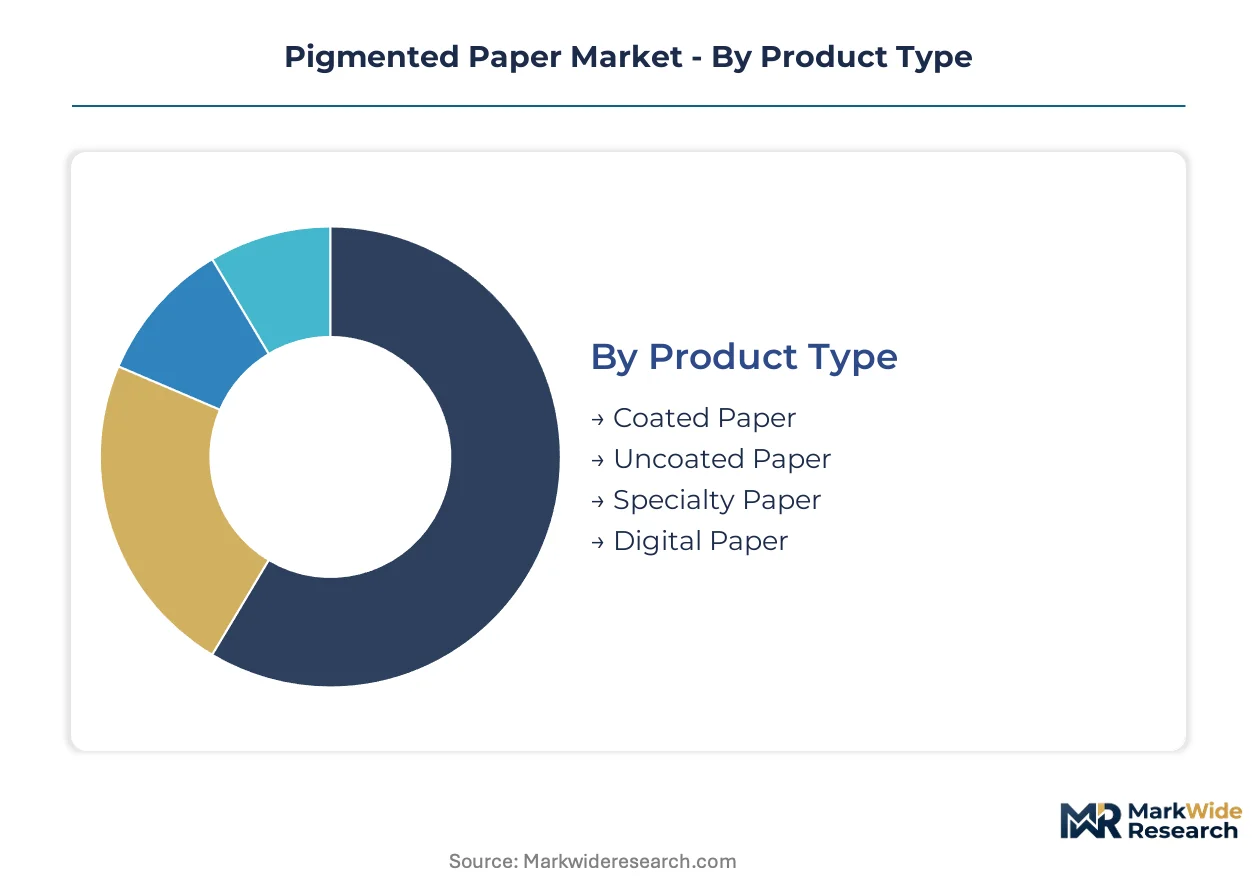
Segmentation in pigmented paper reveals how mineral filler optimization and surface engineering specifications diverge across end-use requirements. Substitution pressures from digital media and polymer-based packaging laminates are fragmenting demand patterns across product categories. Understanding these fault lines exposes where formulation investments yield defensive positioning versus commodity exposure.
Product Type:
Uncoated grades face the most acute substitution threat as electronic document workflows displace business communication volumes, while coated and specialty variants defend share through performance specifications that digital alternatives cannot replicate.
- Coated Paper:Mineral-pigmented substrates with engineered surface treatments achieve ISO brightness above 90% through controlled calcium carbonate and kaolin distribution. Premium food-grade packaging converters in Germany's Rhineland cluster prioritize these formulations to satisfy EU Green Deal recyclability mandates that exclude polymer laminates.
- Specialty Paper:Archival-grade substrates incorporate fade-resistant pigment chemistries and dimensional stability engineering for security documents and high-value cosmetic packaging. Government modernization programs across France and Belgium are accelerating procurement of these premium specifications.
- Uncoated Paper:Volume staple for business communication channels, though demand erosion from digital displacement concentrates remaining procurement among cost-optimized alkaline papermaking operations.
- Digital Paper:Inkjet-optimized surface engineering with rapid drying characteristics and controlled dot gain properties. Short-run commercial printing adoption in the Netherlands and Belgium pulls specialized substrate development.
Uncoated Paper retains volume leadership; Digital Paper holds the steepest expansion curve.
End Use:
Packaging applications command the highest margin tier as brand sustainability scorecards elevate mineral-pigmented alternatives above polymer-laminated competitors, while publishing volumes face structural compression from media digitization.
- Packaging:Food-grade and cosmetic applications dominate procurement, with EMAS-certified converters in Antwerp and Rotterdam capturing regional supply security advantages through just-in-time pigment logistics.
- Publishing:Magazine and catalog segments contract as advertising spend migrates to digital channels, though premium art book niches sustain brightness-critical coated specifications.
- Stationery:Corporate identity and premium writing paper maintain stable demand through gift and ceremonial applications, particularly in German and Swiss markets.
- Labeling:Pressure-sensitive and wet-glue applications require specialized surface adhesion engineering, with adhesive compatibility testing extending qualification cycles under ECHA migration protocols.
Packaging captures the premium pricing tier; Labeling demonstrates the most resilient volume stability against digital substitution.
Application:
Business Communication volumes fragment across digital transition stages, while Art and Craft segments defend physical substrate demand through experiential consumption patterns that resist screen-based alternatives.
- Printing:Commercial and security printing applications split between high-volume offset-optimized stocks and specialized pigmented substrates for anti-counterfeiting features. REACH compliance on titanium dioxide classifications is forcing dual-track formulation maintenance for regulated versus non-regulated end-uses.
- Art and Craft:Pigment loadings and surface textures engineered for watercolor, acrylic, and mixed-media applications command sustained premium positioning. Art supply distributors in France and Germany anchor regional demand concentration.
- Writing:Fountain pen compatibility and bleed resistance specifications differentiate premium stationery grades from commodity copier paper.
- Business Communication:Letterhead, forms, and direct mail volumes decline as enterprise workflows digitize, though compliance documentation retains paper-based requirements in regulated industries.
Printing maintains the broadest end-use diversification; Art and Craft exhibits the strongest pricing power per ton.
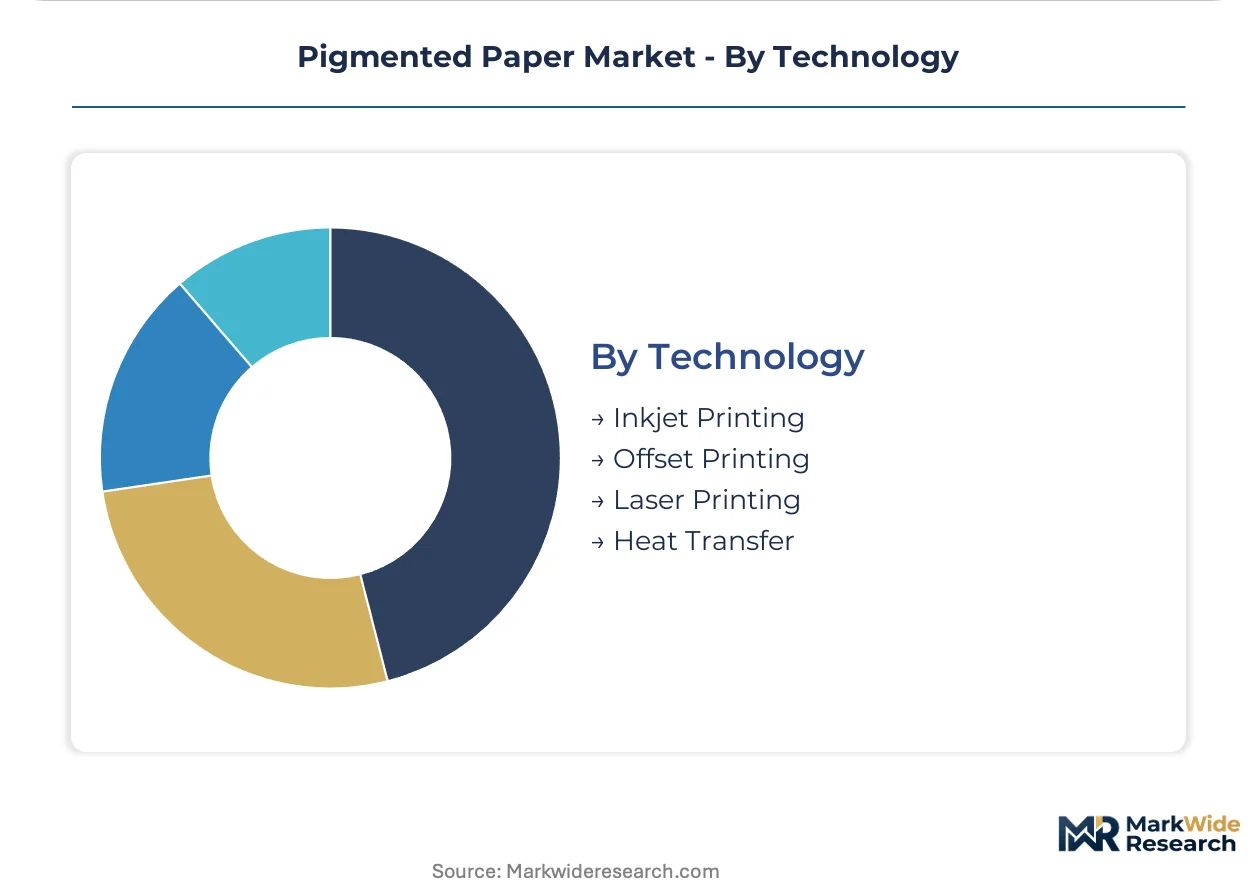
Technology:
Inkjet-optimized substrates are displacing legacy offset stocks as print run lengths compress and personalization requirements intensify, while heat transfer applications defend niche positions in textile and promotional markets.
- Inkjet Printing:Surface porosity and coating chemistry engineered for rapid ink absorption and minimal feathering. Short-run commercial converters across the Benelux region are migrating capacity toward these specifications.
- Offset Printing:Traditional high-volume applications face capacity rationalization as run lengths shrink, though security printing and long-run packaging maintain stable demand.
- Laser Printing:Heat-resistant coating formulations prevent toner offset and ensure fuser compatibility in high-speed office environments.
- Heat Transfer:Sublimation-ready coatings for textile decoration and promotional product applications, with specialized pigment binders that release under thermal pressure.
Offset Printing retains installed base dominance; Inkjet Printing climbs the fastest in capacity investment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH classifications on titanium dioxide pigment anchor European supply chain reconfiguration, with ECHA regulatory timelines compressing procurement cycles across high-opacity coated paper applications. Mill operators from Germany to Belgium face dual pressure from compliance costs and pigment chemist scarcity.
Germany
Specialty packaging converters in the Rhineland cluster drive premium food-grade coated paper procurement, with EMAS-certified operations capturing regional supply security advantages. The country's national environmental regulator enforces strict migration limits for food-contact applications. Düsseldorf and Cologne anchor converting infrastructure that draws upstream pigment formulation investment for brightness-critical specifications.
Netherlands
Rotterdam's port logistics infrastructure supports just-in-time calcium carbonate delivery for flexible packaging converters seeking supply chain resilience. EU Green Deal packaging recyclability mandates accelerate brand owner migration from polymer laminates to mineral-pigmented alternatives. Eindhoven and Amsterdam host procurement teams that weight sustainability certification above unit cost in supplier selection.
Belgium
Antwerp's chemical processing hub concentrates pigment compounding capacity for security paper and archival applications. ECHA hazard classification frameworks force dual-track formulation maintenance for regulated versus non-regulated end-uses. Brussels and Ghent house government document modernization programs that accelerate fade-resistant substrate procurement.
France
Cosmetic packaging converters in Île-de-France prioritize nano-structured calcium carbonate surface treatments for gloss uniformity at reduced coating weights. ANSM food-contact compliance timelines extend qualification cycles for new pigment introductions. Lyon and Marseille anchor art supply distribution networks that sustain premium pigmented paper demand for watercolor and mixed-media applications.
Switzerland
Archival-grade substrate specifications from Swissmedic-regulated pharmaceutical documentation sustain premium positioning for brightness-critical security papers. The country's national pharmaceutical regulator maintains strict dimensional stability requirements for long-term record retention. Zurich and Basel concentrate specialized converting operations that serve government and banking document modernization programs.
Pigmented Paper Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the pigmented paper value chain. Mineral pigment specialists with captive reserves command margin stability against raw material volatility, while polymer chemistry experts differentiate through retention efficiency in alkaline papermaking environments. The competitive structure fragments across three strategic archetypes: vertically integrated mineral compounders, specialized coating technology licensors, and diversified paper producers with in-house formulation capabilities. Dominant competitive moves include backward integration into calcium carbonate reserves and strategic partnerships between pigment suppliers and EMAS-certified converters.
Within the mineral compounder tier, Omya AG and Imerys exemplify divergent approaches to raw material security. Omya AG leverages upstream control over calcium carbonate reserves to sustain formulation cost advantages, while Imerys anchors its positioning through specialized kaolin processing capabilities. Kemira Oyj occupies a distinct technology-licensing position, with its polymer expertise controlling retention efficiency chemistry that reduces fiber consumption per ton of finished substrate. These three entities collectively represent the competitive fault lines between mineral-based and polymer-based formulation strategies.
| Leading Market Players |
|---|
| Omya AG |
| Imerys |
| Minerals Technologies Inc. |
| BASF SE |
| Cabot Corporation |
| Kemira Oyj |
| J.M. Huber Corporation |
| KaMin LLC |
| Mondi Group PLC |
| Others |
Cost & Logistics Intelligence
Mill-scale economies in Germany's Rhineland packaging cluster concentrate pigment formulation capacity among three integrated compounders, establishing price floors that smaller Benelux converters cannot match without EMAS certification premiums. REACH compliance costs on titanium dioxide classifications transmit directly to coating weight specifications, forcing procurement teams to trade off brightness thresholds against regulatory liability exposure.
Pricing Analysis
German Rhineland converters command 15-20% price premiums over Polish and Czech competitors for identical ISO brightness specifications, reflecting EMAS environmental certification and just-in-time logistics integration. Three-tier pricing structure across premium EMAS-certified, standard food-grade, and economy business communication levels stratifies buyer access, with pigment migration testing protocols adding qualification surcharges to premium tiers. Cost compression in economy uncoated grades is intensifying because digital displacement erodes volume leverage, while specialty archival segments exhibit lowest price sensitivity due to government document modernization mandates.
Supply Chain Analysis
Just-in-time calcium carbonate delivery dominates flexible packaging procurement in Antwerp and Rotterdam, though security paper converters maintain strategic stockpiles of fade-resistant kaolin grades against supply disruption. Raw material sourcing draws from Norwegian calcium carbonate reserves, Ukrainian kaolin deposits, and South African rutile ore, with pigment compounding concentrated in Belgium, Germany, and Finland. Single-source vulnerability in titanium dioxide feedstock exposes formulation costs to ilmenite price volatility. Distribution runs through EMAS-certified converting hubs that qualify for FMCG brand owner sustainability scorecards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pigmented paper market is entering a cyclical recovery phase as EU Green Deal packaging mandates force brand owner procurement away from polymer laminates toward mineral-pigmented alternatives, creating replacement demand across food-grade and cosmetic applications.
For Market Incumbents: Consolidate formulation capabilities through backward integration into calcium carbonate reserves or specialized kaolin processing, mirroring Omya AG's captive supply strategy. Acquire EMAS-certified converting capacity in the Benelux corridor to capture just-in-time logistics premiums that offset REACH compliance cost inflation. Defensive positioning requires dual-track titanium dioxide formulation maintenance as ECHA hazard classifications evolve.
For New Entrants and Emerging Players: EMAS environmental certification fast-tracks access to Netherlands and Belgium FMCG procurement teams that weight sustainability scorecards above unit cost. Target nano-structured calcium carbonate surface treatment niches where gloss uniformity specifications command premium positioning in cosmetic packaging. White-space entry favors archival and security paper segments in France and Switzerland where government document modernization programs accelerate fade-resistant substrate demand.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors polymer chemistry specialists with retention efficiency expertise in alkaline papermaking environments, analogous to Kemira Oyj's technology-licensing model. Long-term viability over a 5-10 year window rests on mineral filler optimization convergence with digital printing substrate engineering. Acquisition targets should demonstrate established ECHA compliance infrastructure and EMAS certification pathways. The signal to monitor is titanium dioxide hazard classification revisions that would trigger insurance underwriting recalibration across pigment supplier liability structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Reserves | Omya AG's calcium carbonate captive supply sustains margin stability against rutile ore volatility. |
| EMAS Certification Investment | Antwerp and Rotterdam converters capture FMCG procurement preference for established fiber recovery pathways. |
| Nano-Structured Surface Treatment Development | Cosmetic packaging converters adopt miniaturized pigment distribution for reduced coating weight specifications. |
| Dual-Track Formulation Maintenance | Pigment suppliers hedge ECHA titanium dioxide reclassification risk across food-contact and non-regulated end-uses. |
| Inkjet-Optimized Substrate Engineering | Benelux short-run commercial printers migrate capacity toward rapid drying surface chemistry specifications. |
Research Approach
Initial hypotheses were tested against primary input from paper mill technical directors, specialty packaging procurement managers, pigment formulation chemists, and EMAS certification auditors, then refined against secondary validation from REACH registration databases, ECHA hazard classification dossiers, EU Green Deal packaging directive texts, and customs trade flow records for calcium carbonate and kaolin imports. Bottom-up volume modeling across converting capacity and top-down value triangulation against disclosed segment revenues were cross-referenced for consistency.
Variance decomposition across product type, end-use application, surface engineering technology, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from installed coating capacity expansion schedules, brand owner sustainability procurement policy disclosures, and digital printing adoption curves in short-run commercial channels. Modeled inputs incorporated EMAS certification penetration rates, titanium dioxide price elasticity assumptions, and inkjet substrate qualification timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or ECHA classification stability would require recalibration. Forecasts reflect assumptions on pigment chemist labor market tightness, REACH compliance cost pass-through rates, and ilmenite ore supply continuity. Revision becomes warranted when titanium dioxide hazard reclassification triggers insurance underwriting exclusions or when digital printing substrate adoption crosses inflection thresholds in security printing applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Tissue Paper Market
Paper Products
Paper Machine Systems Market
Paper Products
Printing and Writing Papers Market
Paper Products
Reprographic Paper Market
Paper Products
Inlay Paper Market
Paper Products
Stone Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Acrylic Paper Market
Paper Products
Thin Printing Paper Market
Paper Products
Paper Machinery Market
Paper Products
Global Security Paper Market
Paper Products
Hardwood Pulp Market
Paper Products
Europe Medium-Density Fiberboard Market