
 Unbleached Softwood Kraft Pulp Market | 2026-2036
Unbleached Softwood Kraft Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Unbleached Softwood Kraft Pulp Market Outlook
Project finance tied to certified sustainable forestry is fragmenting competitive access to long-fiber supply. Stora Enso leverages its integrated Nordic mill network to control fiber sourcing from boreal forests. International Paper anchors North American capacity through scale advantages in southeastern US pine belt operations. UPM-Kymmene Corporation differentiates via biorefinery co-product streams that offset virgin pulp cost structures.
Unbleached softwood kraft pulp consists of cellulose fibers extracted from coniferous wood species through the sulfate cooking process, typically retaining lignin content below five percent and yielding high tensile strength for reinforcement applications in paper and board laminates. The kraft process employs sodium sulfide and sodium hydroxide to delignify wood chips while preserving fiber length, producing material prized for tear resistance in packaging grades and absorbent layers. Containerboard commands the dominant volume position as e-commerce corrugated demand strains recycled fiber systems, while specialty papers capture concentrated margin pools in filter and electrical insulation niches. Tissue paper represents the fastest-expanding application segment as Asian consumer markets upgrade from recycled furnish to virgin softwood blends for premium hygiene products.
The EU Green Deal and associated Deforestation Regulation reshape import compliance burdens for non-European suppliers, while FDA food-contact substance notifications govern US pulp migration limits in packaging applications. REACH chemical registration requirements affect process chemical suppliers across European mill networks, creating differentiated compliance costs by geography. Stakeholders must monitor evolving chain-of-custody certification schemes as brand owners harden Scope 3 emissions accounting for virgin fiber inputs.
Market Dynamics
EU Deforestation Regulation enforcement is fragmenting long-fiber supply chains as non-European mills face escalating traceability audits and certification gaps. This structural force concentrates procurement power within Nordic integrated producers holding FSC and PEFC chain-of-custody documentation.
Growth Catalysts
- E-commerce containerboard demand:Corrugated packaging strains recycled fiber systems, forcing mills to blend virgin softwood kraft for tensile strength and burst resistance in heavy-duty shipping boxes.
- EU Green Deal traceability mandates:The regulation requires geolocation verification for all virgin fiber imports, advantaging European producers with established digital chain-of-custody systems.
- Asian tissue premiumization:Consumer markets in South Korea and Japan upgrade hygiene products from recycled furnish to virgin softwood blends for softness and absorbency performance.
Market Restraints
- Boreal fiber supply concentration:Finnish and Swedish mill complexes control over sixty percent of exportable long-fiber capacity, creating single-source vulnerability for specialty paperboard producers.
- Energy cost volatility:Kraft pulping requires steam-intensive digester operations, exposing margins to natural gas price spikes in European grid-dependent facilities.
- Mechanical pulp substitution:Thermomechanical pulp from spruce and fir offers lower-cost reinforcement for some packaging grades, compressing kraft pulp pricing power in commodity segments.
Strategic Opportunities
- Biorefinery co-product monetization:Lignin extraction and tall oil distillation create revenue offsets against virgin pulp production costs, with biochemical applications expanding in adhesives and carbon fiber precursors.
- India packaging modernization:Food safety regulations from FSSAI mandate virgin fiber for direct-contact applications, opening import demand from mills with FDA-compliant bleaching sequences.
- Blockchain traceability integration:Distributed ledger systems verify chain-of-custody from stump to reel, satisfying brand owner Scope 3 emissions accounting requirements.
Industry Challenges
- Auditor certification bottlenecks:FSC and PEFC accredited bodies face eighteen-month backlogs for mill recertification, delaying market access for capacity expansions.
- Legacy digester control system integration:Digital twin implementations for cooking liquor optimization require retrofitting analog-era distributed control systems without production shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unbleached Softwood Kraft Pulp Market |
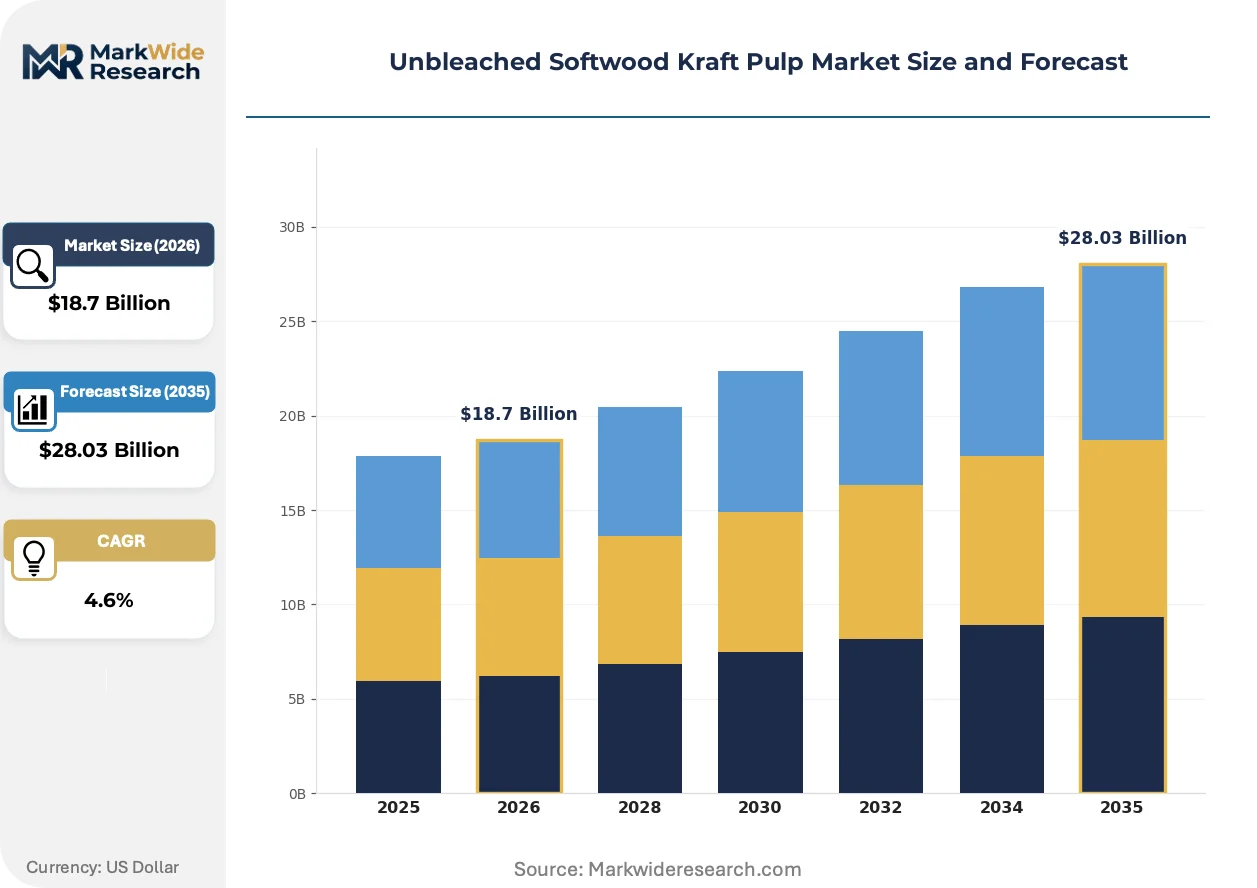
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Market Paper, Tissue Paper, Containerboard, Specialty Papers End Use Industry: Pulp & Paper, Packaging, Textile, Construction Deployment: Onshore, Offshore, Integrated, Converted Quality Grade: Premium, Standard, Low, Recycled |
| Companies Covered | Stora Enso, International Paper, UPM-Kymmene Corporation, West Fraser Timber, Canfor Corporation, Resolute Forest Products, WestRock Company, Sappi Limited, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unbleached Softwood Kraft Pulp Market Strategic Shifts
Process intensification and regulatory digitization are compressing traditional competitive advantages based on scale alone. Technology convergence between biorefining and pulp production is rewriting cost structures across the value chain.
Continuous cooking technology is hybridizing batch kraft processes with extended delignification stages that reduce chemical consumption while preserving fiber length. Specialty paperboard producers in Germany and the Netherlands adopt these systems fastest, seeking tear strength specifications that recycled fiber cannot meet. The technology is hybridizing capital deployment patterns, favoring brownfield upgrades over greenfield mill construction.
REACH chemical registration requirements now govern process aids and biocides across European mill networks, with ECHA evaluating sodium hydrosulfide alternatives for worker exposure reduction. Compliance costs diverge sharply by geography, as US EPA regulations maintain less restrictive hazard communication standards. Containerboard producers with cross-border supply chains face the steepest formulation reconciliation burdens.
Brand owner Scope 3 emissions accounting is reshaping procurement specifications, with sustainability teams now vetoing virgin fiber lacking granular carbon footprint data. Direct mill relationships are displacing merchant traders for large packaging converters, compressing spot market liquidity. This behavioral shift concentrates most visibly in Nordic supply agreements, where integrated producers offer product-level environmental product declarations.
Unbleached Softwood Kraft Pulp Market Segmentation
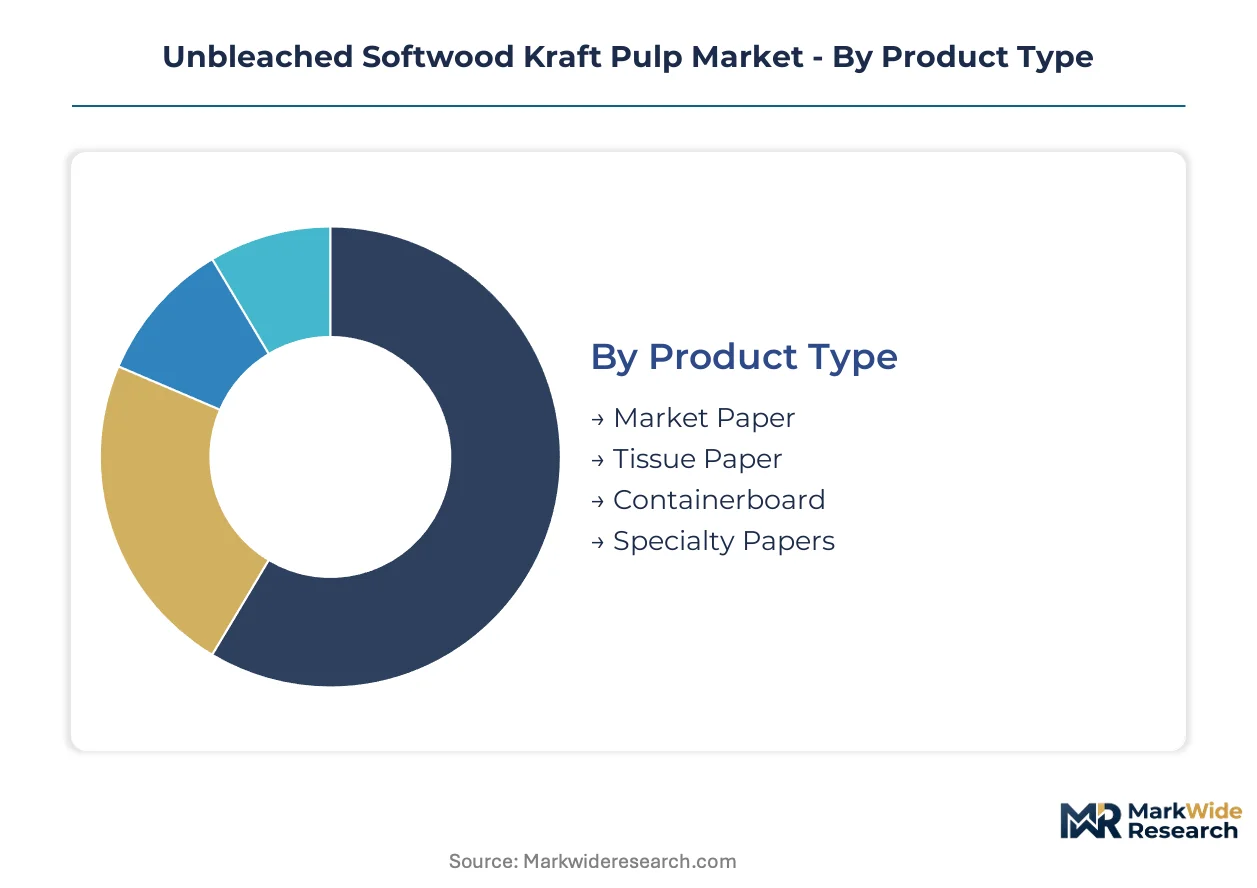
Segment boundaries in unbleached softwood kraft pulp reflect divergent technical specifications, certification requirements, and end-use performance thresholds. Procurement teams segment supply by fiber length, lignin content, and chain-of-custody documentation to match pulping economics with downstream manufacturing constraints.
Product Type:
Inventory velocity varies sharply across product types, with tissue paper turning fastest due to consumer replenishment cycles while specialty papers sit longest awaiting custom orders.
- Containerboard:High-tensile reinforcement pulp blended into corrugated medium and linerboard for e-commerce shipping boxes. Demand concentrates in German and Dutch specialty paperboard mills as EU Green Deal traceability mandates tighten virgin fiber sourcing.
- Tissue Paper:Softwood blends deliver absorbency and softness for premium hygiene products. South Korean and Japanese consumer markets upgrade from recycled furnish fastest, driving spot market premiums for long-fiber softwood grades.
- Market Paper:Standard-grade pulp sold on commodity exchanges for general printing and writing paper production.
- Specialty Papers:Filter media, electrical insulation, and release liner applications requiring precise fiber morphology control.
Containerboard dominates installed base. Tissue paper is where expansion concentrates.
End Use Industry:
Cost-to-serve economics stratify sharply across end uses, with packaging converters squeezing logistics costs while textile spinners absorb premium freight for specialized dissolving pulp grades.
- Packaging:Corrugated converters blend virgin softwood kraft with recycled furnish to meet burst strength specifications for heavy-duty shipping applications. FDA food-contact substance notifications govern US migration limits, while EU Deforestation Regulation traceability audits concentrate procurement power with Nordic integrated producers.
- Pulp & Paper:Integrated mills consume captive pulp for downstream paper and board production, optimizing cooking liquor recovery and energy integration.
- Textile:Viscose and lyocell producers require dissolving pulp with controlled hemicellulose content for regenerated fiber applications.
- Construction:Fiber cement and gypsum board manufacturers use softwood kraft for dimensional stability in building materials.
Packaging commands volume leadership. Pulp & paper integration is climbing the fastest.
Deployment:
Capital intensity and margin capture diverge by deployment mode, with integrated assets locking in fiber supply while converted operations arbitrage spot market dislocations.
- Integrated:Pulp mills captive to paper machines eliminate merchant market exposure and optimize energy recovery through combined heat and power systems. Finnish and Swedish mill complexes anchor this model with FSC and PEFC chain-of-custody documentation spanning boreal forest to finished reel.
- Converted:Standalone pulp mills supply external paper and board producers, requiring inventory buffers and logistics coordination across waterborne and rail networks.
- Onshore:Domestic production serving regional paper mills with minimized transport costs and customs clearance friction.
- Offshore:Export-oriented capacity positioned for deep-sea bulk shipment to Asian packaging and tissue markets.
Integrated deployment holds margin advantage. Converted operations are gaining share fastest in emerging market supply gaps.
Quality Grade:
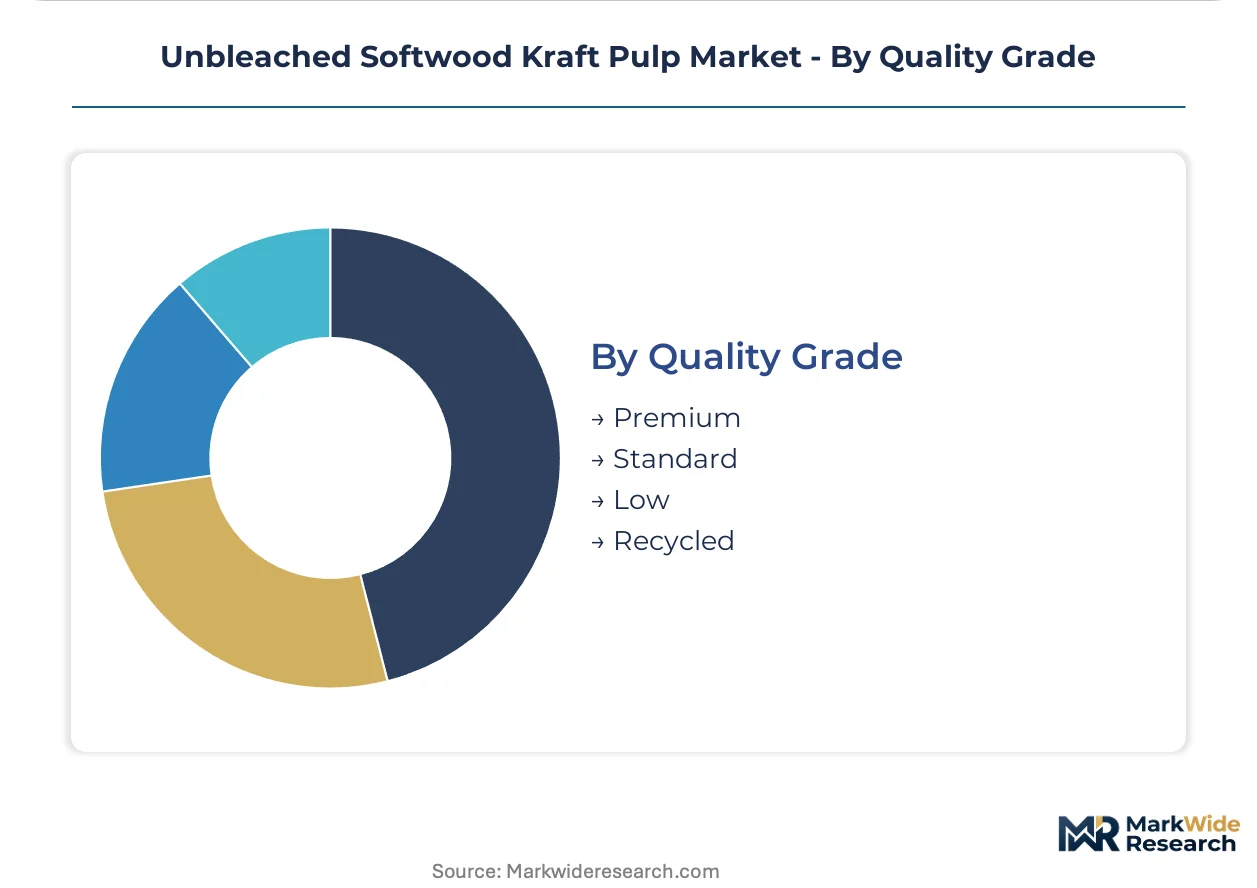
Pricing power and customer stickiness stratify by certification tier, with premium grades commanding long-term contracts while recycled grades compete on spot market liquidity.
- Premium:FSC and PEFC certified pulp with granular carbon footprint data and environmental product declarations. Brand owner Scope 3 emissions accounting requirements in Germany and the Netherlands lock in procurement premiums for documented sustainable forestry.
- Standard:Conventional kraft pulp meeting basic technical specifications without chain-of-custody certification, serving cost-sensitive packaging converters.
- Low:Downgraded pulp with higher shive content or off-specification brightness for filler applications.
- Recycled:Post-consumer recovered fiber blended with virgin softwood for sustainability positioning in select tissue and towel grades.
Premium grade captures contract stability. Standard grade handles spot market volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances concentrate trade flows through Nordic mill complexes and North American pine belt operations, with Asian packaging converters absorbing spot cargoes amid recycled fiber shortages. Geolocation verification mandates under EU Deforestation Regulation reshape procurement geography.
Finland
Specialty paperboard producers in Germany expand orders for Finnish long-fiber grades as EU Green Deal traceability requirements tighten. Metsähallitus forest certification underpins FSC chain-of-custody documentation for Kemi and Oulu mill complexes. The Kemi biorefinery cluster monetizes lignin extraction and tall oil distillation alongside pulp production.
Sweden
Pulp & paper integration climbs fastest in Värmland and Norrland regions where combined heat and power systems optimize energy recovery. Swedish EPA environmental permits govern digester emissions and chemical recovery boiler operations. Sundsvall timber belt mills anchor export capacity for Asian tissue premiumization demand.
United States
Containerboard converters blend southeastern pine belt pulp to meet burst strength specifications for e-commerce corrugated demand. FDA food-contact substance notifications govern migration limits in packaging applications. Georgia and Alabama mill networks leverage scale advantages through integrated kraft linerboard production.
Canada
British Columbia interior mills face fiber cost pressure from mountain pine beetle salvage timber depletion. Canadian Environmental Protection Act regulations align with US EPA standards for cross-border supply chains. Alberta and Quebec operations pivot toward dissolving pulp grades for textile viscose markets.
China
Packaging modernization drives import demand for FDA-compliant unbleached grades from North American suppliers. National Forestry and Grassland Administration chain-of-custody documentation requirements tighten for imported virgin fiber. Yangtze River Delta converters blend softwood kraft with domestic recycled furnish for containerboard laminates.
Unbleached Softwood Kraft Pulp Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on fiber sourcing and chemical recovery. Nordic integrated producers hold procurement power through FSC and PEFC documentation spanning boreal forest to finished reel. Three archetypes dominate: biorefinery-integrated pulp producers, scale-driven North American pine belt operators, and specialty dissolving pulp refiners. Competitive moves concentrate on brownfield continuous cooking upgrades and blockchain traceability system deployment.
Within the Nordic integrated tier, Stora Enso and UPM-Kymmene Corporation exemplify biorefinery-co-product monetization strategies that offset virgin pulp production costs. International Paper anchors North American scale positioning through southeastern US pine belt operations. These three represent divergent geographic and technological archetypes rather than direct substitutability.
| Leading Market Players |
|---|
| Stora Enso |
| International Paper |
| UPM-Kymmene Corporation |
| West Fraser Timber |
| Canfor Corporation |
| Resolute Forest Products |
| WestRock Company |
| Sappi Limited |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
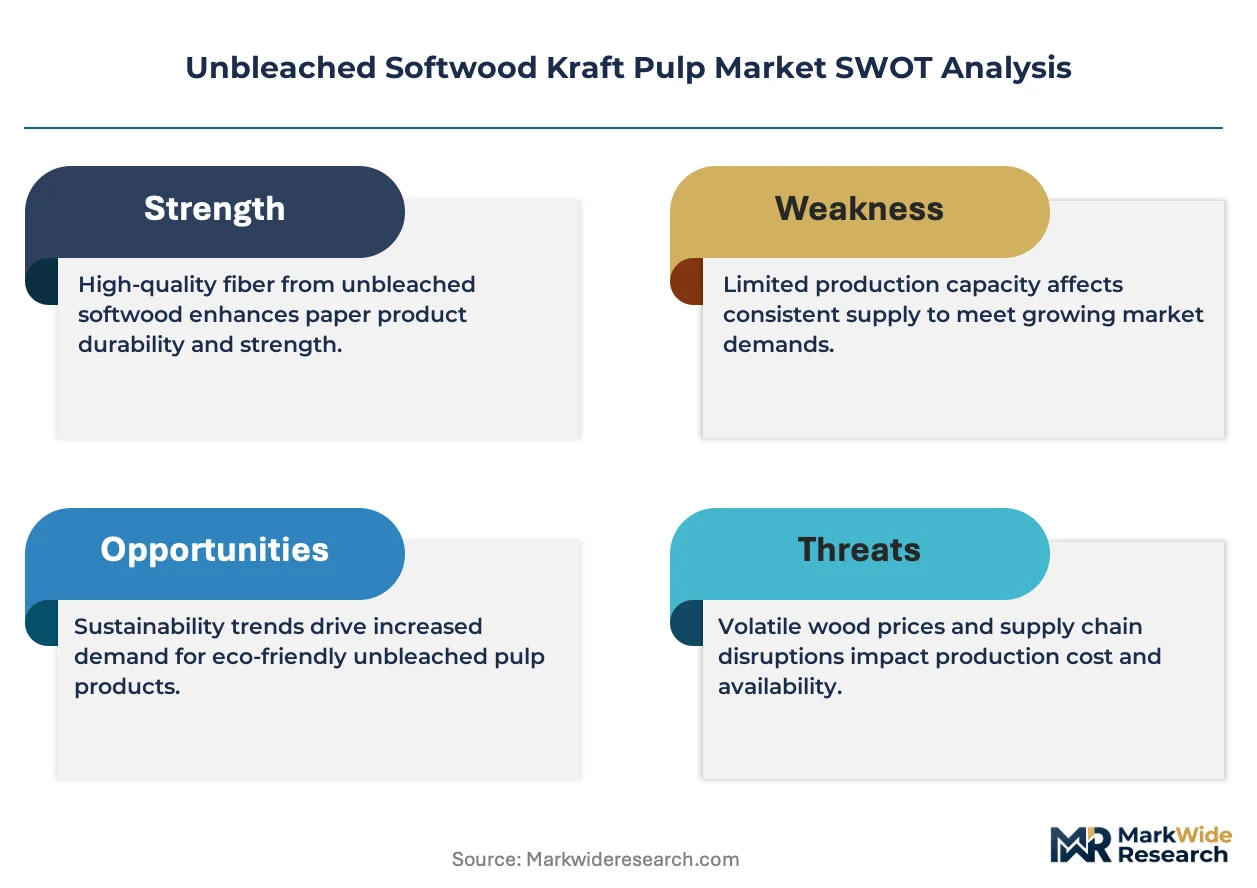
Baltic Sea bulk freight corridors transmit cost volatility directly into Nordic pulp delivered pricing, concentrating margin capture with Finnish and Swedish mills while forcing German specialty paperboard converters to absorb premiums for FSC-certified long-fiber grades. This logistics-cost feedback loop tightens as EU Deforestation Regulation geolocation verification mandates eliminate lower-cost non-European alternatives from qualified supplier lists.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments against indexed pulp price mechanisms. Three-tier pricing stratifies across premium certified, standard merchant, and economy downgraded tiers, with FSC and PEFC documentation commanding sustained premiums from brand owners with Scope 3 emissions accounting obligations. Cost compression in standard grades intensifies as thermomechanical pulp substitutes erode kraft pulp pricing power in commodity containerboard blends. Packaging converters exhibit highest price sensitivity due to thin corrugated margins, while specialty paperboard producers absorb premiums for tear-strength specifications that recycled fiber cannot satisfy.
Supply Chain Analysis
Boreal coniferous feedstock from Finnish and Swedish forest holdings feeds digester operations across the Nordic pulp cluster, with timber supply agreements spanning ten-to-fifteen-year rotations. Sodium sulfide and sodium hydroxide chemical inputs draw from European petrochemical and chlor-alkali networks, while tall oil and lignin co-product streams provide revenue offsets against virgin pulp production costs. Single-source vulnerability concentrates in the Sundsvall and Kemi mill complexes, which control over sixty percent of exportable long-fiber capacity. Distribution runs through deep-sea bulk shipment to Asian packaging converters and rail-fed European paperboard mills, with inventory buffers expanding for converted merchant pulp operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against thermomechanical pulp and recycled fiber blends that erode kraft pulp pricing power in commodity packaging grades. Incumbents must navigate mechanical pulp substitution threats while hardening certification-based differentiation.
For Market Incumbents: Harden FSC and PEFC chain-of-custody documentation through blockchain traceability integration that satisfies brand owner Scope 3 emissions accounting requirements. Expand backward integration into boreal forest timber supply agreements to lock in fiber sourcing against salvage timber depletion in North American pine belt operations. Prioritize continuous cooking technology upgrades that reduce chemical consumption while preserving fiber length specifications for specialty paperboard producers.
For New Entrants and Emerging Players: Build out biorefinery co-product monetization capabilities in lignin extraction and tall oil distillation, targeting revenue offsets that undercut established virgin pulp cost structures. Focus initial penetration on India packaging modernization demand, where FSSAI food safety regulations mandate virgin fiber for direct-contact applications and FDA-compliant bleaching sequences create qualification barriers for incumbent suppliers. Pursue toll-pulping arrangements with stranded timber assets in British Columbia interior regions.
For Investors and Strategic Acquirers: Brownfield mill specialists with digester upgrade potential and stranded energy infrastructure represent the most defensible acquisition targets against greenfield capital cost inflation. Long-term viability hinges on biorefinery pivot flexibility and certification documentation depth rather than scale alone. Watch for FSC and PEFC auditor certification bottlenecks as inflection indicators—eighteen-month recertification backlogs signal supply constraint windows where qualified capacity commands sustained pricing premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Cooking Upgrade | Reduces chemical consumption while preserving fiber length for German specialty paperboard specifications. |
| Blockchain Traceability Deployment | Verifies chain-of-custody from stump to reel for EU Deforestation Regulation compliance. |
| Biorefinery Co-Product Monetization | Lignin extraction and tall oil distillation offset virgin pulp production costs against mechanical pulp substitutes. |
| Boreal Timber Supply Integration | Captive fiber sourcing from Metsähallitus-certified forests locks in FSC documentation for Nordic mill networks. |
| Asian Tissue Market Expansion | South Korean and Japanese consumer premiumization drives spot market premiums for long-fiber softwood grades. |
Study Parameters
A spread of perspectives from pulp mill operations directors, specialty paperboard procurement managers, forest certification auditors, and chemical recovery boiler engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews across Finnish, Swedish, and North American mill complexes with secondary validation against customs trade data, FAO forest product statistics, SEC 10-K filings from publicly traded forest products companies, and ECHA chemical registration databases. Bottom-up capacity utilization modeling triangulated against top-down end-use demand segmentation across containerboard, tissue, and specialty paper applications.
Demand-supply balance mechanics anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, quality grade certification tier, deployment mode, and regional production hub. CAGRs derived from installed capacity expansion schedules, brownfield upgrade timelines, and end-use growth coefficients for e-commerce corrugated and premium hygiene products. Industry-specific forecast inputs incorporated EU Deforestation Regulation enforcement phasing and FDA food-contact substance notification trends governing US packaging migration limits.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biorefinery-integrated pulp producers or state-backed Asian capacity builders would shift outcomes beyond modeled ranges. Cross-checking against FAO forest product trade statistics and RISI pulp price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Carbonless Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Writing Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Billing Paper Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Liquid Paperboard Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Thin Printing Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Europe Decor Paper Market
Paper Products
Global Paperboard Market
Paper Products
Medical Grade Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Europe Thermal Paper Market