
 Europe Medium-Density Fiberboard Market | 2026-2036
Europe Medium-Density Fiberboard Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medium-Density Fiberboard Market Insights
Particleboard substitution in budget furniture and interior fit-outs is expanding the addressable base for MDF across European manufacturing. EGGER Group leverages captive forestry assets and resin formulation capabilities to sustain margin structures in Central European plants. Kronospan anchors production scale across multiple EU member states, while Pfleiderer Group differentiates through specialty surface finishes and thin-board expertise for high-end cabinetry applications.
Medium-density fiberboard is an engineered wood product manufactured from refined wood fibers bonded with synthetic resin under heat and pressure, typically yielding densities between 600 and 800 kg/m³ and uniform surface properties suited to lamination and painting. Its primary purpose is to provide dimensionally stable, cost-efficient panel substrates for furniture, interior construction, and decorative applications where solid wood proves uneconomical or structurally unsuitable. Standard MDF retains the largest volume share across European consumption, though moisture-resistant grades command premium positioning in kitchen and bathroom installations where humidity exposure is routine. Fire-retardant formulations represent a faster-growing niche driven by commercial building codes, while flexible MDF occupies specialized bending and curved-element fabrication segments with limited supplier competition.
ECHA REACH restrictions on formaldehyde classification and the EU Green Deal's embodied-carbon tracking requirements are reshaping resin chemistry investments and product certification pathways for panel producers. CE marking under the Construction Products Regulation governs structural and reaction-to-fire declarations, creating compliance thresholds that favor mid-cap to large manufacturers with in-house testing laboratories. Stakeholders must monitor evolving ECHA substance evaluations and national building-code harmonization to anticipate which product grades will face accelerated substitution or premium pricing power.
Market Dynamics
ECHA REACH formaldehyde reclassification and the EU Green Deal's embodied-carbon tracking are compressing resin chemistry choices and forcing capital redeployment toward low-emission panel grades across Central European production basins.
Growth Catalysts
- EU Green Deal carbon accounting:Builders and furniture manufacturers face procurement mandates for verified low-carbon substrates, accelerating specification of certified MDF in German and Polish contract interiors.
- Kitchen and bathroom humidity exposure:Moisture-resistant MDF grades capture specification share from untreated particleboard in residential wet-zone installations across Northern Europe.
- Flat-pack furniture manufacturing clusters:Poznań and Rhineland logistics hubs concentrate automated cutting and edge-banding capacity, creating localized demand pull for uniform-density panel supply.
Market Restraints
- Urea-formaldehyde resin cost volatility:Petrochemical feedstock fluctuations compress margin structures for standard-grade producers lacking captive chemical synthesis.
- Baltic and Nordic fiber supply concentration:Softwood pulp availability tightens during peak construction seasons, exposing mid-size panel mills to input rationing.
- Cross-laminated timber substitution:Engineered mass-timber systems displace MDF in exposed structural interior applications where aesthetic grain visibility commands premium positioning.
Strategic Opportunities
- Romanian and Bulgarian woodworking revival:Greenfield panel investments near Transylvanian forestry assets access lower-cost fiber and underdeveloped lamination subcontractor networks.
- Fire-retardant commercial building codes:Reaction-to-fire Class B and C certifications unlock specification in airport terminals, healthcare facilities, and high-rise cores under harmonized EN standards.
- Digital print-ready surface technologies:Direct-to-substrate UV printing compatibility opens short-run decorative panel production for hospitality and retail fixture segments.
Industry Challenges
- Resin formulation chemistry expertise:Formaldehyde-free and bio-based binder development requires polymer science capabilities scarce among legacy mechanical-engineering workforces.
- CE marking testing laboratory accreditation:In-house fire-reaction and emission certification infrastructure demands capital commitments exceeding smaller mill balance-sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medium-Density Fiberboard Market |
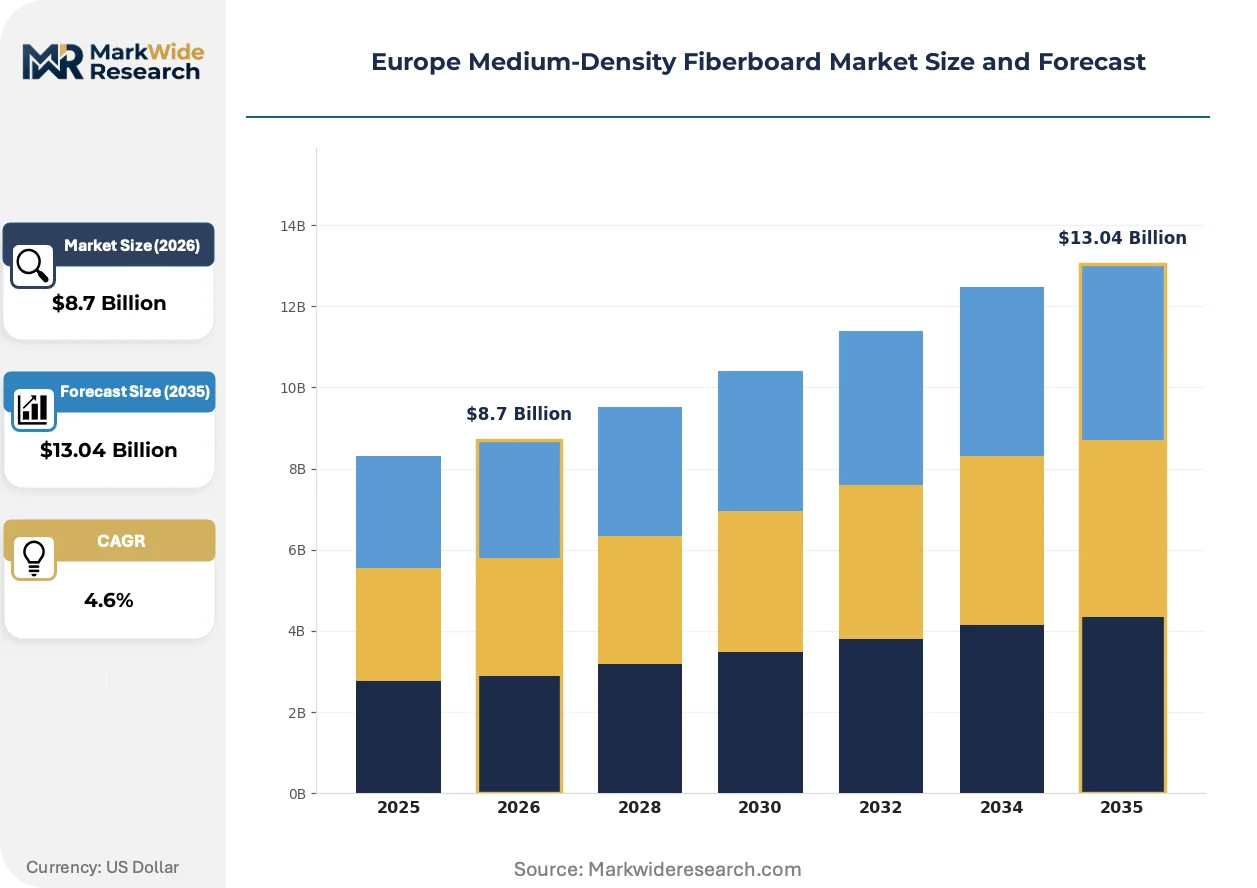
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MDF, Moisture Resistant MDF, Fire Retardant MDF, Flexible MDF Application: Furniture, Flooring, Cabinetry, Wall Panels End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Kastamonu Entegre, M. KAINDL GmbH, Kronospan, Sonae Arauco, Finsa, EGGER Group, Pfleiderer Group, Dynea AS, Swiss Krono Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medium-Density Fiberboard Market Trends and Innovations
Digital manufacturing integration and bio-based material science are reconfiguring how European panel producers compete on specification speed and environmental credential verification.
Continuous press technology with real-time density profiling is decentralizing production economics toward smaller-batch, higher-mix operations. Bavarian and Polish furniture subcontractors adopt these systems to compress order-to-delivery cycles for bespoke interior contracts. The technology is decentralizing volume concentration away from commodity-scale megaplants toward regional flexible-manufacturing nodes.
ECHA REACH restrictions on formaldehyde classification as a carcinogen are forcing resin system conversions across the value chain. Industrial consequence includes accelerated R&D spending on MDI and soy-based binders with higher raw-material costs. Kitchen and bathroom cabinet manufacturers in Germany and Austria are responding by consolidating procurement around suppliers with verified low-emission certification pipelines.
Specification behavior among large furniture retailers is pivoting toward environmental product declarations and digital carbon passports as mandatory bid prerequisites. Traditional spot-market purchasing through distributors is yielding to direct mill relationships with audit rights and chain-of-custody documentation. This shift is most visible in Nordic markets where public-sector procurement mandates drive private-sector compliance alignment.
Europe Medium-Density Fiberboard Market Segmentation
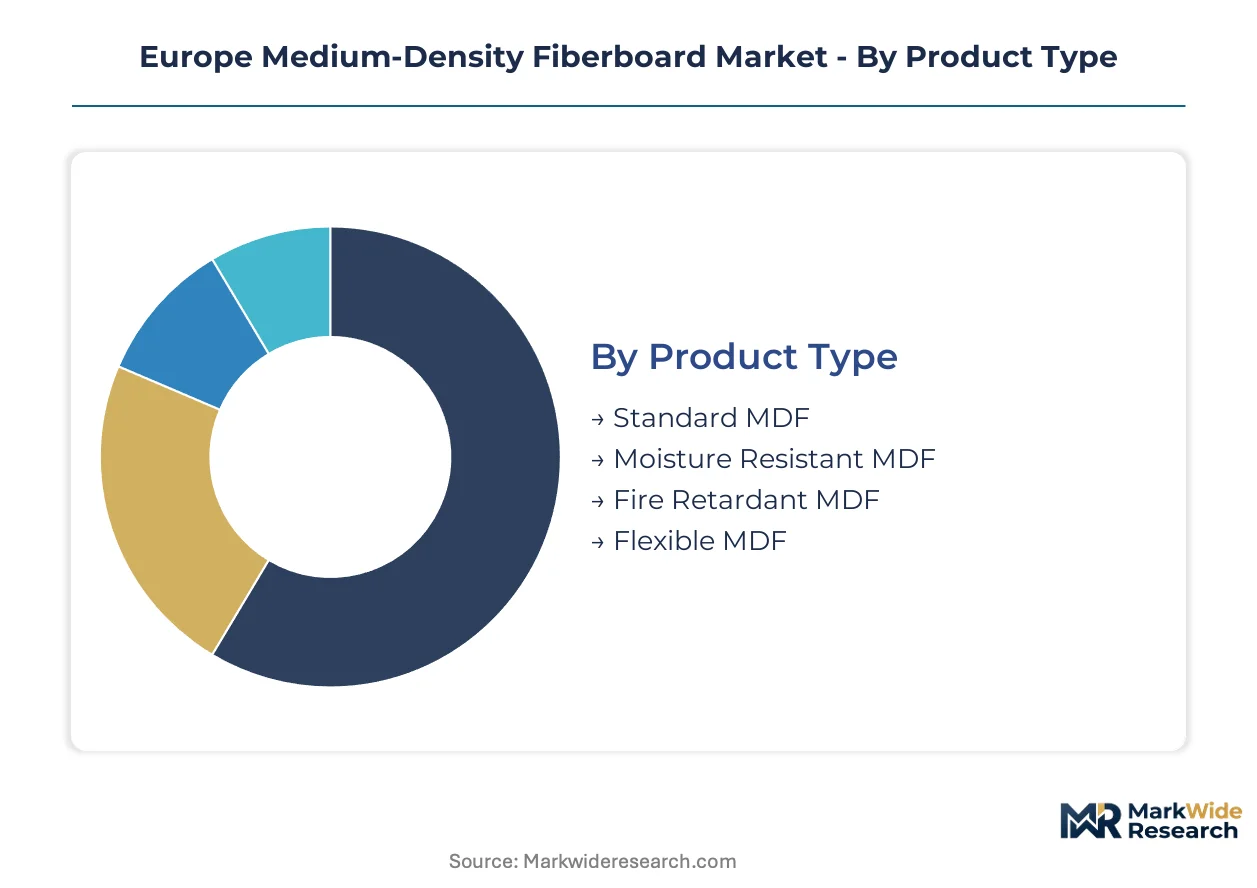
MDF specification diversity in Europe reflects divergent end-use performance requirements and tightening regulatory thresholds. Segmentation logic follows resin chemistry, density calibration, and reaction-to-fire certification as primary axes of supplier differentiation and buyer procurement behavior.
Product Type:
Density calibration and binder chemistry define the specification hierarchy across European panel procurement.
- Standard MDF:Urea-formaldehyde bonded panels at 600-800 kg/m³ density serve as the volume baseline for furniture carcasses and interior fit-outs. German and Polish flat-pack manufacturers anchor procurement around this grade, though ECHA REACH reclassification is compressing margin structures for producers lacking emission certification pipelines.
- Moisture Resistant MDF:Phenolic or enhanced UF resin systems with reduced thickness swelling coefficients target kitchen and bathroom installations across Northern Europe. Bavarian cabinetry manufacturers specify this grade for wet-zone contracts where untreated particleboard faces accelerated substitution.
- Fire Retardant MDF:Ammonium phosphate or boron-compound infused formulations achieve EN 13501-1 Class B and C reaction-to-fire ratings for commercial building cores.
- Flexible MDF:Reduced-density panels with engineered fiber orientation permit radius bending down to 50mm for curved reception desks and retail fixtures.
Standard MDF leads on scale; moisture resistant grades lead on momentum as wet-zone specifications tighten.
Application:
End-use performance requirements segment demand by surface finish tolerance, load-bearing duty, and humidity exposure profile.
- Furniture:Flat-pack and bespoke interior manufacturers in the Rhineland and Poznań clusters drive volume consumption, prioritizing uniform density for CNC machining and edge-banding consistency.
- Flooring:High-density overlays and laminate substrates require moisture-resistant cores with calibrated thickness swelling under 12%.
- Cabinetry:Moisture-resistant and low-emission grades capture specification share in German kitchen manufacturing, where CE marking and E1/E0.5 emission classes function as bid prerequisites.
- Wall Panels:Decorative surfacing and acoustic treatment applications favor medium-density boards with direct-laminate compatibility or print-ready surfaces.
Furniture commands absolute volume; cabinetry exhibits the steepest expansion trajectory as kitchen renovation cycles accelerate.
End User:
Procurement sophistication and certification requirements diverge sharply across buyer categories.
- Residential:Renovation and new-build housing drives standard-grade consumption through retail and wholesale channels, with sustainability credentials gaining weight in Nordic specification behavior.
- Commercial:Office fit-out and hospitality projects demand fire-retardant and low-emission certifications as mandatory bid components under EU Green Deal procurement mandates.
- Industrial:Packaging, tooling, and fixture manufacturing sources commodity grades through direct mill relationships with volume pricing structures.
- Institutional:Healthcare and education procurement operates under strict reaction-to-fire and hygiene standards, favoring suppliers with in-house testing laboratory accreditation.
Residential absorbs the greatest tonnage; institutional buyers command the tightest compliance thresholds.
Distribution Channel:
Channel selection reflects order scale, specification complexity, and documentation requirements across buyer segments.
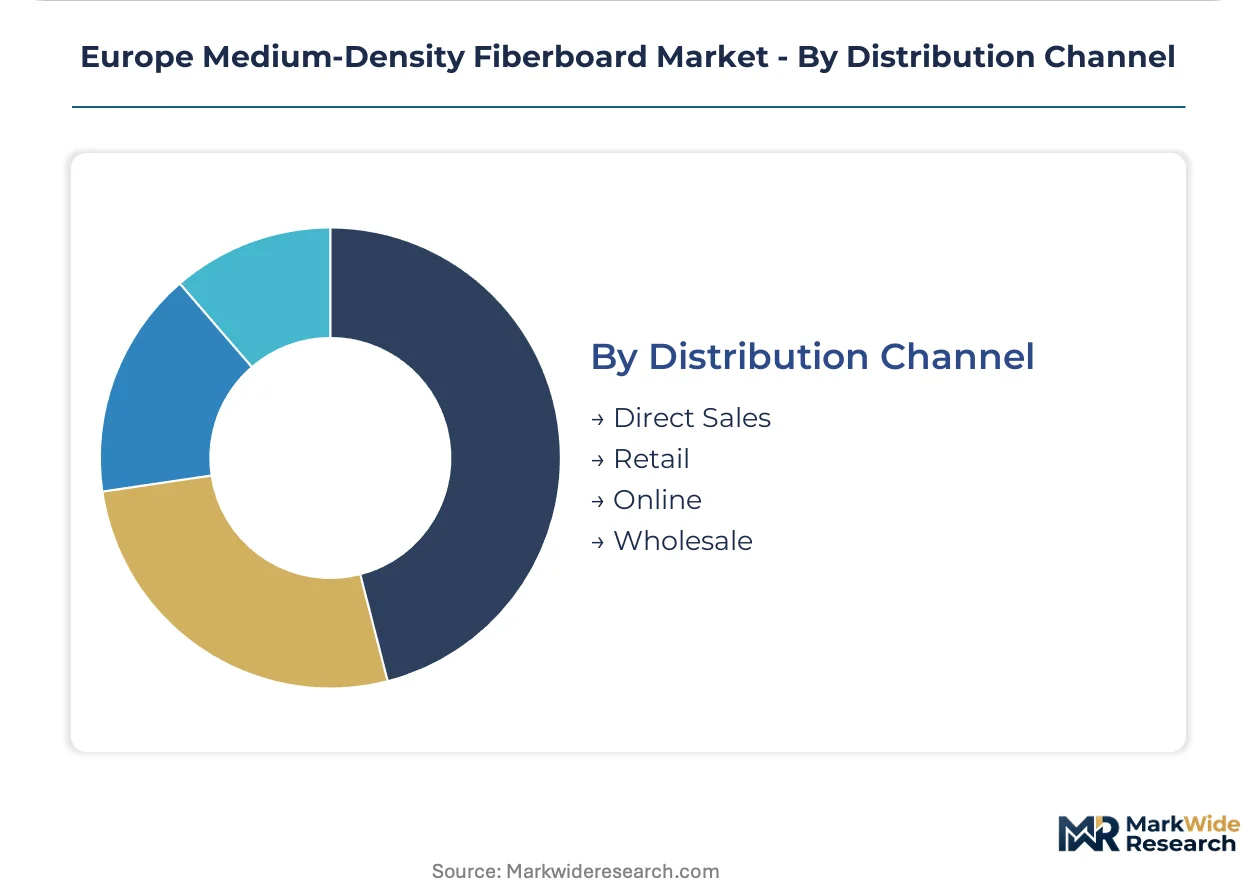
- Direct Sales:Large furniture manufacturers and contract interior specialists source through mill-direct relationships with audit rights and chain-of-custody documentation, displacing spot-market purchasing.
- Retail:Builders merchants and home improvement chains serve renovation contractors and small fabricators with stock-grade availability and cut-to-size services.
- Online:Digital platforms gain traction among small-batch buyers and specialized fabricators seeking rapid price transparency and delivery scheduling.
- Wholesale:Regional distributors maintain inventory buffers for mid-size manufacturers lacking storage infrastructure or credit terms for direct mill procurement.
Direct sales dominate value capture; online channels are climbing the fastest as procurement digitization penetrates smaller fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhineland furniture cluster anchors European MDF consumption, with flat-pack manufacturers in North Rhine-Westphalia driving procurement volumes for export-oriented production. Bavarian cabinetry belts and Polish woodworking districts near Poznań concentrate automated cutting capacity, creating localized demand nodes for uniform-density panel supply.
Germany
Kitchen manufacturers in Bavaria and Baden-Württemberg specify moisture-resistant grades for wet-zone contracts under ECHA REACH formaldehyde reclassification. The EU Green Deal's embodied-carbon tracking mandates now function as bid prerequisites for public-sector interior projects. Cologne and Düsseldorf logistics hubs concentrate lamination subcontractor networks serving Rhineland flat-pack exporters.
Poland
Poznań woodworking districts absorb rising volumes for IKEA-aligned supply chains and bespoke furniture exports to Western Europe. National building-code harmonization with EU Construction Products Regulation accelerates CE marking adoption among mid-size panel fabricators. Lower Silesia and Greater Poland voivodeships host expanding particleboard-to-MDF substitution capacity.
Italy
Lombardy and Veneto furniture districts source high-density overlays for laminate flooring substrates targeting Middle East and North African export markets. CE marking under CPR governs structural declarations for commercial building applications. Brianza's design-driven cabinetry cluster differentiates through specialty surface finishes requiring calibrated fiber density.
France
Île-de-France contract interior specialists procure fire-retardant grades for airport terminal and healthcare facility renovations under EN 13501-1 reaction-to-fire standards. The country's national building regulator enforces stricter emission classes than EU baseline requirements. Auvergne-Rhône-Alpes hosts automotive interior panel fabrication for premium vehicle programs.
Spain
Catalonia and Valencia furniture exporters specify standard-grade panels for cost-competitive retail fixture production serving Latin American markets. ECHA REACH compliance costs disadvantage smaller mills lacking in-house testing laboratories. Basque Country industrial clusters integrate MDF into packaging and tooling applications with shorter certification pathways.
Europe Medium-Density Fiberboard Market Competitive Landscape
Capacity expansion dominates the current landscape as established producers redeploy capital toward low-emission panel grades and continuous press technology. The vendor base concentrates around mid-cap to large manufacturers with captive forestry assets and in-house resin formulation capabilities. Three archetypes define competitive positioning: integrated forest-products conglomerates with upstream fiber control; specialty surface-finish specialists commanding premium cabinetry segments; and regional scale players optimizing logistics proximity to Rhineland and Poznań demand clusters. M&A activity and geographic expansion into Romanian and Bulgarian fiber basins represent the dominant competitive vectors.
Among integrated forest-products conglomerates, EGGER Group and Kronospan exemplify archetypes with upstream fiber security and multi-country production footprints. Pfleiderer Group occupies a position within the specialty tier, differentiated through thin-board expertise and high-end surface technologies. Swiss Krono Group and Sonae Arauco represent regional scale players with logistics-optimized positioning near Central European demand concentrations.
| Leading Market Players |
|---|
| Kastamonu Entegre |
| M. KAINDL GmbH |
| Kronospan |
| Sonae Arauco |
| Finsa |
| EGGER Group |
| Pfleiderer Group |
| Dynea AS |
| Swiss Krono Group |
| Others |
Pricing and Supply Chain Analysis
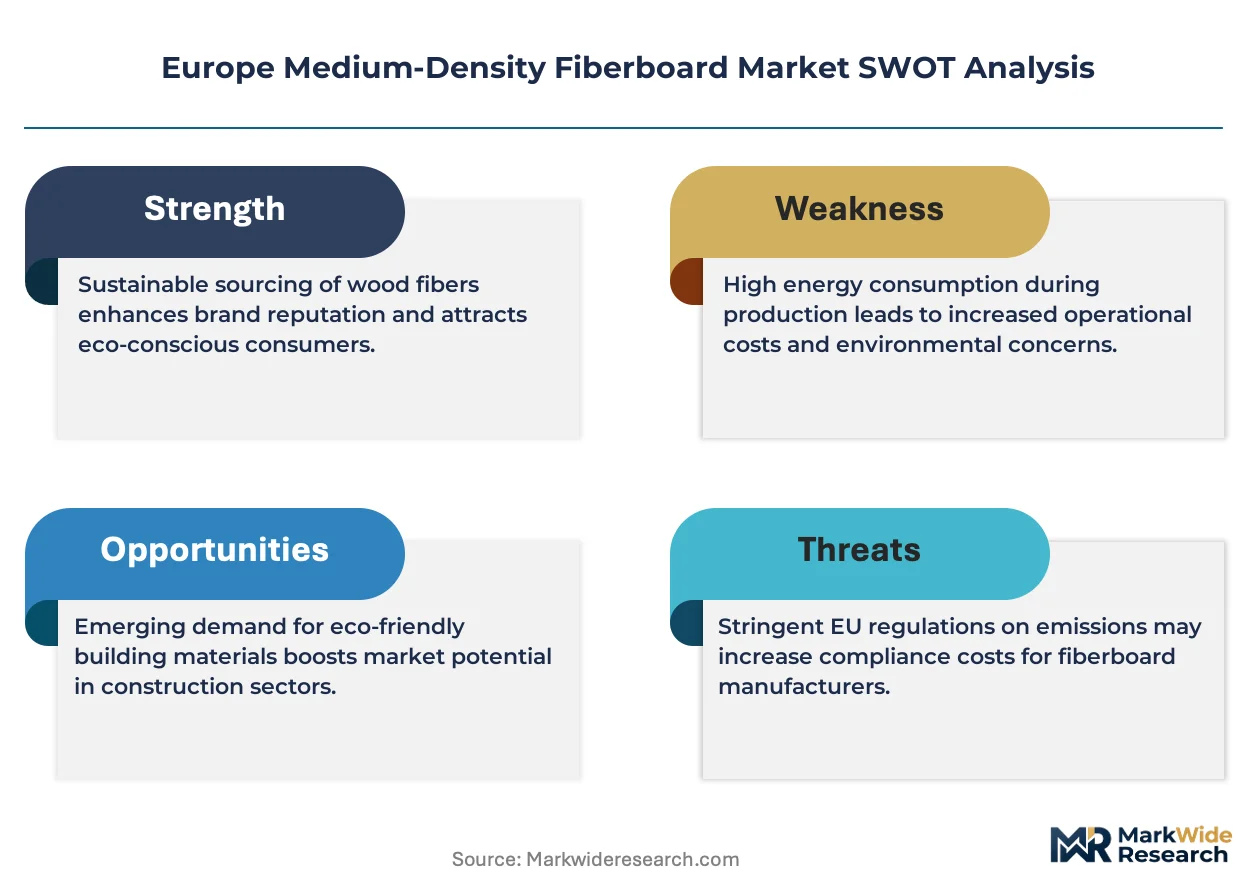
Certification-grade bifurcation between E0.5 low-emission panels and standard E1 grades manifests in divergent margin structures and procurement channel configurations across German and Polish manufacturing basins. Premium-certified supply chains draw from captive resin formulation and in-house testing laboratory infrastructure, while commodity-grade sourcing concentrates through spot-market distributor networks vulnerable to urea-formaldehyde cost volatility.
Pricing Analysis
Input-cost pass-through from petrochemical resin feedstocks compresses margin structures for standard-grade producers lacking captive chemical synthesis capabilities. Three-tier pricing structure across premium certified, standard industrial, and economy spot-market levels differentiates by emission class and fire-reaction certification. Pricing pressure stems from ECHA REACH formaldehyde reclassification compliance investments. Residential renovation contractors exhibit highest price sensitivity; institutional healthcare procurement demonstrates lowest sensitivity due to mandatory certification requirements.
Supply Chain Analysis
Reverse-logistics flows for post-industrial fiber recovery and panel offcut reclamation remain underdeveloped across European production basins, constraining circular-economy cost advantages. Supply concentrates in Germany, Poland, and Austria, with softwood pulp dependencies drawing from Baltic and Nordic forestry assets. Single-source vulnerability concentrates in phenolic resin supply chains tethered to petrochemical refineries. Distribution runs through mill-direct relationships for large furniture manufacturers and wholesale distributor networks for mid-size fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Medium-Density Fiberboard Market functions as a stable compounder anchored by kitchen and bathroom renovation cycles that sustain steady substrate demand regardless of cyclical construction volatility.
For Market Incumbents: Deepen backward integration into captive resin formulation capabilities to defend margin structures against petrochemical cost volatility. Prioritize CE marking testing laboratory accreditation to capture institutional procurement contracts where compliance thresholds exclude smaller competitors. Cross-laminated timber substitution in exposed structural applications represents the priority threat requiring fire-retardant grade diversification.
For New Entrants and Emerging Players: Enter via Romanian and Bulgarian greenfield investments accessing lower-cost Transylvanian fiber assets and underdeveloped lamination subcontractor networks. White-space targets include digital print-ready surface technologies for hospitality fixture short-run production and flexible MDF bending applications with limited supplier competition. Go-to-market angle should emphasize direct mill relationships with audit rights displacing traditional distributor purchasing.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size panel mills lack capital for ECHA REACH compliance infrastructure and in-house certification laboratories. Long-term viability favors integrated forest-products conglomerates with upstream fiber control and multi-country production footprints. Acquisition target archetype: regional scale players with logistics proximity to Rhineland and Poznań demand clusters. Signal to watch: national building-code harmonization accelerating CE marking adoption among previously uncertified fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive urea-formaldehyde and MDI binder production insulates margin structures from petrochemical volatility. |
| CE Marking Testing Laboratory Accreditation | In-house fire-reaction and emission certification unlocks institutional procurement under EN 13501-1 standards. |
| Continuous Press Technology Deployment | Real-time density profiling enables smaller-batch flexible manufacturing for bespoke interior contracts. |
| Fire-Retardant Grade Capacity Expansion | Reaction-to-fire Class B and C certifications access airport terminal and healthcare facility specifications. |
| Geographic Expansion into Romanian Fiber Basins | Transylvanian forestry assets offer lower-cost softwood pulp and greenfield lamination subcontractor development. |
Research Methodology
Bottom-up furniture and cabinetry modeling reconciled against top-down panel production tracking forms the analytical core of this study. Primary interviews with plant managers at German and Polish manufacturing facilities, procurement leads at flat-pack furniture OEMs, distribution channel partners, and technical R&D directors in resin chemistry were combined with secondary validation from ECHA substance evaluation databases, EU Construction Products Regulation harmonization reports, customs and trade data, and SEC filings of listed forest-products conglomerates. Triangulation between demand-side specification behavior and supply-side capacity announcements ensures consistency.
Input-output matrix framing connects end-use application volumes to raw material fiber availability and resin chemistry production capacity across the modeling period. Segmentation dimensions include product type by density and binder chemistry, application by surface finish tolerance, end user by procurement sophistication, and distribution channel by order scale and documentation requirements. CAGRs were derived from fitted growth curves applied to baseline consumption data. Industry-specific forecast inputs encompass kitchen renovation cycle frequency and ECHA REACH implementation timelines.
Inputs from ECHA substance evaluation databases and EU member state building-code harmonization records were available through the study window; gaps in real-time production capacity utilization data introduce uncertainty bands around near-term supply estimates. Forecasts reflect assumptions regarding E0.5 emission class adoption rates and phenolic resin cost trajectories. Practitioners should monitor ECHA substance evaluation updates and national transposition of EU Green Deal procurement mandates for early signals of specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Core Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Global Paperboard Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Graphic Paper Market
Paper Products
Paper Machinery Market
Paper Products
Ceramic Paper Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
White Top Testliner Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Glassine Paper Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
North America Decor Paper Market
Paper Products
Industrial Paper Shredder Machine Market