
 Printing and Writing Papers Market | 2026-2036
Printing and Writing Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Printing and Writing Papers Market Outlook
Capital-intensity divergence between integrated pulp-to-paper producers and merchant converters is rotating competitive advantage toward firms with captive fiber supply. International Paper leverages its North American timberland base to sustain cost parity on uncoated freesheet. Mondi Group anchors European demand through vertically integrated kraft pulp operations. Stora Enso differentiates via bioproduct mill conversions that extend fiber value beyond commodity grades.
Printing and writing papers comprise wood-fiber based sheet products engineered for ink receptivity, dimensional stability, and archival performance, typically manufactured through kraft pulping, bleaching, and Fourdrinier forming to achieve basis weights between 60 and 120 grams per square meter for document reproduction, educational materials, and commercial communication. Uncoated grades dominate volume consumption across office and educational channels where opacity and writability outweigh gloss requirements. Coated and specialty segments concentrate margin pools in commercial printing and premium publishing applications where surface smoothness and color fidelity command price premiums. Recycled fiber integration intensifies as regulatory thresholds for post-consumer content tighten procurement specifications.
The US EPA guides recovered fiber standards under Comprehensive Procurement Guidelines while the EU Ecodesign for Sustainable Products Regulation mandates digital product passports tracing fiber provenance and chemical content. India's BIS certification enforces IS 1848 specifications for writing and printing paper quality, conditioning import access and domestic mill compliance. Stakeholders must monitor how escalating carbon border adjustments and deforestation-free supply chain mandates reshape sourcing economics and regional production allocation decisions.
Market Dynamics
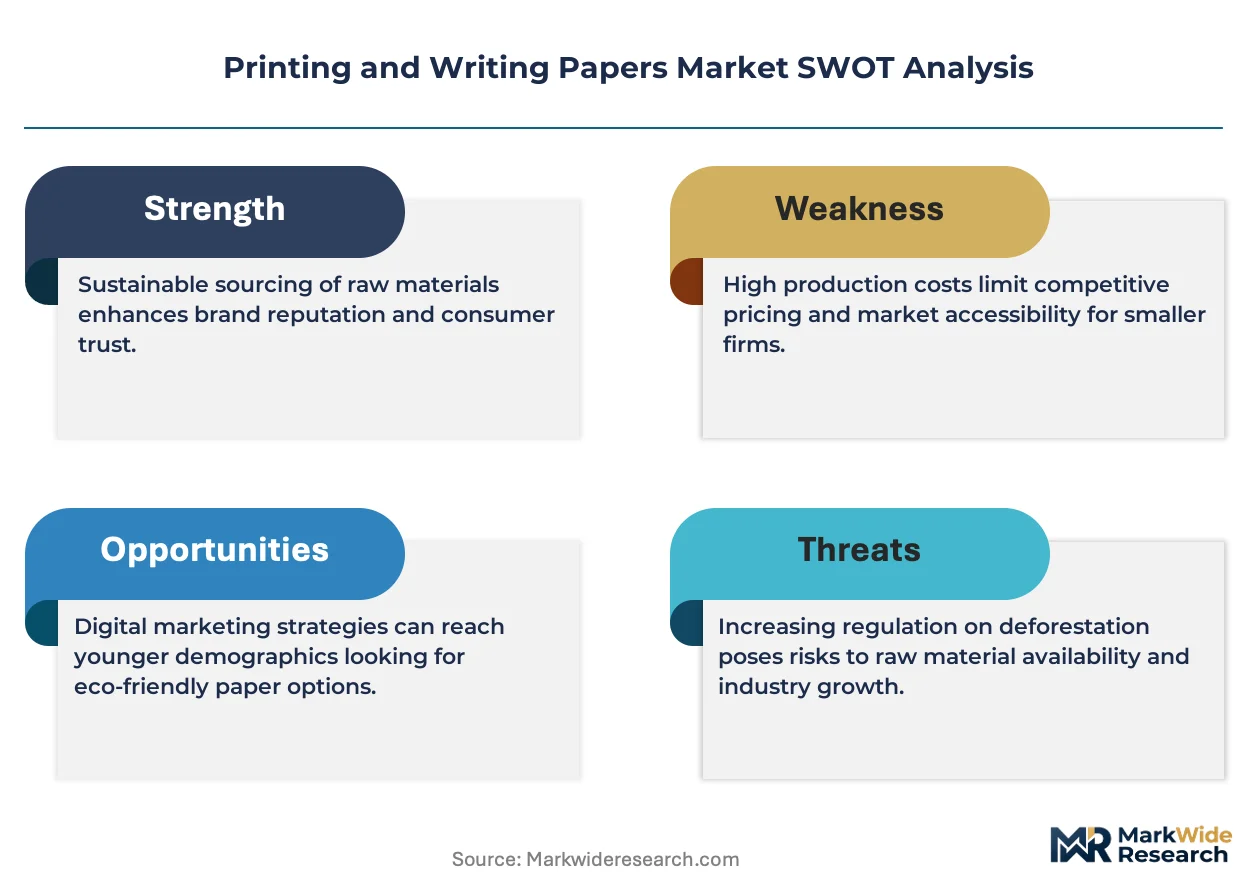
The EU Ecodesign for Sustainable Products Regulation is compressing supply chain margins by mandating digital product passports and deforestation-free fiber provenance, forcing mills to reconfigure sourcing networks and absorb traceability costs.
Growth Catalysts
- India's literacy infrastructure:Government school construction programs sustain bulk procurement of uncoated writing grades for textbook and examination paper production.
- Recycled content mandates:The US EPA's Comprehensive Procurement Guidelines tighten post-consumer fiber thresholds for federal document contracts.
- Bioproduct mill conversions:Kraft pulp integration into packaging and specialty cellulose derivatives extends fiber value capture beyond commodity printing grades.
Market Restraints
- Pulp cost volatility:Hardwood and softwood fiber prices fluctuate with climate-driven timber harvest disruptions in Nordic and North American supply basins.
- Digital substitution:Electronic document workflows and e-learning platforms displace photocopy and workbook consumption in corporate and tertiary education channels.
- Carbon border exposure:The EU's Carbon Border Adjustment Mechanism elevates import costs for mills lacking verified emissions accounting systems.
Strategic Opportunities
- Specialty coating technologies:Inkjet-optimized surface treatments capture premium segments in transactional printing and direct mail applications.
- Rural India distribution:State-level textbook procurement cooperatives offer channel access outside metropolitan paper merchant networks.
- EU circular economy incentives:Ecodesign compliance unlocks preferential positioning in public sector tendering and green public procurement frameworks.
Industry Challenges
- Digital passport implementation:Fiber traceability systems require capital deployment and supplier audit protocols that strain mid-scale mill balance sheets.
- Skilled pulping engineer scarcity:Kraft process expertise concentrates among aging workforces in Finland and Canada, constraining operational expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printing and Writing Papers Market |
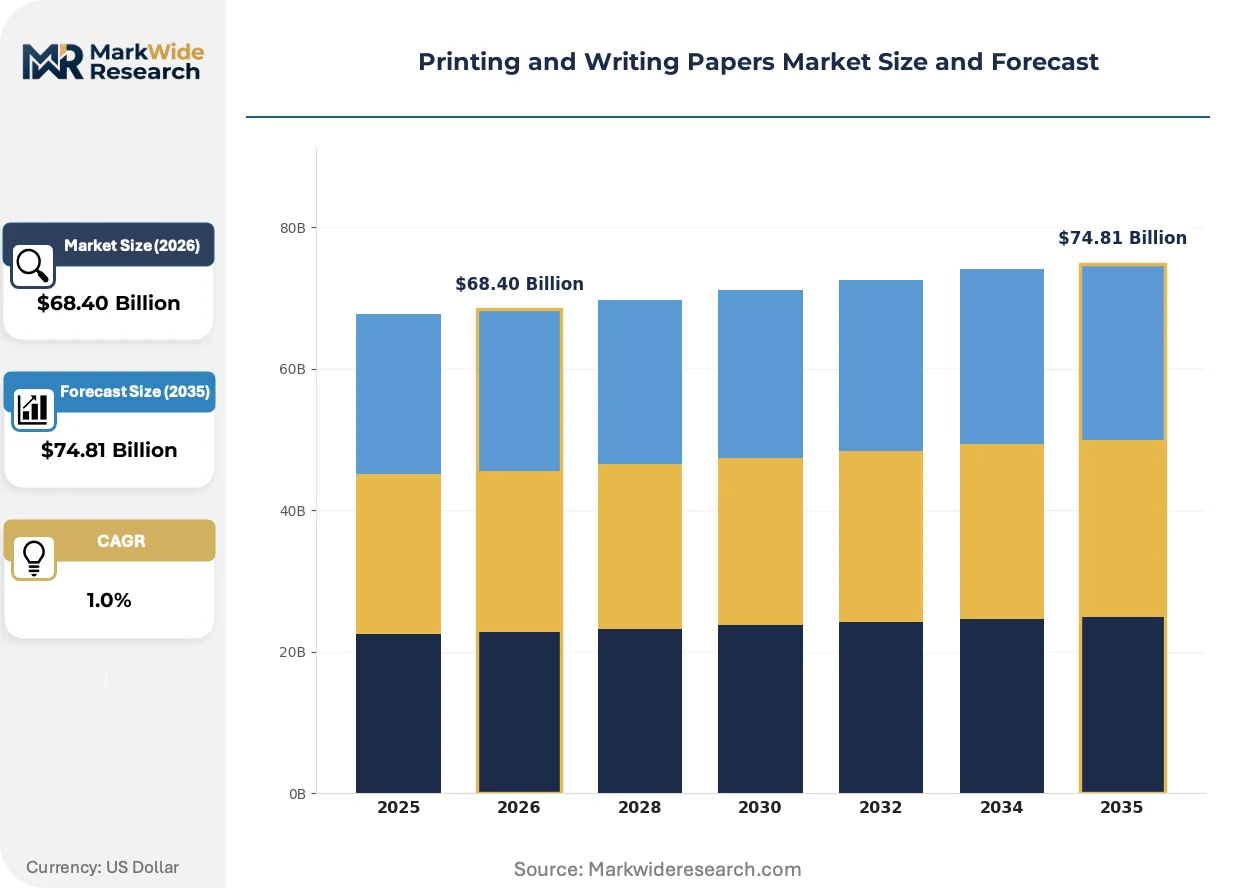
| Market Size in 2026 | $68.40 Billion |
| Market Size in 2035 | $74.81 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: A4, A3, Letter, Legal Grade: Uncoated, Coated, Recycled, Specialty End User: Publishing, Education, Office Supplies, Commercial Printing Packaging Type: Reams, Rolls, Packs, Pallets |
| Companies Covered | International Paper, WestRock, Domtar, Mondi Group, Stora Enso, Nippon Paper Industries, Oji Holdings, Asia Pulp & Paper, Sappi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printing and Writing Papers Market Strategic Shifts
Active transformation in this market centers on regulatory compliance technology, fiber chemistry advancement, and procurement model restructuring that together redefine competitive viability.
Precision coating deposition technology is miniaturizing. Nanoscale pigment distribution systems enable targeted surface porosity control for high-speed inkjet compatibility. Commercial printers in Germany and Japan are adopting these substrates for variable-data direct mail. The technology is miniaturizing equipment footprints and reducing coating raw material waste rates.
The EU Ecodesign for Sustainable Products Regulation mandates digital product passports tracing fiber provenance, chemical content, and recyclability credentials across European supply chains. Mills must deploy blockchain or centralized database infrastructure to maintain market access. Uncoated freesheet producers serving educational and government channels face the steepest compliance cost curves.
Consolidated procurement consortia are displacing fragmented merchant purchasing. Large educational publishers and federal print services in India and the United States are negotiating multi-year volume contracts directly with integrated pulp-to-paper producers. This pattern concentrates buyer power and compresses distributor margins in standard-grade segments.
Printing and Writing Papers Market Segmentation
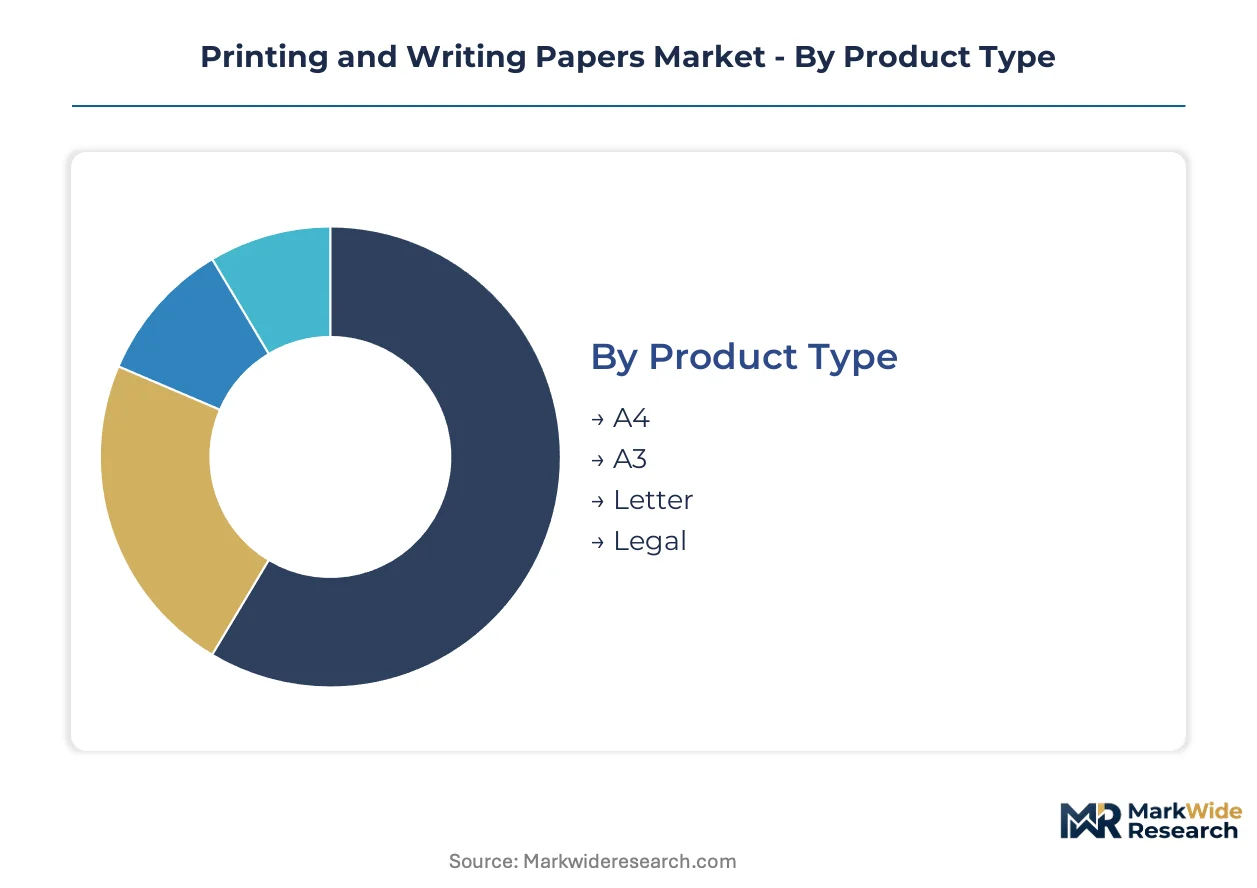
Segmentation in printing and writing papers reveals how procurement channels, fiber specifications, and end-use durability requirements fragment demand across distinct margin tiers. Channel alignment between merchant distributors and direct mill contracts varies sharply by product format and volume scale.
Product Type:
A4 flows predominantly through office supply retailers and educational procurement cooperatives, while larger sheet sizes concentrate in commercial print channels with specialized finishing equipment.
- A4:Standard 210mm x 297mm dimension dominates office copying and desktop printing with basis weights of 70-80 gsm. Government textbook tenders in India and federal document contracts in the United States sustain bulk procurement through direct mill relationships.
- A3:Double-size format serves architectural reproduction, spreadsheet presentation, and poster applications requiring enhanced dimensional stability. German commercial printers and Japanese in-house corporate print centers specify A3 for technical documentation where scaling fidelity matters.
- Letter:US-dominant 8.5 x 11 inch specification aligns with North American office equipment calibration and filing system standards. Merchant distributors in the United States stock Letter as the default uncoated freesheet format for small-business replenishment cycles.
- Legal:Elongated 8.5 x 14 inch format persists in contract documentation, court filings, and real estate transaction records. Law firms and title insurance processors in the United States maintain steady demand despite electronic signature adoption.
A4 dominates installed base. A3 is where expansion concentrates.
Grade:
Cost tier stratification separates commodity uncoated volumes from premium coated and specialty segments with divergent fiber chemistry and surface engineering requirements.
- Uncoated:Filler-loaded woodfree sheet achieves opacity through calcium carbonate loading rather than surface treatment. State education departments in India procure uncoated grades for examination booklets and primary school workbooks where writability and cost efficiency outweigh print fidelity.
- Coated:Clay or calcium carbonate surface layers deliver gloss and ink holdout for commercial catalogs and annual reports. High-end magazine publishers in Germany and Japan specify coated grades for four-color reproduction where color gamut range determines vendor selection.
- Recycled:Post-consumer fiber integration ranging from 30% to 100% content responds to EPA Comprehensive Procurement Guidelines and EU green public procurement thresholds. Federal agencies in the United States face mandatory recycled content floors for contract eligibility.
- Specialty:Security papers with watermark authentication, archival grades with alkaline buffering, and inkjet-optimized porosity control serve niche applications. Banknote substrate producers and fine art reproduction houses in Switzerland and Japan command price premiums for certified longevity specifications.
Uncoated commands volume leadership. Specialty is climbing the fastest.
End User:
Customer type determines order scale, specification tolerance, and contract duration with integrated producers versus merchant intermediaries.
- Publishing:Periodical and book publishers negotiate annual volume contracts with basis weight and brightness tolerances specified to press configuration. Religious text publishers in India and coffee-table book producers in Germany sustain coated sheet demand despite digital circulation erosion.
- Education:Government school construction programs and literacy initiatives generate predictable bulk demand for uncoated writing grades. State textbook corporations in India tender multi-year supply agreements that absorb significant uncoated freesheet mill capacity.
- Office Supplies:Corporate replenishment and small-business retail purchase through distributors favors ream-wrapped A4 and Letter formats. Staples and independent stationers in the United States manage inventory turns against digital substitution headwinds.
- Commercial Printing:Print-for-pay operations serving direct mail, financial statements, and marketing collateral require substrate consistency across high-speed inkjet and offset equipment. Transactional printers in Germany and variable-data specialists in Japan specify inkjet-optimized surface treatments.
Education anchors volume procurement. Commercial printing is gaining share fastest.
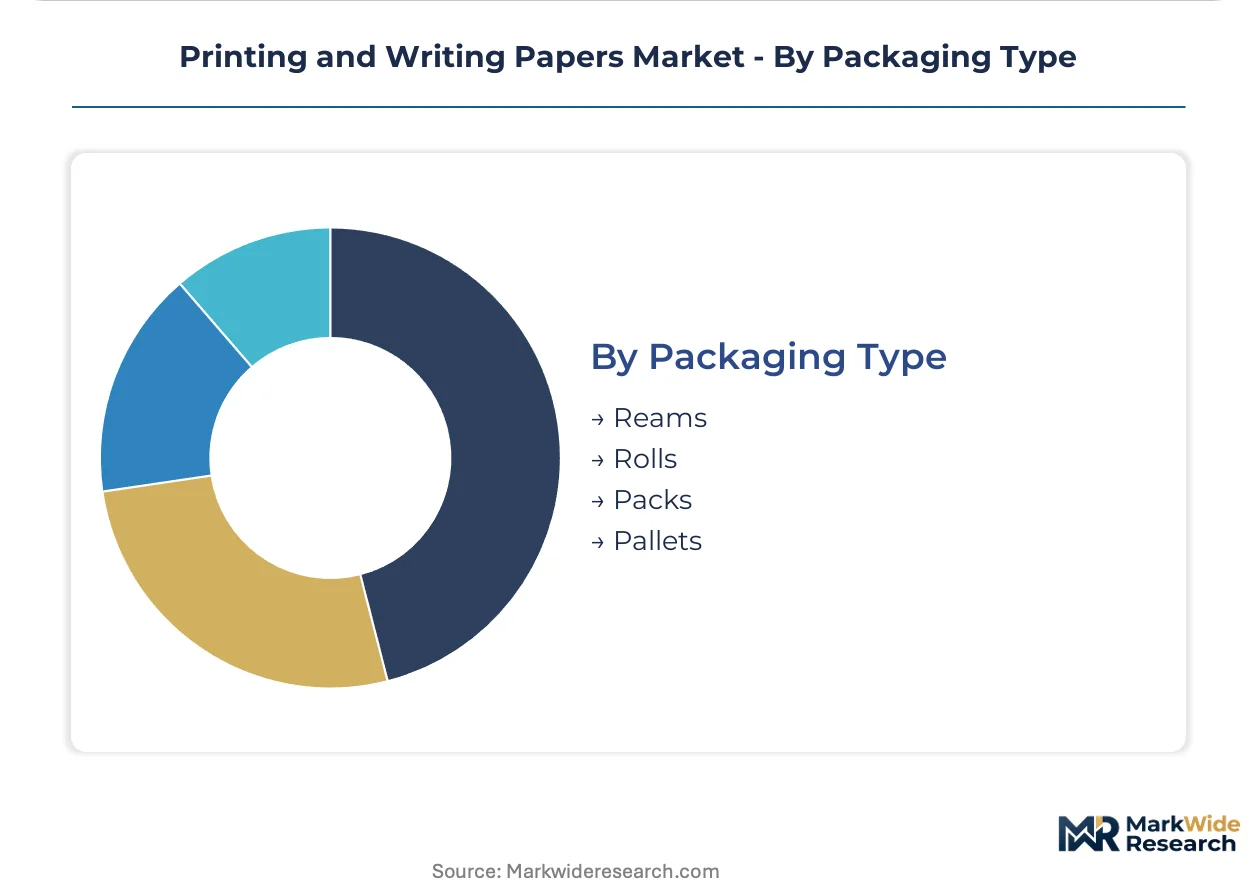
Packaging Type:
Volume scale and handling automation separate retail-ready ream packs from industrial roll formats feeding continuous web presses.
- Reams:500-sheet wrapped units serve office supply retail and educational institutional purchasing with palletized logistics efficiency. Merchant distributors in the United States and India manage ream inventory against seasonal academic procurement cycles.
- Rolls:Continuous web formats feed high-speed offset and inkjet presses in commercial printing and newspaper insert operations. Large-format commercial printers in Germany and Japan specify roll diameters and core dimensions to press manufacturer tolerances.
- Packs:Smaller 100-250 sheet configurations target home office and small-business segments with lower entry price points. E-commerce fulfillment channels in the United States are expanding pack format assortment for remote worker replenishment.
- Pallets:Bulk unitization for direct mill-to-printer logistics bypasses distributor handling for large-volume contract customers. Integrated pulp-to-paper producers serving Indian government tenders and US federal print services prefer palletized delivery to warehouse automation systems.
Reams dominate retail accessibility. Rolls is where operational efficiency concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premiums for coated specialty grades, while Indian mills compete on volume for uncoated educational paper tenders. This asymmetry shapes capital allocation toward traceability investments in Europe versus capacity expansion in South Asia.
United States
Federal document procurement through the EPA's Comprehensive Procurement Guidelines sustains demand for recycled-content uncoated freesheet. The EPA mandates minimum post-consumer fiber thresholds for government contracts. Georgia-Pacific and International Paper operate integrated mills in the Southeast, serving textbook publishers and federal print services with direct mill contracts.
Germany
Commercial printers in Baden-Württemberg and Bavaria specify inkjet-optimized coated grades for variable-data direct mail campaigns. The EU Ecodesign for Sustainable Products Regulation requires digital product passports tracing fiber provenance across supply chains. Heidelberg and Mannheim host specialized finishing operations that demand consistent substrate calibration for high-speed presses.
India
State textbook corporations in Maharashtra and Tamil Nadu tender multi-year supply agreements for uncoated writing grades under government literacy programs. BIS certification enforces IS 1848 quality specifications that condition import access and domestic mill compliance. Tamil Nadu Paper Mills and West Coast Paper Mills serve these procurement channels from southern production clusters.
Japan
Premium publishing houses in Tokyo and Osaka sustain demand for coated art paper and archival-grade specialties despite digital circulation erosion. METI guidelines encourage sustainable fiber sourcing and carbon accounting transparency. Hokkaido pulp operations supply northern mills with softwood kraft fiber for high-brightness publication grades.
Brazil
Eucalyptus pulp integration supports competitive uncoated freesheet production for Latin American educational markets. ANVISA oversees chemical content standards in paper products for consumer safety. São Paulo state hosts merchant converter networks that distribute standard grades across Mercosur markets.
Printing and Writing Papers Market Competitive Environment
Concentration sits with integrated pulp-to-paper producers possessing captive fiber supply. The vendor base stratifies across three tiers: multinational integrated producers with timberland assets, regional specialty converters serving niche applications, and state-affiliated mills anchored to domestic procurement programs. Dominant competitive moves include bioproduct mill conversions extending fiber value beyond commodity grades, and direct contracting with large educational publishers bypassing traditional merchant channels.
Within the integrated producer tier, International Paper exemplifies North American timberland-backed cost parity on uncoated freesheet. Mondi Group anchors European positioning through kraft pulp operations serving packaging and specialty cellulose derivatives. Stora Enso occupies a position in Nordic bioproduct diversification, converting commodity paper capacity toward higher-value fiber applications.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Domtar |
| Mondi Group |
| Stora Enso |
| Nippon Paper Industries |
| Oji Holdings |
| Asia Pulp & Paper |
| Sappi |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Nordic and North American kraft pulp mills shapes both supply concentration and price floors for uncoated freesheet, as integrated producers with captive timberland sustain cost parity while merchant converters absorb fiber volatility through contract terms.
Pricing Analysis
Configured-to-order specialty grades command spreads of 40-60 percent above standard uncoated freesheet baselines, with inkjet-optimized surface treatments and archival certifications anchoring premium tiers. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes, with federal education procurement in India and the United States exhibiting highest price sensitivity due to bulk tender mechanics. Pricing pressure stems from carbon border adjustment exposure elevating import costs for non-compliant mills. Commercial printers in Germany and Japan show lowest price sensitivity, prioritizing substrate consistency over unit cost.
Supply Chain Analysis
Finland and Sweden anchor high-brightness kraft pulp production for European publication grades, while Brazil and Indonesia feed eucalyptus and acacia fiber into Asian uncoated freesheet mills. Hardwood and softwood pulp draws from climate-vulnerable Nordic and North American supply basins, creating raw material dependencies. Single-source vulnerability concentrates in aged pulping engineering expertise across Finnish and Canadian workforces. Distribution runs through consolidated procurement consortia displacing fragmented merchant channels for large-volume educational and government contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as digital substitution and regulatory compliance bifurcate demand between commodity volume and premium specialty niches, creating distinct competitive arenas for differentiated positioning.
For Market Incumbents: Consolidate fiber supply security through backward integration into timberland assets or long-term pulp offtake agreements with Nordic and South American suppliers. Lock in multi-year direct contracts with Indian state textbook corporations and US federal print services to defend against merchant channel compression. Prioritize Ecodesign digital passport infrastructure investment to maintain EU market access against traceability mandates. For New Entrants and Emerging Players: Differentiate on security paper and archival-grade specialties where certification barriers limit competition and price premiums sustain niche margins. Target rural India distribution gaps outside metropolitan merchant networks through state-level textbook procurement cooperatives. Pursue inkjet-optimized coating technology licensing from German and Japanese equipment specialists as go-to-market anchor. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pulp-to-paper producers with captive fiber supply and long-term government education contracts. Five-to-ten year viability favors mills with bioproduct diversification pathways extending fiber value beyond commodity grades. Monitor EU Carbon Border Adjustment Mechanism implementation pace as inflection signal for regional production cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Bioproduct Mill Conversion | Stora Enso's Finnish operations extend kraft pulp into packaging and specialty cellulose derivatives beyond commodity grades. |
| Digital Product Passport Deployment | EU Ecodesign compliance unlocks preferential positioning in European public sector tendering and green procurement frameworks. |
| Direct Mill Contracting | International Paper bypasses distributor margins through direct relationships with US federal print services and textbook publishers. |
| Inkjet-Optimized Coating Investment | German commercial printers adopt nanoscale pigment distribution systems for variable-data direct mail applications. |
| Rural Distribution Channel Development | Tamil Nadu Paper Mills accesses state textbook tenders outside metropolitan merchant networks through procurement cooperatives. |
Study Parameters
A standing panel of kraft mill operations directors, educational procurement officers at Indian state textbook corporations, commercial print production managers in Germany and Japan, pulp procurement leads at integrated producers, and EU regulatory compliance specialists provided ongoing calibration across primary interviews and secondary validation. Trade data from customs authorities, EPA Comprehensive Procurement Guidelines documentation, BIS certification records, EU Ecodesign regulatory filings, and industry association statistics anchored bottom-up and top-down triangulation.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation modeling across product format, fiber grade, end-use channel, and packaging type dimensions. CAGRs derived from trend extrapolation adjusted for digital substitution rates, regulatory compliance cost curves, and fiber price volatility assumptions. Forecast inputs incorporated literacy program budget trajectories in India, federal document procurement thresholds in the United States, and carbon border adjustment implementation timelines in Europe.
The analysis sits within stated boundaries; outcomes outside sustained government education spending, stable pulp fiber supply basins, or delayed regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding substitution elasticity, compliance cost absorption capacity, and procurement contract renewal patterns. Recalibration cycles align with material shifts in EU Ecodesign implementation, Indian literacy infrastructure budgets, and Nordic timber harvest disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Coating Materials Market
Paper Products
Global Paperboard Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Compressed Fiberboard Market
Paper Products
Metallized Paper Market
Paper Products
Fluff Pulp Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
White Line Chipboard Market
Paper Products
North America Medium-Density Fiberboard Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Chemical Cellulose Market
Paper Products
Reprographic Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Middle-East and Africa Paper and Paperboard Market