
 Pulp and Paper Market | 2026-2036
Pulp and Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp and Paper Market Intelligence
The displacement of single-use plastics in food service and consumer goods packaging is consolidating demand for fiber-based alternatives. Stora Enso specializes in developing renewable packaging solutions to address this market shift. International Paper leverages its vast scale in North American containerboard production for the logistics sector. Concurrently, Suzano dominates the global supply of eucalyptus pulp, a critical raw material for tissue and specialty paper grades.
Pulp and paper manufacturing involves the chemical or mechanical separation of cellulosic fibers from sources like wood or recycled paper. These processed fibers are formed into sheets, providing essential materials for communication, packaging, and hygiene products. The packaging paper application, driven by e-commerce, exhibits stronger growth than the mature printing paper segment. The Kraft process remains dominant for strength, but demand for recycled pulp is increasing due to corporate sourcing mandates.
Regulations like the EU's Corporate Sustainability Reporting Directive (CSRD) and China's national GB standards for product quality impact mill operations. These frameworks mandate stricter emissions controls and promote the use of certified, sustainable fiber sources. Future profitability will depend on mill energy efficiency, secure access to low-cost fiber, and continued innovation in plastic-replacement specialty papers.
Market Dynamics
The primary structural force shaping the market is the regulatory and consumer-driven substitution of single-use plastics. This global shift, amplified by frameworks like the EU Green Deal, is fundamentally reorienting capital investment and innovation toward fiber-based packaging solutions.
Growth Catalysts
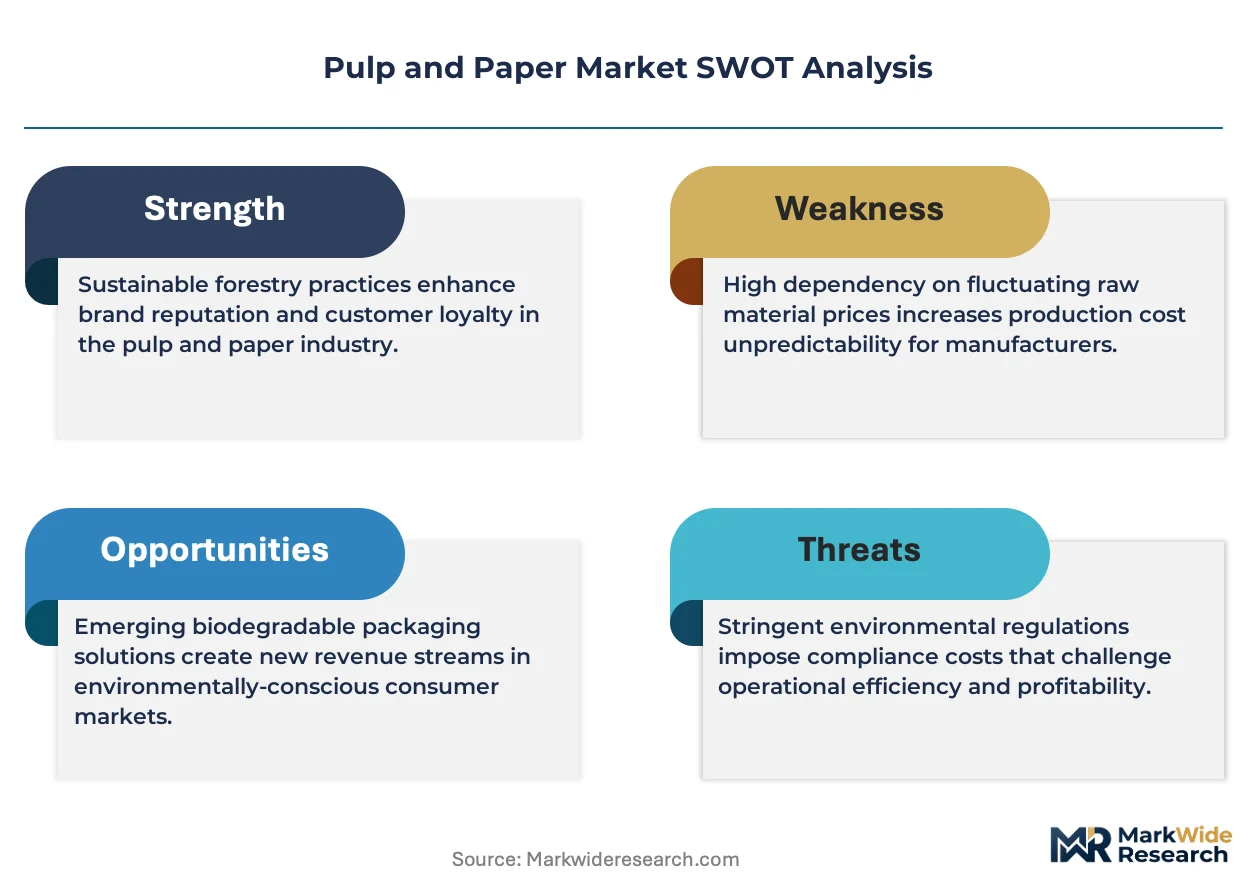
- Sustainable Sourcing Mandates:Regulations such as the EU's Corporate Sustainability Reporting Directive (CSRD) compel companies to disclose supply chain impacts, boosting demand for certified, sustainably sourced paper and pulp products.
- E-commerce Expansion:The logistics sector's need for protective packaging materials, particularly corrugated and containerboard, is a significant demand driver, with concentration in China's manufacturing and export hubs.
- Food-Grade Innovations:Development of advanced barrier coatings for paperboard enables its use in direct food contact applications, creating viable, recyclable alternatives to plastic containers for fresh and frozen foods.
Market Restraints
- Input Cost Volatility:Mill profitability is sensitive to fluctuations in the price of key inputs, including wood fiber, recycled paper, and energy, which are influenced by global logistics and regional environmental policies.
- High Capital Intensity:The construction of new, efficient pulp and paper mills or the retrofitting of older facilities with modern, low-emission technology requires substantial long-term capital investment, creating high barriers to entry.
- Technical Limitations:In certain high-performance packaging segments, fiber-based materials still struggle to match the barrier properties, transparency, and formability of multi-layer flexible plastics, limiting substitution.
Strategic Opportunities
- Molded Fiber Applications:Molded pulp presents a significant opportunity to replace expanded polystyrene (EPS) and thermoformed plastics in protective packaging for consumer electronics, cosmetics, and medical devices.
- Emerging Market Penetration:Southeast Asian and Latin American markets offer considerable growth potential as rising disposable incomes and developing e-commerce infrastructure increase the consumption of packaged goods.
- Smart Packaging Integration:Incorporating technologies like RFID and QR codes into paperboard packaging creates new value streams in supply chain management, anti-counterfeiting, and interactive consumer marketing.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers must navigate a fragmented landscape of national and regional regulations, including China's GB standards and EU food contact material rules, which increases testing and compliance costs.
- Energy and Water Management:The industry's high consumption of energy and water poses a persistent operational challenge, particularly in regions facing stricter environmental controls, carbon pricing, or water scarcity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp and Paper Market |
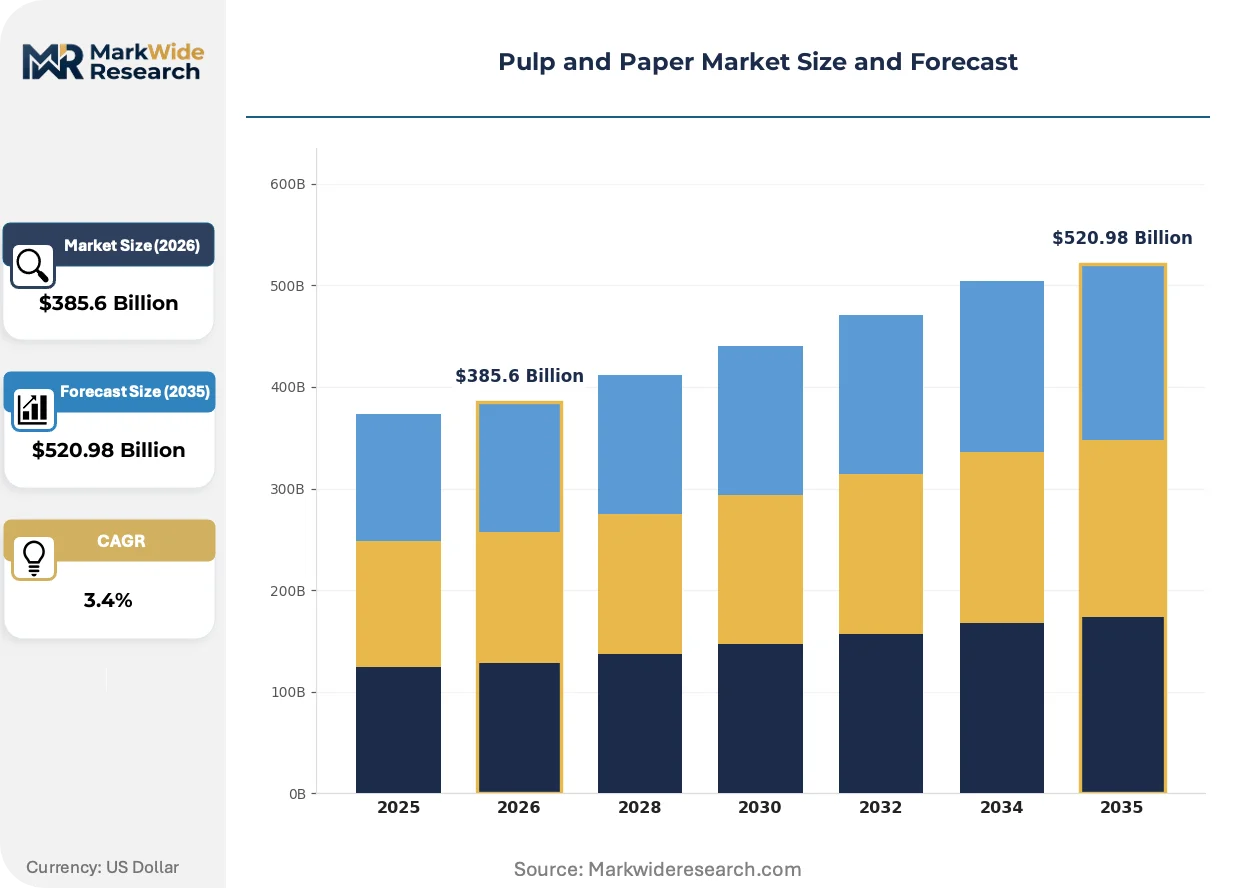
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $520.98 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Pulp, Chemical Pulp, Recycled Pulp, Cotton Linter Pulp Application: Printing Paper, Packaging Paper, Tissue Paper, Specialty Paper Production Technology: Kraft Process, Sulfite Process, Thermomechanical, Chemi-Thermomechanical End User Industry: Publishing, Consumer Goods, Hygiene Products, Industrial Packaging |
| Companies Covered | UPM, WestRock, International Paper, Nine Dragons Paper Holdings, Mondi, Suzano, Oji Holdings, Smurfit Kappa, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp and Paper Market Strategic Shifts & Innovations
A fundamental pivot from bulk commodity production toward specialized, functional materials defines the current innovation cycle. This transition is driven by the need to create viable, high-performance replacements for plastics in demanding packaging and industrial applications, pushing research beyond traditional paper grades.
Lignin valorization technology extracts and refines lignin, a natural polymer co-product of the pulping process, for use in binders, resins, and carbon fiber precursors. Chemical and specialty material producers are adopting this circular economy approach to create new revenue streams from a former waste product. This innovation is rewriting the economic model of the biorefinery, transforming pulp mills into multi-product chemical platforms.
China's national dual carbon goals and stringent GB standards are mandating significant upgrades in mill energy efficiency and emissions control. This policy framework forces investment in black liquor gasification and advanced wastewater treatment systems, increasing operational expenditures for compliance. Domestic Chinese producers are most affected, facing consolidation pressure as smaller, less efficient mills are forced to close or be acquired by larger competitors.
Major consumer packaged goods and e-commerce companies are implementing strict corporate mandates for minimum recycled content in their packaging. This sourcing behavior elevates the strategic importance of securing access to high-quality recovered paper streams, moving procurement away from spot markets toward long-term supply agreements. The trend is most visible in North America and Europe, where brand owners use recycled content claims as a key marketing differentiator.
Pulp and Paper Market Segmentation
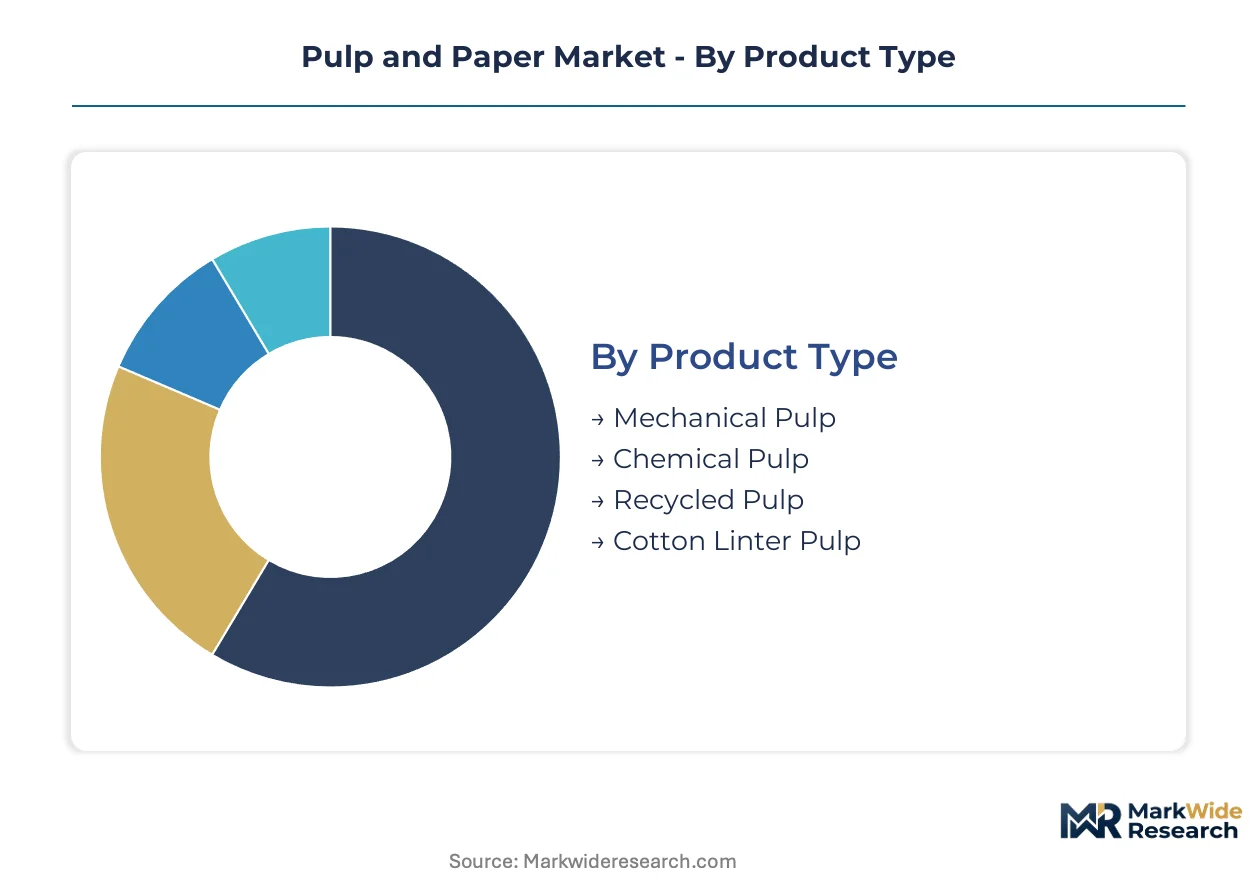
Understanding the distinct segments within the Pulp and Paper market clarifies the diverse material requirements and evolving end-use applications. This granular analysis reveals where innovation is most concentrated and where established production methods continue to provide foundational volumes for the global economy.
Product Type:
The product type segmentation highlights the spectrum from highly customized, specialized fibers to standardized, bulk pulp commodities.
- Chemical Pulp:Produced by chemically separating cellulose fibers from wood, this pulp offers high strength and purity. Demand is significant in packaging and printing applications, with production concentrated in regions with abundant forest resources like the Nordic countries and Brazil.
- Recycled Pulp:Derived from recovered paper and paperboard, this segment focuses on circular economy principles and resource efficiency. Corporate sourcing mandates drive its demand in North America and Europe for consumer packaged goods.
- Mechanical Pulp:Produced by mechanically grinding wood fibers, this pulp yields high opacity and bulk but lower strength compared to chemical pulps. It finds use primarily in newsprint and lower-grade printing papers.
- Cotton Linter Pulp:A high-purity cellulose fiber derived from cotton seed hairs, this specialty pulp serves niche markets requiring exceptional strength and absorbency. It is used in currency paper, medical products, and filter media.
Most installed capacity flows through Chemical Pulp. Expansion is steepest in Recycled Pulp.
Application:
Market application segments delineate the functional roles of paper and pulp products, reflecting varying performance needs and consumer trends.
- Packaging Paper:This category includes corrugated, containerboard, and carton board materials designed for protective and transport packaging. E-commerce expansion drives significant demand, particularly within China's manufacturing and export hubs.
- Specialty Paper:Engineered for specific functional properties, this segment encompasses barrier coatings for food contact and advanced materials for industrial uses. Innovation here focuses on viable plastic-replacement solutions.
- Printing Paper:Comprising graphic papers for magazines, catalogs, and office use, this segment faces maturity and declining volumes due to digital media substitution. It represents a foundational, though contracting, application.
- Tissue Paper:This segment includes absorbent papers for hygiene products like facial tissues, toilet paper, and paper towels. It relies heavily on virgin eucalyptus pulp for softness and strength.
Demand for Packaging Paper drives significant volume, while Specialty Paper exhibits strong growth potential.
Production Technology:
Production technology segments illustrate the diverse methods employed to extract and process cellulose fibers, each yielding different pulp characteristics and environmental footprints.
- Kraft Process:This chemical pulping method, using an alkaline solution, is dominant globally for producing strong, unbleached pulp. It is favored for containerboard and other packaging grades due to its inherent strength.
- Thermomechanical:This mechanical pulping process combines heat and mechanical refining to separate wood fibers. It offers high yield and good optical properties, finding applications in newsprint and coated papers.
- Sulfite Process:An older chemical pulping method using an acidic solution, the sulfite process produces bright, easily bleachable pulp. It serves specialty paper markets requiring specific fiber characteristics.
- Chemi-Thermomechanical:This hybrid process combines chemical pre-treatment with mechanical refining, balancing yield and strength. It is used for printing and packaging grades where a balance of properties is required.
The Kraft Process remains foundational for large-scale production, with Thermomechanical technologies gaining traction for specific fiber properties.
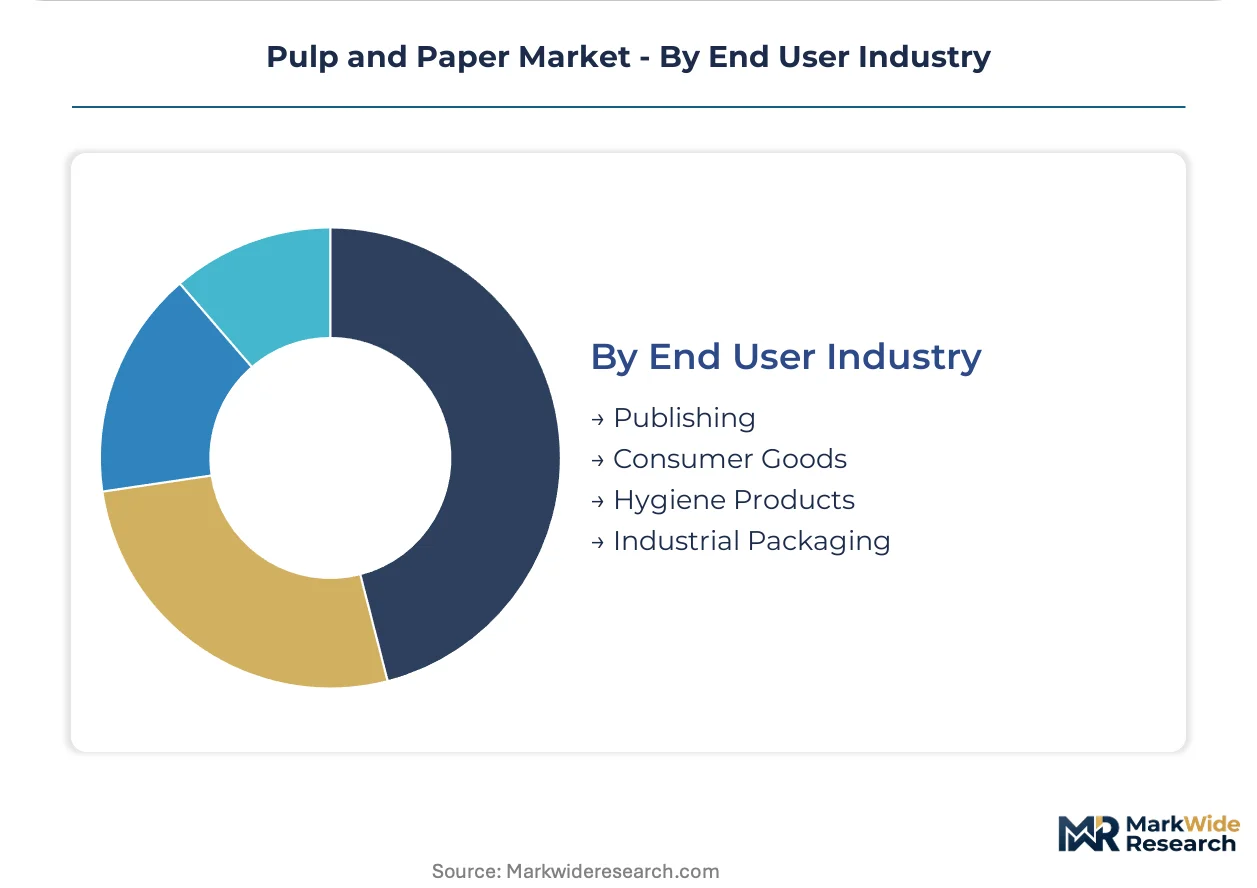
End User Industry:
End-user industry segments highlight how different sectors consume pulp and paper products, revealing distinct demand drivers and regulatory influences.
- Industrial Packaging:This sector utilizes corrugated and containerboard materials for shipping and logistics, particularly for e-commerce fulfillment. Growth in this segment is pronounced, driven by global trade and online retail.
- Consumer Goods:This broad segment includes packaging for food, beverages, and household products, alongside hygiene items. Regulatory and consumer-driven substitution of single-use plastics influences material choices here.
- Publishing:This industry relies on printing paper for books, newspapers, and magazines. Digitalization continues to impact demand, leading to a contraction in traditional print volumes.
- Hygiene Products:This segment encompasses tissue papers for personal care and sanitary applications. It demands soft, absorbent, and often high-purity pulp, with Suzano dominating eucalyptus pulp supply for this use.
The Industrial Packaging sector exhibits the most dynamic expansion, while Publishing represents a mature market facing structural shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal manufacturing and export hubs concentrate significant demand for packaging paper, particularly corrugated and containerboard materials. This concentration drives regional investment in pulp and paper production, influenced by e-commerce expansion and domestic regulatory frameworks. The global market shows diverse growth patterns, reflecting varying economic development and environmental policy adoption across key geographies.
China
Demand for industrial packaging and e-commerce fulfillment materials drives the Chinese market. The country's national GB standards and dual carbon goals mandate significant upgrades in mill energy efficiency. Manufacturing and export hubs along the coast, such as the Yangtze River Delta, continue to concentrate corrugated and containerboard production.
United States
The logistics sector's need for protective packaging materials, especially containerboard, fuels market activity in the United States. Corporate sourcing mandates for minimum recycled content influence procurement strategies. North American containerboard production centers, particularly in the Southeast, support vast e-commerce fulfillment operations.
Brazil
Brazil serves as a critical global supplier of virgin eucalyptus pulp, essential for tissue and specialty paper grades. The country's environmental protection regulations influence sustainable forestry practices. Pulp mills in the Amazon basin and southern states provide foundational raw materials for international markets.
Germany
The German market emphasizes circular economy principles and sustainable packaging alternatives for consumer goods. Regulations such as the EU Green Deal and CSRD compel companies to adopt fiber-based solutions. Industrial centers in North Rhine-Westphalia and Bavaria focus on developing and utilizing advanced barrier-coated paperboard.
India
Rising disposable incomes and a rapidly developing e-commerce infrastructure contribute to the growing demand for packaged goods in India. The Bureau of Indian Standards (BIS) influences product quality and material specifications. Major urban centers like Mumbai and Delhi show expanding consumption of various paper and pulp products.
Pulp and Paper Market Key Industry Players
Global majors compete with regional champions across fiber sourcing and specialized packaging solutions, creating a tiered market structure. The industry includes integrated pulp producers focused on scale, specialized packaging innovators developing plastic-replacement materials, and commodity paper manufacturers. Strategic partnerships for technology sharing and capacity expansion remain dominant competitive moves.
At the scale-driven end, International Paper exemplifies vast North American containerboard production for the logistics sector. Suzano anchors the global supply of eucalyptus pulp, a critical raw material for tissue and specialty paper grades. Stora Enso occupies a position among innovators, specializing in renewable packaging solutions to address market shifts away from single-use plastics.
| Leading Market Players |
|---|
| UPM |
| WestRock |
| International Paper |
| Nine Dragons Paper Holdings |
| Mondi |
| Suzano |
| Oji Holdings |
| Smurfit Kappa |
| Stora Enso |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's emphasis on circular economy principles gates access to qualified supply and premium-tier pricing for fiber-based solutions, particularly for packaging applications.
Pricing Analysis
Input cost volatility for wood fiber and energy directly impacts mill profitability, creating significant pass-through pressure on product pricing. The dominant pricing model for bulk pulp and commodity paper grades remains transactional and spot-market driven, while specialized packaging solutions often leverage contract-based long-term offtake agreements. Price differentiation stems from fiber certification levels, such as FSC or PEFC, and the advanced performance properties of specialty papers like barrier coatings. Pricing softness currently runs through mature segments like printing paper due to digital substitution, while buyers of high-performance packaging for food contact applications exhibit lower price sensitivity.
Supply Chain Analysis
China's GB standards for product quality and recycled content mandates are reshaping sourcing decisions for packaging materials, driving demand for compliant fiber. Geographic supply concentration for critical raw materials centers on Brazil for virgin eucalyptus pulp, and North America for containerboard production. Key dependencies include wood fiber from sustainably managed forests and high-quality recovered paper streams. A structural supply chain risk is the single-source vulnerability for specialized pulps, alongside commodity price volatility. Distribution for industrial packaging typically runs directly from large mills to e-commerce fulfillment centers or through specialized distributors for smaller-volume converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market presents a clear margin-expansion story, driven by the displacement of single-use plastics and the valorization of lignin as a high-value co-product.
For Market Incumbents: Extend investments in energy-efficient mill operations and advanced barrier coating technologies to counter rising input costs and competition from alternative materials. Secure long-term supply agreements for certified, sustainably sourced fiber to meet corporate mandates and regulatory requirements from the EU's CSRD. Focus research and development on lignin valorization to create new revenue streams from former waste, mitigating the threat of margin compression in commodity segments.
For New Entrants and Emerging Players: Small and medium-sized consumer goods brands seeking plastic-free packaging solutions represent an underserved buyer archetype. Target the rapidly expanding e-commerce logistics sector in Southeast Asia and Latin America with innovative molded fiber applications for protective packaging. A compelling go-to-market angle involves offering rapid prototyping and customization services for niche applications, emphasizing material sustainability and performance parity with plastics.
For Investors and Strategic Acquirers: Valuations sit cheapest among legacy printing paper manufacturers facing structural decline, offering potential for asset repurposing into packaging or specialty grades. Seek acquisition targets with strong intellectual property in advanced material science, particularly those developing food-grade barrier coatings or lignin-based bioproducts. A critical signal to watch is the widespread commercialization of lignin valorization technologies, transforming pulp mills into integrated biorefineries with diversified revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Containerboard | Supports e-commerce growth in China's coastal manufacturing hubs. |
| Green Manufacturing Transition | Ensures compliance with EU Green Deal and China's dual carbon goals. |
| Long-term Recycled Fiber Agreements | Secures supply for brands with corporate recycled content mandates. |
| Food-Grade Barrier Coating Product Launch | Enables viable plastic-replacement solutions for consumer goods packaging. |
| Lignin Valorization Joint Venture | Creates new revenue streams and enhances the biorefinery economic model. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a robust, mixed-methods approach. Primary research involved in-depth conversations with mill operators, procurement managers from CPG companies, R&D specialists in material science, and brand owners navigating plastic-substitution mandates. This primary data was triangulated against secondary sources including industry association reports, global trade databases, corporate sustainability disclosures, and regulatory filings from the EU and China.
The segment-weighting approach informed the analytical framework across the projection horizon, integrating detailed modeling for product types, application segments, end-user industries, and production technologies. CAGRs were derived through a combination of historical trend analysis, future demand projections for key end-use sectors, and expert consensus. Key industry-specific forecast inputs included projected e-commerce growth rates in emerging markets and anticipated plastic substitution targets driven by regulatory frameworks like the EU Green Deal.
Underlying measurement precision varies by segment; high-volume commodity pulp and packaging paper carry tighter precision than highly specialized, nascent plastic-replacement materials. Forecasts reflect assumptions documented through extensive primary and secondary research. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Pigment Market
Paper Products
Compressed Fiberboard Market
Paper Products
Global Paperboard Market
Paper Products
Overlay Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Ceramic Paper Market
Paper Products
Tissue Paper Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
North America Decor Paper Market
Paper Products
Graphic Paper Market
Paper Products
Europe Decor Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Clay Coated Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Europe Thermal Paper Market