
 Global Calcium Silicate Insulation Market | 2026-2036
Global Calcium Silicate Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Calcium Silicate Insulation Market Analysis
Aftermarket service revenue for high-temperature insulation systems is reshaping margin distribution across the value chain. Promat International leverages its global fabrication network to sustain premium positioning in fireproofing applications. Johns Manville anchors North American supply through vertical integration into raw mineral sourcing and board manufacturing.
Calcium silicate insulation is a rigid, inorganic material composed primarily of lime and silica with reinforcing fibers, manufactured through hydrothermal curing to achieve densities between 200 and 450 kg/m³ and continuous service temperatures up to 1000°C; its primary purpose is to provide thermal insulation and fire protection for industrial equipment, piping, and structural steel. Board products dominate volume due to standardized fabrication and broad applicability across power generation and chemical processing end users, while pipe insulation commands premium pricing through custom dimensional production and installation labor bundling. Thermal insulation represents the mature demand base, whereas fireproofing exhibits faster growth as building codes tighten and passive fire protection specifications expand in commercial construction.
The EPA enforces emissions and energy efficiency standards that drive industrial facility retrofits, while REACH in Europe restricts hazardous additives in competing organic insulation materials. China's GB standards and MEE directives mandate energy conservation in heavy industry, directly expanding addressable demand for inorganic insulation systems. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate specification shifts and certification requirements that will determine market access.
Market Dynamics
The EU F-Gas Regulation and parallel frameworks across multiple jurisdictions are systematically eliminating foam-based thermal insulation from industrial specifications, creating structural displacement demand for inorganic calcium silicate alternatives in power generation and chemical processing installations.
Growth Catalysts
- High-temperature power infrastructure:Boiler and turbine retrofit cycles in aging coal and combined-cycle plants are expanding procurement volumes for rigid inorganic insulation systems rated above 800°C continuous service.
- REACH chemical restrictions:ECHA's phased limitations on hazardous additives in competing organic insulation materials are narrowing specification options for European industrial buyers toward silica-lime formulations.
- China's dual carbon mandates:MEE directives and GB standards enforcing energy conservation in heavy industry are directly expanding addressable demand for calcium silicate board and pipe insulation across steel and cement sectors.
Market Restraints
- Reinforcing fiber supply concentration:Specialized alkaline-resistant fiber inputs for hydrothermal curing concentrate among limited suppliers, creating input cost volatility and qualification bottlenecks for board manufacturers.
- Installation labor intensity:Rigid calcium silicate systems require skilled mechanical insulation crews for field cutting and fitting, constraining deployment velocity compared to spray-applied organic alternatives in maintenance turnaround windows.
- Weight-to-insulation ratio:Densities of 200-450 kg/m³ impose structural load penalties and elevated shipping costs versus lightweight aerogel or microporous substitutes in offshore and aerospace-adjacent applications.
Strategic Opportunities
- India's industrial corridor buildout:National Manufacturing Zones and dedicated freight corridors are embedding passive fire protection specifications into new commercial construction, opening specification pathways for fireproofing-grade calcium silicate.
- Prefabricated module integration:Skid-mounted process equipment manufacturers are pre-installing insulation during fabrication, shifting value capture toward factory-applied systems and away from field contracting.
- Green building certification premiums:LEED and BREEAM point structures rewarding non-combustible, low-embodied-carbon envelope materials are positioning inorganic insulation for specification in data center and logistics facility construction.
Industry Challenges
- Hydrothermal curing energy intensity:Autoclave processing requires sustained steam pressure and temperature, exposing producers to natural gas price volatility and carbon border adjustment exposure in export markets.
- Multi-jurisdiction certification fragmentation:Divergent fire resistance testing protocols between ASTM E119, EN 1363, and GB 9978 create redundant qualification costs and specification lock-in for multinational projects.
- Legacy equipment compatibility:Retrofit installations must interface with aged substrate conditions and irregular dimensions, demanding custom fabrication capabilities that strain standardized production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Calcium Silicate Insulation Market |
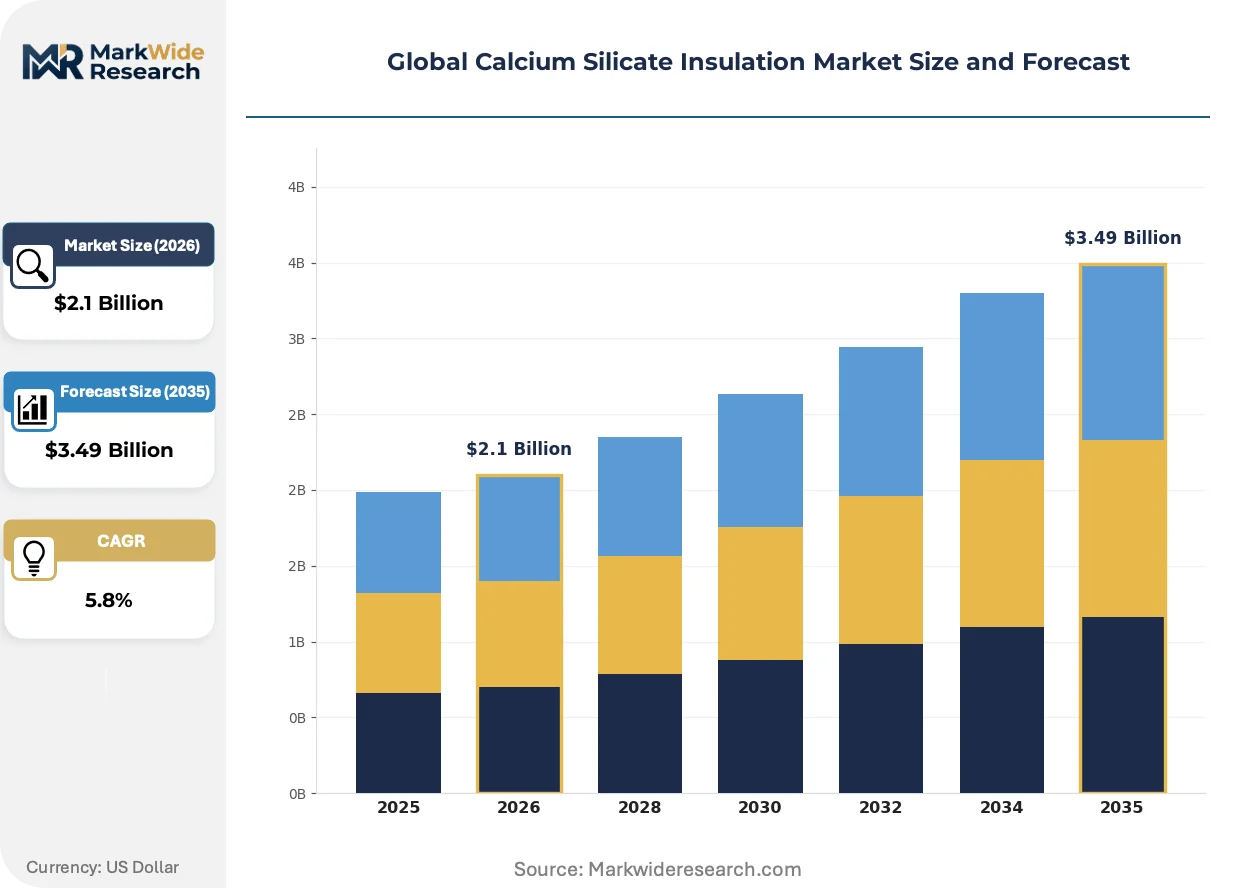
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board, Pipe Insulation, Blanket, Foam End User: Building & Construction, Oil & Gas, Power Generation, Chemical Processing Application: Thermal Insulation, Fireproofing, Acoustic Insulation, Industrial Equipment Installation Method: Mechanical Fastening, Adhesive Bonding, Spray Application, Modular Assembly |
| Companies Covered | Promat International, Johns Manville, Skamol, Etex Group, Morgan Advanced Materials, Isolite Insulating Products, NICHIAS Corporation, Isolatek International, L'ISOLANTE K-FLEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Calcium Silicate Insulation Market Emerging Trajectories
Digital integration of thermal performance monitoring and predictive maintenance platforms is reshaping how insulation systems are specified, installed, and serviced across industrial asset bases. Material science advances and regulatory chemistry restrictions are simultaneously altering formulation priorities and supply chain configurations.
Sensor-embedded calcium silicate insulation is digitizing condition monitoring for high-temperature piping and pressure vessels. Power utilities in Germany and the US are piloting these systems to detect moisture ingress and thermal degradation before insulation removal becomes necessary. The technology is compressing maintenance cycle planning from calendar-based to condition-based intervals, reducing unplanned outage exposure.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is eliminating closed-cell foam competition in European industrial specifications. REACH Annex XVII restrictions on flame retardant chemistries in organic insulation are accelerating substitution toward inherently non-combustible inorganic systems. Chemical processing and offshore energy infrastructure in the North Sea and Rhine-Ruhr corridor are responding fastest, with specification revisions completed ahead of 2027 compliance deadlines.
Buyer consolidation among multinational EPC contractors is compressing supplier qualification timelines and bundling insulation procurement into long-term framework agreements. Lump-sum turnkey project delivery in Middle Eastern petrochemical developments is displacing fragmented local subcontractor purchasing. Engineering firms in Saudi Arabia and the UAE are consolidating specification authority at headquarters level, favoring globally certified manufacturers with regional fabrication presence over purely local suppliers.
Global Calcium Silicate Insulation Market Segmentation
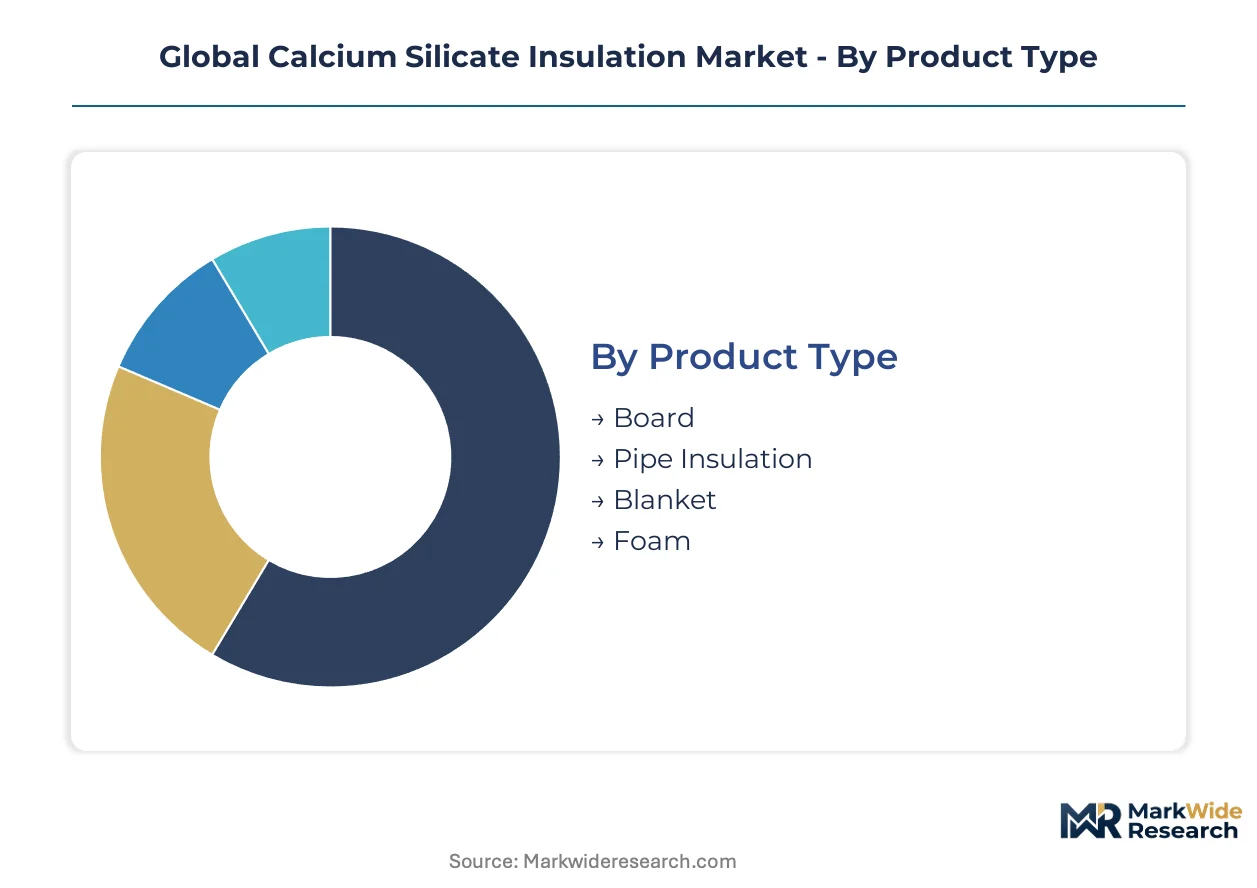
Segmentation in calcium silicate insulation reveals divergent margin profiles and service intensity requirements across product forms and installation contexts. Board and pipe formats sustain recurring aftermarket revenue through inspection and replacement cycles, while fireproofing applications command specification premiums tied to certification maintenance.
Product Type:
Aftermarket service intensity varies sharply across product formats, with pipe insulation requiring the most intensive field support due to dimensional customization and joint sealing protocols.
- Board:Rigid panels manufactured through hydrothermal curing achieve densities between 200-450 kg/m³ and continuous service temperatures to 1000°C. Demand concentrates in power generation utilities across China and Germany where boiler and turbine retrofit cycles are accelerating simultaneously. Board formats dominate procurement volumes through standardized fabrication and broad applicability across industrial infrastructure.
- Pipe Insulation:Custom-molded or fabricated sections designed for cylindrical equipment and piping networks require skilled field cutting and fitting. Procurement in the US chemical processing sector bundles installation labor with material supply, compressing margins for pure product vendors while elevating integrated service providers. The format commands premium pricing through dimensional precision and thermal bridging mitigation.
- Blanket:Flexible mat formats reinforced with alkaline-resistant fibers serve irregular surfaces and maintenance access points where rigid systems prove impractical.
- Foam:Lower-density formulations compete in applications where weight constraints override maximum temperature ratings.
By volume, Board leads. By growth pace, Pipe Insulation is ahead.
End User:
Cost tier stratification separates specification-grade procurement in regulated infrastructure from commodity purchasing in commercial construction.
- Building & Construction:Passive fire protection specifications in commercial and industrial buildings drive demand for non-combustible envelope materials. India's National Manufacturing Zones are embedding fireproofing requirements into new commercial construction, opening specification pathways for calcium silicate systems.
- Oil & Gas:Offshore platforms and downstream refineries require insulation rated for combined thermal, fire, and mechanical stress. The North Sea and Middle Eastern petrochemical developments are consolidating procurement through lump-sum turnkey contractors, favoring manufacturers with regional fabrication presence.
- Power Generation:Aging coal and combined-cycle plants across Germany and the US are executing boiler and turbine retrofits, expanding procurement for rigid inorganic systems above 800°C continuous service. This segment concentrates the highest aftermarket service revenue through scheduled inspection and replacement cycles.
- Chemical Processing:Reactor vessels and process piping in the Rhine-Ruhr corridor and US Gulf Coast are responding fastest to REACH chemical restrictions and EPA emissions standards, with specification revisions eliminating foam-based alternatives.
Power Generation captures the highest service attach rates. Chemical Processing is expanding most quickly.
Application:
Volume distribution favors mature thermal insulation, while specification evolution is concentrating fastest in fireproofing as building codes tighten across multiple jurisdictions.
- Thermal Insulation:The established demand base for industrial equipment, piping, and pressure vessels. MEE directives and China's GB standards are mandating energy conservation retrofits across steel and cement sectors, directly expanding addressable demand.
- Fireproofing:Structural steel protection in commercial construction and industrial facilities. LEED and BREEAM point structures rewarding non-combustible, low-embodied-carbon materials are positioning inorganic insulation for specification in data center and logistics facility construction across Germany and India.
- Acoustic Insulation:Secondary performance attribute in combined systems where thermal and fire ratings dominate specifications.
- Industrial Equipment:Skid-mounted process equipment manufacturers are pre-installing insulation during fabrication, shifting value capture toward factory-applied systems.
Thermal Insulation leads by installed base. Fireproofing shows the steepest expansion trajectory.
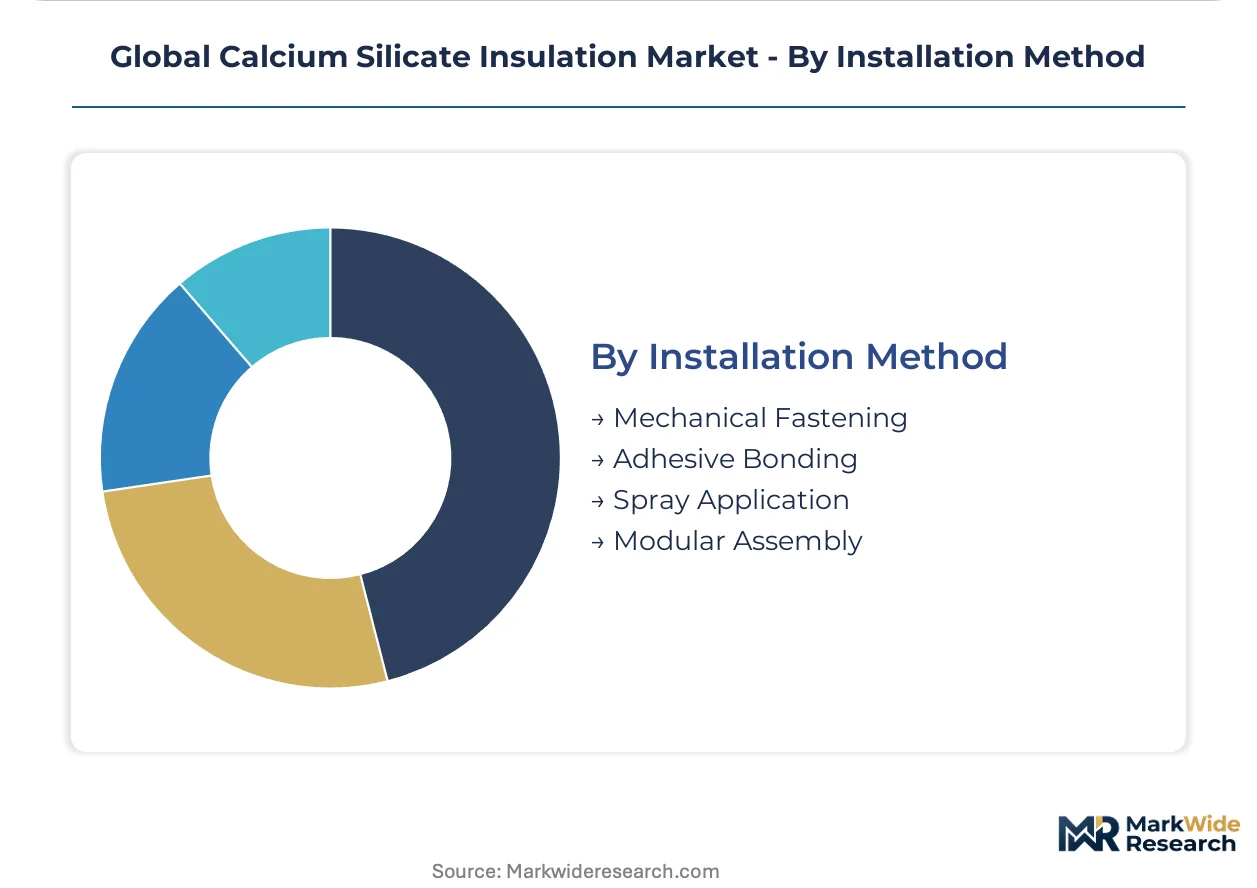
Installation Method:
Customer type stratification separates owner-operators with in-house mechanical crews from EPC contractors outsourcing specialized insulation labor.
- Mechanical Fastening:Pins, clips, and banding systems for rigid board and pipe insulation in high-vibration environments. Saudi Aramco and UAE petrochemical developments favor this method for maintenance accessibility.
- Adhesive Bonding:Direct attachment for flat surfaces and irregular substrates where mechanical penetration is restricted.
- Spray Application:Limited relevance for rigid calcium silicate; primarily serves repair and patch applications where factory-fabricated sections are impractical.
- Modular Assembly:Pre-insulated skids and process modules fabricated offsite. This method is gaining share fastest as engineering firms consolidate specification authority at headquarters level and favor factory quality control over field installation variables.
Mechanical Fastening dominates field installation. Modular Assembly is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes calcium silicate insulation primarily for thermal retrofit cycles in heavy industry, while Germany and the United States concentrate procurement in power generation boiler replacements, and India channels demand toward passive fire protection in new commercial construction.
China
Steel and cement sectors drive procurement volumes as MEE directives enforce energy conservation retrofits across aging industrial bases. GB standards mandate thermal efficiency upgrades for high-temperature equipment, expanding specification opportunities for rigid inorganic systems. The Yangtze River Delta industrial corridor concentrates fabrication capacity and end-user demand for board and pipe insulation formats.
Germany
Combined-cycle power plants and chemical processing facilities in the Rhine-Ruhr corridor execute turbine and reactor vessel retrofits on compressed schedules. ECHA's REACH Annex XVII restrictions on flame retardant additives in organic insulation systematically displace foam-based competitors from industrial specifications. Bavaria's data center construction pipeline embeds LEED point structures rewarding non-combustible envelope materials.
United States
EPA emissions standards and FERC efficiency mandates accelerate boiler replacements in aging coal fleets across the Midwest and Southeast. The US Gulf Coast chemical processing sector bundles insulation procurement into lump-sum turnkey contracts with consolidated EPC contractors. Houston and Lake Charles anchor regional demand for high-temperature piping and pressure vessel applications.
India
National Manufacturing Zones and dedicated freight corridors embed passive fire protection specifications into new commercial and logistics facility construction. BIS standards for non-combustible building materials tighten code compliance pathways for calcium silicate fireproofing systems. Maharashtra and Gujarat industrial clusters concentrate procurement for steel sector structural protection and power plant infrastructure.
Saudi Arabia
Petrochemical developments and downstream refinery expansions consolidate insulation procurement through headquarters-level engineering specifications. The country's national industrial regulator mandates fire resistance ratings for offshore and process infrastructure. The Eastern Province concentrates demand for high-temperature mechanical fastening systems in maintenance-accessible configurations.
Global Calcium Silicate Insulation Market Vendor Landscape
Capability concentration sits with specialized fabricators commanding premium positioning through certification maintenance and custom dimensional production; scale advantage sits with integrated mineral processors anchoring regional supply security through captive raw material access. The vendor base separates into three archetypes: global fabrication networks sustaining premium fireproofing positioning, vertically integrated board manufacturers controlling upstream mineral sourcing, and regional specialists capturing maintenance turnaround contracts through proximity logistics. Consolidation pressure manifests through framework agreement bundling by multinational EPC contractors and pre-insulated module integration shifting value capture toward factory-applied systems.
Within the global fabrication tier, Promat International and Johns Manville occupy positions exemplifying divergent strategic anchors—Promat representing the distributed production network model for specification-grade fireproofing, Johns Manville embodying backward integration into raw mineral sourcing and board manufacturing for regional supply security. Skamol sits within the specialty fabricator archetype, its geographic naming convention indicating Nordic operational origins while its market presence reflects positioning toward custom-engineered thermal solutions. These three company structures illustrate the competitive spectrum: capability-differentiated global networks, resource-integrated regional anchors, and application-focused technical specialists.
| Leading Market Players |
|---|
| Promat International |
| Johns Manville |
| Skamol |
| Etex Group |
| Morgan Advanced Materials |
| Isolite Insulating Products |
| NICHIAS Corporation |
| Isolatek International |
| L'ISOLANTE K-FLEX |
| Others |
Supply Flow & Price Mechanics
Alkaline-resistant fiber supply concentration in Japan and Germany determines both the premium-to-economy pricing spread for high-temperature board grades and the geographic clustering of hydrothermal curing capacity near qualified fiber terminals. This input bottleneck compresses margins for non-integrated fabricators while rewarding producers with captive fiber qualification pathways.
Pricing Analysis
Long-term framework agreements dominate procurement in Middle Eastern petrochemical developments and North American power generation, compressing spot market liquidity. Pricing stratifies across premium certification-grade fireproofing, standard industrial thermal insulation, and economy retrofit board tiers, with differentiation anchored in ASTM E119 versus EN 1363 test compliance and regional fabrication proximity. Cost compression in the economy tier intensifies as Chinese board exports displace local production in Southeast Asian maintenance markets. Chemical processing EPC contractors in the US Gulf Coast exhibit lowest price sensitivity due to bundled turnkey contracting, while independent mechanical insulation subcontractors in India face acute margin pressure from raw material volatility.
Supply Chain Analysis
Contract manufacturing for calcium silicate board concentrates in China's Yangtze River Delta, Germany's North Rhine-Westphalia, and the US Southeast near Atlanta. Production draws from specialized wollastonite deposits in New York and Finland, alkaline-resistant glass fiber from Japanese and Belgian suppliers, and lime from regional captive kilns. Single-source vulnerability in fiber reinforcement creates qualification bottlenecks for new market entrants. Distribution runs through regional fabrication networks that pre-cut and jacket board for field installation, with Promat International and Johns Manville maintaining owned-channel presence in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium silicate insulation incumbents face a substitution defense against aerogel and microporous systems in aerospace-adjacent and offshore weight-constrained applications. Market positioning requires hardening specification authority before lightweight alternatives achieve cost parity in broader industrial segments.
For Market Incumbents: Harden fireproofing certification maintenance as the primary defensive moat, investing in simultaneous ASTM E119, EN 1363, and GB 9978 qualification to lock multinational EPC contractors into single-source relationships. Deepen backward integration into wollastonite and lime sourcing to insulate margin structures from mineral freight volatility. Aerogel substitution in North Sea offshore platforms represents the most proximate technology threat requiring active specification blocking.
For New Entrants and Emerging Players: Build out factory-applied insulation capabilities for skid-mounted process equipment manufacturers in Saudi Arabia and the UAE, where headquarters-level engineering specifications favor pre-qualified module suppliers over field contractors. India's National Manufacturing Zones offer the most penetrable geography for fireproofing-grade calcium silicate, with BIS standards tightening just ahead of local supply capacity. Target integrated service bundling that combines material supply with installation labor to differentiate from pure-product vendors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated regional anchors with captive mineral access over pure-play fabricators. Long-term viability across the projection horizon rests on positioning for carbon border adjustment exposure in European export markets and China's dual carbon mandate enforcement. Acquisition targets should demonstrate qualified fiber supply relationships and multi-jurisdiction certification portfolios. Monitor MEE directive enforcement intensity in Chinese steel and cement sectors as the inflection signal for thermal retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Minerals | Captive wollastonite and lime supply insulates margin structures from freight volatility in board manufacturing. |
| Multi-Jurisdiction Certification Investment | Simultaneous ASTM E119, EN 1363, and GB 9978 qualification locks EPC contractors into single-source relationships. |
| Factory-Applied Module Integration | Pre-insulated skid partnerships shift value capture from field contracting toward fabrication-stage margins. |
| Regional Fabrication Network Expansion | Proximity logistics in Saudi Arabia and UAE capture lump-sum turnkey procurement consolidation. |
| Sensor-Embedded Product Development | Condition-monitoring insulation digitizes maintenance cycles and creates recurring service revenue attachment. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with plant engineers at power generation utilities, procurement leads at chemical processing facilities, EPC contract managers, and mechanical insulation contractors; and secondary validation through customs trade databases, SEC filings of listed building materials producers, EPA emissions compliance records, and ECHA REACH restriction timelines. Bottom-up demand modeling across boiler retrofit cycles and top-down macro industrial construction indicators were triangulated to ground volume estimates.
Forecast inputs considered product format segmentation across board, pipe, and blanket configurations; end-use industry exposure spanning power generation, chemical processing, and building construction; and application mix between thermal insulation and fireproofing. CAGRs were derived from regression against industrial fixed asset investment indices and regulatory compliance deadline clustering. The modeling period incorporated REACH Annex XVII implementation phases and China's MEE directive enforcement trajectories as structural demand shifters.
Stress conditions across natural gas price volatility for autoclave energy input, reinforcing fiber supply disruption scenarios, and EPC contractor consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of GB standards revision cadence, BIS fire code adoption timelines, and F-Gas Regulation phase-down compliance reporting is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Acoustic Materials Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market