
 Paper Goods Market | 2026-2036
Paper Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Goods Market Insights
Modular packaging configurations is repositioning how retail and foodservice buyers specify paper-based containment. Kimberly-Clark leverages its North American tissue manufacturing base to sustain consistent supply to institutional channels. Georgia-Pacific anchors its competitive stance through integrated pulp-to-box operations across the southeastern United States. Mondi competes by specializing in recyclable barrier papers that replace multi-material laminates in European fresh food applications.
Paper goods encompass finished or semi-finished products manufactured from wood pulp, recycled fiber, or alternative cellulose sources, typically calipered between 0.25 mm for lightweight tissue and 5 mm for corrugated board, and engineered for absorption, structural protection, or printable communication surfaces. Their primary commercial purpose spans hygiene management, product protection through distribution, and information display. Packaging paper and kraft paper together carry the largest volume share, with kraft grades benefiting from e-commerce box demand while specialty paper commands the highest margin pools due to functional coatings and certified supply chains. Tissue paper oriented toward hospitality and consumer channels maintains steady replacement-cycle demand, though printing paper faces structural contraction as digital documentation displaces office consumption.
EPA effluent guidelines and OSHA workplace exposure limits shape US mill operations and capital allocation toward closed-loop water systems. The EU Green Deal, F-Gas Regulation, and REACH chemical restrictions collectively mandate fiber sourcing transparency and restrict certain bleaching chemistries in European production. Stakeholders must monitor how divergent regional compliance timelines affect cross-border sourcing strategies and capital deployment priorities for new capacity.
Market Dynamics
E-commerce fulfillment networks are pulling corrugated packaging specifications toward lighter-weight, high-strength board grades that reduce dimensional weight shipping penalties while maintaining stack integrity through automated sortation hubs.
Growth Catalysts
- EU Green Deal packaging mandates:Single-use plastics directives in Europe are redirecting foodservice demand toward molded fiber and paper-based barrier alternatives for takeaway containers.
- Bleached eucalyptus kraft pulp:Latin American pulp mills are expanding softwood-grade substitution capacity that feeds Asian tissue and specialty paper expansion.
- India:BIS certification requirements for food-contact paper are formalizing quality standards that accelerate organized sector consolidation against unbranded suppliers.
Market Restraints
- Recovered fiber price volatility:OCC (old corrugated containers) input costs swing with Chinese import quota fluctuations and domestic collection efficiency gaps.
- Indonesian pulp concentration:Three integrated producers control the majority of global hardwood pulp exports, creating single-source vulnerability for European coated paperboard mills.
- Digital documentation substitution:Cloud-based record systems and e-invoicing platforms are compressing office printing and copying paper demand across corporate procurement.
Strategic Opportunities
- Vietnam and Bangladesh:Underpenetrated per-capita tissue consumption and nascent retail packaging standards create first-mover positioning for regional production investment.
- Barrier coating convergence:Water-based polymer and bio-wax technologies are enabling oil-resistant, heat-sealable paper formats that replace multi-material flexible packaging in fresh protein applications.
- Direct-to-brand e-commerce channels:Subscription box merchants and DTC food brands are bypassing traditional distribution to specify custom-printed, right-sized corrugated directly from converters.
Industry Challenges
- Process control engineering talent:Mill automation and closed-loop water system operation require specialized skills that outpace vocational training program output in North America and Europe.
- FSC and PEFC chain-of-custody certification:Multi-site audit complexity and documentation burden slow supplier onboarding for brand-committed sustainable sourcing programs.
- Legacy ERP integration with IoT sensor networks:Real-time moisture and basis weight monitoring systems face interoperability friction with decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Goods Market |
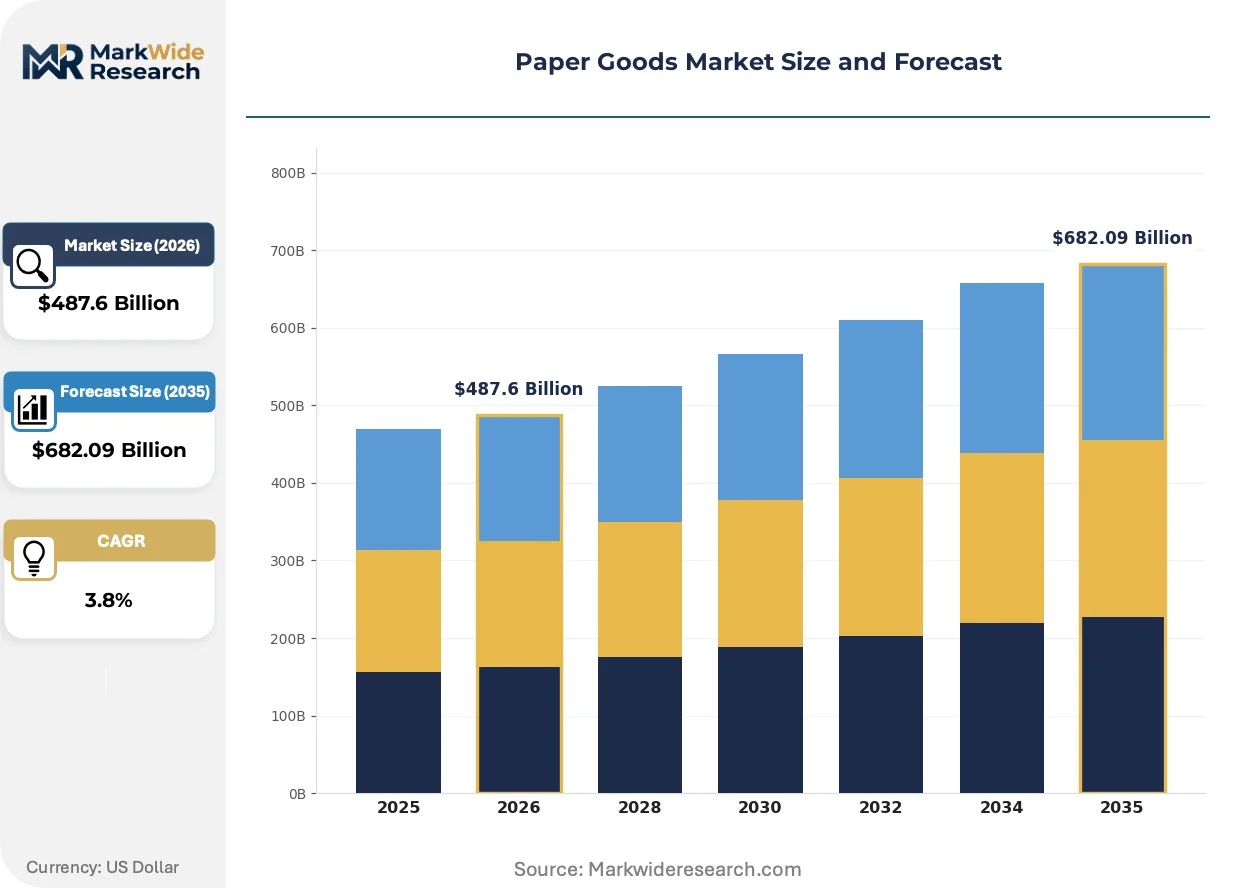
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $682.09 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printing Paper, Tissue Paper, Packaging Paper, Specialty Paper, Kraft Paper Application: Office Supplies, Food Packaging, Hygiene Products, Industrial Wrapping, Consumer Goods End User: Educational Institutions, Hospitality Sector, Manufacturing Units, Retail Chains, Government Agencies Distribution Channel: Online Retailers, Wholesale Distributors, Specialty Stores, Direct Sales, Institutional Supply |
| Companies Covered | Kimberly-Clark, Procter & Gamble, Essity, International Paper, Georgia-Pacific, Mondi, Smurfit Westrock, Stora Enso, Oji Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Goods Market Trends and Innovations
Active investment in barrier chemistry, fiber sourcing transparency, and packaging format modularity is compressing development cycles and rewiring supplier-buyer technical collaboration models.
Recyclable barrier paper technology is integrating mineral and bio-based coatings that achieve grease resistance and moisture vapor transmission rates previously requiring polyethylene lamination. Fresh food retailers in Germany and the Netherlands are specifying these formats for ready-meal and deli applications at accelerating volume. The technology is integrating single-material recovery streams that reduce sorting complexity and improve bale value for municipal recycling operators.
REACH chemical restrictions and ECHA substance of very high concern listings are eliminating certain fluorinated treatments and optical brighteners from European food-contact paper production. Mill chemists are reformulating wet-end additives and surface sizing agents to maintain performance without restricted compounds. Specialty paper segments serving premium chocolate and confectionery packaging are most affected, with producers accelerating migration to compliant alternatives ahead of sunset dates.
Brand-led sustainable packaging commitments are compressing supplier qualification timelines and shifting technical specification authority from procurement to corporate sustainability offices. Major CPG and quick-service restaurant chains are consolidating vendor panels around converters with certified fiber sourcing and carbon disclosure documentation. This pattern is most visible in North American and Western European markets where ESG reporting requirements and consumer-facing sustainability claims drive packaging decision criteria.
Paper Goods Market Segmentation
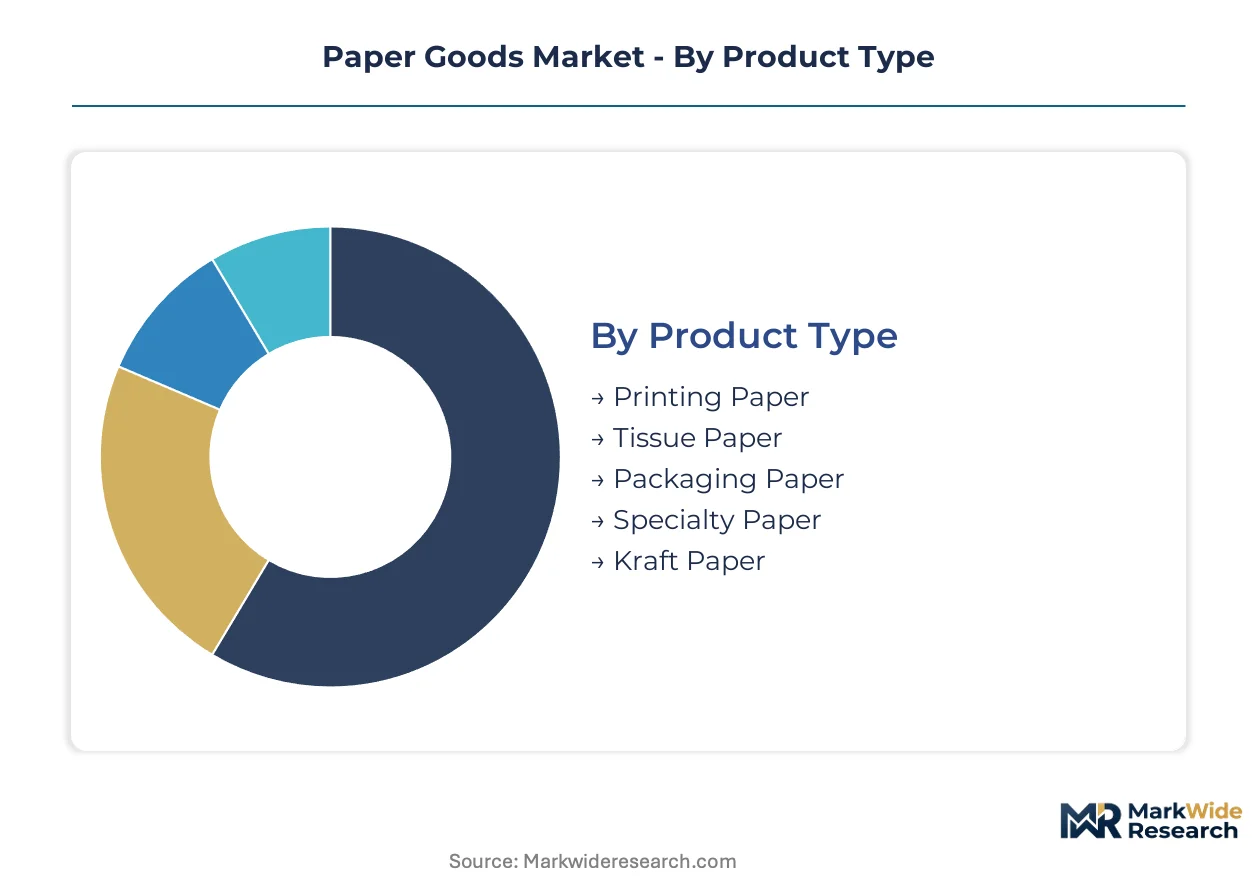
Paper goods segmentation reveals how fiber specifications, barrier performance, and end-use durability requirements fragment manufacturing capacity across incompatible asset bases. Converters must match caliper, coating, and certification attributes precisely to buyer technical standards or forfeit qualification.
Product Type:
Supply concentration in kraft pulping and tissue creping equipment shapes competitive boundaries across product categories.
- Packaging Paper:Corrugated medium and linerboard grades engineered for burst strength and edge crush resistance. E-commerce fulfillment networks in the United States and Germany are pulling specifications toward lighter basis weights that reduce dimensional weight shipping penalties while maintaining automated sortation integrity.
- Kraft Paper:Unbleached sulfate pulp sheets ranging from 40 to 350 gsm, prized for tear resistance and printability. Sack kraft demand from Brazilian agribusiness and Indian cement packaging is absorbing new Latin American pulp capacity ahead of European board mill contracts.
- Printing Paper:Coated and uncoated woodfree sheets for offset and digital presses. Corporate cloud migration and e-invoicing mandates are compressing office procurement volumes.
- Tissue Paper:Creped cellulose webs calipered below 0.5 mm for absorption and softness. Hospitality replenishment cycles and consumer premiumization are sustaining replacement demand.
- Specialty Paper:Functional substrates with barrier coatings, release properties, or security features. Thermal receipt paper and label facestock are climbing fastest.
Packaging paper and kraft paper together absorb the bulk of installed capacity; specialty paper is expanding most quickly.
Application:
Cost tier stratification separates commodity hygiene products from certified food-contact formats requiring audit documentation.
- Food Packaging:Grease-resistant wraps, molded fiber trays, and barrier-coated boards for direct food contact. EU Green Deal mandates are redirecting quick-service restaurant procurement away from polystyrene toward fiber-based alternatives in France and the Netherlands.
- Hygiene Products:Facial tissue, toilet paper, and absorbent cores for personal care. Per-capita consumption gaps in Vietnam and Bangladesh are attracting regional greenfield investment.
- Office Supplies:Copy paper, notebooks, and filing materials. Digital documentation substitution is forcing capacity rationalization among North American uncoated freesheet producers.
- Industrial Wrapping:VCI papers, interleaving sheets, and protective cushioning for metal and electronics shipments. Automotive just-in-time logistics in Mexico and Thailand are specifying custom-printed protective formats.
- Consumer Goods:Folding cartons, rigid boxes, and retail-ready packaging. Direct-to-brand e-commerce channels are bypassing traditional distribution to specify right-sized corrugated directly from converters.
Food packaging commands the highest compliance burden; hygiene products maintain the steadiest volume baseline.
End User:
Customer type determines specification authority, contract tenure, and sustainability documentation requirements.
- Retail Chains:Private-label tissue and branded consumer packaged goods requiring FSC chain-of-custody certification. Walmart and Carrefour sustainability scorecards are consolidating supplier panels around converters with carbon disclosure documentation.
- Hospitality Sector:Hotels, restaurants, and catering operations with high-frequency replenishment needs. Post-pandemic occupancy recovery in Dubai and Singapore is restoring institutional tissue demand.
- Manufacturing Units:Industrial absorbents, protective wrapping, and process consumables. Automotive and electronics clusters in Mexico and Thailand specify just-in-time delivery with vendor-managed inventory.
- Educational Institutions:Copy paper, notebooks, and administrative supplies. Budget compression and digital learning platform adoption are reducing procurement volumes.
- Government Agencies:Standardized procurement of office paper and hygiene products through centralized purchasing bodies. BIS certification requirements in India are formalizing quality standards that accelerate organized sector consolidation.
Retail chains concentrate specification authority; manufacturing units are gaining share fastest on reshoring and near-shoring trends.
Distribution Channel:
Volume concentration favors wholesale distributors with mill-direct relationships and logistics scale.
- Wholesale Distributors:Regional and national paper merchants consolidating truckload volumes from multiple mills. Southeast United States corrugated converters rely on distributor inventory buffers to manage OCC price volatility.
- Online Retailers:E-commerce platforms offering private-label tissue and subscription box corrugated. Amazon and Alibaba fulfillment specifications are standardizing box dimensions and print requirements.
- Direct Sales:Mill-direct relationships for high-volume accounts with customized specifications. Major quick-service restaurant chains are consolidating vendor panels around converters with certified fiber sourcing.
- Specialty Stores:Independent stationers and packaging suppliers serving small business and craft segments. Premium chocolate and confectionery packaging in Belgium and Switzerland demand specialty paper with compliant barrier coatings.
- Institutional Supply:Group purchasing organizations serving healthcare and education. Contract tenure and sustainability documentation requirements are extending procurement cycles.
Wholesale distributors anchor volume throughput; online retailers are climbing the fastest on e-commerce fulfillment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Indonesia attract pulp mill investment through tax holidays and duty exemptions on imported machinery. These zones concentrate new capacity serving Asian tissue and packaging demand.
United States
E-commerce fulfillment networks in Georgia and Tennessee specify lighter-weight corrugated grades to reduce dimensional weight shipping penalties. EPA effluent guidelines under the Clean Water Act mandate closed-loop water system investments at southeastern integrated mills. The Alabama-Georgia pulp-to-box corridor anchors domestic containerboard supply for Amazon and Walmart distribution centers.
China
Dual carbon goals and MIIT energy efficiency standards are accelerating mill consolidation in Shandong and Guangdong provinces. NMPA food-contact material regulations formalize quality standards for paper-based food packaging. The Yangtze River Delta cluster concentrates specialty paper capacity serving pharmaceutical and electronics packaging demand.
Germany
EU Green Deal packaging mandates and REACH chemical restrictions are eliminating fluorinated treatments from food-contact paper production. ECHA substance of very high concern listings drive reformulation of wet-end additives at mills in Baden-Württemberg. The Rhine-Ruhr industrial corridor hosts converters supplying recyclable barrier papers to Dutch and French fresh food retailers.
India
BIS certification requirements for food-contact paper accelerate organized sector consolidation against unbranded suppliers in Maharashtra and Gujarat. The PLI scheme for manufacturing incentivizes packaging material investments in Tamil Nadu. Mumbai-Pune industrial belt tissue converters serve hospitality sector replenishment demand from Dubai and Singapore hotel chains.
Brazil
Bleached eucalyptus kraft pulp expansion in São Paulo state feeds Asian tissue and specialty paper growth. ANVISA food-contact regulations align with Mercosur standards for paper-based packaging materials. The Santos port cluster handles hardwood pulp exports to European coated paperboard mills facing Indonesian supply concentration risk.
Paper Goods Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across incompatible asset configurations. The market structure shows moderate consolidation at the pulp and tissue tier with fragmentation among regional corrugated converters. Three archetypes dominate: integrated pulp-to-box operators controlling fiber supply, specialty barrier paper chemists serving food-contact compliance, and scale tissue manufacturers with institutional channel relationships. Capacity expansion and certified fiber sourcing partnerships constitute the dominant competitive moves.
Among North American integrated operators, Georgia-Pacific and Kimberly-Clark occupy positions spanning pulp supply through finished goods distribution. Mondi represents the European specialty archetype with recyclable barrier paper capabilities. These three exemplify how geographic anchoring and technical specialization segment competitive territory without direct overlap across all product categories.
| Leading Market Players |
|---|
| Kimberly-Clark |
| Procter & Gamble |
| Essity |
| International Paper |
| Georgia-Pacific |
| Mondi |
| Smurfit Westrock |
| Stora Enso |
| Oji Holdings |
| Others |
Pricing and Supply Chain Analysis
Quick-service restaurant chains and major e-commerce fulfillment operators concentrate procurement volumes sufficiently to command contract-based pricing with volume-scaled tiering. Their specification authority shapes how converters structure premium grades for certified fiber sourcing against standard grades for generic applications.
Pricing Analysis
Lead-time-driven pricing separates rush orders for custom-printed corrugated from scheduled production slots booked months ahead. Three-tier pricing structure across premium, standard, and economy levels tracks FSC chain-of-custody certification, with premium tiers capturing brand-committed sustainable sourcing programs. Pricing pressure stems from OCC input cost volatility as Chinese import quotas fluctuate. Regional corrugated converters show highest price sensitivity due to thin margins on commodity box grades.
Supply Chain Analysis
Regional distribution centers in the southeastern United States and Rhine-Ruhr corridor buffer mill-direct shipments against demand spikes. Supply concentrates in Brazil, Indonesia, and China for hardwood pulp exports that feed European coated paperboard mills. Raw material dependencies center on bleached eucalyptus kraft pulp, recovered OCC fiber, and water-based barrier coatings. Single-source vulnerability from three Indonesian integrated producers creates structural risk. Distribution runs through wholesale merchants with mill-direct relationships and logistics scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certified fiber sourcing and barrier chemistry capabilities as REACH restrictions and EU Green Deal mandates force smaller converters into acquisition or exit.
For Market Incumbents: Cement market position through captive pulp supply arrangements in Brazil and Southeast Asia to offset Indonesian concentration risk. Invest in water-based barrier coating R&D ahead of fluorinated treatment sunset dates. Lock in FSC chain-of-custody certification across all mill sites before supplier panel consolidation accelerates.
For New Entrants and Emerging Players: Recyclable barrier paper technology offers a technology-first wedge into European fresh food retail specifications currently served by multi-material laminates. Target underpenetrated tissue demand in Vietnam and Bangladesh where per-capita consumption gaps support regional greenfield economics. Pursue direct-to-brand e-commerce channels that bypass traditional distributor relationships.
For Investors and Strategic Acquirers: The window for entry favors specialty barrier paper chemists with compliant coating portfolios and established European retailer relationships. Long-term viability hinges on carbon disclosure documentation and certified supply chain transparency. Watch for BIS certification enforcement in India as an inflection indicator for organized sector consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive eucalyptus kraft capacity in Brazil secures input cost stability against Indonesian export volatility. |
| Barrier Coating R&D Partnership | Collaboration with German chemical suppliers accelerates compliant alternatives to restricted fluorinated treatments. |
| FSC Chain-of-Custody Certification | Multi-site audit completion qualifies converters for Walmart and Carrefour sustainability scorecards. |
| Regional Distribution Center Expansion | Georgia and Tennessee hub additions reduce lead times for Amazon and Walmart fulfillment specifications. |
| Direct-to-Brand E-commerce Channel | Bypassing wholesale merchants captures margin from subscription box merchants specifying right-sized corrugated. |
Research Methodology
Trade flow databases, mill capacity registries, and customs export records formed the secondary backbone of this analysis. Primary interviews with pulp procurement directors, corrugated plant managers, retail packaging specification leads, and sustainability compliance officers supplied operational context. Bottom-up and top-down triangulation cross-validated volume estimates against disclosed capacity utilization and end-use consumption patterns.
Bottom-up modeling tracked fiber input costs, coating formulation shifts, and end-use demand by product caliper and barrier specification across the analysis window. Segmentation dimensions included product type, application durability requirements, end-user procurement authority, and distribution channel logistics configuration. CAGRs were derived from trend extrapolation of e-commerce fulfillment expansion and regulatory substitution effects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt OCC price spikes or accelerated EU chemical restriction timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Sawn Wood Market
Paper Products
GCC Paper Products Market
Paper Products
Photographic Paper Market
Paper Products
Europe Coated Paper Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Organic Tissue Paper Market
Paper Products
Europe Thermal Paper Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Global Security Paper Market
Paper Products
Acrylic Paper Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Abaca Pulp Market
Paper Products
Super Calendered Glassine Paper Market