
 Global Ceramic Tube Market | 2026-2036
Global Ceramic Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Tube Market Analysis
Medical device OEMs is collapsing as the dominant buyer archetype while aerospace primes and automotive Tier-1 suppliers gain procurement share. Kyocera Corporation leverages its vertically integrated alumina and zirconia powder-to-part pipeline to dominate medical-grade ceramic tube supply. CeramTec GmbH anchors European demand through specialized silicon carbide and aluminum nitride formulations for implantable electronics. CoorsTek, Inc. competes on manufacturing scale with multi-site production across Colorado and Arkansas serving defense and energy clients.
Ceramic tubes are cylindrical components formed from advanced oxide, non-oxide, or composite ceramic materials, typically manufactured via isostatic pressing, extrusion, or injection molding and sintered at temperatures exceeding 1600°C to achieve dense, thermally stable structures. Their primary purpose is to provide electrical insulation, chemical inertness, and dimensional stability in extreme thermal or corrosive environments across industrial and medical systems. Insulator tubes occupy the largest revenue pool due to pervasive deployment in power distribution and furnace architectures, while thermocouple tubes represent the fastest-growing category as semiconductor fabrication pushes process temperatures higher. Structural tubes command premium pricing in aerospace propulsion and satellite thermal management where failure tolerance approaches zero.
REACH in Europe and FDA 21 CFR Part 820 in the United States impose material traceability and biocompatibility testing burdens that filter out commodity-grade suppliers and elevate certified manufacturers. EMA medical device regulations and Japan's PMDA standards further fragment market access, requiring country-specific quality management certifications. Stakeholders must monitor evolving dual-use export controls on high-purity ceramic formulations and pre-position supply agreements before qualification timelines extend.
Market Dynamics
Medical-grade ceramic tube procurement is consolidating around vertically integrated powder-to-part manufacturers as FDA 21 CFR Part 820 and REACH compliance timelines stretch beyond 18 months, filtering out commodity suppliers and concentrating qualified supply among certified producers with captive alumina and zirconia refining capabilities.
Growth Catalysts
- Semiconductor fabrication scaling:Thermocouple tubes face surging procurement from foundries operating above 1400°C process nodes, with silicon carbide formulations replacing legacy metal sheaths in diffusion furnaces.
- Japan's PMDA medical device standards:Implantable electronics housings now mandate aluminum nitride purity thresholds that only specialized ceramic converters can satisfy, accelerating qualification of Japanese and German suppliers.
- Aerospace propulsion thermal management:Structural tubes in satellite bus architectures require zero-failure tolerance, locking in multi-year supply agreements with certified manufacturers before design freeze.
Market Restraints
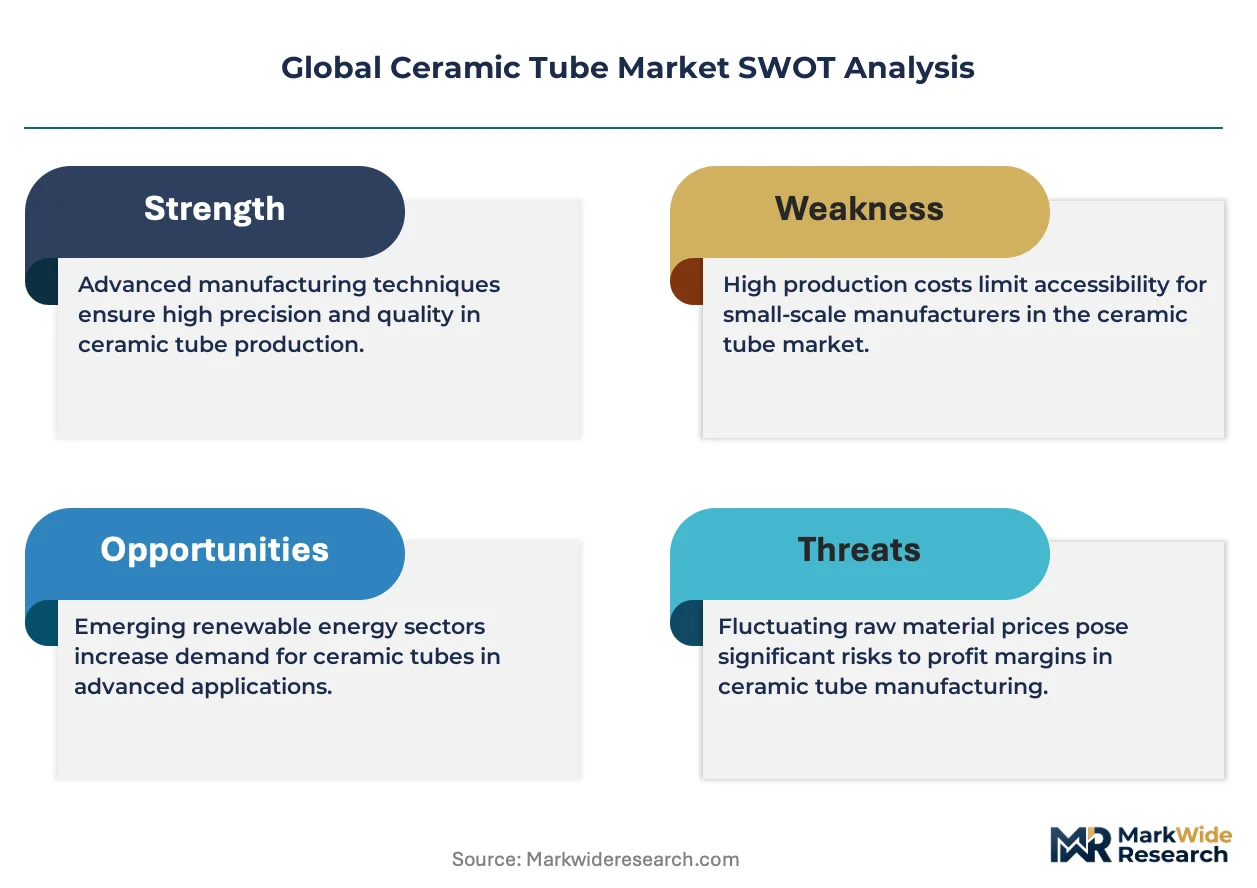
- High-purity alumina powder concentration:Premium feedstock supply concentrates among three specialized refiners, exposing tube manufacturers to input cost volatility and allocation risk during demand spikes.
- Dual-use export controls:Silicon carbide and aluminum nitride formulations above specified purity thresholds face licensing requirements from US Commerce and EU authorities, delaying shipment to non-allied defense contractors.
- Metal-ceramic composite substitution:Cermet tubes with cobalt-chromium matrices encroach on mid-temperature aerospace applications where ceramic alone was previously specified.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract ceramic tube producers to establish powder synthesis and sintering operations near Mumbai and Hyderabad device clusters.
- Hybrid electric aircraft thermal systems:Ceramic-to-metal brazed tube assemblies enable heat exchanger miniaturization in next-generation turboprop architectures, opening a white-space segment beyond traditional jet engine supply.
- EU Green Deal industrial decarbonization:Electric furnace retrofits in Germany and France replace refractory metal components with oxide ceramic tubes, creating regulatory-mandated replacement demand.
Industry Challenges
- ISO 13485 medical quality system implementation:Device OEMs now require full supply chain certification, forcing tube converters to requalify sub-tier powder sources under compressed timelines.
- Hot isostatic pressing capacity scarcity:Structural tube densification for aerospace applications requires specialized HIP equipment with 24-month lead times, constraining qualified output expansion.
- Multi-jurisdiction biocompatibility testing:Cytotoxicity and sensitization studies must replicate across US FDA, Japan PMDA, and EU EMA protocols, tripling pre-market validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Tube Market |
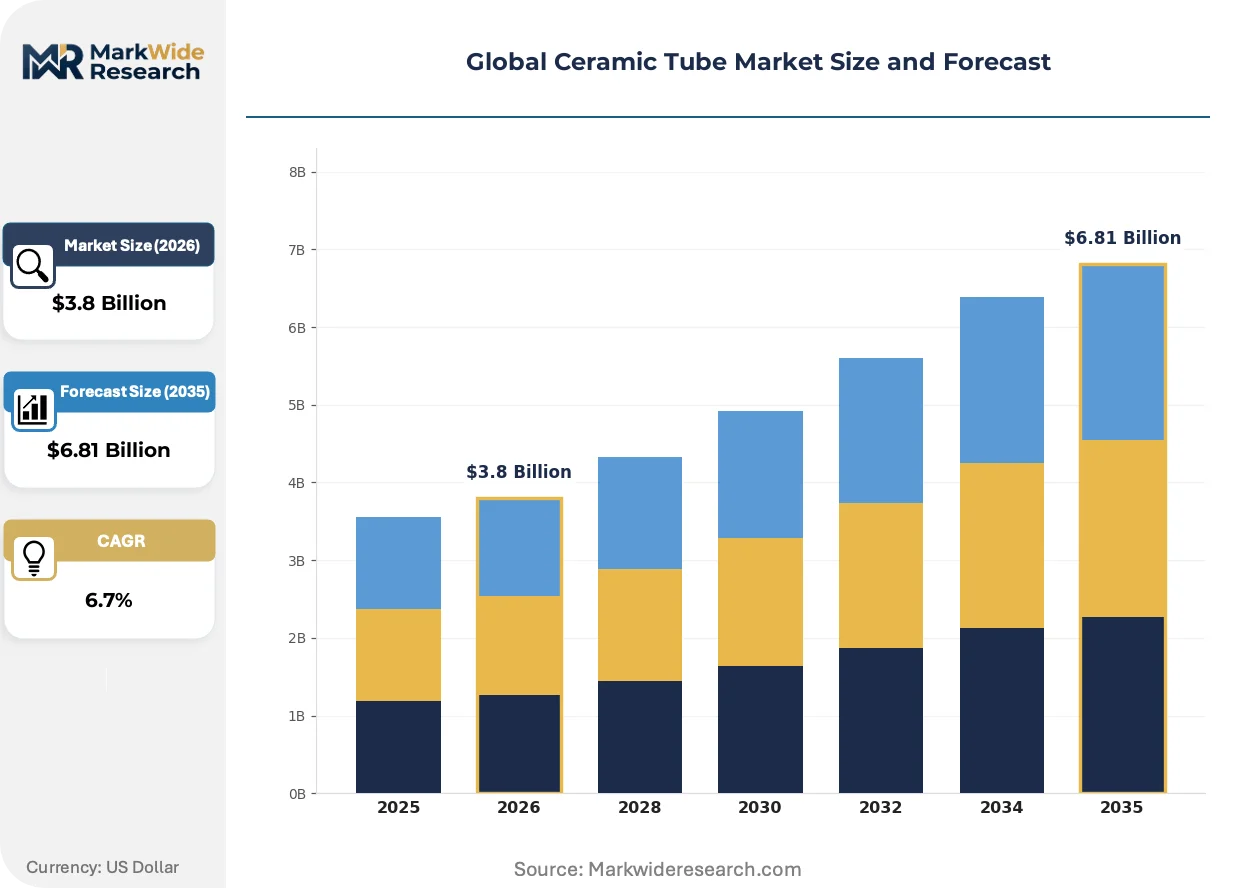
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulator Tubes, Conduit Tubes, Thermocouple Tubes, Structural Tubes End User: Aerospace, Medical Devices, Electronics, Automotive Components Form: Round, Square, Rectangular, Custom Shapes Application: Electrical Insulation, High-Temperature Applications, Chemical Processing, Heat Exchangers |
| Companies Covered | Kyocera Corporation, CeramTec GmbH, CoorsTek, Inc., Morgan Advanced Materials, NGK Insulators, Saint-Gobain, Carborundum Universal, Rauschert GmbH, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Tube Market Emerging Trajectories
Additive manufacturing of ceramic tube preforms is disrupting conventional isostatic pressing economics, enabling complex internal geometries for thermocouple protection sheaths and implantable device feedthroughs that were previously machined from solid blanks.
Silicon carbide-silicon nitride composite tubes is bifurcating the high-temperature insulator category. These materials deliver thermal shock resistance beyond monolithic alumina, attracting semiconductor equipment OEMs in Germany and Japan who specify them for rapid thermal processing chambers. The technology is compressing qualification cycles for legacy oxide formulations while creating a premium tier priced on failure-mode predictability.
REACH Article 33 substance disclosure requirements are forcing supply chain transparency down to raw material mining sources. ECHA enforcement actions against undocumented zirconia feedstock have triggered batch-level traceability investments across European ceramic tube converters. Medical device manufacturers sourcing from Germany and Switzerland now require conflict-mineral-free certifications that extend to tantalum and niobium dopants.
Buyer consolidation among orthopedic implant OEMs is concentrating procurement leverage with three dominant device groups. These buyers now mandate vendor-managed inventory programs with 48-hour replenishment commitments, displacing traditional purchase-order cycles. Germany's CeramTec and Japan's Kyocera have restructured European distribution to direct fulfillment models, bypassing regional distributors who previously handled technical specification support.
Global Ceramic Tube Market Segmentation
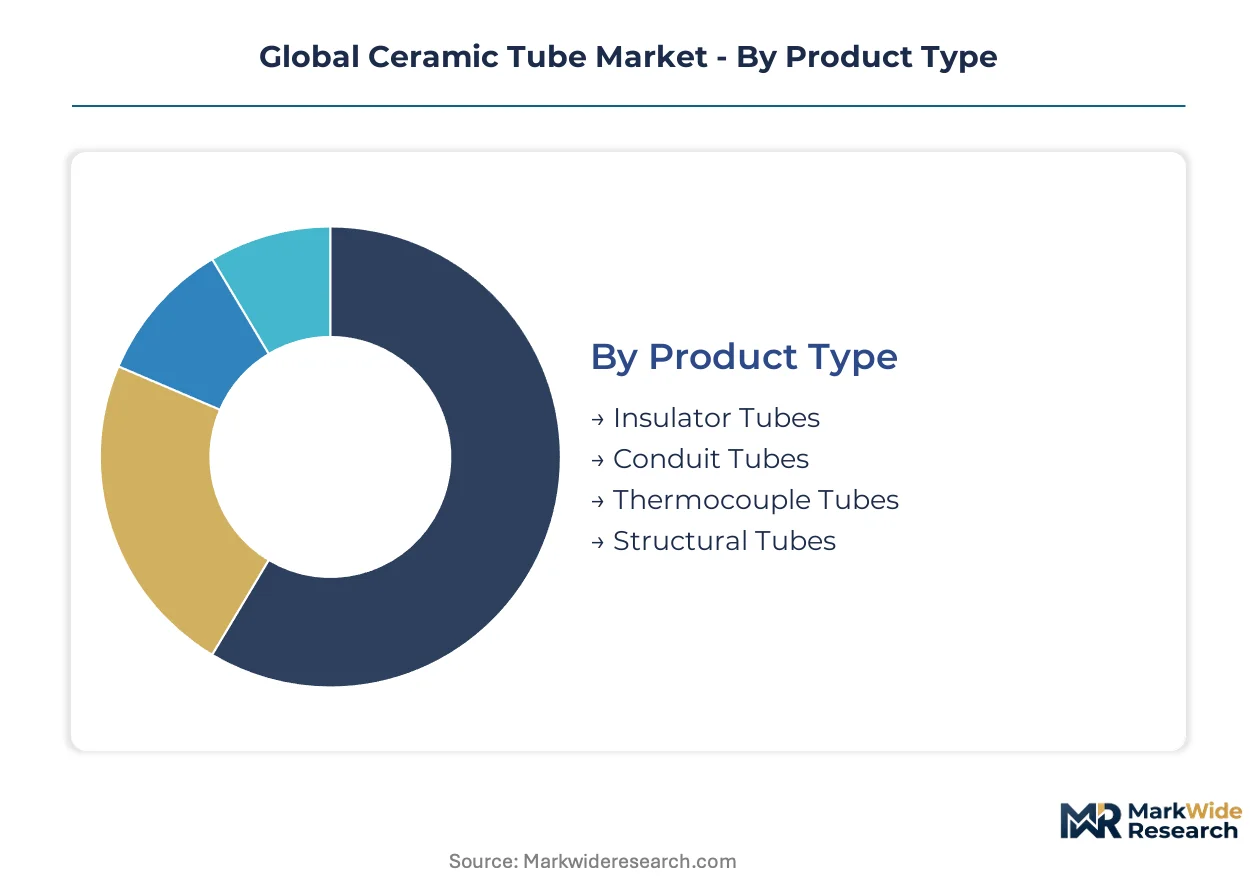
Ceramic tube procurement patterns diverge sharply across product architectures and end-use specifications. Buyers in semiconductor fabrication, implantable medical devices, and aerospace propulsion each impose distinct material purity, dimensional tolerance, and supply chain traceability requirements that reshape competitive positioning within every segment.
Product Type:
Export-led demand concentrates in thermocouple and structural tubes serving German and Japanese precision equipment OEMs, while insulator and conduit tubes track domestic infrastructure cycles in the United States and China.
- Insulator Tubes:Dense alumina and zirconia formulations provide dielectric isolation in power distribution switchgear and industrial furnace architectures. Procurement from German grid infrastructure OEMs and Japanese semiconductor equipment builders dominates export volumes, with REACH Article 33 substance disclosure requirements forcing batch-level traceability investments.
- Thermocouple Tubes:Silicon carbide and aluminum nitride sheaths protect temperature sensors in diffusion furnaces operating above 1400°C. Japanese foundries and German rapid thermal processing equipment manufacturers drive qualification of composite formulations that outperform legacy oxide ceramics under thermal shock cycling.
- Conduit Tubes:Alumina-based channels route electrical wiring through corrosive chemical environments. US petrochemical plant retrofits and Chinese industrial automation projects anchor regional demand clusters.
- Structural Tubes:Zero-failure-tolerance components in satellite thermal management and aerospace propulsion systems. US defense primes and European satellite bus manufacturers lock in multi-year supply agreements before design freeze.
Insulator tubes hold the largest share; momentum sits with thermocouple tubes.
End User:
Cost-tier stratification separates aerospace and medical device procurement—where qualification timelines and purity certifications command 40-60% price premiums—from electronics and automotive volume contracts.
- Aerospace:Structural and insulator tubes in satellite bus architectures and jet engine thermal management require HIP densification and material lot pedigree to AS9100 standards. US primes and European satellite integrators concentrate procurement leverage with certified manufacturers.
- Medical Devices:Implantable electronics housings and surgical instrument shafts demand ISO 13485 quality systems and FDA 21 CFR Part 820 traceability. Japanese PMDA purity thresholds for aluminum nitride and German REACH compliance timelines filter supply to vertically integrated powder-to-part converters.
- Electronics:Thermocouple protection sheaths and feedthrough insulators for semiconductor fabrication equipment. German and Japanese equipment OEMs specify silicon carbide-silicon nitride composites for rapid thermal processing chambers.
- Automotive Components:Exhaust sensors and hybrid powertrain insulation. US Tier-1 suppliers and German automotive OEMs drive standardization of alumina formulations for cost-sensitive thermal management applications.
Medical devices command the steepest price premiums; electronics is expanding most quickly.
Form:
Volume concentration favors round extrusions for thermocouple and insulator applications, while margin capture concentrates in custom-shaped structural tubes for aerospace where machining yield rates determine profitability.
- Round:Dominant geometry for thermocouple sheaths and electrical conduit. German and Japanese equipment OEMs specify tight diameter tolerances for automated assembly compatibility.
- Square:Heat exchanger and furnace lining applications where packing density matters. Indian electric furnace retrofit projects under EU Green Deal decarbonization mandates create regulatory-driven replacement demand.
- Rectangular:Satellite thermal management and implantable device housings requiring flat sealing surfaces. US aerospace primes and Swiss medical device OEMs drive specification development.
- Custom Shapes:Additive-manufactured preforms with complex internal geometries for thermocouple protection and feedthrough assemblies. German semiconductor equipment builders and Japanese implantable electronics manufacturers qualify geometries impossible via conventional isostatic pressing.
Round forms capture the highest volume; custom shapes are gaining share fastest.
Application:
Customer-type bifurcation separates specification-driven buyers in high-temperature and chemical processing—where material certification and failure-mode predictability dominate—from price-sensitive electrical insulation procurement.
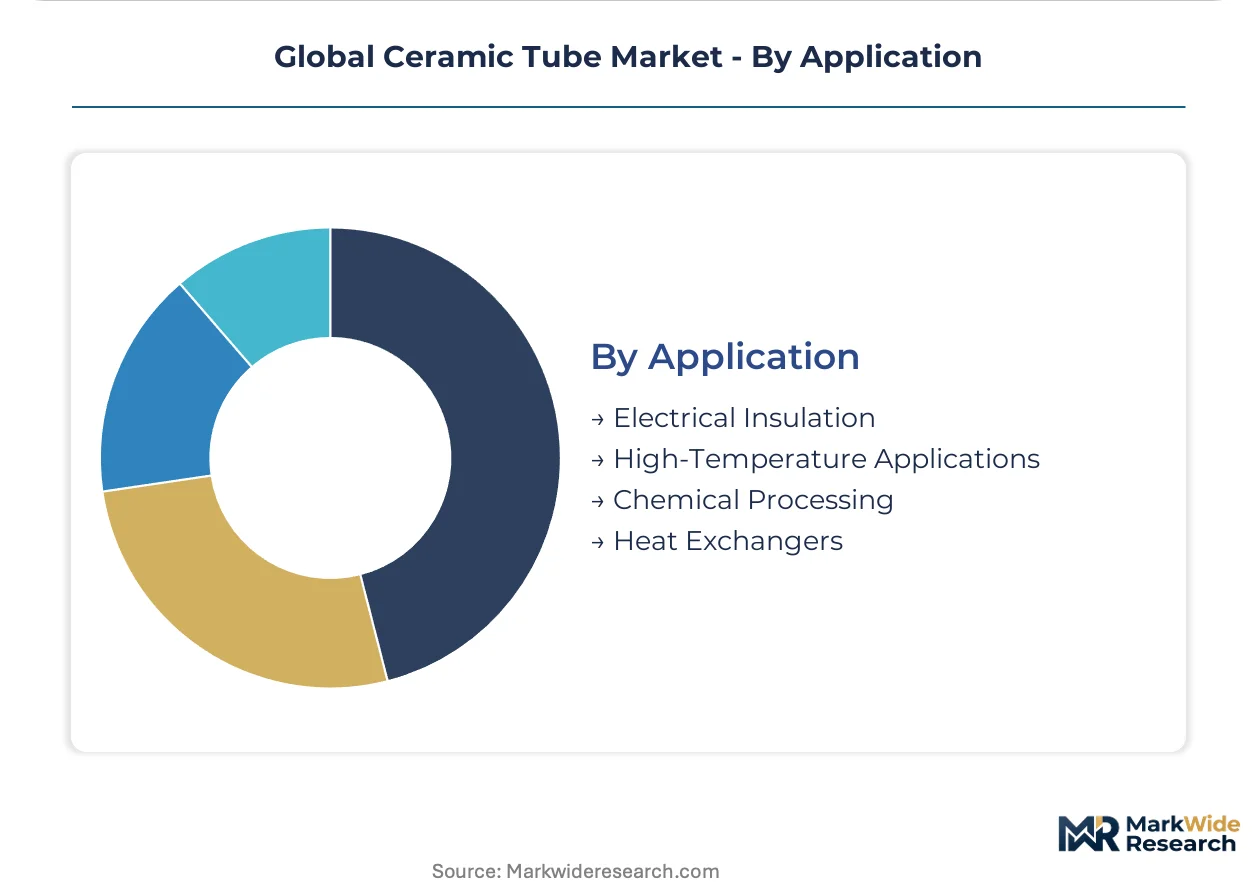
- Electrical Insulation:Dielectric barriers in power distribution, semiconductor equipment, and medical devices. German grid infrastructure investment and Japanese foundry expansion drive cross-border procurement of high-purity alumina formulations.
- High-Temperature Applications:Furnace components, jet engine thermal management, and satellite propulsion systems. US FAA certification requirements and EASA equivalent standards impose material pedigree documentation that commodity suppliers cannot satisfy.
- Chemical Processing:Corrosion-resistant conduit and reactor lining in petrochemical and pharmaceutical manufacturing. US EPA process safety management regulations and EU Seveso III directives mandate material traceability for critical containment.
- Heat Exchangers:Ceramic-to-metal brazed assemblies in hybrid electric aircraft and industrial decarbonization retrofits. German turboprop manufacturers and French electric furnace operators pioneer qualification of thermal expansion-matched joint designs.
Electrical insulation holds the largest share; heat exchangers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device OEMs in Germany, Japan, and the United States concentrate procurement leverage, while semiconductor equipment builders in Taiwan and South Korea accelerate qualification of high-purity formulations. Aerospace primes in France and satellite integrators in Switzerland lock in multi-year supply agreements before design freeze.
United States
Defense contractors and medical device OEMs drive structural tube procurement for satellite thermal management and implantable electronics housings. FDA 21 CFR Part 820 traceability requirements filter supply to certified manufacturers with captive powder refining. Colorado and Arkansas host multi-site production clusters serving aerospace and energy clients.
Germany
Grid infrastructure OEMs and rapid thermal processing equipment manufacturers anchor insulator and thermocouple tube demand. REACH Article 33 substance disclosure mandates batch-level traceability investments across ceramic converters. Bavaria and Baden-Württemberg precision ceramics clusters serve semiconductor and aerospace supply chains.
Japan
Foundries operating above 1400°C process nodes and implantable electronics manufacturers specify aluminum nitride purity thresholds. PMDA standards accelerate qualification of domestic suppliers with specialized powder-to-part capabilities. Nagoya and Osaka industrial corridors concentrate equipment OEM procurement.
South Korea
Memory and logic foundries drive thermocouple tube procurement for diffusion furnace retrofits. MFDS medical device regulations create parallel qualification tracks for implantable electronics applications. Seoul Capital Area and Busan-Ulsan manufacturing belts host semiconductor equipment supply chain clusters.
India
Domestic medical device manufacturing incentives attract ceramic tube producers to establish powder synthesis operations near Mumbai and Hyderabad device clusters. CDSCO quality system requirements align with ISO 13485 standards for orthopedic implant OEMs. PLI scheme subsidies compress qualification timelines for export-oriented producers.
Global Ceramic Tube Market Vendor Landscape
Player mix skews toward vertically integrated powder-to-part specialists with captive alumina and zirconia refining capabilities. Three archetypes dominate: Japanese and German precision ceramics conglomerates with medical-grade certifications, US-based scale producers serving defense and energy volumes, and regional specialists capturing cost-sensitive industrial applications. Competitive moves concentrate on backward integration into high-purity powder supply and geographic expansion into India's PLI-subsidized manufacturing zones.
Among Japanese precision ceramics producers, Kyocera Corporation exemplifies the vertically integrated archetype with medical-grade supply chain control. German specialists CeramTec GmbH occupy a position within the high-purity formulation tier serving implantable electronics. US-based CoorsTek, Inc. anchors the scale-driven segment with multi-site production serving defense and industrial energy clients.
| Leading Market Players |
|---|
| Kyocera Corporation |
| CeramTec GmbH |
| CoorsTek, Inc. |
| Morgan Advanced Materials |
| NGK Insulators |
| Saint-Gobain |
| Carborundum Universal |
| Rauschert GmbH |
| 3M |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with alumina and zirconia indexation lock in supply access and price visibility for medical-grade ceramic tube buyers, insulating qualified manufacturers from spot powder volatility while committing them to 18-month REACH and FDA qualification timelines that commodity suppliers cannot match.
Pricing Analysis
Cost-plus contracts indexed to high-purity alumina spot prices dominate medical and aerospace procurement, with ISO 13485-certified manufacturers commanding 40-60% premiums over industrial-grade suppliers. Three-tier pricing structure across medical-certified, aerospace-qualified, and industrial-standard levels separates segments by failure-tolerance requirements and traceability depth. Cost compression in industrial insulator tubes is intensifying because Indian PLI-subsidized producers are scaling powder synthesis capacity. Automotive Tier-1 suppliers show highest price sensitivity, while satellite integrators accept premium pricing for AS9100 material pedigree.
Supply Chain Analysis
Inbound logistics costs from Hamburg and Yokohama ports constrain just-in-time delivery to German and Japanese precision equipment OEMs, forcing ceramic tube converters to pre-position inventory near Bavaria and Nagoya industrial corridors. Supply concentrates in Germany, Japan, and the United States for qualified medical and aerospace grades, with captive alumina refining in Arkansas and Colorado serving defense clients. Raw material dependencies rest on high-purity alumina from specialized refiners, zirconia feedstock with conflict-mineral documentation, and aluminum nitride powder for implantable electronics. Single-source vulnerability in HIP densification equipment creates 24-month capacity bottlenecks for structural tube output. Distribution runs through direct fulfillment models that displace regional technical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cermet tubes with cobalt-chromium matrices threaten ceramic incumbents in mid-temperature aerospace applications, forcing substitution defense through purity escalation and qualification speed.
For Market Incumbents: Fortify backward integration into high-purity alumina and zirconia refining to secure powder allocation during demand spikes. Accelerate ISO 13485 certification timelines for sub-tier suppliers before FDA traceability mandates harden. Lock in multi-year offtake agreements with satellite integrators and orthopedic implant OEMs before design freeze eliminates late entrants. For New Entrants and Emerging Players: Lead with India's PLI-subsidized manufacturing zones near Mumbai and Hyderabad, where CDSCO-aligned quality systems compress export qualification timelines. Target hybrid electric aircraft thermal systems as a white-space segment beyond traditional jet engine supply chains. Pursue ceramic-to-metal brazed tube assemblies for heat exchanger miniaturization with German turboprop manufacturers seeking thermal expansion-matched joint designs. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated powder-to-part specialists with captive refining and existing FDA 21 CFR Part 820 certifications. Long-term viability over the next decade hinges on REACH Article 33 traceability infrastructure and PMDA-aligned purity thresholds that filter out commodity converters. Watch for ECHA enforcement actions against undocumented zirconia feedstock as an inflection indicator for batch-level transparency investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Powder Refining | Captive alumina supply insulates Kyocera and CeramTec from input cost volatility during semiconductor demand spikes. |
| ISO 13485 Supply Chain Recertification | Full sub-tier powder source qualification meets FDA 21 CFR Part 820 traceability mandates for implantable device OEMs. |
| Direct Fulfillment Model Restructuring | Bypassing regional distributors enables 48-hour replenishment commitments to consolidated orthopedic implant buyers in Germany. |
| Additive Manufacturing Preform Qualification | Complex internal geometries for thermocouple sheaths attract German semiconductor equipment OEMs seeking rapid thermal processing chamber upgrades. |
| India PLI Zone Manufacturing Establishment | Domestic powder synthesis and sintering operations near Hyderabad device clusters capture export-oriented medical tube demand. |
Methodological Framework
Initial hypotheses were tested against primary input from ceramic tube procurement managers at medical device OEMs, aerospace prime supplier quality engineers, semiconductor equipment OEMs technical directors, and powder refinery operations heads, then refined against secondary validation from FDA 510(k) filings, ECHA REACH registration databases, Japan PMDA medical device approvals, SEC 10-K disclosures from precision ceramics conglomerates, and customs trade data for high-purity alumina and zirconia imports. Bottom-up segment sizing across product types, end users, and applications was triangulated with top-down market consolidation checks.
Variance decomposition across the projection horizon isolates volume drivers by end-use segment, with semiconductor fabrication scaling, aerospace propulsion thermal management, and implantable electronics housing demand modeled separately. Segmentation dimensions include product architecture, purity certification tier, geographic regulatory cluster, and buyer consolidation level. CAGRs were derived from installed base replacement cycles, foundry capacity expansion pipelines, and satellite constellation deployment schedules tracked through FAA and EASA certification filings.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820, REACH Article 33, and Japan PMDA standards; material policy shifts would require re-modeling qualification timeline assumptions and biocompatibility testing cost structures. Specific risks include dual-use export control expansion on silicon carbide and aluminum nitride formulations, ECHA enforcement intensity on zirconia feedstock traceability, and HIP equipment capacity constraints extending aerospace structural tube lead times. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Thermal Spray Powder Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Stoneware Market
Ceramics
Aluminium Nitride Market
Ceramics
Alumina Slurry Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Strontium Carbonate Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Ceramic Binders Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Global Ceramic Foams Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Medical Ceramics Market
Ceramics
Earthenware Market
Ceramics
Europe Aluminum Oxide Market