
 Iran Ceramic Tiles Market | 2026-2036
Iran Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Ceramic Tiles Market Foresight
Digital inkjet printing is rewriting surface decoration protocols across Iranian tile factories, enabling single-run customization that cuts glaze waste and shortens design cycles. Sina Tile and Ceramic Co leverages in-house digital lines to dominate domestic premium wall tile output. Mehregan Trading Co anchors export logistics through Bandar Abbas port corridors into Central Asian markets. Ardakan Industrial Ceramics Co specializes in large-format porcelain slabs for Tehran's high-rise residential towers.
Ceramic tiles are sintered clay-based surfacing materials fired at 1,000–1,250°C, typically measuring 300×300 mm to 600×1,200 mm, engineered for abrasion resistance, moisture protection, and aesthetic cladding in built environments. Floor tiles command the largest volume share as Iran's urban housing stock modernizes, while porcelain tiles represent the fastest-expanding category due to superior density and frost resistance for outdoor applications. Mosaic tiles occupy a niche decorative segment concentrated in heritage restoration projects across Isfahan and Shiraz.
Iran's national standardization body enforces building material quality protocols that shape domestic production specifications, while the country's trade administration regulates export documentation for ceramic shipments to neighboring markets. Compliance with these frameworks determines factory certification status and cross-border market access for Iranian producers. Stakeholders must monitor shifts in construction finance availability and raw material import licensing to anticipate capacity utilization swings across the Yazd-Kashan production belt.
Market Dynamics
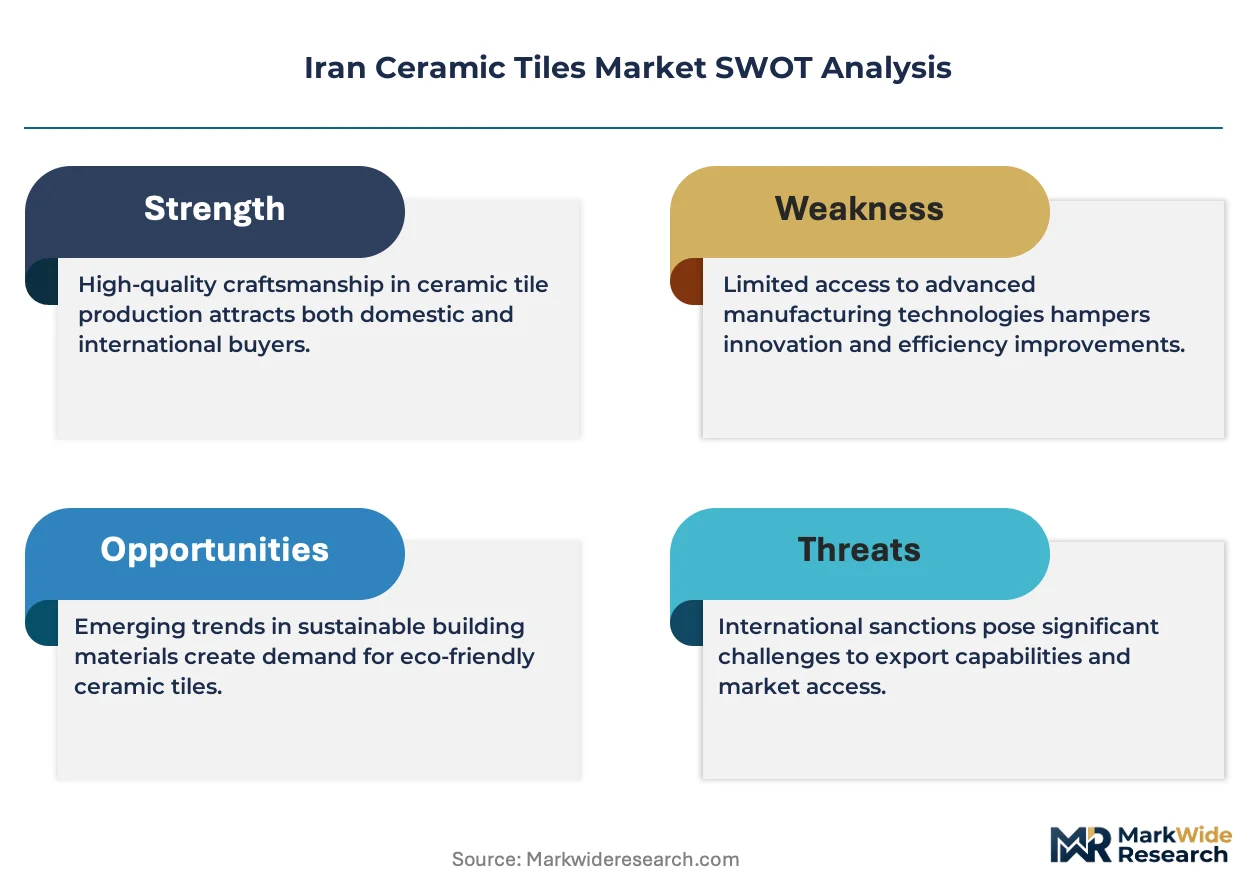
Digital inkjet printing lines are compressing design-to-production cycles across Iranian tile factories, forcing capital retooling decisions on smaller producers clustered around Yazd and Kashan.
Growth Catalysts
- Tehran residential tower construction:High-rise developers specify large-format porcelain slabs for facade cladding and interior surfacing, creating sustained pull from the capital's construction pipeline.
- Building material certification mandates:Iran's national standards body enforces updated quality protocols that favor locally manufactured glazed products over imported alternatives.
- Bandar Abbas export corridor expansion:Port infrastructure improvements enable ceramic shipments to Central Asian markets with reduced transit friction.
Market Restraints
- Frit and glaze import dependency:Iranian producers rely on imported raw materials for specialized surface finishes, exposing margins to currency fluctuation and licensing delays.
- Natural gas supply volatility:Kiln operations across the Yazd-Kashan belt face intermittent feedstock pressure from domestic energy allocation priorities.
- Substitute surfacing materials:Engineered quartz and compact sintered stone gain specification share in premium Tehran residential projects.
Strategic Opportunities
- Isfahan heritage restoration pipeline:Mosaic tile demand from monument conservation projects offers specialized production niches for artisanal manufacturers.
- Central Asian cross-border retail:Underdeveloped distribution networks in Turkmenistan and Tajikistan present first-mover channel establishment potential.
- Dual-fuel kiln technology convergence:Hybrid natural gas-electric firing systems enable producers to arbitrage energy input costs across seasonal price cycles.
Industry Challenges
- Digital print technician scarcity:Factory floors lack operators capable of calibrating multi-channel inkjet heads for complex glaze deposition patterns.
- Export documentation complexity:Compliance with destination-country certification requirements extends order fulfillment timelines for Bandar Abbas shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Ceramic Tiles Market |
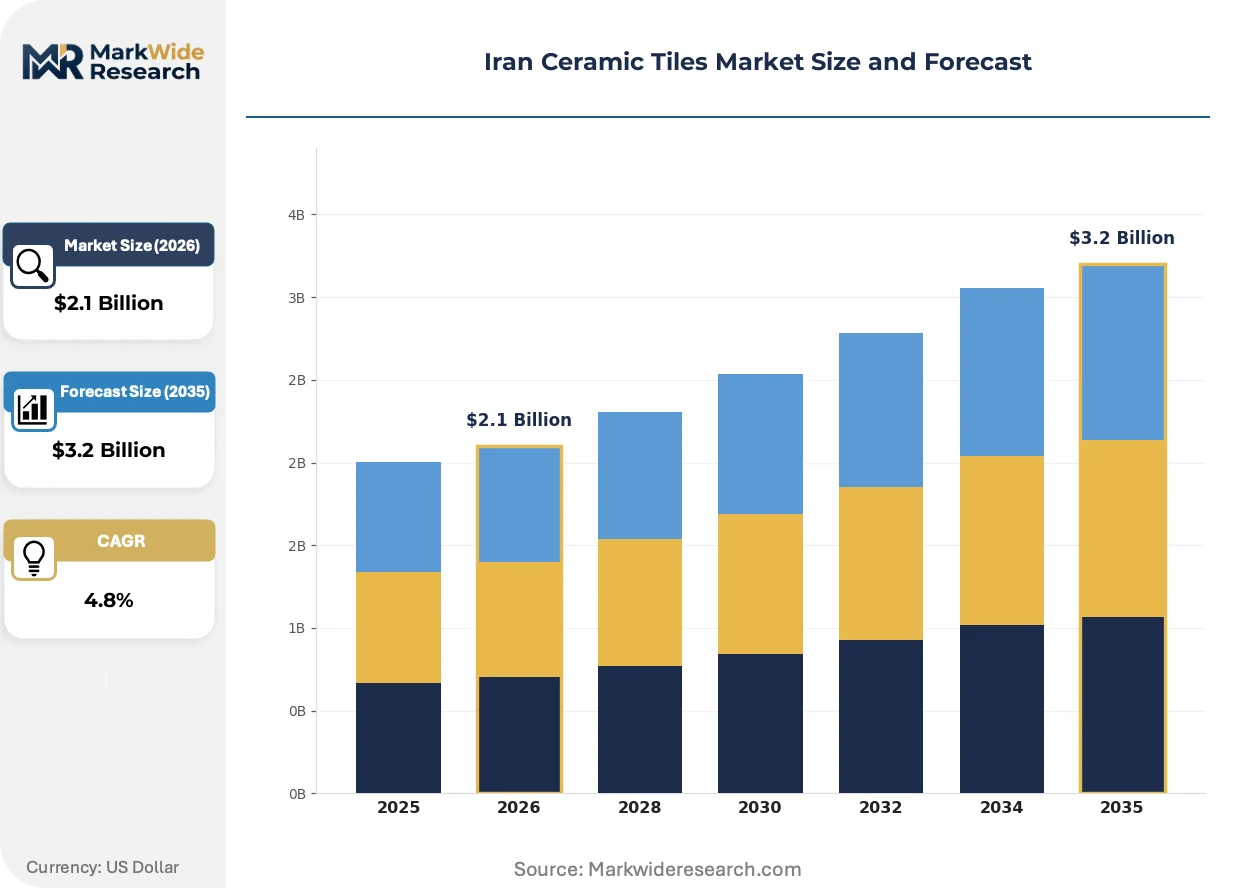
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Tiles, Wall Tiles, Mosaic Tiles, Porcelain Tiles Application: Residential, Commercial, Industrial, Outdoor Material: Ceramic, Glazed, Unglazed, Stoneware Size: Small Format, Large Format, Custom Size, Standard Size |
| Companies Covered | Mehregan Trading Co, Sina Tile and Ceramic Co, Marjan Tile Co, Saba Tile, Ardakan Industrial Ceramics Co, RAK Ceramics, Kam Ceramics, Ceramara Co, Setareh Meybod Ceramic Tile Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Ceramic Tiles Market Shifts & Advancements
Surface decoration workflows are fragmenting into shorter production runs with higher design variability, compressing the economic viability of traditional screen-printing investments.
Single-pass digital inkjet systems are hybridizing conventional glaze application with photorealistic surface reproduction, merging technical performance with aesthetic customization. Tehran luxury residential developers specify these digitally printed slabs for lobby and bathroom installations. The technology is hybridizing inventory models—factories now produce to confirmed orders rather than speculative stock, reducing working capital intensity.
Iran's national standards body mandates updated building material certifications that require factory-level quality management system documentation. Compliance audits now extend to raw material traceability and finished product frost-resistance testing. Glazed wall tile producers face the tightest compliance timelines, with certification renewal cycles compressing from biennial to annual intervals.
Specification authority is migrating from general contractors to interior design studios in Tehran's high-end residential segment. Design studios now source tiles directly from Kashan manufacturers, disintermediating traditional distributor relationships. This channel compression is most visible in north Tehran luxury tower projects, where design-led procurement reduces standard product markups.
Iran Ceramic Tiles Market Segmentation
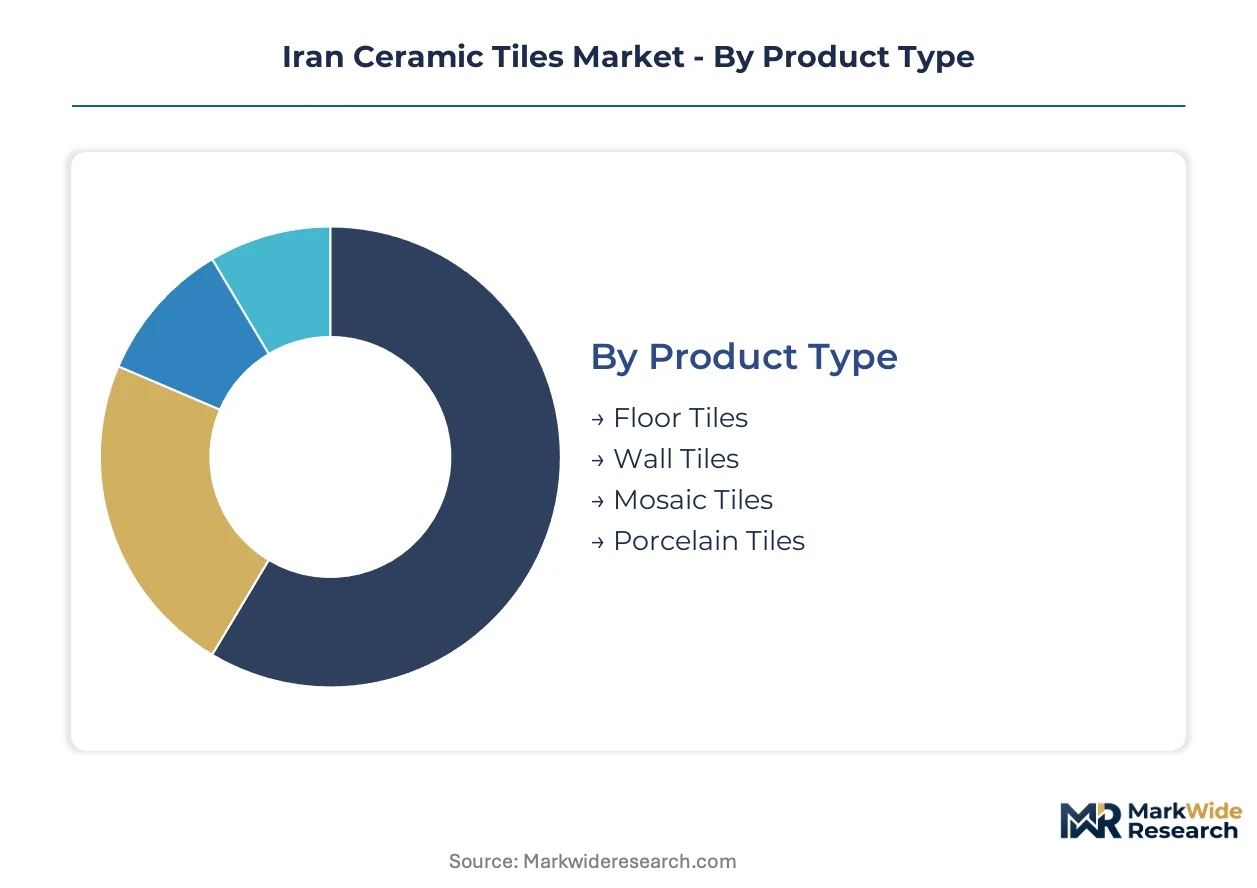
Segmentation reveals how Iranian tile manufacturers align production capabilities with distinct construction workflows. Each dimension—product type, application, material composition, and dimensional format—carries specific technical requirements that shape factory equipment decisions and raw material procurement patterns.
Product Type:
Floor tiles dominate residential tower specifications across Tehran's northern districts, while wall tiles anchor decorative surfacing in commercial interiors. Mosaic tiles serve heritage conservation projects, and porcelain slabs penetrate high-rise facade applications.
- Floor Tiles:Engineered for abrasion resistance with higher clay density and thicker glaze layers. Tehran high-rise developers specify these for apartment interiors, though competition from engineered stone intensifies in premium segments.
- Wall Tiles:Lighter body composition prioritizes decorative surface finish over structural load-bearing. Kashan factories dominate output through digital inkjet lines that enable rapid pattern customization for Isfahan hotel and retail projects.
- Mosaic Tiles:Small-format tesserae assembled for decorative borders and heritage restoration. Isfahan's monument conservation pipeline sustains artisanal production clusters.
- Porcelain Tiles:Fired at higher temperatures for superior density and frost resistance. Yazd manufacturers specialize in large-format slabs for outdoor applications and facade cladding.
The dominant share belongs to Floor Tiles, while Porcelain Tiles is closing the gap fastest.
Application:
Cost tier stratification separates mass housing from luxury residential and commercial specifications. Residential construction absorbs volume production, while commercial and industrial segments demand certified durability ratings.
- Residential:Volume consumption concentrates in Tehran and Isfahan provinces where housing stock modernization drives replacement cycles. Developers specify mid-range glazed products for cost-controlled apartment projects.
- Commercial:Hotels, retail centers, and office towers require slip-resistant ratings and stain-resistant glazes. Tehran's north district luxury developments source directly from Kashan design studios.
- Industrial:Chemical resistance and heavy-load tolerance define specifications for factory floors and warehouse surfacing. Limited domestic production capacity forces reliance on imported technical ceramics.
- Outdoor:Frost resistance and UV stability are mandatory for Iran's continental climate extremes. Porcelain slabs from Yazd clusters penetrate this segment through Bandar Abbas export corridors.
Residential commands the volume base, yet Commercial applications deliver the steepest margin expansion.
Material:
Supply concentration around Yazd and Kashan determines material availability, with glazed products benefiting from localized frit production. Unglazed and stoneware categories face raw material import dependencies.
- Ceramic:Standard clay-based body fired at conventional temperatures. Mass housing projects across Tehran's peripheral districts absorb this volume production.
- Glazed:Surface glass layer enables decorative variation and moisture protection. Iran's national standards body mandates updated certification protocols favoring domestic glazed output over imports.
- Unglazed:Natural clay finish prized for slip resistance in industrial and outdoor applications. Limited local sourcing of specialized clays constrains capacity expansion.
- Stoneware:Higher firing temperatures yield vitrified, non-porous bodies. Technical specifications align with European export requirements, though domestic demand remains narrow.
Glazed products hold the certification advantage, while Unglazed variants are climbing fastest on industrial project specifications.
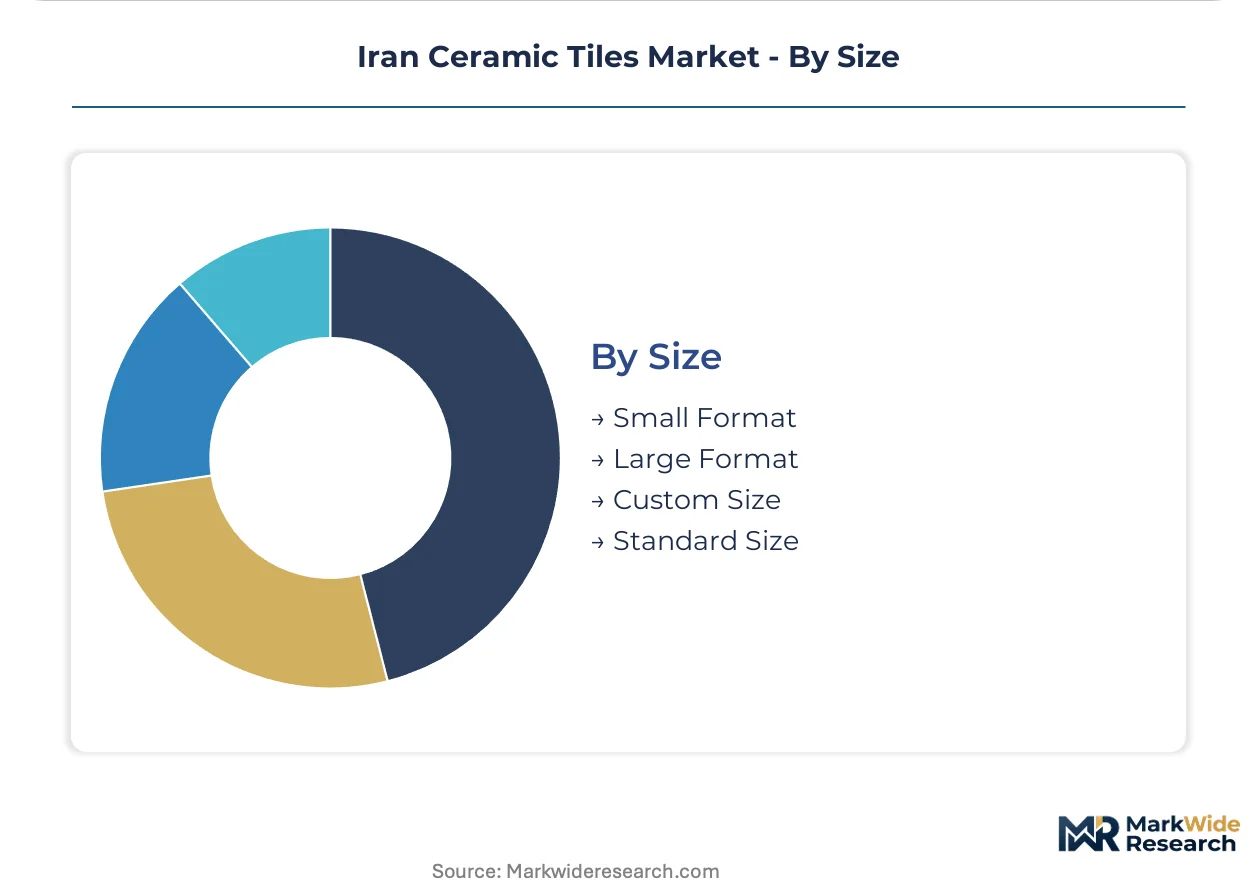
Size:
Customer type stratification separates speculative stock production from confirmed-order manufacturing. Large formats dominate design-led procurement, while standard sizes sustain distributor inventory models.
- Small Format:Traditional dimensions suit renovation projects and budget residential construction. Kashan factories maintain screen-printing lines for this volume segment.
- Large Format:Slabs exceeding 600×1200 mm require specialized pressing and firing equipment. Tehran luxury tower lobbies and bathrooms specify these for seamless surface aesthetics.
- Custom Size:Project-specific dimensions produced to confirmed orders rather than speculative stock. Design studios in north Tehran source directly from manufacturers, compressing traditional distribution margins.
- Standard Size:300×300 mm and 600×600 mm dimensions dominate distributor inventories across Iran's provincial markets. Price competition intensifies as digital printing democratizes surface decoration.
Standard Size retains the volume position, though Large Format is expanding most quickly on high-rise construction specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iran's ceramic tile production exceeds domestic absorption, creating persistent export surplus pressure through Bandar Abbas corridors into Central Asian markets. The trade balance dynamics shape capacity decisions across the Yazd-Kashan production belt. Provincial construction cycles determine where inventory accumulates versus clears.
Tehran Province
High-rise residential towers in northern districts specify large-format porcelain slabs for facade cladding and interior surfacing. The national standards body mandates updated building material certifications that favor locally manufactured glazed products. Shahr-e Qods and Parand industrial zones host pressing and firing facilities supplying the capital's construction pipeline.
Isfahan Province
Heritage restoration projects across Naqsh-e Jahan Square and Safavid monument complexes sustain artisanal mosaic tile demand. The province's cultural heritage administration enforces conservation material specifications that privilege traditional production methods. Kashan ceramic clusters anchor decorative wall tile output through digital inkjet lines serving hotel and retail interiors.
Yazd Province
Continental climate extremes drive frost-resistant porcelain specifications for outdoor applications and desert-facing construction. Energy allocation priorities from the national gas distribution network intermittently constrain kiln operations across the Ardakan industrial corridor. Meybod tile factories specialize in large-format slabs exported through Bandar Abbas to Turkmenistan and Tajikistan.
Kashan County
Design studios in north Tehran source directly from Kashan manufacturers, compressing traditional distributor relationships and reducing standard product markups. The county's technical and vocational training system struggles to supply digital print technicians capable of calibrating multi-channel inkjet heads. Finishing facilities cluster along the Qom-Kashan highway corridor.
Bandar Abbas Corridor
Port infrastructure improvements enable ceramic shipments to Central Asian markets with reduced transit friction. The trade administration regulates export documentation compliance, extending order fulfillment timelines for cross-border consignments. Warehouse consolidation near the container terminal supports just-in-time loading for Uzbekistan and Afghanistan-bound freight.
Iran Ceramic Tiles Market Competitive Landscape
On the supply side, the industry is fragmented across family-owned production clusters with limited inter-factory consolidation. Capacity scales range from artisanal mosaic workshops to integrated porcelain slab facilities. Three archetypes dominate: design-forward digital print specialists, export-logistics integrators, and large-format technical producers. Competitive moves center on direct procurement relationships with Tehran design studios and backward integration into frit formulation.
Among domestic fabricators, Sina Tile and Ceramic Co, Mehregan Trading Co, and Ardakan Industrial Ceramics Co occupy distinct positioning vectors. Sina Tile exemplifies the design-forward archetype through in-house digital decoration capabilities. Mehregan Trading represents the export-logistics integrator model, anchoring cross-border shipment coordination through southern port infrastructure. Ardakan Industrial Ceramics sits within the large-format technical tier, serving high-rise construction specifications. These three entities collectively illustrate how Iranian producers partition the value chain across decoration technology, distribution control, and dimensional capability.
| Leading Market Players |
|---|
| Mehregan Trading Co |
| Sina Tile and Ceramic Co |
| Marjan Tile Co |
| Saba Tile |
| Ardakan Industrial Ceramics Co |
| RAK Ceramics |
| Kam Ceramics |
| Ceramara Co |
| Setareh Meybod Ceramic Tile Co |
| Others |
Supply & Pricing Matrix
Yazd-Kashan production belt capacity utilization swings directly determine downstream pricing power across Iran's ceramic tile distribution networks. Tehran design studios and provincial distributors face divergent cost structures depending on which cluster supplies their inventory.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Iran's ceramic tile market. Price differentiation separates certified glazed products meeting national standards body protocols from unglazed industrial grades and artisanal mosaic outputs. Cost compression in standard-format wall tiles is intensifying because digital inkjet printing democratizes surface decoration. Mass housing developers exhibit highest price sensitivity, while north Tehran luxury tower projects show relative inelasticity for large-format porcelain slabs.
Supply Chain Analysis
Export-control regimes on advanced digital inkjet printing heads constrain technology flows into Iranian tile factories, forcing reliance on older-generation equipment or third-country sourcing. Supply concentrates in Iran's domestic Yazd and Kashan clusters, with secondary inputs drawn from China and India for specialized frits and glazes. Raw material dependencies rest on imported zirconium silicates, titanium dioxide, and digital printing inks. Single-source vulnerability around Bandar Abbas port logistics creates chokepoint risk for Central Asian-bound shipments. Distribution runs through direct manufacturer-to-studio relationships in Tehran's luxury segment and traditional provincial distributor networks elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's ceramic tile market represents an early-cycle expansion story, with digital printing penetration in surface decoration still below saturation levels across Yazd and Kashan factory floors.
For Market Incumbents: Harden defensible positions by deepening backward integration into frit formulation to offset imported raw material currency exposure. Secure captive natural gas supply arrangements with the national distribution network to insulate kiln operations from seasonal allocation volatility. These moves counter substitute surfacing materials—engineered quartz and compact sintered stone—gaining specification share in premium Tehran residential projects.
For New Entrants and Emerging Players: Turkmenistan and Tajikistan's underdeveloped ceramic distribution networks present first-mover channel establishment potential through Bandar Abbas corridor logistics. Target heritage restoration material supply as a specialized niche, sourcing mosaic tile contracts from Isfahan's monument conservation pipeline. Establish direct procurement relationships with Tehran interior design studios to bypass traditional distributor markups in north Tehran luxury tower projects.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because family-owned production clusters across Yazd-Kashan lack inter-factory merger activity despite complementary capability profiles. Target acquisition archetypes include digital print specialists with in-house decoration lines and export-logistics integrators controlling Bandar Abbas warehouse consolidation. Monitor shifts in construction finance availability from Iran's banking sector as an inflection indicator for capacity utilization recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Frit Production | Captive supply of glaze raw materials insulates margins from rial fluctuation against import licensing delays. |
| Dual-Fuel Kiln Technology Deployment | Hybrid natural gas-electric firing enables energy input cost arbitrage across seasonal price cycles in the Yazd belt. |
| Direct Design Studio Procurement Channel | Bypassing traditional distributors captures margin compression in north Tehran luxury residential specifications. |
| Central Asian Distribution Network Establishment | First-mover positioning in Turkmenistan and Tajikistan leverages Bandar Abbas port infrastructure improvements. |
| Digital Print Technician Training Program | Addressing factory floor scarcity of multi-channel inkjet calibration skills sustains decoration line utilization rates. |
Research Methodology
A spread of perspectives from ceramic plant managers, Tehran design studio procurement leads, Bandar Abbas logistics coordinators, and Kashan frit supply specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from Iran's national standards body certification records, customs export documentation filings, and provincial industrial zone capacity registries. Bottom-up factory output estimates triangulated against top-down construction sector absorption projections across the analysis window.
Demand-supply balance modeling anchored the forecast framework, with segmentation dimensions spanning product type, application tier, material composition, and dimensional format. CAGRs were derived from capacity expansion pipelines and residential construction permit trajectories. Key inputs included natural gas allocation priorities from the national distribution network and digital printing line installation rates across Yazd-Kashan clusters.
Practitioners should monitor construction finance availability from Iran's banking sector and raw material import licensing timelines for early signals requiring forecast revision. Cross-checking against provincial industrial zone employment and energy consumption benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Barium Carbonate Powder Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Nanoceramic Powder Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Zirconium Dioxide Market
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Ceramic Additives Market
Ceramics
Stoneware Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Mullite Market
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
ME K-Feldspar Market
Ceramics
Aluminium Nitride Market
Ceramics
Fly Ash and Ceramic Microsphere Market