
 Organic Binders Market | 2026-2036
Organic Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Binders Market Outlook
Multi-source procurement of bio-based feedstocks is expanding across the organic binders value chain as formulators reduce dependency on single-origin petrochemical supplies. BASF SE leverages its integrated polymer research network to sustain leadership in cellulose ether derivatives for construction applications. Wacker Chemie AG anchors its position through captive silicone-organic hybrid technologies, while Celanese Corporation competes in emulsion binders for paper coatings through specialized acetylation processes. DuPont de Nemours Inc. differentiates via bioengineered protein platforms that target adhesive end-uses with controlled viscosity profiles.
Organic binders comprise naturally derived or synthetically modified polymeric substances—typically possessing molecular weights between 10,000 and 1,000,000 Daltons—that cohere particulate matter or laminate substrates through film formation, hydrogen bonding, or entanglement mechanisms. These materials function primarily to replace formaldehyde-emitting synthetic resins in construction panels, paper coatings, textile sizing, and food-grade adhesives where volatile organic compound thresholds apply. Cellulose derivatives currently dominate value capture in construction-grade pastes and powders due to established supply chains and predictable rheological performance under variable humidity. Starch-based emulsions represent the fastest-expanding product class as paper manufacturers retrofit coating lines to run aqueous systems at higher solids content. Protein-based granules occupy a premium niche in textile sizing applications where biodegradability mandates from EU Ecolabel criteria reshape procurement specifications.
REACH registration requirements and the EU F-Gas Regulation constrain formulation choices for binders imported into Europe, while India's BIS compulsory registration scheme and China's SAMR-administered GB standards enforce VOC disclosure thresholds that favor waterborne emulsions over solvent systems. The US EPA Toxic Substances Control Act and OSHA permissible exposure limits further segment market access based on formaldehyde content declarations and worker safety documentation. Stakeholders must monitor evolving biopolymer certification schemes and feedstock traceability mandates to secure long-term supply contracts and avoid disqualification from public procurement frameworks.
Market Dynamics
EU Green Deal enforcement and India's BIS certification mandates are compressing formulation windows for synthetic resin alternatives, redirecting procurement toward starch-based and cellulose ether systems with verified low-VOC credentials.
Growth Catalysts
- REACH registration thresholds:European formulators face mandatory substance disclosure for imported binders above one tonne annually, accelerating substitution toward pre-registered cellulose derivatives.
- Paper coating retrofit cycles:Asian manufacturers are converting solvent-based lines to aqueous starch emulsions to meet SAMR-administered GB standards for packaging adhesives.
- Construction chemical procurement:German contractors now specify protein-based granules for interior panel lamination under tightened workplace exposure protocols.
Market Restraints
- Feedstock concentration risk:Specialty cellulose ether supply chains cluster in China's eastern manufacturing corridor, exposing formulators to single-origin disruption.
- Natural latex price volatility:Hevea brasiliensis harvest fluctuations in Southeast Asia compress margin predictability for waterborne emulsion producers.
- Technical performance ceilings:Starch-based systems exhibit humidity-sensitive viscosity drift that limits deployment in tropical construction applications.
Strategic Opportunities
- Brazilian packaging sector:ANVISA's pending biodegradability mandates for food-contact adhesives create first-mover positioning for protein-based granule suppliers.
- Silicone-organic hybrid convergence:Wacker Chemie's captive silicone technology offers pathways to temperature-stable binders for automotive interior lamination.
- Direct mill procurement channels:Paper manufacturers are bypassing distributors to contract directly with acetylated starch producers for coating line feedstock.
Industry Challenges
- Biopolymer certification timelines:EU Ecolabel biodegradability verification requires 18-24 month laboratory cycles that delay contract eligibility.
- Rheology formulation expertise gap:Construction chemical compounders lack trained specialists to match cellulose ether grades to variable humidity substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Binders Market |
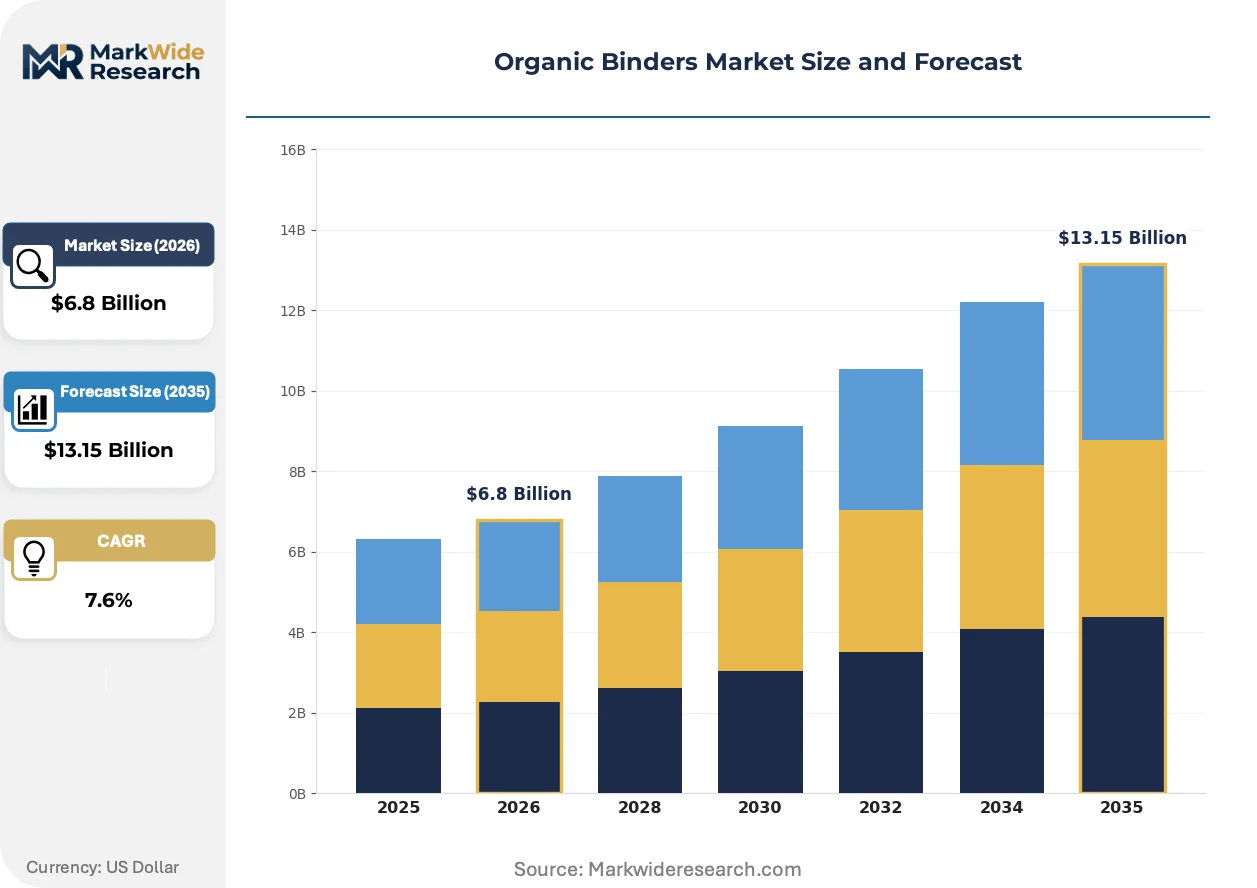
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Latex, Starch-Based, Cellulose, Protein-Based Application: Construction, Paper Industry, Textile, Adhesives End User: Manufacturers, Contractors, Textile Producers, Bakeries Operating Form: Pastes, Powders, Granules, Emulsions |
| Companies Covered | Ashland Inc., Oilex International GmbH, BASF SE, Harmony Additive Pvt. Ltd., ENDURA IPNR, Wacker Chemie AG, Celanese Corporation, Empower Materials Inc., DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Binders Market Strategic Shifts
Formulation science is pivoting toward hybrid natural-synthetic architectures that preserve process compatibility while satisfying multi-jurisdiction VOC thresholds.
Enzymatically modified starch derivatives with tailored amylopectin branching are overtaking unmodified native starch in high-speed paper coating lines. Korean packaging converters have adopted these systems at commercial scale since 2023. The technology is overtaking conventional oxidized starch in applications requiring solids content above 65% without viscosity breakdown.
China's SAMR enforcement of GB 33372-2020 for low-VOC adhesives is eliminating solvent-based formaldehyde resins from construction panel manufacturing. Domestic producers must submit third-party test reports for every formulation variant. Wood-based panel mills in Shandong and Jiangsu provinces are retrofitting spray lines to accommodate waterborne protein binders with extended open times.
Specification-driven procurement now dominates construction chemical buying, where architects embed binder chemistry requirements directly into tender documents rather than delegating to subcontractor discretion. Distributor technical sales roles are contracting as mill procurement teams build in-house formulation literacy. This pattern concentrates in German commercial construction, where EU Green Deal carbon accounting rules flow through to material selection clauses.
Organic Binders Market Segmentation
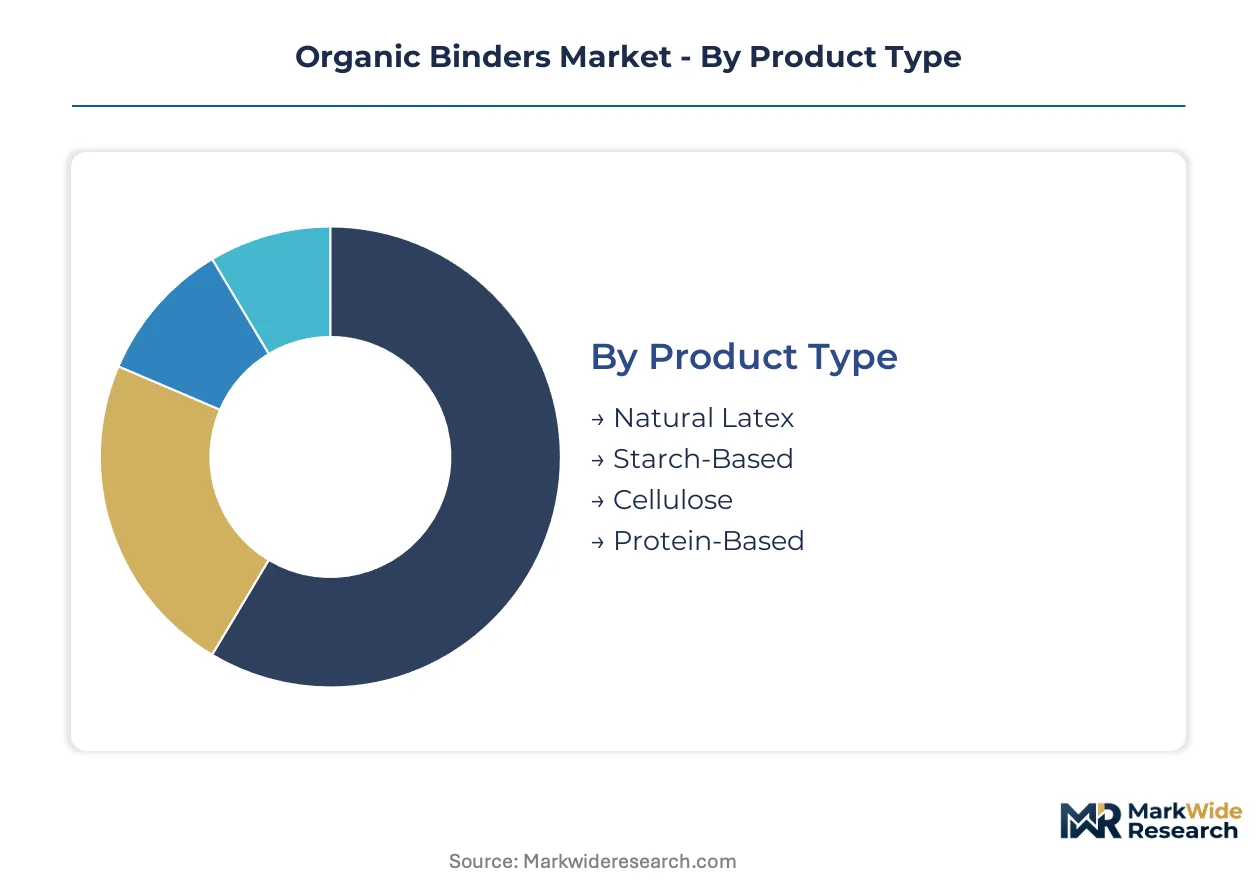
Formulation chemistry dictates procurement specifications across construction, paper, and textile verticals. Buyers segment organic binders by technical performance thresholds rather than price alone, with VOC compliance and humidity stability filtering supplier shortlists before commercial negotiations begin.
Product Type:
Procurement teams prioritize rheological predictability and regulatory pre-certification when selecting binder chemistry platforms.
- Cellulose:Ether derivatives dominate construction-grade applications through established supply chains and consistent viscosity profiles under variable humidity. German contractors specify these systems for interior panel lamination under tightened workplace exposure protocols.
- Starch-Based:Enzymatically modified amylopectin structures enable high-solids coating without viscosity breakdown. Asian paper manufacturers retrofit solvent-based lines to run aqueous starch emulsions at solids content above 65 percent.
- Natural Latex:Hevea brasiliensis-derived emulsions serve waterborne adhesive formulations where elasticity and film formation balance.
- Protein-Based:Bioengineered platforms target textile sizing and food-grade adhesives with controlled biodegradability credentials under EU Ecolabel criteria.
Cellulose leads on scale; starch-based systems lead on momentum.
Application:
End-use specifications flow from regulatory enforcement rather than discretionary preference.
- Construction:Building codes under the EU Green Deal and India's BIS mandates compress formulation windows toward low-VOC cellulose and protein systems. Panel manufacturers in Shandong province submit third-party test reports for every formulation variant.
- Paper Industry:Coating line retrofits favor enzymatically modified starch derivatives with extended open times and stable solids handling. Korean packaging converters adopted these systems at commercial scale.
- Textile:EU Ecolabel biodegradability mandates reshape procurement specifications for sizing applications, favoring protein-based granules over synthetic alternatives.
- Adhesives:SAMR-enforced GB standards eliminate solvent-based formaldehyde resins from packaging adhesive formulations.
Construction commands volume concentration; paper industry applications climb fastest.
End User:
Specification authority determines contract structure and technical support requirements.
- Contractors:German commercial construction teams embed binder chemistry requirements directly into tender documents under EU Green Deal carbon accounting rules.
- Manufacturers:Wood-based panel mills in China's eastern manufacturing corridor build in-house formulation literacy and bypass distributor channels.
- Textile Producers:Sizing operations prioritize biodegradability verification timelines of 18-24 months to secure EU Ecolabel eligibility.
- Bakeries:Food-grade adhesive applications demand protein-based systems with traceable feedstock documentation for ANVISA and FDA compliance.
Manufacturers lead on procurement scale; contractors lead on specification authority.
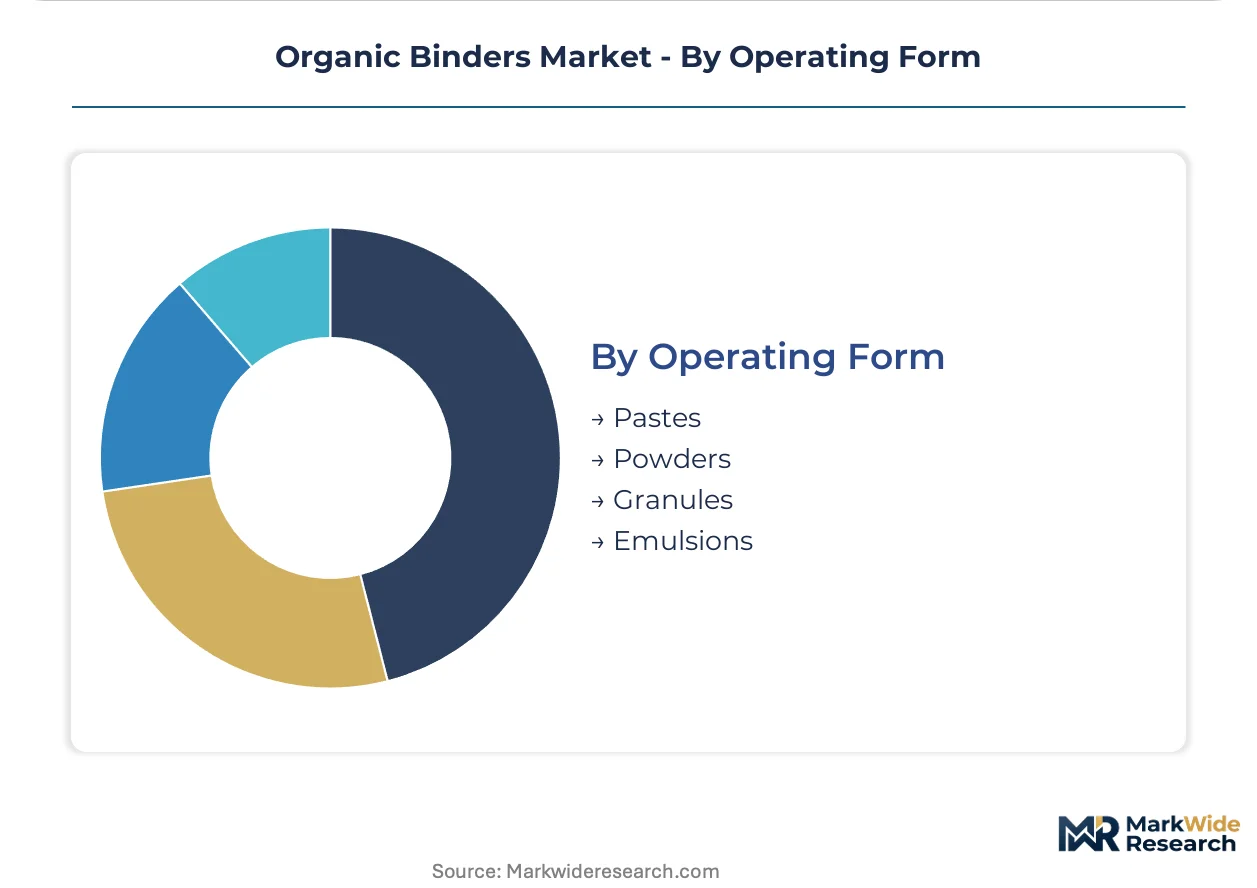
Operating Form:
Process compatibility and handling logistics segment buyer preferences by production line configuration.
- Emulsions:Waterborne systems dominate paper coating retrofits where SAMR GB standards mandate VOC thresholds. Asian manufacturers convert solvent lines to accommodate aqueous protein and starch formulations.
- Powders:Cellulose ether derivatives ship as dry concentrates for construction paste reconstitution at point of use.
- Granules:Protein-based sizing agents arrive as controlled-dissolution granules for textile bath applications requiring precise viscosity management.
- Pastes:Pre-hydrated cellulose systems serve ready-to-apply construction adhesives where humidity stability varies.
Emulsions lead on format adoption; granules lead on premium application growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates cellulose ether production capacity while regulatory enforcement across multiple jurisdictions redirects formulation choices toward low-VOC alternatives. Procurement patterns diverge sharply between mature markets with specification-driven buying and emerging economies with cost-sensitive retrofit cycles.
China
Wood-based panel mills in Shandong and Jiangsu provinces retrofit spray lines for waterborne protein binders as SAMR enforces GB 33372-2020 VOC thresholds. Domestic producers submit third-party test reports for every formulation variant under tightened disclosure mandates. The Yangtze River Delta hosts the densest concentration of acetylated starch capacity serving paper coating conversions.
Germany
Commercial construction teams embed binder chemistry requirements directly into tender documents under EU Green Deal carbon accounting rules. REACH registration thresholds above one tonne annually accelerate substitution toward pre-registered cellulose derivatives. The Rhine-Ruhr industrial corridor sustains demand for interior panel lamination systems with verified workplace exposure credentials.
India
BIS compulsory registration schemes compress formulation windows for imported synthetic resins, redirecting procurement toward starch-based and cellulose ether alternatives. Construction contractors in Maharashtra and Gujarat expand sourcing of bio-based feedstocks as building codes tighten. The western industrial belt clusters retrofit activity for aqueous emulsion coating lines.
United States
EPA Toxic Substances Control Act enforcement segments market access based on formaldehyde content declarations and worker safety documentation. Food-grade adhesive applications in the Midwest demand protein-based systems with traceable feedstock documentation for FDA compliance. The Ohio River Valley concentrates construction chemical distribution serving specification-driven commercial projects.
Brazil
ANVISA's pending biodegradability mandates for food-contact adhesives create positioning opportunities for protein-based granule suppliers. Packaging converters in São Paulo state evaluate enzymatically modified starch derivatives for high-solids coating compatibility. The southeastern manufacturing belt leads retrofit investment ahead of anticipated regulatory finalization.
Organic Binders Market Competitive Environment
Global majors compete with regional champions across certification depth and feedstock integration levels. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive polymer research networks, mid-scale specialists with focused application expertise, and regional formulators serving localized regulatory windows. Strategic moves concentrate on backward integration into bio-based feedstock supply and direct mill procurement channel development.
Within the integrated chemical tier, BASF SE and Wacker Chemie AG exemplify divergent technology anchoring strategies. BASF leverages its polymer research network across cellulose ether derivatives, while Wacker Chemie occupies a position through silicone-organic hybrid capabilities. Celanese Corporation sits within the specialty emulsion segment, representing acetylation-process expertise for paper coating applications. DuPont de Nemours Inc. anchors the bioengineered protein platform niche targeting controlled viscosity profiles for adhesive end-uses.
| Leading Market Players |
|---|
| Ashland Inc. |
| Oilex International GmbH |
| BASF SE |
| Harmony Additive Pvt. Ltd. |
| ENDURA IPNR |
| Wacker Chemie AG |
| Celanese Corporation |
| Empower Materials Inc. |
| DuPont de Nemours Inc. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon accounting rules gate qualified supply for premium-tier cellulose ether and protein-based binders, compressing accessible vendor pools while elevating price floors for certified formulations. Procurement teams in Germany and China now face bifurcated markets where pre-certified supply commands structural premiums over uncertified alternatives.
Pricing Analysis
Input-cost pass-through from Hevea brasiliensis harvest volatility and specialty cellulose pulp premiums shapes contract structures across waterborne emulsion tiers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered cellulose derivatives from provisional-grade starches and uncertified natural latex. Pricing pressure stems from feedstock concentration in China's eastern corridor, where single-origin disruption risk elevates security premiums. Small-scale textile sizing operations exhibit highest price sensitivity, while German commercial contractors prioritize specification compliance over unit cost.
Supply Chain Analysis
Certification timelines for EU Ecolabel and BIS registration gate supplier qualification, extending onboarding cycles for new feedstock sources. Manufacturing concentration clusters in China, Germany, and India, with specialty cellulose ether capacity anchored in the Yangtze River Delta and Rhine-Ruhr corridor. Raw material dependencies center on acetylated starch feedstocks, bioengineered protein platforms, and natural latex emulsions. Single-source vulnerability runs through Southeast Asian Hevea plantations exposed to climate volatility. Distribution runs through direct mill procurement channels as paper manufacturers bypass distributor networks for coating line feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic binders market represents a late-cycle quality story where specification-driven procurement favors suppliers with verified low-VOC credentials and pre-certified biodegradability profiles. Demand is concentrating toward premium-tier cellulose and protein systems as building codes tighten across multiple jurisdictions.
For Market Incumbents: Hedge against feedstock concentration risk by securing multi-origin cellulose pulp contracts and captive acetylation capacity in India. BASF SE and Wacker Chemie AG should reinforce channel control through direct mill procurement partnerships, as distributor technical sales roles contract. Certification investment in EU Ecolabel pre-approval buffers against 18-24 month verification delays that disqualify competitors from public tenders. For New Entrants and Emerging Players: Launch via direct-to-mill distribution models targeting Brazilian packaging converters ahead of ANVISA's final biodegradability mandates. The most penetrable white-space sits in enzymatically modified starch derivatives for high-solids paper coating, where Korean converters have validated commercial scale. Positioning around protein-based granules for textile sizing exploits EU Ecolabel procurement reshaping and avoids incumbent-dominated construction cellulose markets. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale acetylated starch specialists because direct procurement channel development requires concentrated application expertise that fragments across regional formulators. Long-term viability favors platforms with backward integration into bio-based feedstock supply and SAMR pre-certification for GB 33372-2020 compliance. The signal to watch is BIS compulsory registration scheme expansion into additional construction chemical categories, which would replicate India's procurement redirection in adjacent markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captive supply of acetylated starch secures margin stability against Hevea price volatility. |
| EU Ecolabel Pre-Certification Investment | Early biodegradability verification locks in 18-24 month lead time for textile sizing contracts. |
| Direct Mill Procurement Channel Development | Bypassing distributors captures specification authority as paper manufacturers build in-house formulation literacy. |
| Silicone-Organic Hybrid R&D Expansion | Wacker Chemie's captive technology enables temperature-stable binders for automotive interior lamination. |
| SAMR GB 33372-2020 Compliance Infrastructure | Third-party test report capability qualifies suppliers for Shandong and Jiangsu panel mill retrofits. |
Study Parameters
Multiple input streams — formulation chemistry databases, regulatory filing repositories, and procurement pattern tracking — were reconciled to construct demand estimates across construction, paper, and textile verticals. Primary interviews with construction chemical compounders, paper coating line engineers, textile sizing operations managers, and SAMR compliance officers informed specification-driven buying behavior. Secondary validation drew from REACH registration databases, BIS compulsory registration schemes, GB standards disclosure records, and customs trade flows. Bottom-up capacity modeling and top-down end-use consumption estimates were triangulated against supplier shipment patterns.
Historical volume trajectories were cross-referenced against panel input from procurement directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include formulation chemistry platform, operating form, end-use vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating VOC threshold enforcement timelines and coating line retrofit cycles. Industry-specific forecast inputs encompassed starch solids content handling limits and protein-based granule dissolution rate specifications.
Several conditions sit outside the modeled scope, including unforeseen biopolymer feedstock crop failures, abrupt REACH substance restriction amendments, and currency fluctuation impacts on import-dependent markets. Forecasts reflect documented assumptions about regulatory enforcement consistency and certification timeline stability. A model refresh is warranted upon material change in EU Green Deal implementation pace or ANVISA mandate finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
Azelaic Acid Market