
 Global Wollastonite Powder Market | 2026-2036
Global Wollastonite Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wollastonite Powder Market Outlook
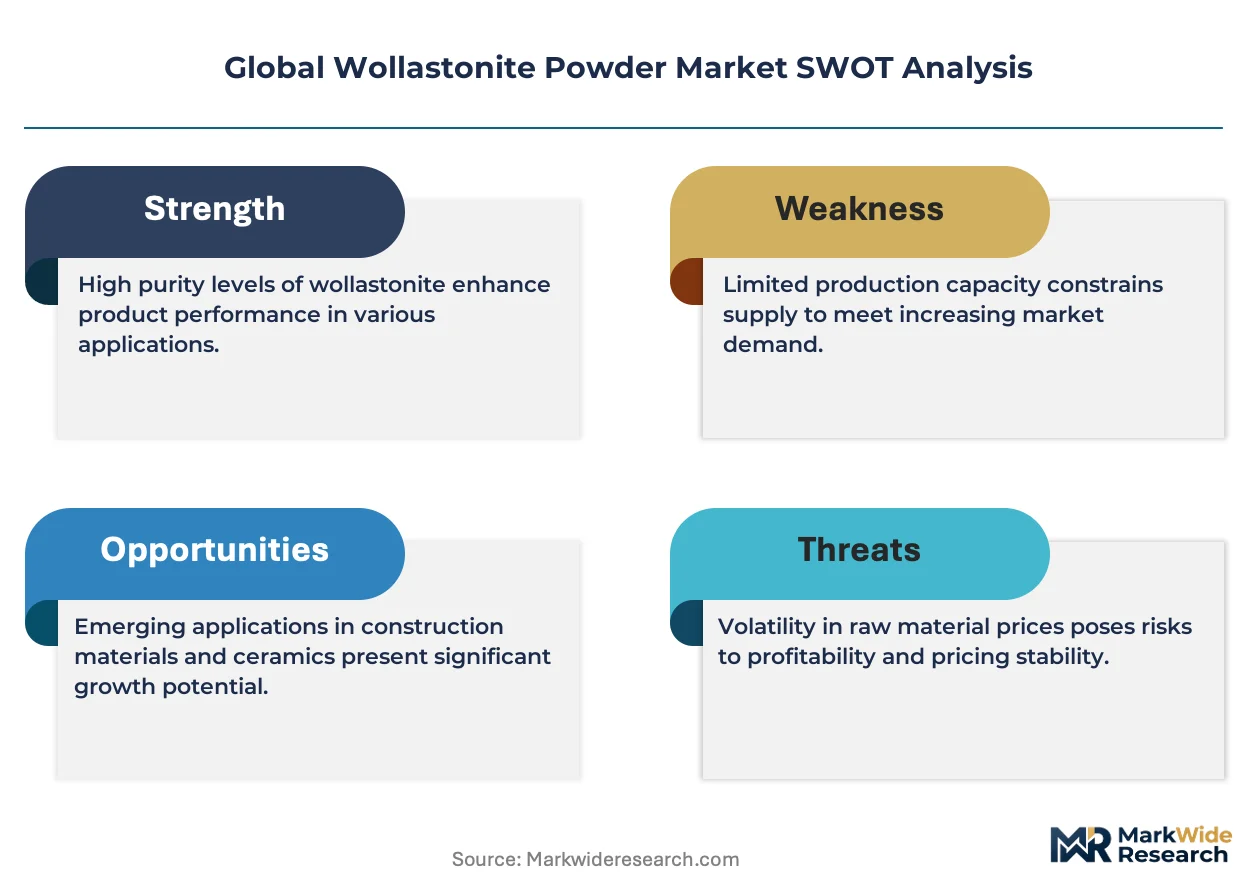
High-purity grade specification is collapsing the gap between industrial and technical applications across the value chain. Wolkem India Limited leverages captive mining assets in Rajasthan to sustain cost-advantaged supply to Asian ceramics producers. Imerys dominates European distribution through integrated processing networks serving REACH-compliant formulations. Canadian Wollastonite anchors North American supply with in-house beneficiation capacity targeting plastics compounding customers.
Wollastonite powder is a naturally occurring calcium metasilicate mineral (CaSiO₃) with acicular crystal structure, typically processed to 325-mesh fineness for industrial use, valued for its high aspect ratio, low thermal expansion, and chemical inertness in high-temperature applications. The mineral functions primarily as a functional filler and reinforcement agent across polymer, ceramic, and coating systems where dimensional stability and dielectric performance matter. Technical grade formulations command premium positioning in electronics and automotive under-the-hood components where dielectric constant and thermal resistance specifications tighten. Plastics application leads volume absorption through polyamide and polypropylene reinforcement, while ceramics maintains margin concentration through specialized refractory and sanitaryware formulations. Industrial grade supply remains mature with pricing anchored to construction-sector procurement cycles.
EPA industrial mineral dust exposure limits and OSHA silica permissible exposure standards shape milling and handling infrastructure investments across US processing facilities. ECHA REACH Annex XVII restrictions on heavy metal content in mineral fillers redirect import sourcing toward certified low-lead deposits. China's GB standards for non-metallic mineral products and MEE environmental compliance audits concentrate domestic supply among licensed processors. Stakeholders must monitor evolving EU CSRD supply chain disclosure requirements and their cascading impact on mineral traceability investments.
Market Dynamics
REACH Annex XVII heavy metal thresholds are forcing beneficiation upgrades across European import channels, compressing margins for uncertified deposits while rewarding integrated processors with captive low-lead ore bodies.
Growth Catalysts
- Advanced ceramics refractory demand:High-aspect-ratio wollastonite enables thinner kiln furniture designs. Sanitaryware producers in India leverage BIS-certified grades for thermal shock resistance.
- EV battery thermal management:Dielectric-grade powder fills gaps in polyamide battery module housings. Automotive OEMs specify GB-compliant Chinese supply for cost-controlled scale.
- REACH-compliant formulation mandates:ECHA restrictions on mineral filler purity redirect European compounders toward certified low-cadmium deposits. Technical grade premiums widen accordingly.
Market Restraints
- Acicular talc substitution in plastics:Lamellar talc offers comparable stiffness at lower cost in non-critical polypropylene applications. Price-sensitive packaging buyers switch readily.
- Rajasthan deposit concentration:Over half of Asian supply routes through Indian desert mining belts. Monsoon logistics disruptions constrain Q3 delivery reliability.
- Silica PEL compliance costs:OSHA permissible exposure limits mandate dust suppression infrastructure at US milling facilities. Small processors face six-figure capex burdens.
Strategic Opportunities
- Brazilian plastics compounding:ANVISA-regulated medical device manufacturing creates demand for USP-grade mineral fillers. Local beneficiation capacity remains underdeveloped.
- Dual carbon alignment in China:MEE environmental audits favor processors with closed-loop water systems. Carbon-efficient operations secure state procurement preferences.
- CSRD supply chain disclosure:EU corporate sustainability reporting requirements mandate mineral traceability. Early certifiers capture premium positioning with European OEMs.
Industry Challenges
- Acicular particle characterization:Aspect ratio measurement standardization lags across ISO and ASTM frameworks. Buyers and sellers dispute specification compliance.
- Legacy flotation circuit retrofitting:Older Chinese processing plants lack automated density separation. Manual sorting yields inconsistent purity grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wollastonite Powder Market |
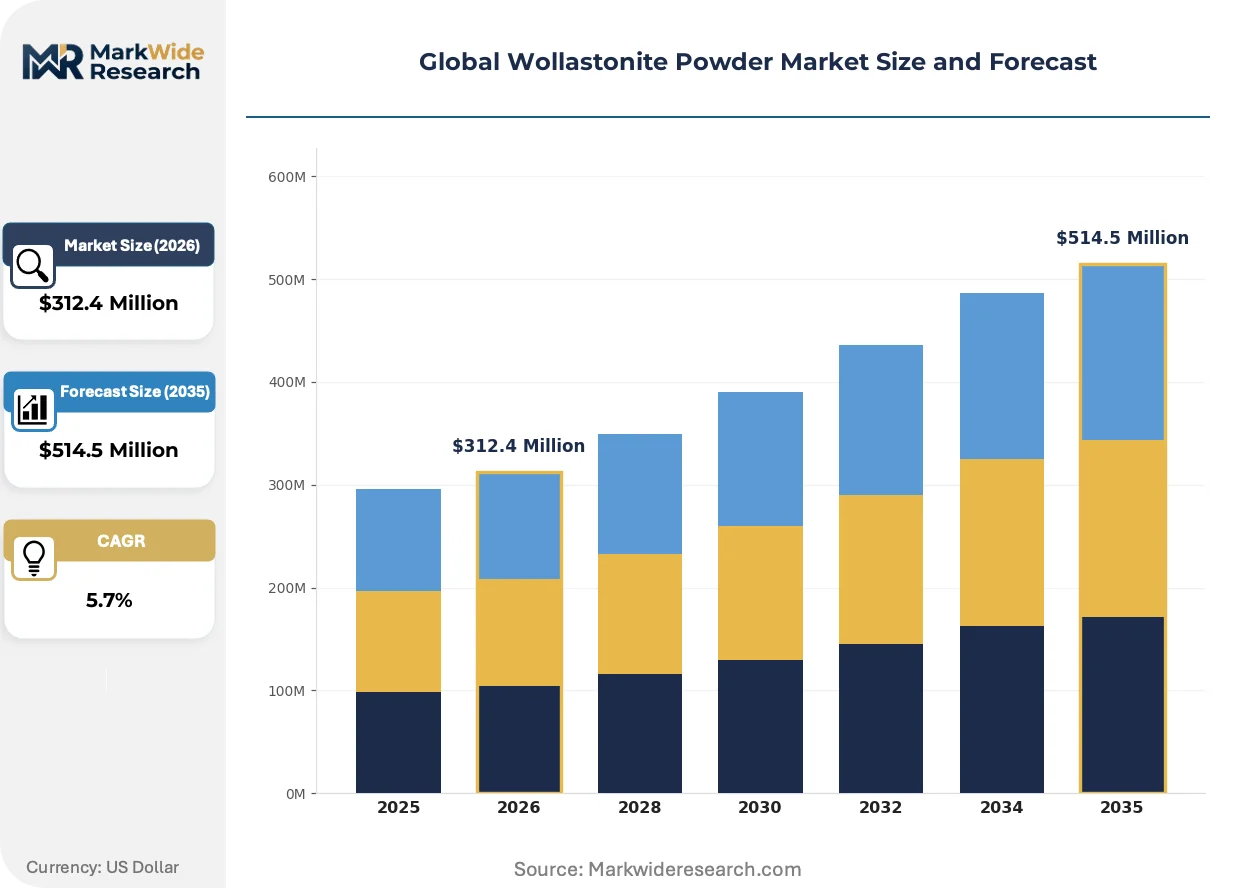
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $514.5 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wollastonite A, Wollastonite B, Wollastonite C, Wollastonite D Application: Plastics, Ceramics, Paints, Adhesives End User: Construction, Automotive, Electronics, Agriculture Grade: Industrial Grade, Technical Grade, High Purity, Others |
| Companies Covered | Nordkalk Corporation, Jilin Shanwei Wollastonite Mining, Wolkem India Limited, Changxing Earth New Type of Material Co., Ltd., Canadian Wollastonite, Imerys, Xinyu South Wollastonite Co., Ltd., ACBM JSC, R.T. Vanderbilt Holding Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wollastonite Powder Market Strategic Shifts
Surface modification chemistry and beneficiation automation are compressing the cost-performance gap between industrial and technical grade supply, enabling grade migration across traditional application boundaries.
Colloidal silica coating technology is decomposing the historical separation between filler and reinforcement functions in polymer systems. Tier-1 automotive suppliers now specify surface-treated wollastonite for under-the-hood nylon components. The technology is decomposing commodity pricing structures by collapsing multiple additive categories into single-source supply.
ECHA REACH SVHC candidate list expansion is redirecting mineral sourcing toward geologies with naturally low heavy metal content. Compounders serving EU electronics customers now demand certified CoA documentation for every lot. German automotive cable manufacturers have shifted procurement criteria to prioritize traceable Scandinavian and Canadian deposits over traditional Asian supply.
Direct mill-to-compounder relationships are displacing layered distribution networks in North American plastics markets. Large polyamide compounders in Ohio and Michigan now contract directly with Quebec beneficiation facilities. This channel compression is most visible in automotive under-the-hood applications where lot-to-lot consistency requirements exceed distributor quality assurance capabilities.
Global Wollastonite Powder Market Segmentation
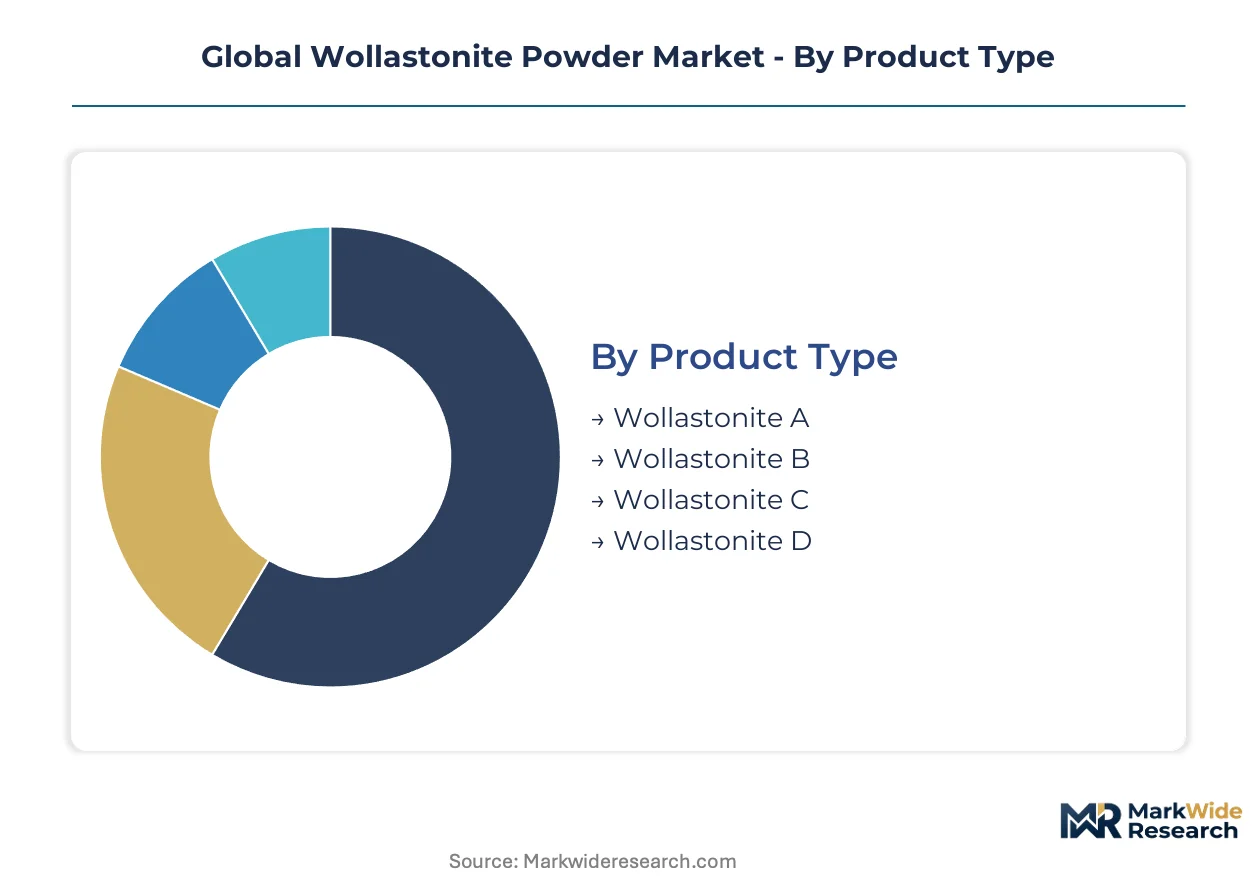
Wollastonite powder markets segment across mineralogical variants, application chemistry, and purity thresholds that dictate pricing power. Grade differentiation separates commodity construction fillers from dielectric-grade materials commanding technical premiums. Understanding segment boundaries reveals where beneficiation investments unlock margin expansion versus volume plays.
Product Type:
Geographic supply concentration varies sharply across product variants, with acicular grades dominating export flows from Indian desert mining belts while blocky morphologies serve regional construction markets.
- Wollastonite A:Coarse acicular morphology with aspect ratios exceeding 15:1, processed through dry milling circuits. Automotive under-the-hood polyamide reinforcement in Michigan and Ohio compounders absorbs the bulk of North American offtake. REACH-compliant Canadian deposits supply German cable manufacturers seeking SVHC-free certification.
- Wollastonite B:Medium aspect ratio material (8-12:1) balancing reinforcement with surface area for coating applications. Indian sanitaryware producers in Gujarat and Tamil Nadu specify BIS-certified grades for thermal shock resistance in kiln furniture. Monsoon logistics disruptions constrain Q3 delivery reliability from Rajasthan mining belts.
- Wollastonite C:Finely ground blocky morphology serving construction-sector sealants and adhesives. Domestic Chinese processors supply GB-compliant material for interior wall putty formulations.
- Wollastonite D:Ultra-fine precipitated grades for specialty electronics encapsulation. Japanese compounders in Osaka prefecture import limited quantities for high-frequency substrate applications.
Wollastonite A holds the largest share; momentum sits with Wollastonite B as Indian ceramics capacity expands.
Application:
Cost tier stratification runs from commodity construction fillers through technical-grade polymer reinforcement to premium dielectric formulations.
- Plastics:Polyamide and polypropylene compounding absorbs the highest volume, with surface-modified grades displacing glass fiber in under-the-hood automotive components. Ohio and Michigan compounders contract directly with Quebec beneficiation facilities to secure lot-to-lot consistency.
- Ceramics:Refractory and sanitaryware formulations command margin concentration through specialized thermal shock resistance specifications. Indian producers leverage BIS-certified grades for export competitiveness.
- Paints:Industrial coating systems utilize wollastonite for corrosion resistance and film integrity. Formulators prioritize low-oil-absorption grades to minimize resin demand.
- Adhesives:Construction sealants employ finely ground material for rheology control and crack resistance. Price-sensitive buyers switch to calcium carbonate where specifications permit.
Plastics dominates volume absorption; ceramics delivers the steepest expansion trajectory through advanced refractory demand.
End User:
Customer type segmentation separates project-driven construction procurement from specification-tight automotive and electronics manufacturing.
- Construction:Interior wall putty, tile adhesives, and exterior insulation systems drive mature demand cycles. Chinese state procurement preferences favor MEE-compliant processors with closed-loop water systems.
- Automotive:Battery module housings and under-the-hood components specify dielectric-grade powder for thermal management. OEMs source GB-compliant Chinese supply for cost-controlled scale in EV platforms.
- Electronics:High-frequency substrates and encapsulation materials demand certified low-heavy-metal grades. German cable manufacturers have shifted procurement toward traceable Scandinavian and Canadian deposits.
- Agriculture:Soil amendment applications remain nascent outside Japanese horticultural markets. Limited beneficiation capacity targets this segment.
Construction anchors volume; electronics is climbing the fastest on traceability premiums.
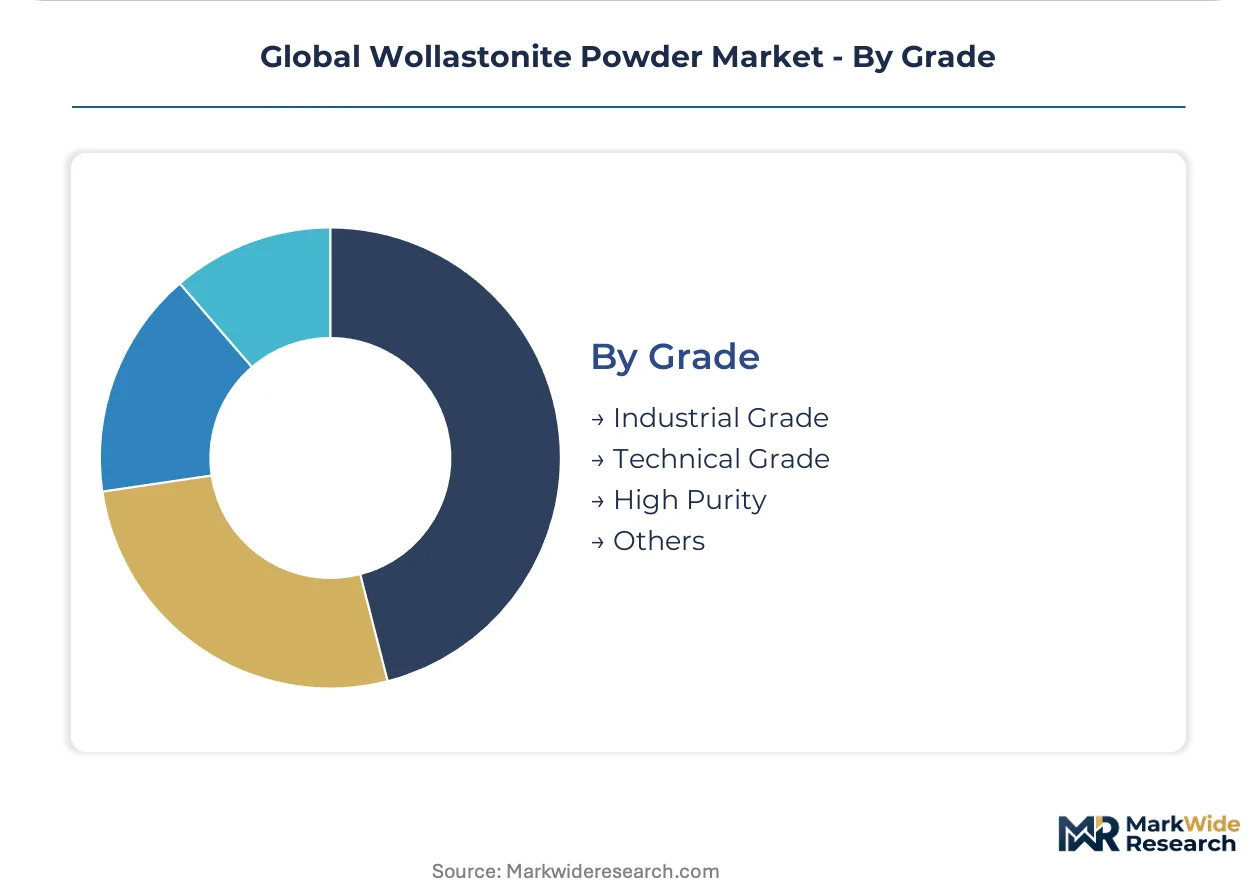
Grade:
Supply concentration favors integrated processors with captive low-lead ore bodies capable of meeting tightening purity mandates.
- Industrial Grade:Standard 325-mesh material for construction and general filler applications. Pricing follows regional procurement cycles with limited differentiation.
- Technical Grade:Controlled particle size distribution and aspect ratio for polymer reinforcement. ECHA REACH Annex XVII restrictions on mineral filler purity redirect European compounders toward certified low-cadmium deposits.
- High Purity:Sub-50 ppm heavy metal content for electronics and medical device applications. ANVISA-regulated Brazilian medical device manufacturing creates demand for USP-grade mineral fillers.
- Others:Custom surface-treated and coated variants for specialty applications. Colloidal silica coating technology collapses traditional additive category boundaries.
Industrial Grade retains the largest share; High Purity is gaining share fastest on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Indian desert mining belts and Canadian beneficiation facilities dominate international trade, while Chinese processors retain material for domestic construction and electronics manufacturing. Import dependence in Europe and North America creates pricing leverage for integrated suppliers with captive ore bodies.
China
Domestic construction and electronics manufacturing absorb the majority of national output, with polyamide battery module housings for EV platforms driving technical grade demand. MEE environmental audits and GB standards for non-metallic mineral products concentrate supply among licensed processors with closed-loop water systems. Yangtze River Delta compounders source GB-compliant material for cost-controlled automotive scale.
India
Rajasthan mining belts supply over half of Asian acicular grade exports, with BIS-certified grades serving sanitaryware producers in Gujarat and Tamil Nadu. Monsoon logistics disruptions constrain Q3 delivery reliability through desert transport corridors. Captive mining assets in Rajasthan sustain cost-advantaged supply to Asian ceramics producers.
United States
Ohio and Michigan polyamide compounders contract directly with Quebec beneficiation facilities for automotive under-the-hood applications. EPA industrial mineral dust exposure limits and OSHA silica permissible exposure standards shape milling infrastructure investments. Dust suppression capex burdens squeeze small processors.
Canada
Quebec beneficiation facilities anchor North American supply with in-house capacity targeting plastics compounding customers. REACH-compliant deposits supply German cable manufacturers seeking SVHC-free certification. Direct mill-to-compounder relationships displace layered distribution networks.
Germany
Automotive cable manufacturers have shifted procurement toward traceable Scandinavian and Canadian deposits over traditional Asian supply. ECHA REACH Annex XVII restrictions on heavy metal content redirect mineral sourcing toward certified low-lead deposits. Technical grade premiums widen on compliance mandates.
Global Wollastonite Powder Market Competitive Environment
Listed leaders compete with private specialists across beneficiation scale and regulatory certification capabilities. Market structure tilts toward integrated processors with captive low-lead ore bodies capable of meeting tightening purity mandates. Three archetypes dominate: mining-holding conglomerates with diversified mineral portfolios, single-mineral specialists with deep deposit control, and regional processors serving construction-grade demand. Competitive moves concentrate on direct customer relationships and automated beneficiation upgrades.
Within the integrated conglomerate tier, Imerys and Nordkalk Corporation exemplify European positioning through REACH-compliant distribution networks. Wolkem India Limited anchors the single-mineral specialist archetype with Rajasthan-based deposit control. Canadian Wollastonite occupies the North American regional processor position with Quebec beneficiation capacity. These three represent distinct strategic postures on certification, scale, and geographic focus.
| Leading Market Players |
|---|
| Nordkalk Corporation |
| Jilin Shanwei Wollastonite Mining |
| Wolkem India Limited |
| Changxing Earth New Type of Material Co., Ltd. |
| Canadian Wollastonite |
| Imerys |
| Xinyu South Wollastonite Co., Ltd. |
| ACBM JSC |
| R.T. Vanderbilt Holding Company |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles at Quebec beneficiation facilities concentrate pricing power with integrated processors holding captive Rajasthan ore bodies, while spot buyers absorb volatility from monsoon-disrupted Indian desert transport corridors. ECHA REACH Annex XVII compliance costs compress margins for uncertified deposits and widen technical grade premiums across European compounder procurement.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with polyamide compounders in Ohio and Michigan securing lot-to-lot consistency through direct Quebec mill relationships. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified dielectric grades from BIS-certified ceramics feedstock and construction-grade blocky morphologies. Cost compression in industrial grade supply intensifies as calcium carbonate substitution pressures sealant and adhesive formulations. Price-sensitive construction buyers switch readily where specifications permit, while automotive under-the-hood compounders absorb technical premiums for certified low-cadmium deposits.
Supply Chain Analysis
Rajasthan desert mining belt concentration underwrites Asian acicular grade flows, with monsoon logistics disruptions constraining Q3 delivery reliability through single-source vulnerability in Indian transport corridors. Canadian in-house beneficiation capacity and Chinese licensed processors with closed-loop water systems feed from crystalline silica ore and energy-intensive milling inputs. Distribution runs through direct mill-to-compounder relationships displacing layered networks in North American plastics markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV battery thermal management specifications are disrupting traditional polymer filler categories, with dielectric-grade wollastonite displacing glass fiber in polyamide battery module housings and collapsing multiple additive categories into single-source supply.
For Market Incumbents: Compound captive ore body advantages through automated density separation upgrades at legacy flotation circuits, securing ECHA REACH SVHC-free certification ahead of EU CSRD supply chain disclosure mandates. Backward integration into surface modification chemistry preserves margin position against colloidal silica coating technology commoditization. For New Entrants and Emerging Players: Differentiate on ANVISA-regulated USP-grade mineral filler supply to Brazilian medical device manufacturers, where local beneficiation capacity remains underdeveloped. Target Indian sanitaryware expansion in Gujarat and Tamil Nadu with BIS-certified thermal shock resistance grades, leveraging direct technical service relationships absent from commodity distributor channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining-holding conglomerates with underperforming industrial mineral portfolios, particularly those holding Scandinavian or Canadian deposits with naturally low heavy metal content. Long-term viability hinges on regulatory certification moats rather than volume scale. Watch for ECHA SVHC candidate list expansion crossing thresholds that redirect German automotive cable procurement toward traceable supply.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Beneficiation Upgrade | Density separation automation at Rajasthan facilities compresses cost-performance gaps between industrial and technical grades. |
| REACH Certification Investment | ECHA Annex XVII compliance unlocks premium positioning with European polyamide compounders facing SVHC documentation mandates. |
| Surface Modification Capacity | Colloidal silica coating technology collapses traditional filler-reinforcement category boundaries for Tier-1 automotive suppliers. |
| Direct Mill-to-Compounder Relationships | Channel compression in Ohio and Michigan exceeds distributor quality assurance capabilities for lot-to-lot consistency. |
| Dual Carbon Alignment | MEE-compliant closed-loop water systems secure Chinese state procurement preferences for carbon-efficient mineral processors. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with mineral processing plant managers, polyamide compounder procurement leads, ceramics R&D directors, and REACH compliance officers; and secondary validation through customs trade databases, ECHA SVHC candidate list filings, SEC 10-K industrial mineral disclosures, and BIS certification registries. Bottom-up volume triangulation across grade-tiered production capacities reconciled with top-down demand absorption estimates from end-use industry consumption patterns.
Across the projection horizon, the analytical framework modeled segmentation across acicular morphology grades, application chemistry in plastics-ceramics-coatings, purity thresholds from industrial through high-purity dielectric, and geographic production hub concentration. CAGRs derived from regression against EV battery thermal management content-per-vehicle trajectories and Indian sanitaryware kiln furniture expansion rates, with cross-validation against MEE environmental audit compliance timelines and ECHA regulatory expansion scenarios.
The analysis sits within stated boundaries; outcomes outside sustained EV platform dielectric-grade specification tightening or abrupt ECHA heavy metal threshold reduction would require recalibration. Forecasts assume continued Rajasthan mining belt concentration and Quebec beneficiation capacity stability. Revision becomes warranted when acicular talc substitution economics in non-critical polypropylene applications cross threshold viability for price-sensitive packaging buyers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
China Ceramic Tiles Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market
Ceramics
Titanium Carbide Market
Ceramics
Wollastonite Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Ceramic Substrate Market
Ceramics
Mullite Market
Ceramics
Clay Market
Ceramics
Ceramic Frit Market
Ceramics
White Fused Alumina Market
Ceramics
USA and Canada Alumina Market
Ceramics
Global Ceramic Tube Market
Ceramics
Technical Ceramics Market
Ceramics
Ceramic Kilns Market
Ceramics
UAE Ceramic Tiles Market