
 Europe Oriented Strand Board Market | 2026-2036
Europe Oriented Strand Board Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oriented Strand Board Market Foresight
Multi-source procurement for wood furnish is hardening across the European OSB value chain as mills diversify away from Baltic birch dependencies. Kronospan leverages its integrated forestry holdings across Austria and Poland to secure chip supply through captive harvesting. Egger competes through R&D intensity in low-formaldehyde resin systems that meet stricter indoor air quality protocols. Sonae Arauco anchors its position via deep specialization in moisture-resistant grades for Iberian and French coastal construction markets.
Oriented strand board is an engineered wood panel manufactured from cross-oriented layers of elongated wood strands bonded with synthetic resin under heat and pressure, typically achieving densities between 600 and 750 kg per cubic meter and structural ratings per EN 300 standards. Its primary purpose is to deliver load-bearing performance in wall sheathing, roof decking, and subfloor assemblies at lower weight and cost than plywood. Structural OSB dominates volume flows across European housing starts, while moisture-resistant and fire-rated variants command premium positioning in commercial envelope specifications and retrofit projects where building codes intensify performance requirements. Thin-panel grades for furniture components occupy a mature niche with stable margin pools tied to IKEA-tier supply contracts.
CE marking under the Construction Products Regulation governs structural integrity declarations for OSB placed on the EU market, while the EU Green Deal's embodied-carbon benchmarks and national implementations of the Energy Performance of Buildings Directive steer procurement toward low-emission certified products. ECHA oversight of formaldehyde emissions under REACH restrictions further shapes resin formulation roadmaps and factory investment priorities across member states. Stakeholders must monitor how the EU Deforestation Regulation's due-diligence obligations will reshape wood-fiber sourcing economics and supplier qualification timelines.
Market Dynamics
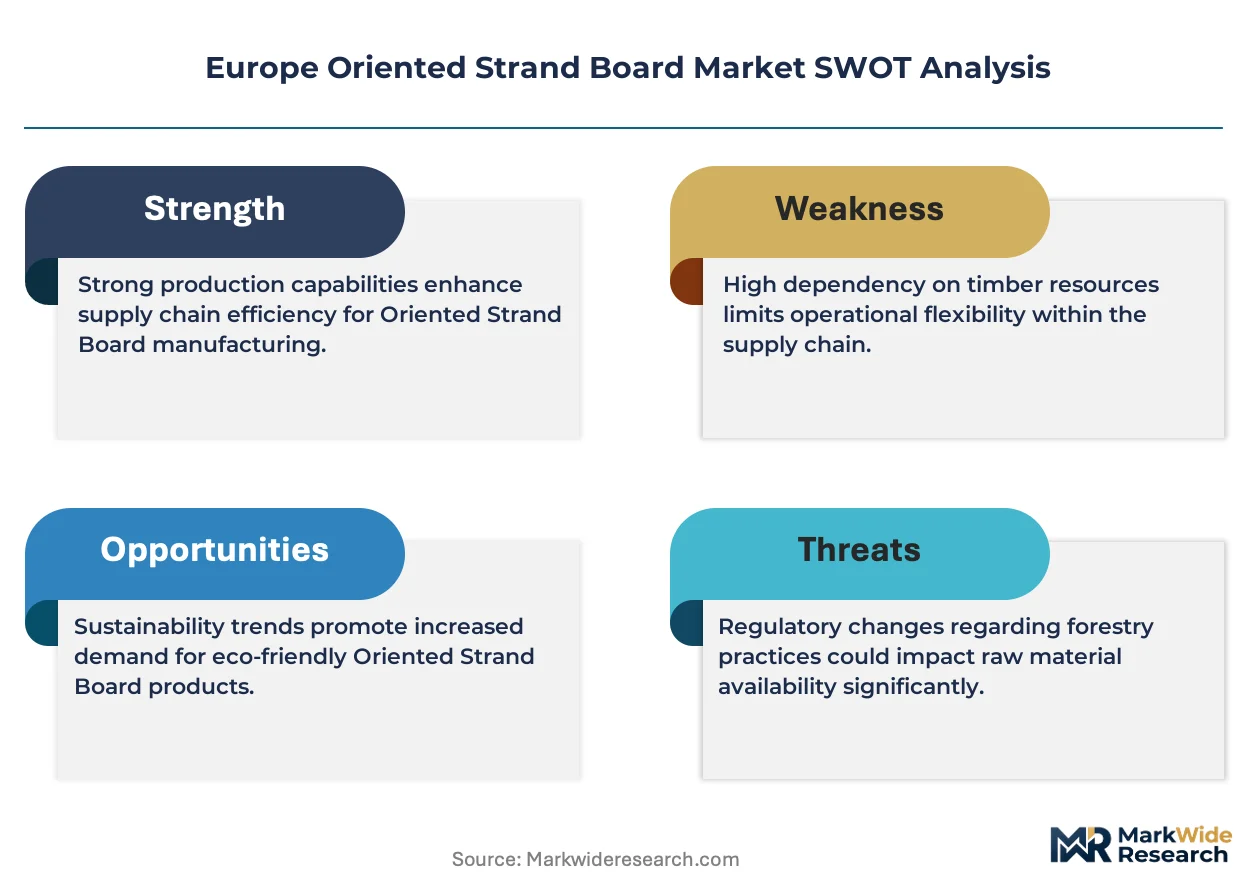
The EU Green Deal's embodied-carbon thresholds are compressing specification timelines for structural panels across Central and Eastern European housing corridors, forcing mills to requalify supply chains under accelerated compliance windows.
Growth Catalysts
- Energy Performance of Buildings Directive:National implementations across Germany and Poland mandate thermal envelope upgrades in residential retrofits, expanding specification volumes for load-bearing sheathing panels.
- Cross-laminated timber integration:Hybrid construction systems combining OSB with mass timber elements are gaining traction in mid-rise residential projects across Austrian and Czech building codes.
- Baltic birch substitution:Mills are redirecting furnish sourcing toward Central European spruce and pine strands to reduce dependency on eastern Baltic supply corridors.
Market Restraints
- Formaldehyde resin cost volatility:Methanol price swings and ECHA REACH compliance costs are squeezing margin structures for conventional phenol-formaldehyde bonding systems.
- Baltic wood fiber concentration:Remaining dependence on Estonian and Latvian roundwood exposes mills to EU Deforestation Regulation due-diligence bottlenecks and extended supplier qualification timelines.
- Cross-laminated timber substitution:Solid wood panel systems are capturing specification share in premium residential and commercial structural applications where carbon accounting favors mass timber.
Strategic Opportunities
- Romanian and Bulgarian housing markets:Underpenetrated residential construction volumes in southeastern Europe offer expansion corridors for moisture-resistant grades suited to continental climate envelopes.
- Fire-rated commercial specifications:Evolving French and Italian building codes for mid-rise timber construction are creating demand for treated structural panels with enhanced char resistance.
- Digital fabrication integration:CNC-ready thin-panel grades are converging with automated off-site manufacturing systems serving modular housing factories in the Netherlands and Belgium.
Industry Challenges
- Resin chemistry talent scarcity:Formulation expertise for low-emission bio-based adhesives is concentrated among a narrow pool of specialists across German and Austrian chemical clusters.
- CE marking timeline compression:Factory production control audits under the Construction Products Regulation are extending lead times for new product variant approvals.
- Wood-fiber traceability system integration:EU Deforestation Regulation geolocation requirements are forcing legacy ERP upgrades at mills with fragmented supplier data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oriented Strand Board Market |
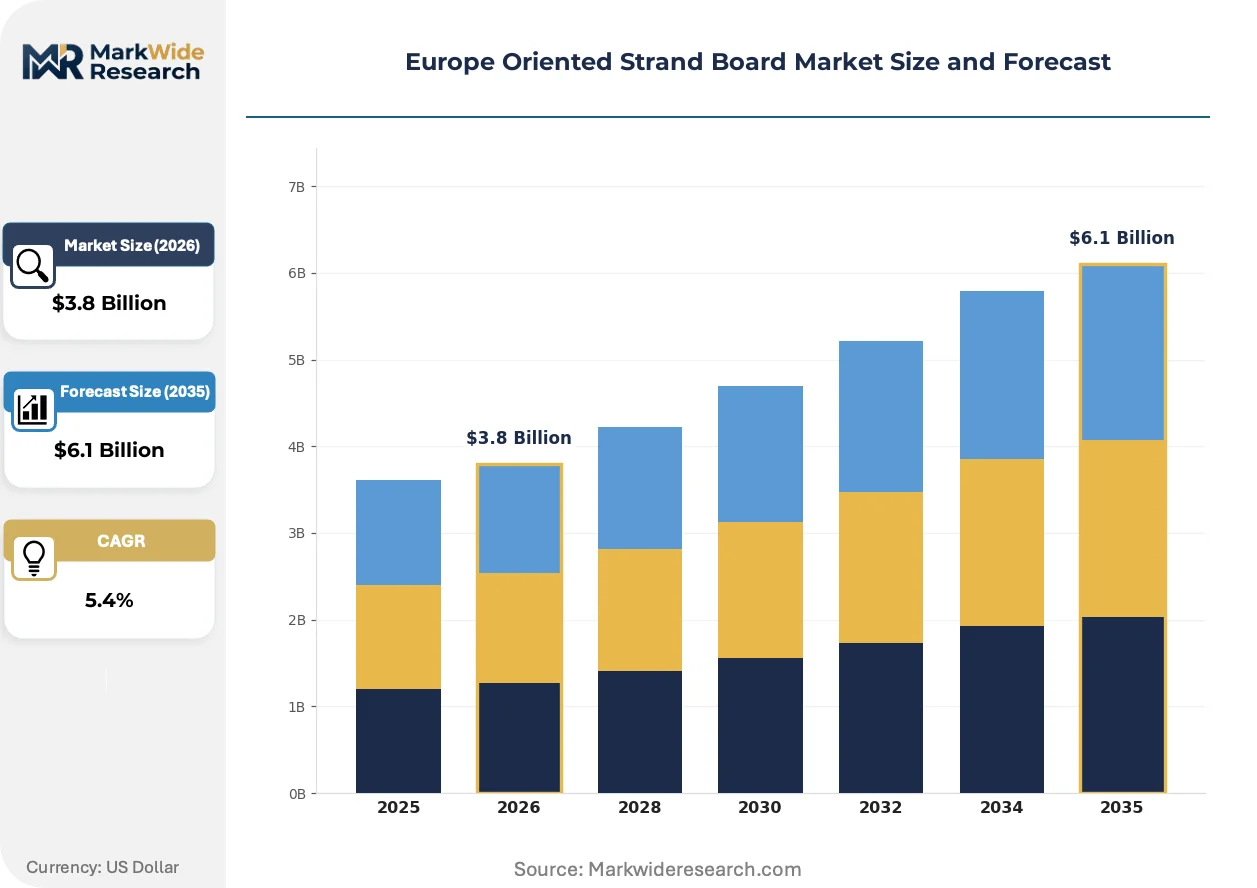
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard OSB, Structural OSB, Fire-Rated OSB, Moisture-Resistant OSB End User: Construction, Furniture Manufacturing, Packaging, Industrial Thickness: Thin, Thick, Medium, Heavy Application: Wall Sheathing, Roof Decking, Flooring, Furniture Components |
| Companies Covered | Kronoplus Limited, Coillte, Egger, Steico SE, HEM DENMARK A/S, SWISS KRONO Group, West Fraser, Kronospan, Sonae Arauco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oriented Strand Board Market Shifts & Advancements
Process intensification and regulatory chemistry mandates are reshaping how European mills configure resin systems and panel grades. Three developments are restructuring competitive capability requirements.
Continuous press technology with real-time density profiling is modularizing production flexibility at integrated Central European facilities. German and Polish housing developers are specifying mixed-grade orders with shorter lead times. This equipment transition is compressing batch-changeover economics and enabling just-in-time sheathing supply for large-scale residential contractors.
REACH restrictions on formaldehyde emissions are tightening resin formulation roadmaps across ECHA-regulated member states. Mills are accelerating phenol-formaldehyde substitution with methylene diphenyl diisocyanate and bio-based adhesive trials. Southern European commercial envelope specifications are most affected, with Iberian and Italian projects now requiring third-party indoor air quality certification.
Building information modeling workflows are penetrating structural panel specification channels. French and Dutch engineering firms are embedding performance data directly into digital twin environments for multi-story timber frames. Specification authority is migrating from traditional distributor relationships toward direct mill engagement with design-build consortia.
Europe Oriented Strand Board Market Segmentation
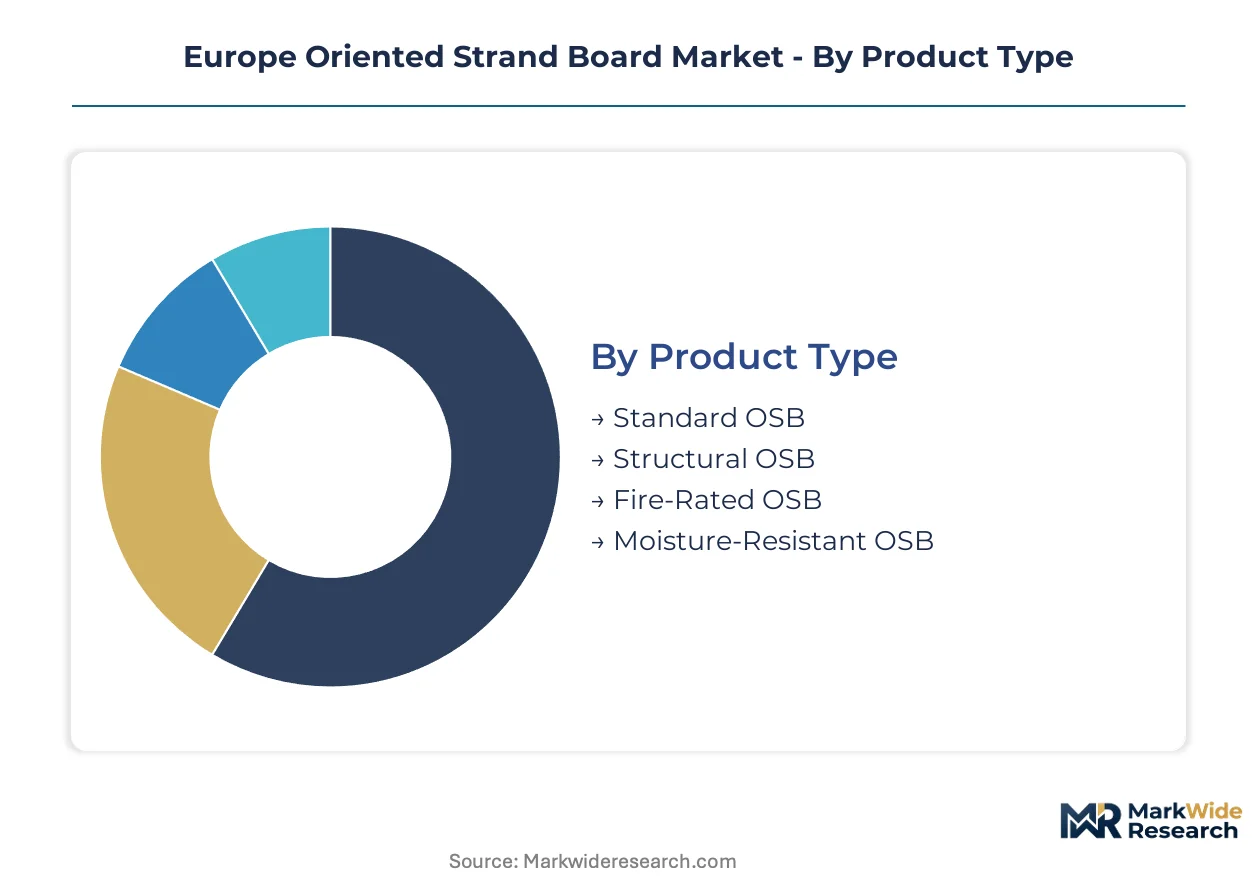
OSB specification channels in Europe fragment across performance tiers tied to building-code cycles and manufacturing automation. Upgrade trajectories differ sharply between residential construction envelopes and industrial fabrication systems.
Product Type:
Replacement cycles for sheathing panels accelerate where EU energy regulations force envelope retrofits, compressing requalification timelines for mills serving German and Polish housing corridors.
- Standard OSB:Basic structural grade achieving densities near 650 kg per cubic meter without specialized resin treatments. Polish and Romanian residential contractors specify this grade for cost-sensitive single-family housing where thermal bridging requirements remain less stringent.
- Structural OSB:Cross-oriented strand architecture engineered for load-bearing wall and floor assemblies per EN 300 OSB/3 and OSB/4 ratings. German mid-rise timber frames and Czech hybrid construction projects concentrate demand here as building codes mandate higher racking resistance.
- Fire-Rated OSB:Intumescent-treated panels meeting French CSTB and Italian UNI standards for mid-rise timber construction. Regulatory tightening in Paris and Milan commercial envelopes drives specification.
- Moisture-Resistant OSB:Phenolic resin-bonded grades with reduced thickness swelling for coastal Iberian and French Atlantic construction. CE marking extensions for humid service conditions extend factory audit timelines.
Volume placements concentrate in Structural OSB; the faster expansion belongs to Fire-Rated OSB.
End User:
Customer procurement patterns diverge between project-scale construction workflows and continuous manufacturing lines with automated feed systems.
- Construction:Residential and commercial contractors specifying sheathing for wall, roof, and subfloor assemblies. German housing starts and Polish multi-family retrofits absorb the majority of European panel flows.
- Furniture Manufacturing:CNC-ready thin-panel grades for flat-pack producers and modular component fabricators. IKEA-tier supply contracts in Sweden and Slovakia anchor stable margin pools.
- Packaging:Industrial crating and export pallet applications requiring lower structural ratings. Czech and Hungarian automotive component suppliers drive recurring demand.
- Industrial:Specialty applications including concrete formwork and temporary site protection. French infrastructure projects and Dutch offshore wind construction generate intermittent large-lot orders.
Construction commands the dominant share; furniture manufacturing climbs the fastest as automated production lines proliferate.
Thickness:
Panel dimension preferences track equipment compatibility in downstream fabrication and field installation methods.
- Thin:Panels below 12 millimeters optimized for furniture components and decorative surfacing. Dutch and Belgian modular housing factories integrate these grades into automated cutting lines.
- Thick:Panels exceeding 18 millimeters for heavy-duty flooring and structural platforms. German warehouse and logistics construction specifications favor this dimension for point-load distribution.
- Medium:12-18 millimeter range dominating standard wall sheathing and roof decking. Polish and Czech residential contractors specify this grade for cost-optimized envelope assemblies.
- Heavy:Specialized structural platforms exceeding 25 millimeters for industrial mezzanines and temporary roadways. Nordic heavy civil projects generate concentrated demand.
Medium thickness holds the volume center; thin panels gain share fastest through digital fabrication integration.
Application:
Use-case specification intensity varies with building-code enforcement geography and climate exposure requirements.
- Wall Sheathing:Exterior bracing panels providing racking resistance and air-barrier substrate. German Passivhaus retrofits and Polish energy-efficiency mandates drive specification volume.
- Roof Decking:Structural substrate for membrane and tile roofing systems. French and Italian coastal construction requires moisture-resistant grades for this exposure.
- Flooring:Subfloor and finished floor applications in residential and light commercial. Austrian and Swiss multi-family housing projects concentrate demand for acoustic-rated assemblies.
- Furniture Components:Shelving, cabinet carcasses, and interior fittings. Swedish and Slovak flat-pack manufacturers specify thin-panel CNC grades with tight dimensional tolerances.
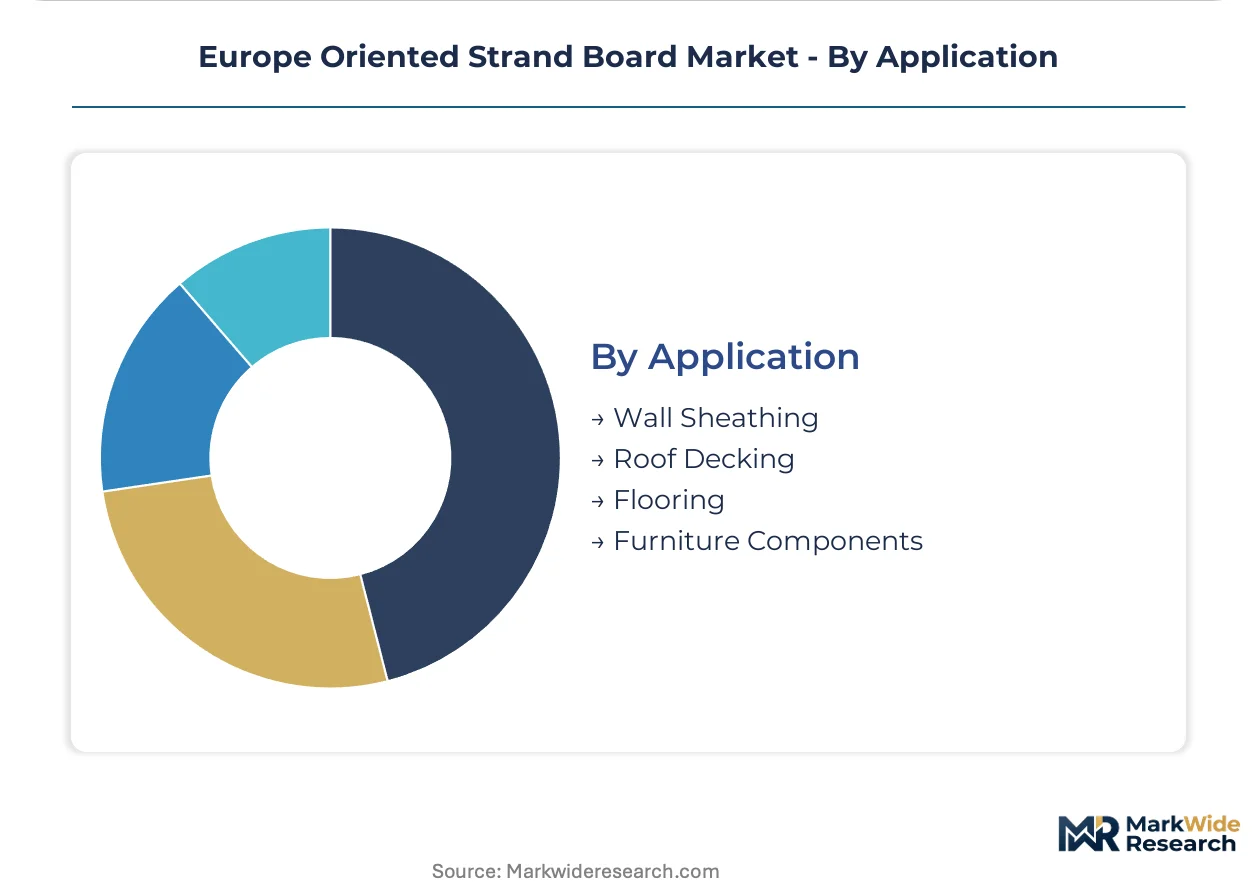
Wall sheathing captures the largest placement volumes; furniture components expand most quickly through off-site manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential construction corridors across Central and Eastern Europe concentrate demand for structural sheathing panels, with German and Polish housing starts absorbing the dominant share of regional panel flows. Energy-efficiency retrofits mandated under national implementations of the Energy Performance of Buildings Directive are compressing procurement timelines for certified OSB grades.
Germany
Mid-rise timber frame construction and Passivhaus envelope retrofits drive specification volumes for OSB/3 and OSB/4 structural grades. The national implementation of the Energy Performance of Buildings Directive mandates thermal bridge reduction in residential retrofits. The Stuttgart and Munich metropolitan corridors concentrate demand from design-build consortia specifying hybrid mass timber systems.
Poland
Multi-family housing starts and cross-border supply to German contractors sustain high-volume absorption of medium-thickness sheathing panels. EU Green Deal embodied-carbon benchmarks are redirecting procurement toward mills with verified low-emission supply chains. The Silesian and Greater Poland voivodeships host manufacturing clusters serving Central European distribution networks.
France
Commercial envelope specifications in Paris and Lyon are tightening fire-resistance requirements for mid-rise timber construction under evolving CSTB standards. The RE2020 environmental regulation is accelerating demand for low-carbon structural panels in new residential builds. The Grand Est and Nouvelle-Aquitaine regions concentrate manufacturing capacity oriented toward Atlantic coastal moisture-resistant grades.
Austria
Hybrid construction systems combining OSB with cross-laminated timber elements are gaining traction in multi-family residential projects across Tyrol and Styria. Strict indoor air quality protocols under national building codes favor low-formaldehyde resin formulations. The Upper Austria region anchors integrated forestry-to-panel supply chains serving Alpine construction markets.
Romania
Underpenetrated residential construction volumes in Bucharest and Transylvanian urban centers offer expansion corridors for cost-optimized structural grades. The EU Deforestation Regulation is extending due-diligence timelines for wood-fiber sourcing from Carpathian forestry operations. The Prahova Valley industrial zone is emerging as a distribution hub for southeastern European housing markets.
Europe Oriented Strand Board Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated mills scale continuous press installations to serve compressed lead-time requirements from large-scale residential contractors. The vendor base concentrates among Austrian, German, and Iberian integrated producers with captive forestry holdings and multi-site European manufacturing footprints. Three archetypes define competitive positioning: integrated forestry-panel conglomerates with backward supply control, specialized moisture-resistant grade producers serving coastal markets, and thin-panel specialists anchored to furniture manufacturing contracts. M&A activity and geographic diversification into southeastern European housing corridors represent the dominant competitive vectors reshaping market share distribution.
Among Austrian-based integrated producers, Kronospan and Egger exemplify the forestry-backed archetype with multi-country manufacturing footprints. Sonae Arauco represents the coastal-specialist positioning with deep orientation toward Iberian and French Atlantic moisture-resistant specifications. SWISS KRONO Group occupies a position bridging Central European structural grade production with thin-panel supply to furniture manufacturing channels. These three anchors illustrate how competitive capability requirements diverge between envelope construction and industrial fabrication end uses.
| Leading Market Players |
|---|
| Kronoplus Limited |
| Coillte |
| Egger |
| Steico SE |
| HEM DENMARK A/S |
| SWISS KRONO Group |
| West Fraser |
| Kronospan |
| Sonae Arauco |
| Others |
Supply & Pricing Matrix
Resin chemistry specialists concentrated in German and Austrian chemical clusters command wage premiums that compress margin structures at mills competing on standard-grade volumes. Labor-cost differentials between these formulation hubs and Central European manufacturing corridors widen pricing spreads between certified low-emission panels and conventional structural grades serving Polish and Romanian residential contractors.
Pricing Analysis
Warranty-backed CE marking extensions and third-party indoor air quality certification bundle into premium panel pricing, while unbundled standard grades trade on spot resin cost indices. Three-tier pricing structure across premium, standard, and economy levels separates fire-rated commercial specifications from moisture-resistant coastal grades and basic structural sheathing. Cost compression in economy tiers is intensifying because methanol price volatility squeezes phenol-formaldehyde bonding systems. Polish and Romanian residential contractors exhibit highest price sensitivity; German design-build consortia specifying hybrid mass timber systems show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Estonian and Latvian roundwood suppliers facing EU Deforestation Regulation due-diligence bottlenecks. Wood furnish draws from Central European spruce and pine strands, Baltic birch residuals, and Iberian maritime pine feedstocks. Methanol and phenol resin inputs rest on petrochemical supply chains concentrated in German and Benelux refining corridors. Tariff exposure on Russian-origin wood fiber before sanctions redirected flows has forced ERP upgrades at mills with fragmented supplier data architectures. Distribution runs through integrated mill-direct channels serving large-scale residential contractors and specialized distributor networks for furniture manufacturing thin-panel grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU Green Deal embodied-carbon thresholds and extended CE marking timelines force capital-constrained regional mills toward exit or acquisition.
For Market Incumbents: Hedge Baltic birch dependency by accelerating captive forestry development in Polish and Austrian holdings before EU Deforestation Regulation enforcement tightens. Secure resin formulation talent through targeted recruitment from German chemical clusters or partnership with Austrian technical universities. Cross-laminated timber substitution in premium structural applications threatens OSB/4 grade margins; defend through hybrid system certification that embeds OSB sheathing into mass timber design-build specifications. For New Entrants and Emerging Players: Capture underpenetrated Romanian and Bulgarian residential construction corridors where cost-optimized structural grades face limited certified competition. Target moisture-resistant specifications for southeastern European continental climate envelopes where Sonae Arauco's Iberian focus leaves distribution gaps. Enter through toll-manufacturing arrangements with existing Polish or Czech continuous press facilities to bypass capital-intensive greenfield timelines. For Investors and Strategic Acquirers: Re-rating potential sits with integrated forestry-panel conglomerates with verified low-emission supply chains given EU Green Deal procurement mandates accelerating specification authority migration toward certified producers. Long-term viability centers on backward integration depth and multi-country manufacturing footprint scalability. Watch for CE marking audit backlogs as inflection indicator—extended timelines signal regulatory capacity constraints that favor incumbents with established factory production control systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Forestry | Secures chip supply through Austrian and Polish harvesting operations ahead of EU Deforestation Regulation enforcement. |
| Continuous Press Technology Upgrade | Enables real-time density profiling for mixed-grade orders from German housing developers demanding compressed lead times. |
| Low-Formaldehyde Resin Certification | Meets French and Italian indoor air quality protocols that now require third-party verification for commercial envelope specifications. |
| Fire-Rated Grade Capacity Addition | Addresses evolving CSTB and UNI standards for mid-rise timber construction in Paris and Milan commercial markets. |
| Digital Fabrication Partnership | Aligns CNC-ready thin-panel output with automated off-site manufacturing systems serving Dutch and Belgian modular housing factories. |
Research Methodology
Document review covered customs and trade data, SEC and national registry filings from integrated forestry-panel conglomerates, ECHA REACH regulatory guidance, and EU Construction Products Regulation technical documentation, complemented by interviews with plant managers at Central European OSB facilities, procurement leads at German timber frame developers, distribution channel partners serving Iberian coastal construction markets, and technical R&D directors specializing in bio-based adhesive formulation. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across residential construction forecasts.
Cross-referencing historical capacity utilization patterns against forward-looking panel input from industry participants informed the analytical framework. Segmentation dimensions modeled include product performance tier, end-use application, panel thickness specification, and regional regulatory cluster. CAGRs derived from regression analysis of housing starts correlation with sheathing intensity, adjusted for energy-efficiency retrofit mandates under national Energy Performance of Buildings Directive implementations. Industry-specific forecast inputs incorporated cross-laminated timber substitution elasticities and resin chemistry cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Deforestation Regulation enforcement stringency and methanol price volatility in petrochemical feedstock markets. Deviation in CE marking audit processing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Aluminum Board Raised Access Floor Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Marble Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market