
 North America Flow Cytometry Market | 2026-2036
North America Flow Cytometry Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flow Cytometry Market Insights
Direct-to-laboratory distribution channels are reshaping how flow cytometry systems reach end users in North America. Becton Dickinson leverages its embedded service infrastructure to sustain long-term contracts with major hospital networks. Beckman Coulter anchors its position through specialized hematology workflows that dominate high-throughput diagnostic laboratories. Thermo Fisher Scientific competes by extending its consumables portfolio into recurring revenue streams that tighten customer retention.
Flow cytometry is a laser-based analytical technique that measures physical and chemical characteristics of cells or particles suspended in fluid, typically detecting forward scatter, side scatter, and fluorescence emission across multiple wavelengths simultaneously. Its primary commercial purpose is quantitative cell analysis for clinical diagnostics, drug discovery, and biomedical research requiring single-cell resolution. Instruments and reagents together capture the dominant value share, with imaging flow cytometry representing the fastest-expanding technology tier as researchers demand spatial context alongside traditional intensity metrics. Academic institutes and pharmaceutical companies form contrasting demand poles: the former prioritizes multicolor analysis flexibility while the latter drives standardization for regulated cell-therapy manufacturing.
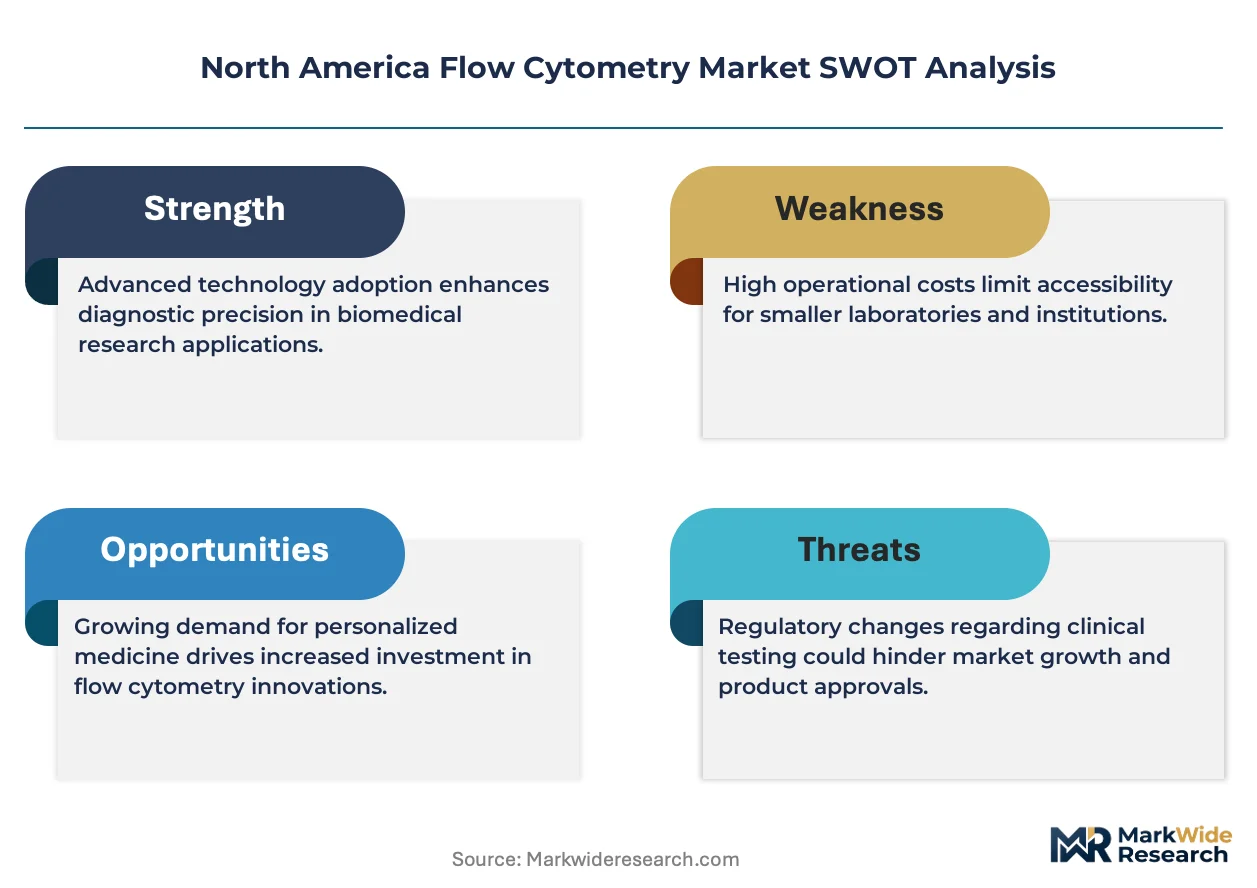
The FDA governs flow cytometry devices as in vitro diagnostics under 21 CFR Part 820 quality system regulations, while Health Canada applies the Medical Devices Regulations through its Medical Devices Bureau for products entering the Canadian market. The Clinical Laboratory Improvement Amendments administered by CMS in the United States further shape demand by mandating analytical performance verification for laboratory-developed flow cytometry tests. Stakeholders must monitor how the FDA's evolving guidance on cell and gene therapy manufacturing will redefine instrument validation requirements and software documentation standards.
Market Dynamics
The FDA's 21 CFR Part 11 electronic records mandate is compressing validation timelines for flow cytometry software platforms, forcing vendors to reengineer data integrity architectures while pharmaceutical customers demand audit-ready systems for cell-therapy manufacturing workflows.
Growth Catalysts
- Cell-therapy manufacturing standards:FDA guidance on cell and gene therapy production is mandating validated flow cytometry protocols for in-process quality control, pulling instrument upgrades across contract manufacturing organizations.
- Boston-Cambridge biotech corridor concentration:Academic institutes and CROs clustered in this hub are driving multicolor panel standardization that ripples through national procurement specifications.
- CLIA laboratory certification expansion:CMS enforcement of analytical performance verification for laboratory-developed tests is expanding the addressable market for certified reference materials and control beads.
Market Restraints
- Laser and optical component supply concentration:Specialized solid-state laser suppliers in Germany and Japan create lead time vulnerability for instrument manufacturers assembling systems in the United States.
- FDA 510(k) pathway complexity:Substantial equivalence determinations for novel fluorochrome combinations are extending premarket notification timelines beyond typical diagnostic device cycles.
- Mass spectrometry cytometry substitution:CyTOF platforms are capturing high-parameter immunophenotyping applications previously served by conventional fluorescence systems.
Strategic Opportunities
- Canadian provincial laboratory consolidation:Health Canada's Medical Devices Bureau oversight of centralized diagnostic procurement in Ontario and Quebec creates volume aggregation opportunities for qualified vendors.
- Imaging flow cytometry convergence:Integration of high-resolution microscopy with traditional scatter detection is opening spatial biology applications in immuno-oncology biomarker discovery.
- Direct-to-laboratory distribution channels:Bypassing traditional distributor networks tightens vendor control over installation, training, and consumables replenishment cycles.
Industry Challenges
- Multicolor panel design expertise scarcity:Compensation matrix construction and fluorochrome selection for 20+ color experiments require specialized cytometry scientists that academic training programs are not producing at sufficient scale.
- Legacy LIS integration complexity:Hospital laboratory information systems built on 1990s architectures resist seamless data exchange with modern flow cytometry workstations, forcing middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flow Cytometry Market |
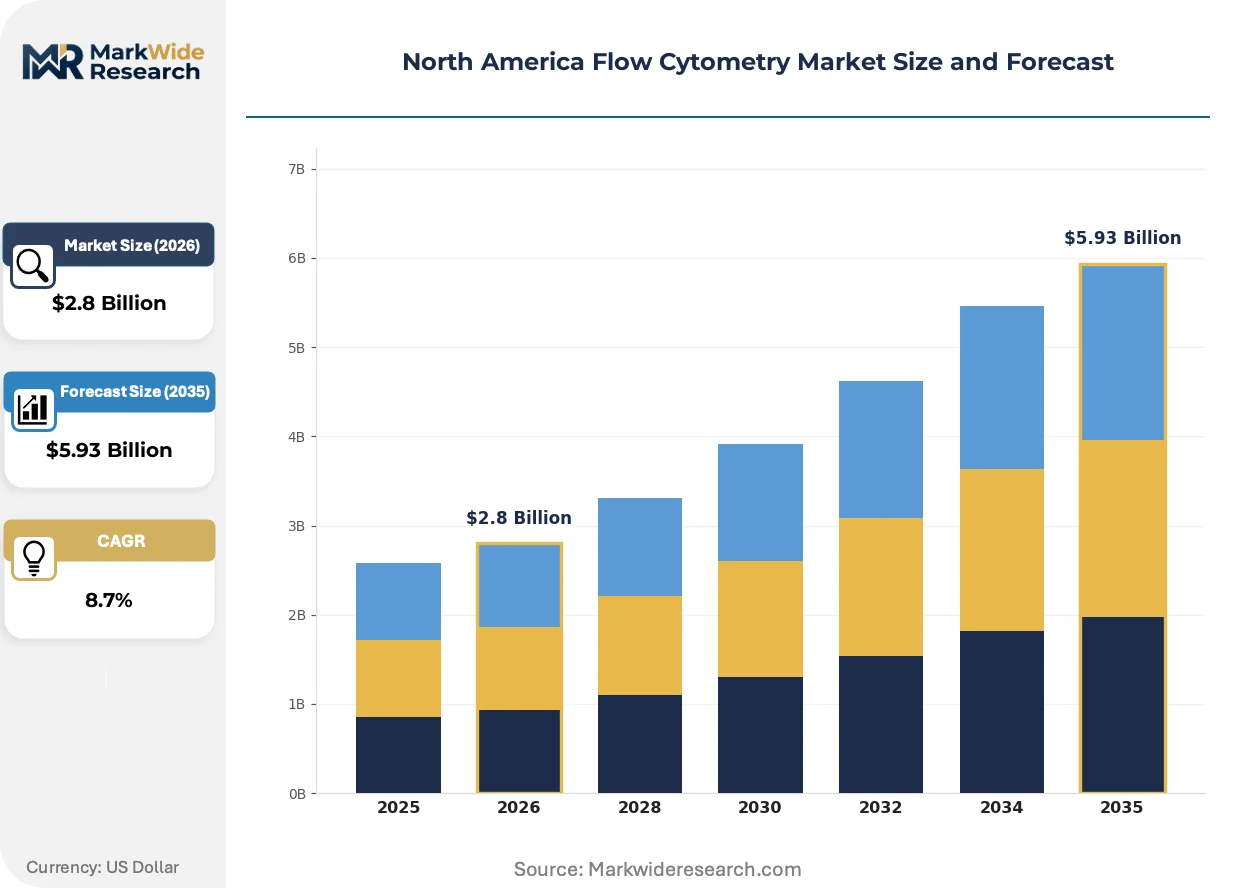
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables Application: Clinical Diagnostics, Research & Development, Immunology, Hematology End User: Academic Institutes, Hospitals, Diagnostic Laboratories, Pharmaceutical Companies Technology: Cell Sorting, Cell Analysis, Multicolor Analysis, Imaging Flow Cytometry |
| Companies Covered | Becton Dickinson, Beckman Coulter, Thermo Fisher Scientific, Bio-Rad Laboratories, Agilent Technologies, Danaher, Cytek Biosciences, Sysmex, Luminex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flow Cytometry Market Trends and Innovations
Spectral unmixing algorithms and AI-assisted gating are compressing analysis timelines while reshaping how cytometrists interact with high-dimensional datasets across research and clinical settings.
Spectral flow cytometry is digitizing traditional compensation workflows by replacing serial optical filters with continuous wavelength detection. Pharmaceutical companies running high-throughput screening campaigns are adopting these systems to compress panel development cycles. The technology is digitizing the fluorochrome selection process, enabling 40+ parameter panels that were previously optically impossible.
Health Canada's Medical Devices Regulations are tightening post-market surveillance requirements for Class III diagnostic cytometers entering the Canadian market. Manufacturers must now maintain active complaint handling systems and periodic safety update reporting that mirror FDA QSR expectations. The Canadian market is responding with preemptive quality management system investments before product registration submissions.
Academic core facilities are unbundling service contracts from instrument procurement, negotiating separate agreements for preventive maintenance, application support, and software upgrades. This disaggregation is pressuring vendors to price modules transparently rather than burying costs in bundled packages. The pattern is most visible in California and Texas university systems where centralized procurement offices mandate line-item contract decomposition.
North America Flow Cytometry Market Segmentation
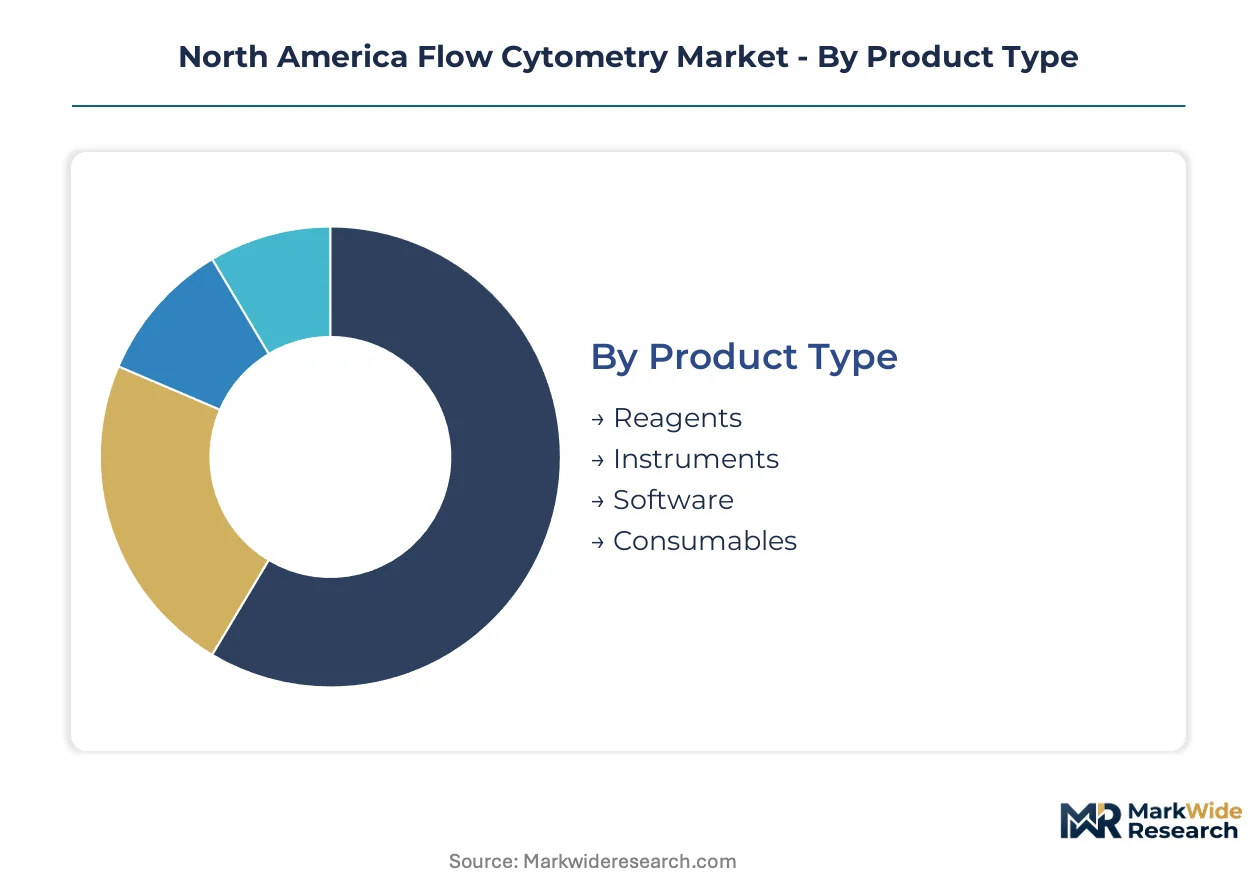
Flow cytometry vendors structure their commercial operations around distinct product and customer segments, each demanding differentiated service intensity and technical support architectures. The segmentation reveals where recurring revenue concentrates versus where capital equipment cycles dominate purchasing behavior.
Product Type:
After-sales service intensity varies dramatically across product categories, with reagents and consumables generating monthly replenishment touchpoints while instruments demand multi-year field engineering relationships.
- Reagents:Fluorochrome-conjugated antibodies and staining solutions constitute the highest-margin recurring revenue stream, with pharmaceutical companies in the Boston-Cambridge corridor driving standardization for cell-therapy quality control protocols.
- Instruments:Analytical and cell-sorting platforms represent capital-intensive procurement decisions where FDA 21 CFR Part 11 validation requirements extend sales cycles and embed vendors through multi-year service contracts.
- Software:Data analysis platforms for compensation matrix construction and gating algorithms are increasingly unbundled from hardware, with academic core facilities negotiating separate licensing for spectral unmixing modules.
- Consumables:Sheath fluid, cleaning agents, and calibration beads capture steady replacement demand, particularly in high-throughput diagnostic laboratories subject to CLIA analytical performance verification mandates.
Reagents hold the largest share; momentum sits with imaging-capable software modules as spatial biology applications expand.
Application:
Regulatory stringency creates divergent margin profiles across applications, with clinical diagnostics demanding validated workflows while research applications prioritize panel flexibility.
- Clinical Diagnostics:Leukemia/lymphoma immunophenotyping and CD4 T-cell enumeration dominate hospital laboratory menus, where CMS CLIA enforcement mandates rigorous control tracking and proficiency testing participation.
- Research & Development:Drug discovery workflows in pharmaceutical companies emphasize high-parameter screening, with spectral flow cytometry displacing conventional compensation methods for 40+ color panel development.
- Immunology:Immune monitoring for infectious disease and autoimmunity studies concentrates in academic medical centers, where core facilities manage shared instrumentation across principal investigator groups.
- Hematology:Beckman Coulter anchors this segment through specialized high-throughput workflows, capturing diagnostic laboratory volume with integrated complete blood count and flow cytometry platforms.
Clinical diagnostics commands the greatest installed base; R&D applications are climbing the fastest as cell-therapy manufacturing scales.
End User:
Procurement authority and technical sophistication vary sharply across end-user categories, shaping whether vendors sell through distributor networks or direct-to-laboratory relationships.
- Academic Institutes:Core facilities manage centralized instrumentation for multicolor analysis flexibility, with California and Texas university systems pioneering unbundled service contract structures that pressure transparent module pricing.
- Hospitals:Integrated delivery networks leverage Becton Dickinson's embedded service infrastructure for long-term contracts, though legacy laboratory information systems resist seamless data exchange with modern workstations.
- Diagnostic Laboratories:High-throughput operations prioritize hematology workflow integration, with Health Canada's Medical Devices Bureau oversight of centralized provincial procurement in Ontario and Quebec creating volume aggregation opportunities.
- Pharmaceutical Companies:Cell-therapy manufacturers demand audit-ready systems with validated protocols, pulling instrument upgrades across contract manufacturing organizations responding to FDA guidance on in-process quality control.
Hospitals represent the deepest installed base; pharmaceutical companies are gaining share fastest as regulated manufacturing workflows proliferate.
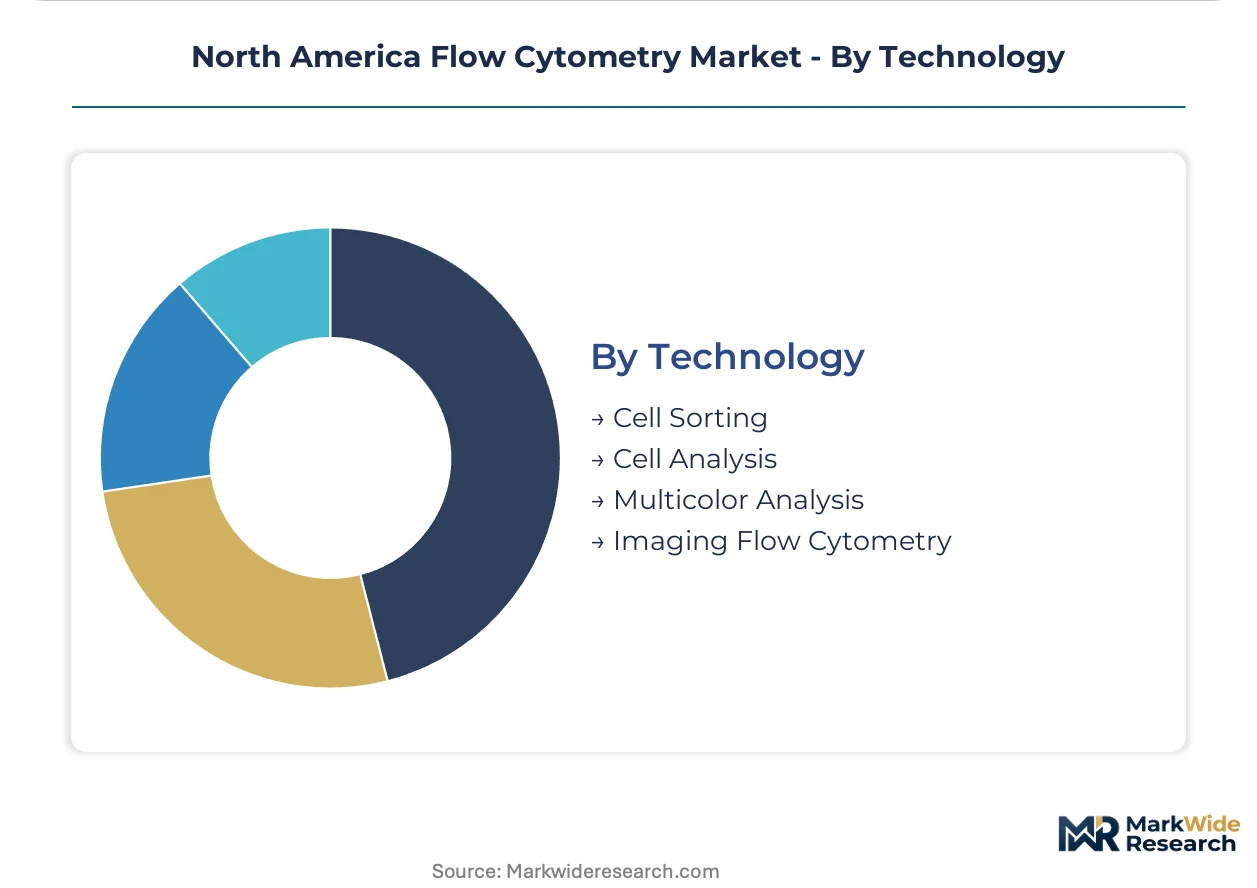
Technology:
Technical complexity and capital requirements stratify the technology landscape, with advanced modalities commanding premium pricing and specialized application expertise.
- Cell Sorting:Fluorescence-activated cell separation systems enable sterile isolation of defined populations for downstream culture or genomic analysis, with stem cell research facilities driving demand for index sorting capabilities.
- Cell Analysis:Conventional analytical cytometers remain the volume foundation, though mass spectrometry cytometry substitution threatens high-parameter immunophenotyping applications previously served by fluorescence systems.
- Multicolor Analysis:Compensation matrix construction for 20+ color experiments requires scarce specialized expertise, creating bottlenecks as academic training programs fail to produce cytometry scientists at sufficient scale.
- Imaging Flow Cytometry:Integration of high-resolution microscopy with scatter detection opens spatial biology applications, with immuno-oncology biomarker discovery programs adopting these platforms for morphology-informed quantification.
Cell analysis maintains the broadest deployment; imaging flow cytometry shows the steepest expansion trajectory as researchers demand spatial context alongside traditional intensity metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of cell and gene therapy manufacturing is reshaping procurement patterns across North America, while Health Canada applies parallel Medical Devices Regulations that tighten post-market surveillance for diagnostic cytometers entering Canadian provinces.
United States
Pharmaceutical companies in the Boston-Cambridge biotech corridor are expanding validated flow cytometry protocols for in-process quality control. The FDA's 21 CFR Part 11 electronic records mandate is compressing software validation timelines for vendors serving cell-therapy manufacturers. California and Texas university systems are pioneering unbundled service contract structures that pressure transparent module pricing from instrument suppliers.
Canada
Health Canada's Medical Devices Bureau oversees centralized diagnostic procurement in Ontario and Quebec, creating volume aggregation opportunities for qualified vendors. Provincial laboratory consolidation in these provinces is tightening technical specifications for hematology workflow integration. Manufacturers must now maintain active complaint handling systems and periodic safety update reporting that mirror FDA QSR expectations.
Mexico
Diagnostic laboratories in Mexico City and Nuevo León are upgrading analytical platforms to meet CLIA-equivalent quality standards for cross-border reference testing. The country's national health regulator applies progressive medical device classification rules that align with international harmonization efforts. Guadalajara's emerging biotechnology cluster is attracting contract research organizations seeking cost-advantaged cell analysis capabilities.
North America Flow Cytometry Market Competitive Landscape
Integrated life science conglomerates and specialized cytometry boutiques split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: diversified instrument platforms with embedded service infrastructure, reagent-focused specialists with recurring revenue models, and spectral technology disruptors challenging conventional compensation workflows. Dominant competitive moves include direct-to-laboratory distribution channel expansion and unbundled software licensing to capture academic procurement offices.
Within the diversified platform tier, Becton Dickinson and Beckman Coulter occupy positions sustained by long-term hospital network contracts and hematology workflow integration respectively. Thermo Fisher Scientific exemplifies the consumables-recurring model, tightening customer retention through sheath fluid and calibration bead replenishment cycles. Cytek Biosciences represents the spectral disruption archetype, capitalizing on pharmaceutical demand for high-parameter panel development.
| Leading Market Players |
|---|
| Becton Dickinson |
| Beckman Coulter |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Danaher |
| Cytek Biosciences |
| Sysmex |
| Luminex Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese solid-state laser suppliers compresses pricing tier spreads while forcing instrument manufacturers toward premium configured-to-order systems that absorb supply risk premiums.
Pricing Analysis
The customization-premium spread separates validated FDA 21 CFR Part 11-compliant platforms from standard research-grade instruments. Pharmaceutical cell-therapy manufacturers absorb premium pricing for audit-ready software architectures and multi-year service bundling. Academic core facilities in California and Texas university systems drive price compression through unbundled contract negotiations. Diagnostic laboratories exhibit highest price sensitivity due to CLIA-mandated analytical verification costs, while contract manufacturing organizations show lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for optical filter assemblies and electronic subcomponents. Instrument manufacturers draw from Germany, Japan, and the United States for specialized lasers, precision optics, and fluidic systems. Sheath fluid and calibration bead distribution runs through direct-to-laboratory channels that bypass traditional medical device distributors. Single-source vulnerability concentrates in solid-state laser modules, forcing manufacturers to maintain dual-qualified suppliers and extend inventory positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital networks and centralized academic procurement offices that demand transparent module pricing and unbundled service structures.
For Market Incumbents: Build switching-cost moats through embedded service infrastructure and validated protocol libraries that lock in cell-therapy manufacturers facing FDA inspection cycles. Deepen backward integration into consumables manufacturing to capture recurring sheath fluid and bead replenishment revenue. Counter spectral flow cytometry substitution threat by accelerating imaging-capable platform development. For New Entrants and Emerging Players: Pursue white-space opportunities in Canadian provincial laboratory consolidation where Health Canada oversight creates qualified-vendor entry barriers for established players. Target mid-tier diagnostic laboratories in Mexico seeking CLIA-equivalent quality upgrades. Lead with direct-to-laboratory distribution models that circumvent entrenched distributor relationships. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors spectral-capable platform specialists over conventional compensation-dependent vendors. Long-term viability hinges on software unbundling flexibility and AI-assisted gating capabilities. Watch FDA guidance evolution on cell and gene therapy manufacturing validation as the inflection signal for instrument upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 11 Software Validation | Compresses vendor development timelines while embedding pharmaceutical customer lock-in through audit-ready data architectures. |
| Spectral Platform Integration | Displaces conventional compensation workflows for 40+ color panel development in high-throughput screening applications. |
| Direct-to-Laboratory Distribution | Bypasses distributor networks to tighten vendor control over installation, training, and consumables replenishment cycles. |
| Imaging Flow Cytometry Development | Captures spatial biology demand in immuno-oncology biomarker discovery through morphology-informed quantification capabilities. |
| Canadian Provincial Partnership | Aggregates volume through Health Canada oversight of centralized diagnostic procurement in Ontario and Quebec. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cytometry core facility directors, biomedical engineers, pharmaceutical QC managers, and hospital laboratory administrators; and secondary validation against FDA 510(k) filings, Health Canada Medical Devices Bureau registrations, CMS CLIA enforcement records, and academic procurement database trends. Bottom-up instrument and reagent demand modeling triangulated against top-down market sizing from trade flow analysis.
Forecast inputs incorporated technology adoption curves across spectral and imaging modalities, regulatory validation timeline compression effects, and end-user procurement pattern shifts. Segmentation dimensions spanned product type, application, end-user category, and technology tier. CAGRs derived from regression analysis of historical capital equipment replacement cycles and consumables replenishment velocity across the projection horizon.
Sensitivities concentrate around FDA guidance revisions on cell-therapy manufacturing, Health Canada post-market surveillance tightening, and mass spectrometry cytometry substitution rates. Forecasts reflect documented assumptions regarding laser component supply stability and academic funding continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Telepathology Market