
 Circulating Tumor Cells (Ctcs) Prognostic Technologies Market | 2026-2036
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market Outlook
Oncology clinics is reorganizing procurement priorities around non-invasive monitoring protocols, shifting volume away from centralized reference laboratories. Thermo Fisher Scientific leverages its clinical diagnostics infrastructure to sustain instrument placement contracts across integrated delivery networks. QIAGEN anchors molecular profiling workflows with sample-to-insight automation that reduces manual CTC isolation variability. Bio-Techne Corporation specializes in reagent systems that support downstream single-cell genomic analysis from enriched circulating tumor cell populations.
Circulating Tumor Cells prognostic technologies isolate and enumerate viable tumor cells from peripheral blood using immunomagnetic separation, microfluidic dielectrophoresis, or size-based filtration with detection thresholds approaching one cell per milliliter. These platforms enable real-time treatment response monitoring and minimal residual disease surveillance without repeated tissue biopsy. CellSearch technology occupies the established clinical segment with FDA-cleared enumeration for breast, colorectal, and prostate cancer prognostication. CTC-iChip microfluidic systems represent the fastest-expanding technology category as researchers adopt label-independent isolation for broader cancer type applicability. Reagents command concentrated margin pools due to recurring purchase obligations tied to instrument-installed bases.
FDA premarket notification requirements and CLIA high-complexity laboratory certification shape commercial access for CTC enumeration assays in the United States. EMA in vitro diagnostic regulation and MDR conformity assessment create parallel compliance obligations for European market entry. Stakeholders must monitor evolving payer coverage determinations for liquid biopsy codes versus tissue-based testing to align capital deployment with reimbursement trajectories.
Market Dynamics
The transition from tissue-based to liquid biopsy protocols is compressing CTC isolation workflows into point-of-care settings, forcing instrument manufacturers to redesign for decentralized deployment rather than centralized laboratory scale-up.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for companion diagnostics is reducing commercialization timelines for CTC enumeration assays in breast and prostate cancer monitoring.
- Oncology clinic consolidation:Integrated health networks in the United States are standardizing CTC-based minimal residual disease surveillance across multi-site cancer centers.
- Microfluidic dielectrophoresis:Label-independent isolation technology is expanding CTC capture applicability beyond epithelial cancers to melanoma and sarcoma subtypes.
Market Restraints
- Antibody reagent cost volatility:EpCAM and cytokeratin conjugate supply concentrates among three specialty chemical suppliers, creating input price instability for immunomagnetic separation kits.
- CLIA high-complexity certification friction:Personnel qualification requirements and proficiency testing mandates limit laboratory participation in CTC assay commercialization.
- Tissue biopsy institutional inertia:Pathology departments retain reimbursement advantages and clinical authority over liquid biopsy alternatives.
Strategic Opportunities
- India diagnostic laboratory expansion:Private hospital chains in Mumbai and Bangalore are investing in liquid biopsy infrastructure ahead of CDSCO regulatory framework finalization.
- AI-assisted CTC morphometry:Deep learning classification of circulating tumor cell images is converging with automated enumeration platforms to reduce pathologist review burden.
- Home collection service models:Direct-to-patient blood draw networks are bypassing hospital-based phlebotomy for longitudinal treatment monitoring.
Industry Challenges
- Bioinformatics specialist scarcity:Single-cell genomic analysis from enriched CTC populations requires computational biology expertise that outpaces current training pipeline output.
- Instrument-software integration complexity:Microfluidic chip readers and laboratory information management systems lack standardized data exchange protocols, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circulating Tumor Cells (Ctcs) Prognostic Technologies Market |
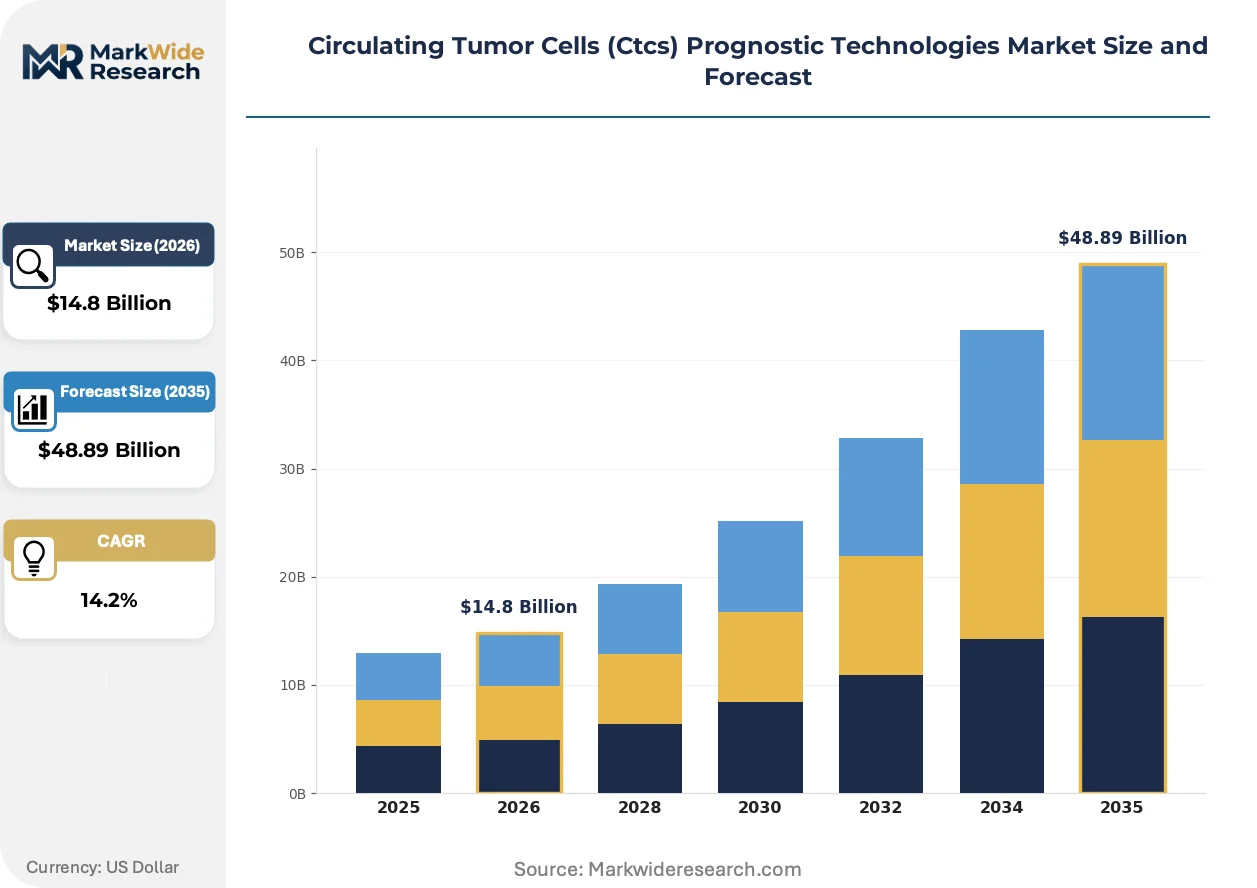
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $48.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: CellSearch, DEPArray, OncoBC, CTC-iChip End User: Research Laboratories, Hospitals, Diagnostic Centers, Oncology Clinics Application: Breast Cancer, Colorectal Cancer, Lung Cancer, Prostate Cancer Product Type: Reagents, Instruments, Consumables, Software |
| Companies Covered | Thermo Fisher Scientific Inc., QIAGEN, Bio-Techne Corporation, Menarini Silicon Biosystems, Precision for Medicine, Fluxion Biosciences Inc., Miltenyi Biotec, Greiner Bio One International GmbH, Ikonisys Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market Strategic Shifts
CTC prognostic technology is fragmenting across isolation methodology, detection sensitivity, and clinical application scope. Three concurrent developments are reshaping competitive positioning and value capture models.
Microfluidic CTC-iChip systems are decomposing the dominance of immunomagnetic CellSearch technology by enabling label-independent capture based on size and deformability. Academic medical centers in Germany and Japan are adopting these platforms for rare cancer type research. The shift is compressing reagent margin pools as instrument manufacturers compete on consumable lock-in versus open-system flexibility.
EMA In Vitro Diagnostic Regulation (IVDR) conformity assessment timelines are extending market entry pathways for European CTC assay commercialization. Manufacturers are responding by front-loading clinical validation studies to support Class C device classification. Breast cancer prognostication applications face the steepest documentation requirements under the new risk-based framework.
Hospital procurement committees are consolidating vendor contracts around sample-to-insight automation bundles rather than discrete instrument purchases. Integrated delivery networks in Texas and California are leading this transition, replacing point-solution procurement with multi-year service agreements. The model shifts capital expenditure to operational budgets while embedding vendor technical support into clinical workflow design.
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market Segmentation
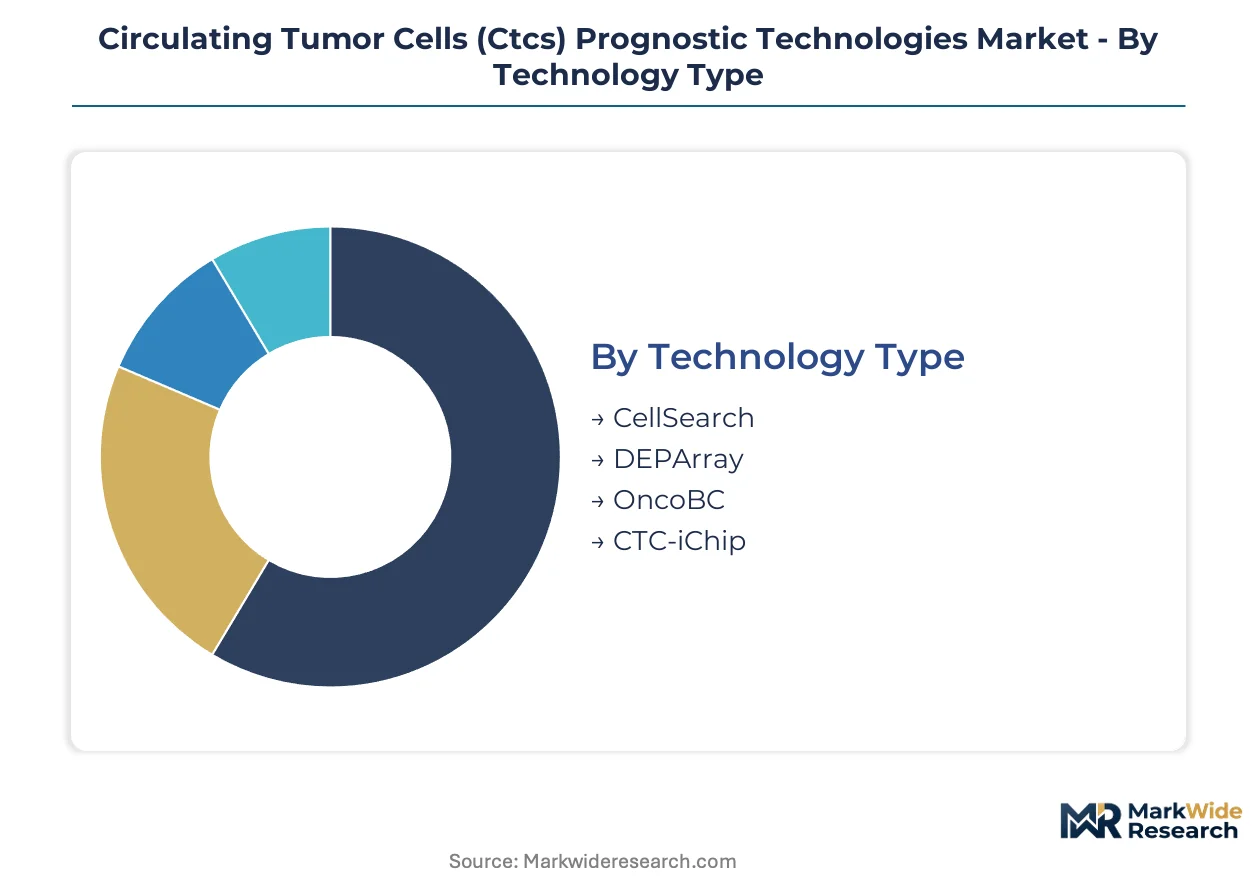
CTC prognostic technologies fragment across isolation methodologies, clinical settings, and downstream analytical workflows. Each segmentation dimension carries distinct margin structures, regulatory pathways, and vendor competitive dynamics that shape capital deployment decisions.
Technology Type:
Immunomagnetic platforms face substitution pressure from label-independent microfluidic systems as researchers expand beyond epithelial cancer applications.
- CellSearch:FDA-cleared immunomagnetic enumeration platform using EpCAM-coated ferrofluid capture. Academic medical centers in the United States anchor demand for breast, colorectal, and prostate cancer prognostication protocols.
- CTC-iChip:Microfluidic dielectrophoresis system enabling size and deformability-based isolation without antibody labeling. German and Japanese research institutes drive adoption for melanoma and sarcoma subtype investigation.
- DEPArray:Dielectrophoretic cell manipulation technology combining enrichment with single-cell recovery for downstream genomic analysis.
- OncoBC:Proprietary isolation workflow optimized for blood-based biomarker multiplexing in oncology monitoring applications.
CellSearch anchors the volume base while CTC-iChip gains share at the steepest rate.
End User:
Procurement authority is migrating from centralized reference laboratories toward point-of-care settings as decentralized testing infrastructure matures.
- Oncology Clinics:Integrated health networks in Texas and California are consolidating CTC-based minimal residual disease surveillance across multi-site cancer centers.
- Hospitals:Academic medical centers drive protocol standardization for treatment response monitoring in breast and prostate cancer patient populations.
- Diagnostic Centers:CLIA high-complexity certified laboratories commercialize CTC enumeration assays under FDA 510(k) cleared workflows.
- Research Laboratories:Single-cell genomic analysis from enriched CTC populations requires computational biology expertise that outpaces current training pipeline output.
Hospitals command the installed instrument base while oncology clinics expand most quickly as procurement decentralizes.
Application:
Reimbursement coding advantages for tissue-based diagnostics create persistent headwinds against liquid biopsy penetration in certain cancer types.
- Breast Cancer:CellSearch enumeration claims FDA clearance for prognostication in metastatic settings, with EMA IVDR conformity assessment imposing steepest documentation requirements under Class C device classification.
- Prostate Cancer:Androgen receptor variant detection from CTC-derived nucleic acids is reshaping therapeutic resistance monitoring in castration-resistant subtypes.
- Colorectal Cancer:KRAS mutation profiling from liquid biopsy specimens competes with tissue-based companion diagnostic standards.
- Lung Cancer:EGFR T790M resistance mutation surveillance from CTC-derived DNA faces reimbursement uncertainty versus plasma ctDNA alternatives.
Breast cancer anchors the assay revenue base while prostate cancer applications climb the fastest amid therapeutic resistance monitoring demand.
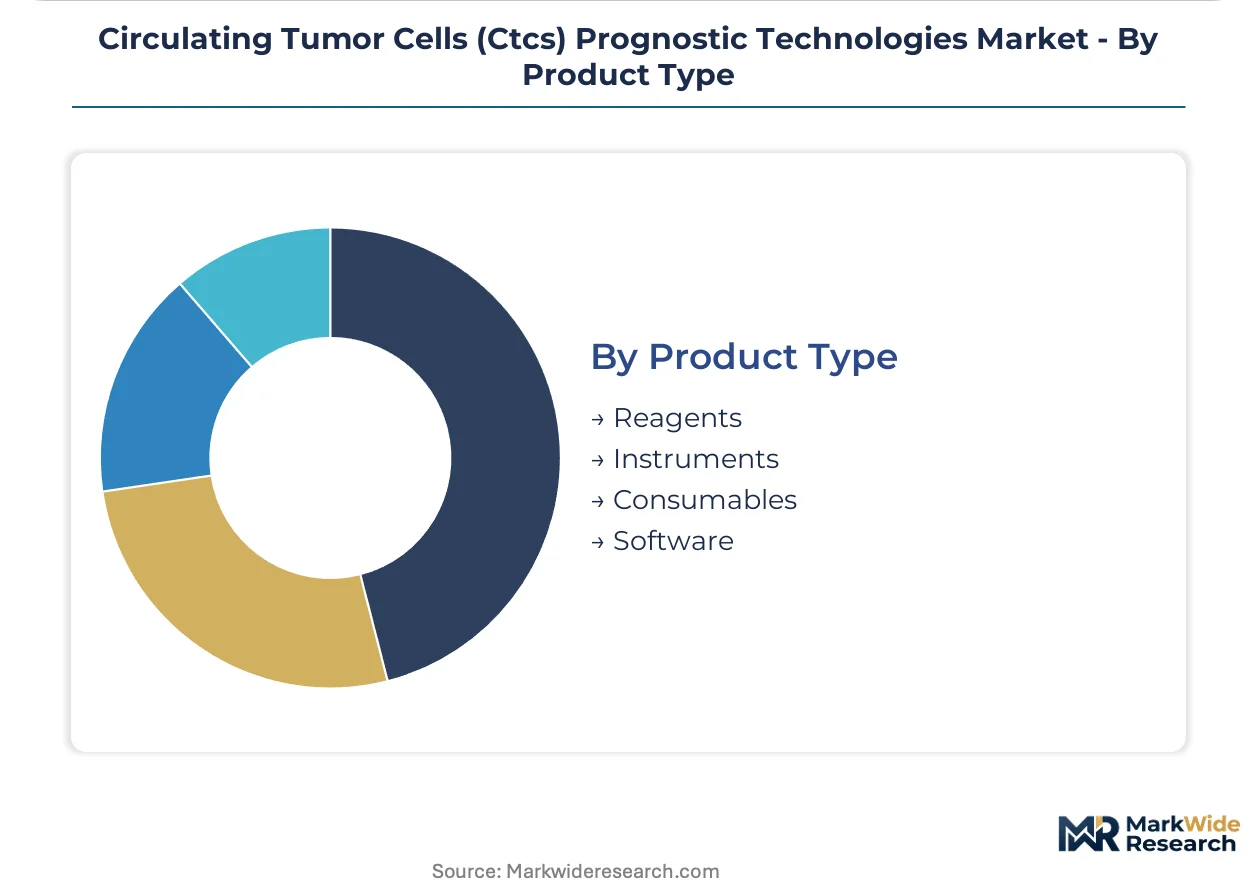
Product Type:
Margin capture concentrates in recurring consumable purchases tied to instrument lock-in, forcing vendors to defend position through reagent supply contracts.
- Reagents:EpCAM and cytokeratin conjugate supply concentrates among three specialty chemical suppliers, creating input price instability for immunomagnetic separation kits.
- Instruments:Microfluidic chip readers and laboratory information management systems lack standardized data exchange protocols, forcing custom middleware development.
- Consumables:Single-use microfluidic cartridges and collection tubes generate recurring revenue streams proportional to test volume expansion.
- Software:AI-assisted CTC morphometry platforms using deep learning classification are converging with automated enumeration to reduce pathologist review burden.
Reagents generate the highest margin contribution while software represents the steepest expansion trajectory as AI-assisted classification matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology clinics and academic medical centers in the United States, Germany, Japan, India, and China concentrate procurement authority for CTC isolation platforms. Each geography presents distinct regulatory pathways and infrastructure maturity levels that shape vendor market entry strategies.
United States
FDA 510(k) premarket notifications and CLIA high-complexity laboratory certification dominate commercial access requirements for CTC enumeration assays. Integrated health networks in Texas and California are consolidating minimal residual disease surveillance protocols across multi-site cancer centers. The Boston-Cambridge corridor anchors single-cell genomic research from enriched CTC populations.
Germany
EMA In Vitro Diagnostic Regulation (IVDR) conformity assessment timelines are extending market entry pathways for CTC assay commercialization. Class C device classification imposes steepest documentation requirements for breast cancer prognostication applications. Heidelberg and Munich research institutes drive adoption of CTC-iChip microfluidic systems for melanoma and sarcoma subtype investigation.
Japan
PMDA regulatory consultations are accelerating companion diagnostic pathway development for CTC-based liquid biopsy workflows. METI industrial policy supports domestic microfluidic manufacturing capacity expansion. Tokyo and Osaka academic medical centers standardize treatment response monitoring protocols for castration-resistant prostate cancer subtypes.
India
Private hospital chains in Mumbai and Bangalore are investing in liquid biopsy infrastructure ahead of CDSCO regulatory framework finalization. Central Drugs Standard Control Organization draft guidelines for in vitro diagnostics are creating pre-compliance investment windows. Diagnostic laboratory expansion concentrates in Maharashtra and Karnataka state clusters.
China
NMPA innovative medical device review pathways are compressing approval timelines for microfluidic CTC isolation platforms. National reimbursement catalog negotiations determine hospital procurement eligibility for liquid biopsy assays. Shanghai and Beijing integrated cancer centers pilot real-time treatment response monitoring without repeated tissue biopsy.
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market Competitive Environment
Player mix skews toward diversified life science conglomerates with clinical diagnostics infrastructure. Market structure exhibits moderate consolidation around instrument-reagent bundling models. Three strategic archetypes dominate: sample-to-insight automation specialists, immunomagnetic separation kit suppliers, and microfluidic platform innovators. Competitive moves center on multi-year service agreements replacing point-solution procurement and AI-assisted morphometry software integration.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and QIAGEN exemplify instrument placement contract strategies across integrated delivery networks. Bio-Techne Corporation occupies a position among reagent specialists supporting downstream single-cell genomic analysis. These three entities represent contrasting approaches to margin capture—through consumable lock-in, workflow automation, or analytical reagent supply.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Bio-Techne Corporation |
| Menarini Silicon Biosystems |
| Precision for Medicine |
| Fluxion Biosciences Inc. |
| Miltenyi Biotec |
| Greiner Bio One International GmbH |
| Ikonisys Inc. |
| Others |
Value Chain & Pricing Dynamics
CLIA high-complexity laboratory certification gates both supplier qualification and price differentiation simultaneously, as only certified laboratories can commercialize CTC enumeration assays under FDA-cleared workflows. This regulatory threshold segments the market into premium-tier automated platforms serving integrated health networks and economy-tier manual workflows constrained by personnel qualification bottlenecks.
Pricing Analysis
Cost-plus contracts with antibody reagent indexation dominate CTC isolation kit procurement, tying instrument placement agreements to recurring consumable purchases. Price differentiation rests on FDA clearance tier and automation level, with 510(k)-cleared platforms commanding premiums over research-use-only alternatives. Cost compression in manual immunomagnetic separation kits is intensifying because EpCAM conjugate supply concentrates among three specialty chemical suppliers. Academic medical centers exhibit lowest price sensitivity due to grant-funded research budgets, while independent diagnostic laboratories face acute margin pressure from proficiency testing mandates.
Supply Chain Analysis
China and Japan anchor microfluidic chip fabrication for CTC-iChip systems, with Germany supplying precision dielectrophoresis instrumentation. Raw material dependencies include silicon wafers, ferrofluid nanoparticles, and EpCAM antibody conjugates. Single-source vulnerability concentrates in specialty chemical suppliers for immunomagnetic reagents. Distribution runs through integrated delivery network procurement committees consolidating multi-year service agreements rather than discrete instrument purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
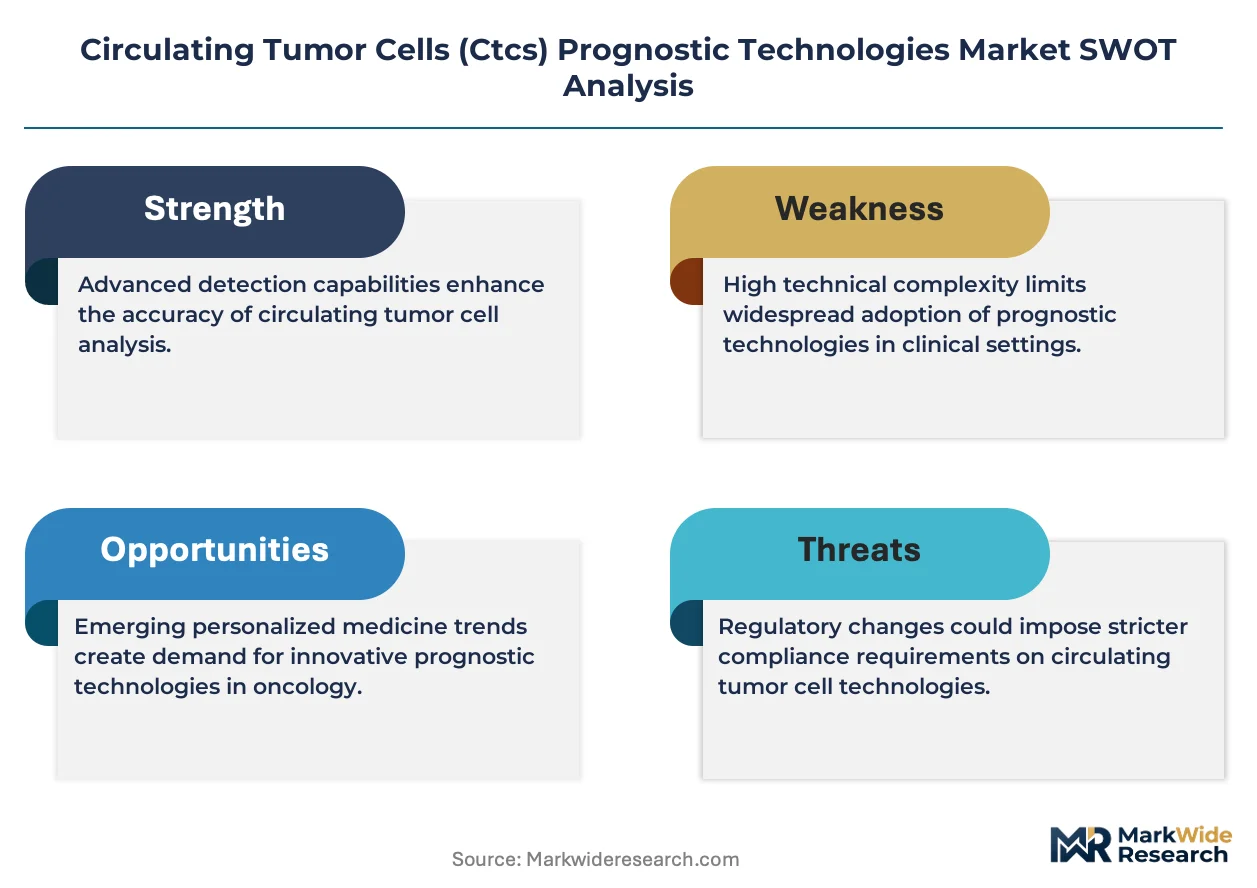
Circulating tumor cell prognostic technologies occupy an early-cycle expansion phase, with FDA 510(k) pathway acceleration for companion diagnostics compressing commercialization timelines and expanding addressable oncology monitoring protocols.
For Market Incumbents: Fortify instrument-reagent bundling contracts across Texas and California integrated health networks before microfluidic label-independent platforms displace immunomagnetic CellSearch dominance. Prioritize backward integration into antibody conjugate production to mitigate EpCAM supply volatility from specialty chemical suppliers. Expand CLIA laboratory technical support staffing to reduce customer proficiency testing failure rates that threaten account retention.
For New Entrants and Emerging Players: Differentiate on AI-assisted CTC morphometry software integration, where deep learning classification platforms reduce pathologist review burden and create workflow stickiness. Target private hospital chains in Mumbai and Bangalore ahead of CDSCO regulatory framework finalization, exploiting pre-compliance investment windows before incumbent instrument placement contracts harden. Pursue hospital-at-home blood collection service models bypassing hospital-based phlebotomy infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microfluidic platform manufacturing as domestic production capacity expands in China and Japan. Long-term viability favors sample-to-insight automation specialists with installed base lock-in rather than point-solution instrument vendors exposed to reagent margin compression. Monitor EMA IVDR Class C device classification timelines as the critical inflection signal for European market entry cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Morphometry Development | Deep learning classification reduces pathologist review burden in CTC enumeration workflows. |
| CLIA Laboratory Partnership Expansion | Technical support embedding secures multi-year service agreements with integrated health networks. |
| Antibody Conjugate Backward Integration | Captive EpCAM supply mitigates input price instability from specialty chemical suppliers. |
| Home Collection Service Infrastructure | Direct-to-patient blood draw networks bypass hospital phlebotomy for longitudinal monitoring. |
| EMA IVDR Pre-Validation Investment | Front-loaded clinical studies compress European market entry timelines under Class C classification. |
Study Parameters
A standing panel of oncology clinic procurement directors, CLIA laboratory medical directors, microfluidic platform engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EMA IVDR submission databases, hospital procurement records, and CMS Medicare reimbursement determinations. Bottom-up instrument placement tracking and top-down reagent revenue modeling were triangulated against integrated health network capital expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include isolation technology type, end-user setting, cancer application, and regional regulatory cluster. CAGRs were derived from instrument installed base expansion rates and per-test consumable revenue trajectories, with inputs from companion diagnostic approval timelines and payer coverage determination patterns.
The analysis sits within stated boundaries; outcomes outside FDA clearance pathway acceleration or EMA IVDR timeline compression would require recalibration. Forecasts reflect assumptions regarding reimbursement code expansion for liquid biopsy protocols and laboratory personnel training pipeline output. Recalibration cycles align with material shifts in regulatory approval timelines and integrated health network consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Stem Cell Panel Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Global ELISA Analyzer Market