
 Retinal Gene Therapy Market | 2026-2036
Retinal Gene Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Gene Therapy Market Analytics
Market Context
Platform licensing revenue from AAV manufacturing is narrowing as sponsors bring vector production in-house. Novartis leverages its established gene therapy infrastructure across European and North American markets. Spark Therapeutics sustains competitive positioning through specialized expertise in ophthalmic delivery systems. REGENXBIO anchors its presence via proprietary NAV technology platform partnerships with multiple biopharma developers.
Technical Definition and Structural Segments
Retinal gene therapy comprises nucleic acid-based interventions delivered to retinal tissue to correct or compensate for genetic mutations causing vision loss, typically employing recombinant adeno-associated virus vectors engineered for photoreceptor or retinal pigment epithelium transduction at titers exceeding 10^13 vector genomes per milliliter. The therapy area dimension shows Leber Congenital Amaurosis representing the most mature segment with approved commercial products, while Stargardt Disease programs are advancing through late-stage trials and Retinitis Pigmentosa pipelines are broadening addressable patient populations. Delivery mode segmentation reveals subretinal injection maintains primacy for precise vector placement beneath the retina, though intravitreal administration routes are gaining development investment for less invasive therapeutic access.
Regulatory Framework and Outlook
FDA's Office of Therapeutic Products within CBER oversees gene therapy IND and BLA reviews with specialized guidance for ocular indications, while EMA's Committee for Advanced Therapies evaluates centralized marketing authorizations across EU member states under ATMP classification. REACH and GMP vector manufacturing standards constrain supplier qualification and batch release timelines for European market entry. Stakeholders must monitor evolving FDA guidance on long-term follow-up requirements for integrating vectors and corresponding payer evidence demands for durable efficacy demonstrations.
Market Dynamics
Vector manufacturing consolidation is compressing supply timelines as sponsors internalize AAV production capabilities, shifting bargaining power from contract manufacturers to integrated biopharma developers and reshaping platform economics across the value chain.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed BLA review timelines for ocular gene therapies are shortening commercialization cycles for inherited retinal disease programs. Sponsors leverage regenerative medicine advanced therapy designation to access priority review resources.
- Germany's Hospital Reimbursement Framework:Diagnosis-related group carve-outs for one-time gene therapies are enabling inpatient administration at specialized ocular centers. Payer agreements now cover vector costs alongside procedural fees.
- Subretinal Delivery Automation:Surgical robotics for precise vector placement beneath the retinal pigment epithelium are reducing procedure variability. Training protocols at academic medical centers are standardizing technical competency.
Market Restraints
- Plasmid DNA Supply Concentration:North American and European contract manufacturers control critical raw material inputs for AAV backbone production. Batch release timelines extend when qualified suppliers face capacity constraints.
- EMA ATMP Classification Complexity:Centralized marketing authorization requirements under Committee for Advanced Therapies jurisdiction create documentation burdens. Member state reimbursement negotiations add sequential approval delays.
- Long-Term Follow-Up Burden:FDA guidance on fifteen-year safety monitoring for integrating vectors imposes patient registry costs. Payer evidence demands for durable efficacy compress net present value of approved therapies.
Strategic Opportunities
- Japan's Orphan Drug Incentives:PMDA sakigake designation provides priority review and extended exclusivity for retinitis pigmentosa indications. Reimbursement premiums for designated therapies improve commercial economics.
- Intravitreal Route Development:Less invasive vector administration through the vitreous cavity expands treatable patient populations. Formulation advances in capsid engineering are overcoming physical barriers to retinal transduction.
- Stargardt Disease Expansion:Late-stage pipeline assets target the larger addressable population beyond Leber congenital amaurosis. Disease awareness campaigns at retinal specialty centers are accelerating genetic testing uptake.
Industry Challenges
- Ocular Surgical Specialist Scarcity:Vitreoretinal surgeons capable of subretinal injection represent a bottleneck for therapy access. Fellowship training programs at academic medical centers require multi-year expansion timelines.
- Vector Potency Assay Standardization:In vitro infectivity measurements lack harmonization across contract manufacturing organizations. Release testing discrepancies between sites complicate multi-source supply strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Gene Therapy Market |
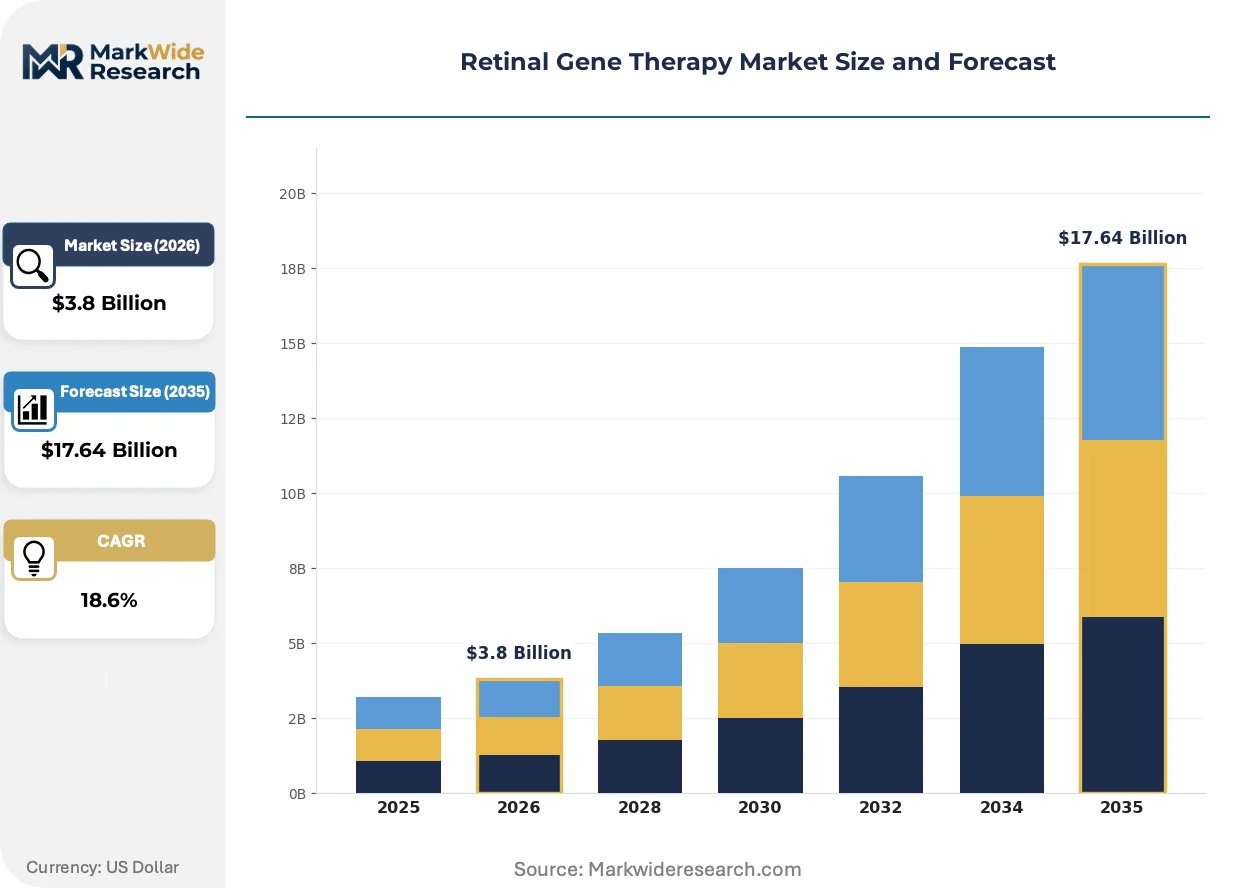
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adeno-Associated Virus, Lentivirus, Plasmid DNA, CRISPR Therapy Area: Retinitis Pigmentosa, Stargardt Disease, Leber Congenital Amaurosis, Macular Degeneration Delivery Mode: Intravitreal Injection, Subretinal Injection, Systemic Administration, Topical Application End User: Hospitals, Research Institutes, Ophthalmology Clinics, Biotech Companies |
| Companies Covered | Novartis, Spark Therapeutics, Adverum Biotechnologies, REGENXBIO Inc., MeiraGTx Holdings plc, Applied Genetic Technologies Corporation, Biogen Inc., Coave Therapeutics, Beacon Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Gene Therapy Market Evolving Landscape
In silico design platforms are compressing capsid engineering cycles, while regulatory frameworks adapt to real-world evidence generation and procurement models evolve toward outcomes-based arrangements for one-time curative interventions.
Machine learning algorithms trained on structural biology datasets are predicting AAV capsid variants with enhanced retinal tropism and reduced immunogenicity. Biopharma sponsors at integrated discovery centers deploy these tools to bypass iterative screening cycles. This computational approach is virtualizing the traditional wet-lab optimization bottleneck that previously consumed eighteen to twenty-four months per candidate.
REACH and GMP vector manufacturing standards in Europe are constraining supplier qualification timelines for clinical and commercial batches. EMA's centralized ATMP classification requires extensive comparability protocols when manufacturing sites change. European sponsors respond by qualifying dual-source plasmid suppliers and investing in in-house analytical method development to reduce external dependency.
Hospital procurement committees are consolidating gene therapy purchasing decisions under pharmacy and therapeutics subcommittees rather than individual physician preference. Specialty distributors with cold-chain logistics capabilities are displacing traditional wholesale relationships for vector products. This channel concentration is most visible in United States academic medical centers where integrated delivery networks negotiate enterprise-level contracts spanning multiple therapeutic areas.
Retinal Gene Therapy Market Segmentation
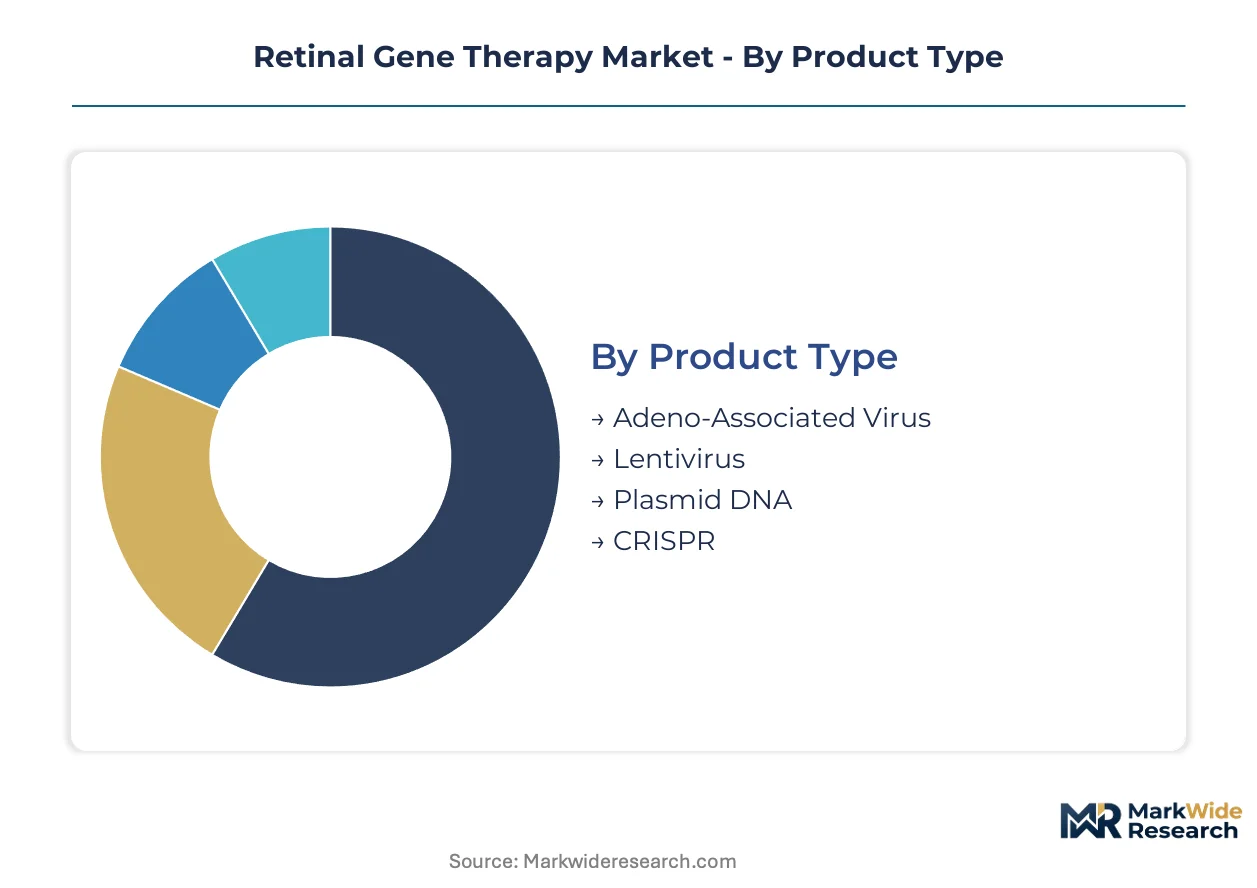
Retinal gene therapy segmentation reveals how vector engineering choices, disease target selection, and administration complexity create distinct commercial pathways. Each dimension carries implications for manufacturing scale, reimbursement negotiation, and patient access geography.
Product Type:
Maturity varies sharply across vector platforms, with established viral systems anchoring near-term revenue while gene editing tools build clinical validation.
- Adeno-Associated Virus:Recombinant AAV serotypes engineered for photoreceptor transduction dominate approved products and late-stage pipelines. Manufacturing infrastructure concentrates in Massachusetts, Pennsylvania, and North Carolina facilities where sponsors have internalized production.
- Lentivirus:Integrating vectors enable larger transgene payloads for complex genetic corrections, though FDA's fifteen-year follow-up guidance dampens commercial enthusiasm. Development activity clusters in academic medical center spinouts targeting Stargardt disease.
- Plasmid DNA:Non-viral delivery platforms circumvent immunogenicity concerns but face transfection efficiency barriers in retinal tissue. European sponsors explore electroporation-enhanced administration for macular degeneration.
- CRISPR:In vivo base editing approaches remain preclinical for most inherited retinal diseases. Allogeneic ex vivo programs at research institutes in California and Massachusetts are advancing toward first-in-human studies.
Adeno-associated virus handles the majority of throughput; CRISPR is gaining share fastest as editing specificity improves.
Therapy Area:
Addressable population size and genetic heterogeneity create divergent investment profiles across inherited retinal diseases.
- Leber Congenital Amaurosis:RPE65 mutation-specific approvals established regulatory precedent and payer frameworks. Treatment windows narrow to pediatric populations before photoreceptor degeneration advances.
- Stargardt Disease:ABCA4 mutation complexity requires larger gene cassettes, favoring dual-vector or lentiviral strategies. Patient advocacy in Germany and Japan is accelerating genetic screening penetration.
- Retinitis Pigmentosa:Heterogeneous genetic etiology demands mutation-agnostic approaches or extensive companion diagnostic infrastructure. Intravitreal route development expands treatable cohorts beyond surgical subretinal candidates.
- Macular Degeneration:Age-related forms present larger populations but complex multifactorial pathophysiology challenges monogenic correction paradigms. Gene therapy complements rather than replaces anti-VEGF regimens in current development.
Leber congenital amaurosis retains installed base leadership; Stargardt disease shows steepest expansion trajectory as vector payload engineering matures.
Delivery Mode:
Invascularity and surgical complexity segment the market between precision interventions and scalable administration.
- Subretinal Injection:Direct vector placement beneath retinal pigment epithelium achieves highest transduction efficiency for photoreceptor targets. Vitreoretinal surgeon scarcity in United States academic centers constrains therapy access.
- Intravitreal Injection:Vitreous cavity administration leverages existing anti-VEGF infrastructure but requires capsid engineering to overcome inner limiting membrane barriers. Formulation advances at biotechnology developers in Switzerland and California are improving retinal penetration.
- Systemic Administration:Intravenous delivery avoids ocular surgical risk but demands blood-retinal barrier penetration and risks systemic immunogenicity. Preclinical programs explore engineered AAV variants with enhanced retinal tropism.
- Topical Application:Eye drop formulations remain investigational for gene therapy payloads, limited by corneal and conjunctival barriers to posterior segment access. Research institutes in Japan are pioneering penetration-enhancing excipient development.
Subretinal injection commands premium pricing; intravitreal routes are climbing fastest as surgical robotics standardize technique.
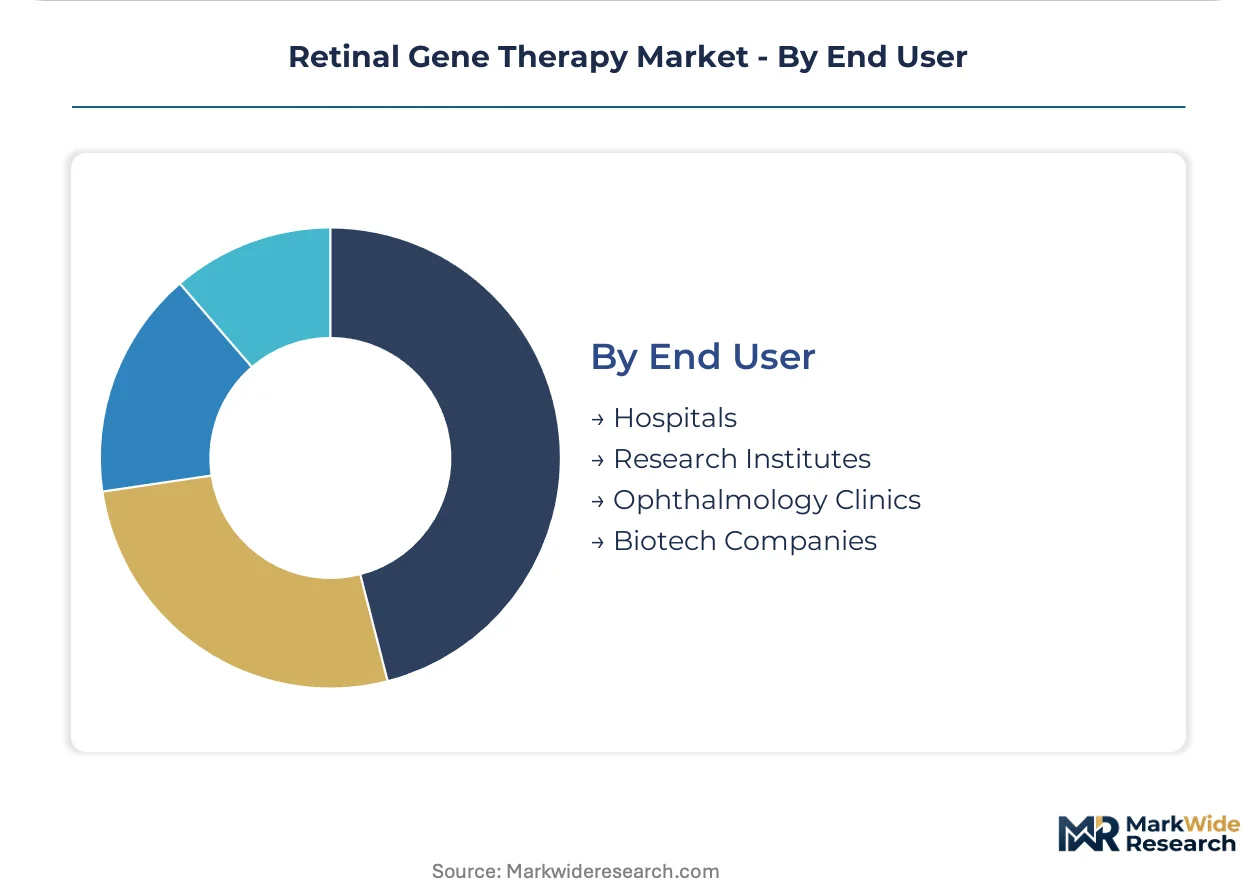
End User:
Site-of-care economics and technical capability requirements distribute patients across institutional settings.
- Hospitals:Academic medical centers with integrated vitreoretinal surgery and gene therapy pharmacy capabilities anchor commercial administration. Diagnosis-related group carve-outs in Germany enable inpatient reimbursement for one-time therapies.
- Ophthalmology Clinics:Specialized retinal practices with surgical suites and cold-chain logistics partnerships extend geographic access. United States integrated delivery networks are consolidating purchasing decisions under pharmacy and therapeutics committees.
- Research Institutes:Early-phase clinical trial execution and natural history study enrollment concentrate at National Institutes of Health-funded centers and European reference networks.
- Biotech Companies:Sponsors with internal manufacturing and clinical operations are bypassing traditional site-of-care distinctions through company-sponsored treatment protocols.
Hospitals manage the highest patient volumes; ophthalmology clinics are expanding quickest as surgical training programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payer willingness varies sharply across geographies, with United States and Germany absorbing premium pricing while emerging markets remain price-sensitive. Hospital infrastructure and specialized surgical capacity determine therapy access more than regulatory approval speed.
United States
Academic medical centers in Massachusetts, Pennsylvania, and North Carolina anchor commercial administration through integrated vitreoretinal surgery and gene therapy pharmacy capabilities. FDA's Office of Therapeutic Products within CBER oversees IND and BLA reviews with specialized guidance for ocular indications, compressing development timelines for sponsors with regenerative medicine advanced therapy designation. Boston and Philadelphia clusters concentrate sponsor manufacturing infrastructure and clinical trial execution.
Germany
Diagnosis-related group carve-outs for one-time gene therapies enable inpatient administration at specialized ocular centers in Berlin, Munich, and Heidelberg. EMA's Committee for Advanced Therapies evaluates centralized marketing authorizations under ATMP classification, while REACH and GMP vector manufacturing standards constrain supplier qualification timelines. Bavarian and Baden-Württemberg regions host reference networks for inherited retinal disease natural history studies.
Japan
PMDA sakigake designation provides priority review and extended exclusivity for retinitis pigmentosa indications, with reimbursement premiums improving commercial economics for approved therapies. Tokyo and Osaka academic centers lead patient advocacy engagement and genetic screening penetration for Stargardt disease. The country's national pharmaceutical regulator coordinates with specialized ocular gene therapy centers to standardize surgical training protocols.
Switzerland
Swissmedic marketing authorizations leverage EMA centralized procedures while maintaining independent pricing negotiations with cantonal hospital networks. Basel and Zurich clusters concentrate biotechnology sponsor headquarters and vector engineering research institutes. The country's regulatory framework accommodates early-access programs for pediatric Leber congenital amaurosis patients before full commercial rollout.
United Kingdom
NHS England specialized commissioning frameworks negotiate outcomes-based reimbursement for one-time curative interventions, with London and Manchester academic centers anchoring treatment delivery. The country's national pharmaceutical regulator aligns with EMA ATMP classification while maintaining independent post-authorization safety monitoring requirements. Scottish and Welsh health boards participate in UK-wide patient registries for long-term follow-up data collection.
Retinal Gene Therapy Market Competitive Landscape
Capability concentration sits with integrated vector manufacturing specialists; scale advantage sits with diversified pharmaceutical sponsors with established rare disease commercial infrastructure. The market structures around three tiers: platform technology licensors with proprietary capsid libraries, integrated biopharma developers with in-house AAV production, and regional contract manufacturers qualifying under multi-jurisdictional GMP standards. Dominant competitive moves include backward integration into plasmid DNA supply and strategic partnerships for intravitreal route formulation rights.
Among diversified pharmaceutical sponsors, Novartis and Biogen occupy positions spanning commercial infrastructure and rare disease payer relationships. Spark Therapeutics and REGENXBIO exemplify the platform-specialist archetype, with the former representing ophthalmic delivery expertise and the latter anchoring proprietary NAV technology partnerships. These three companies illustrate how competitive positioning splits between manufacturing integration depth and vector engineering specialization.
| Leading Market Players |
|---|
| Novartis |
| Spark Therapeutics |
| Adverum Biotechnologies |
| REGENXBIO Inc. |
| MeiraGTx Holdings plc |
| Applied Genetic Technologies Corporation |
| Biogen Inc. |
| Coave Therapeutics |
| Beacon Therapeutics |
| Others |
Value Network & Pricing Analysis
Single-source plasmid DNA dependency determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of AAV manufacturing. North American and European contract manufacturers control critical backbone inputs, compressing margins for sponsors without captive supply while enabling premium capture for integrated producers with qualified dual-source strategies.
Pricing Analysis
Post-administration monitoring and registry maintenance drive lifetime value capture across the retinal gene therapy value chain. Pricing stratifies across premium, standard, and economy tiers based on vector titer certification and companion diagnostic bundling. Cost compression in standard-tier AAV production is intensifying because sponsors are internalizing manufacturing capabilities previously outsourced to contract manufacturers. Academic medical centers with integrated surgery and pharmacy capabilities exhibit lowest price sensitivity; specialized retinal practices negotiating through group purchasing organizations face highest pressure.
Supply Chain Analysis
Extended payment terms from integrated biopharma sponsors are restructuring supplier-financing relationships with contract manufacturing organizations. AAV vector production concentrates in Massachusetts, Pennsylvania, and North Carolina facilities where sponsors have built in-house capabilities. Manufacturing draws from qualified plasmid DNA suppliers, GMP-grade cell banks, and specialized analytical testing services. Single-source vulnerability in plasmid supply creates structural risk when qualified vendors face capacity constraints. Distribution runs through specialty cold-chain logistics providers with vector-handling certifications rather than traditional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retinal gene therapy represents an early-cycle expansion story where FDA and EMA accelerated approval pathways are compressing development timelines and expanding treatable patient populations faster than historical rare disease benchmarks.
For Market Incumbents: Build manufacturing moats through backward integration into plasmid DNA production and analytical method development. Secure dual-source qualification for critical raw materials to mitigate supplier concentration risk. Expand fellowship training partnerships at academic medical centers to address vitreoretinal surgeon scarcity constraining therapy access.
For New Entrants and Emerging Players: Build out intravitreal route formulation capabilities to access patient populations excluded from subretinal surgical candidates. Target Stargardt disease indications where genetic screening penetration is accelerating in Germany and Japan. Pursue platform licensing arrangements with established AAV technology holders to bypass eighteen-to-twenty-four month capsid engineering cycles.
For Investors and Strategic Acquirers: FDA long-term follow-up guidance finalization reshapes the acquisition landscape by clarifying fifteen-year safety monitoring cost burdens and payer evidence requirements. Five-to-ten year viability hinges on durability of efficacy demonstrations in patient registries. Acquisition target archetype: platform-specialist biotechnology developers with proprietary capsid libraries and ophthalmic delivery expertise. Signal to watch: PMDA sakigake designation awards for retinitis pigmentosa programs as indicator of regulatory prioritization and reimbursement premium potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Internalizing AAV production at Massachusetts and North Carolina facilities reduces plasmid dependency and compresses batch release timelines. |
| Regulatory Approval Pathway | Regenerative medicine advanced therapy designation from FDA's Office of Therapeutic Products unlocks priority review resources and compressed BLA timelines. |
| Hospital System Partnership | Integrated delivery network contracts at academic medical centers consolidate purchasing decisions and secure preferred site-of-care status. |
| Pipeline Diversification | Stargardt disease programs expand addressable populations beyond Leber congenital amaurosis with established regulatory precedent. |
| Licensing Agreement | Proprietary NAV technology partnerships enable emerging sponsors to access validated capsid engineering without multi-year discovery investment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA BLA submissions, EMA centralized marketing authorization procedures, ClinicalTrials.gov protocols, and formulary database coverage decisions. Primary interviews engaged drug development executives at integrated biopharma sponsors, regulatory affairs leads navigating ATMP classification, hospital procurement managers at academic medical centers, and payer access specialists negotiating outcomes-based arrangements. Bottom-up patient population modeling and top-down revenue triangulation across vector manufacturing capacity estimates validated market size calculations.
Forecast inputs span therapy area penetration rates, administration route adoption curves, and regional reimbursement framework evolution across the projection horizon. Segmentation dimensions modeled include vector platform type, inherited retinal disease indication, delivery mode, and end-user site-of-care category. CAGRs were derived from slope analysis of historical approval trajectories and forward projection of pipeline asset conversion probabilities. Industry-specific inputs incorporate vitreoretinal surgeon training pipeline expansion and capsid engineering cycle compression from in silico design platforms.
Stress conditions across plasmid supply disruption, fifteen-year follow-up cost inflation, and intravitreal route technical failure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway standardization and payer evidence requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market