
 Drug Delivery in Cancer Market | 2026-2036
Drug Delivery in Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Delivery in Cancer Market Analysis
A capital-intensity divergence between large-cap biopharmaceutical incumbents and emerging nanotechnology specialists is unwinding legacy competitive boundaries. Pfizer Inc. leverages its manufacturing scale to secure liposomal drug supply chains across North American hospital networks. Novartis AG anchors its position through controlled-release oncology platforms that integrate with existing infusion infrastructure. Amgen Inc. differentiates via targeted delivery biologics that command premium formulary placement.
Drug delivery in cancer encompasses engineered carrier systems—liposomes, polymeric nanoparticles, and microneedle arrays—designed to transport cytotoxic or biologic agents to tumor tissue while minimizing systemic exposure, typically achieving payload concentrations tenfold higher at target sites than conventional intravenous administration. Liposomal drugs and nanoparticles dominate current revenue pools as clinically validated platforms with established reimbursement codes, while RNA interference technologies represent the fastest-expanding segment as siRNA and mRNA constructs advance through late-stage oncology trials. Hospitals remain the primary end-user channel, though homecare settings are gaining structural traction as subcutaneous and wearable delivery formats reduce infusion center dependency.
FDA, EMA, and the EU AI Act collectively shape market access through divergent evidentiary requirements for novel delivery mechanisms, with FDA breakthrough therapy designation accelerating review timelines and EMA's MDR framework imposing stricter biocompatibility testing on implantable drug-eluting devices. Stakeholders must monitor how evolving pharmacovigilance obligations for nanomaterial-based therapies will reshape post-market surveillance costs and liability structures.
Market Dynamics
FDA breakthrough therapy designation is compressing clinical timelines for nanoparticle-based oncology platforms while tertiary cancer centers in the United States consolidate protocol standardization, creating asymmetric access patterns between integrated health networks and independent infusion sites.
Growth Catalysts
- Accelerated Regulatory Pathways:FDA breakthrough therapy designation reduces review timelines for novel delivery mechanisms. EMA's PRIME eligibility extends similar compressions across European member states.
- Infusion Infrastructure Expansion:Oncology clinics in the United States are retrofitting facilities for liposomal drug administration. Hospital networks prioritize controlled-release platforms that integrate with existing chemotherapy suites.
- Payload Concentration Advantages:Nanoparticle engineering achieves tenfold higher tumor-site drug accumulation versus conventional intravenous delivery. This pharmacokinetic edge drives formulary placement at tertiary cancer centers.
Market Restraints
- Biocompatibility Testing Burden:EMA's MDR framework imposes extended validation timelines for implantable drug-eluting devices. European market entry costs escalate accordingly.
- Specialized Manufacturing Concentration:Liposomal drug production clusters among a limited set of contract manufacturing organizations. Supply vulnerability intensifies during capacity constraints.
- RNA Stability Limitations:siRNA and mRNA constructs require cold-chain infrastructure beyond standard oncology distribution. Thermal degradation risk constrains geographic reach.
Strategic Opportunities
- Homecare Channel Development:Subcutaneous and wearable delivery formats reduce infusion center dependency. Japan's aging population presents concentrated demand for ambulatory administration.
- EU AI Act Compliance Positioning:Predictive dosing algorithms embedded in smart delivery devices gain competitive differentiation. Early movers capture data governance advantages.
- Biologic-Device Convergence:Antibody-drug conjugates paired with microneedle arrays enable patient-administered oncology therapy. This convergence opens chronic lymphoma management to outpatient settings.
Industry Challenges
- Nanotoxicology Expertise Scarcity:Pharmacovigilance teams lack specialized training for nanomaterial long-term effects. Post-market surveillance obligations strain regulatory affairs departments.
- Legacy Infusion System Integration:Smart pump interoperability with novel delivery formats requires proprietary software development. Hospital IT procurement cycles delay adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Delivery in Cancer Market |
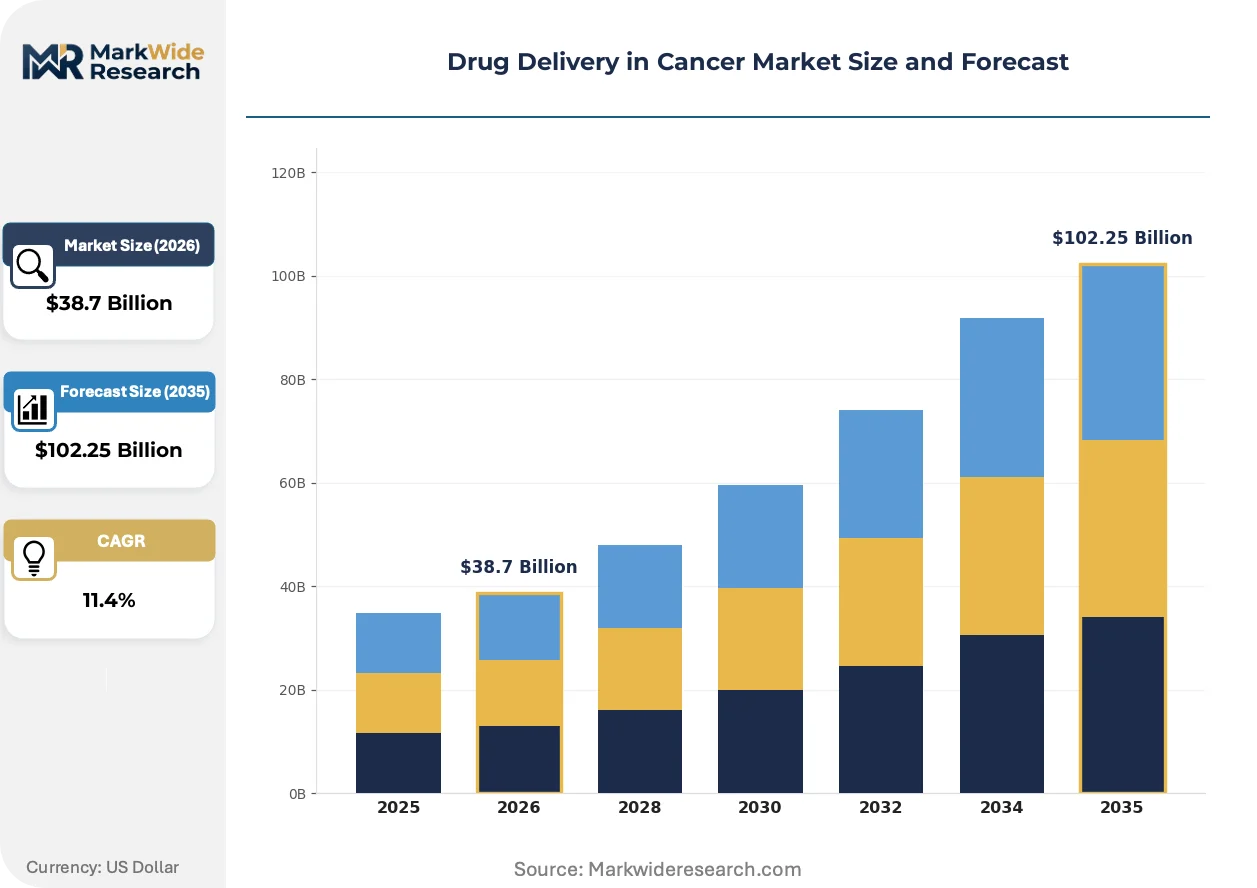
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomal Drugs, Nanoparticles, Microneedles, Injectable Solutions Technology: Targeted Delivery, Controlled Release, Gene Therapy, RNA Interference Therapy Area: Breast Cancer, Lung Cancer, Leukemia, Colorectal Cancer End User: Hospitals, Research Institutes, Clinics, Homecare Settings |
| Companies Covered | Amgen Inc., Teva Pharmaceutical Industries Ltd., Sanofi, Merck KGaA, Johnson & Johnson Services, Inc., Pfizer Inc., Novartis AG, AstraZeneca, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Delivery in Cancer Market Emerging Trajectories
RNA interference technologies are advancing through late-stage oncology trials, compressing development paradigms while microneedle arrays and wearable infusion systems reconfigure where cancer therapy is administered.
Microneedle-based transdermal delivery is displacing conventional subcutaneous injection for biologic oncology agents. Outpatient oncology centers in Germany and the United States are piloting patient-administered formats that reduce nursing labor intensity. This shift compresses reimbursement structures toward pharmacy benefit models and away from procedure-based hospital billing.
EMA's MDR framework now mandates extended biocompatibility testing for implantable drug-eluting devices. European manufacturers face elongated validation timelines before CE marking. Implantable oncology platforms targeting hormone-sensitive tumors experience the most pronounced regulatory friction, with several programs redirecting toward United States-first approval strategies.
Hospital procurement committees now prioritize delivery platforms with established J-code reimbursement over novel mechanisms requiring prior authorization. This preference consolidation disadvantages early-stage nanotechnology developers lacking claims history. The behavioral shift is most visible in United States integrated delivery networks, where formulary placement decisions increasingly centralize at the health-system level rather than individual physician discretion.
Drug Delivery in Cancer Market Segmentation
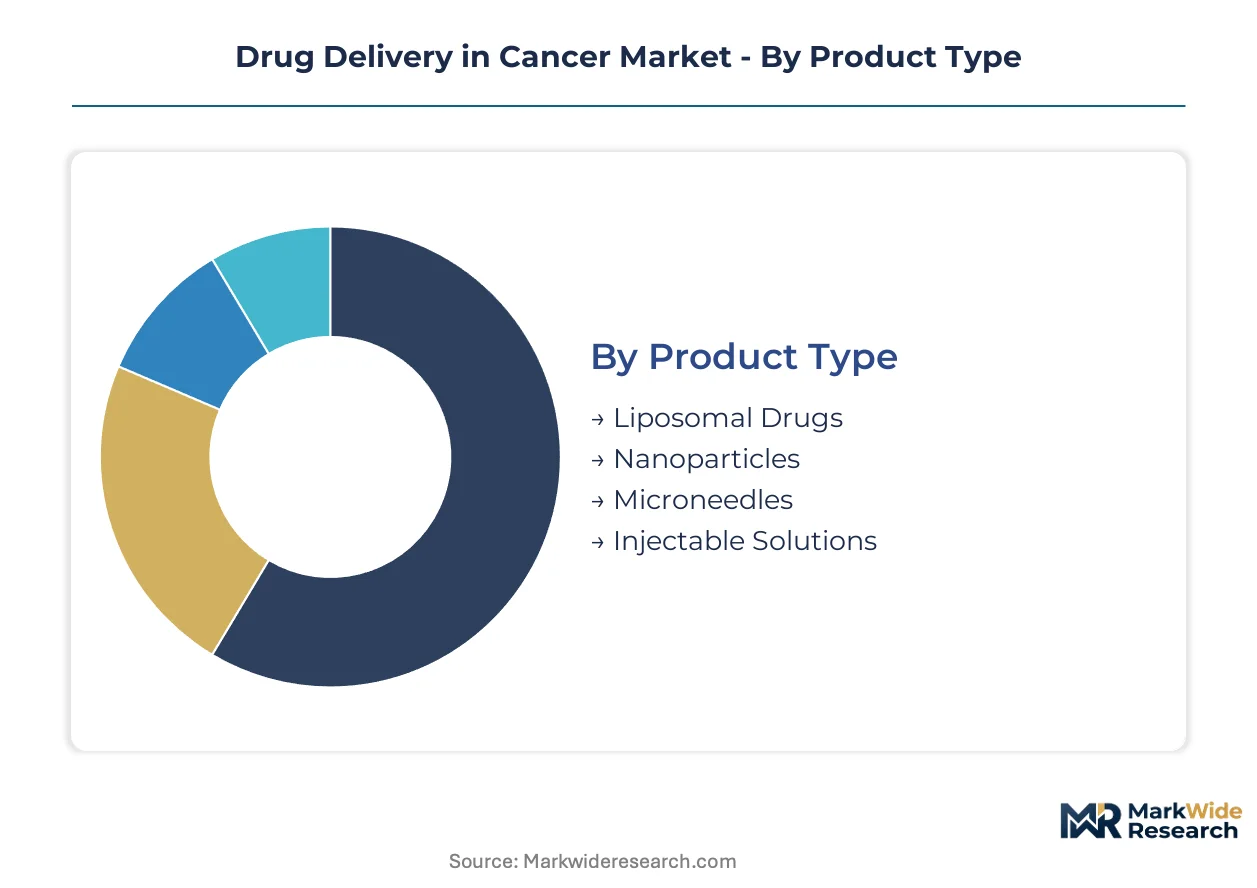
Segmentation in cancer drug delivery reveals how formulation technology, clinical application, and care setting intersect to determine reimbursement pathways and manufacturing scale. Each dimension carries distinct regulatory requirements and infrastructure dependencies that shape competitive positioning.
Product Type:
Domestic production clusters in the United States and Germany for liposomal and nanoparticle platforms, while microneedle arrays draw more heavily from East Asian contract manufacturing.
- Liposomal Drugs:Phospholipid bilayer vesicles encapsulate cytotoxic agents to reduce systemic toxicity. United States tertiary cancer centers drive demand through established J-code reimbursement and infusion infrastructure.
- Nanoparticles:Polymeric or lipid-based carriers below 100nm enable passive tumor targeting via enhanced permeability. Research institutes in Boston and Basel anchor early-phase adoption for novel payloads.
- Microneedles:Dissolvable or hydrogel arrays penetrate stratum corneum for transdermal biologic delivery. Japanese manufacturers lead pilot programs for patient-administered oncology applications.
- Injectable Solutions:Conventional parenteral formulations remain volume leaders in emerging markets lacking cold-chain infrastructure for advanced carriers.
Liposomal drugs hold the largest share; momentum sits with nanoparticles.
Technology:
Cost tier separation is pronounced: targeted delivery and controlled release command premium pricing, while RNA interference platforms absorb heavy R&D amortization.
- Targeted Delivery:Ligand-conjugated carriers direct payloads to tumor-specific antigens. Antibody-drug conjugates from Amgen and Roche dominate formulary placement at United States academic medical centers.
- RNA Interference:siRNA and mRNA constructs silence oncogenes or express tumor antigens. Cold-chain requirements and stability challenges constrain distribution beyond major metropolitan hospital networks.
- Controlled Release:Polymeric matrices or osmotic pumps sustain therapeutic concentrations over weeks. Implantable formulations face extended EMA biocompatibility testing under MDR requirements.
- Gene Therapy:Viral and non-viral vectors deliver genetic material to modify tumor biology. Manufacturing complexity limits production to specialized facilities in North Carolina and Belgium.
Targeted delivery commands the revenue base; RNA interference is climbing fastest.
Therapy Area:
Application intensity varies by tumor biology: solid tumors favor nanoparticle accumulation, while hematologic malignancies enable simpler vascular access for infusion.
- Breast Cancer:Liposomal doxorubicin and nanoparticle albumin-bound paclitaxel anchor adjuvant and metastatic protocols. United States oncology clinics prioritize these formulations for reduced cardiotoxicity profiles.
- Lung Cancer:Inhalable and intratumoral delivery platforms target primary and metastatic lesions. German university hospitals pilot microneedle patches for EGFR inhibitor administration.
- Leukemia:Intrathecal and targeted liposomal therapies address blood-brain barrier penetration challenges. Pediatric protocols at St. Jude Children's Research Hospital drive specialized formulation demand.
- Colorectal Cancer:Controlled-release implants and hepatic arterial infusion dominate regional therapy approaches. Japanese aging demographics expand homecare eligibility for maintenance regimens.
Breast cancer holds the largest share; momentum sits with lung cancer applications.
End User:
Customer type determines procurement authority: hospital networks centralize formulary decisions, while homecare shifts reimbursement toward pharmacy benefit managers.
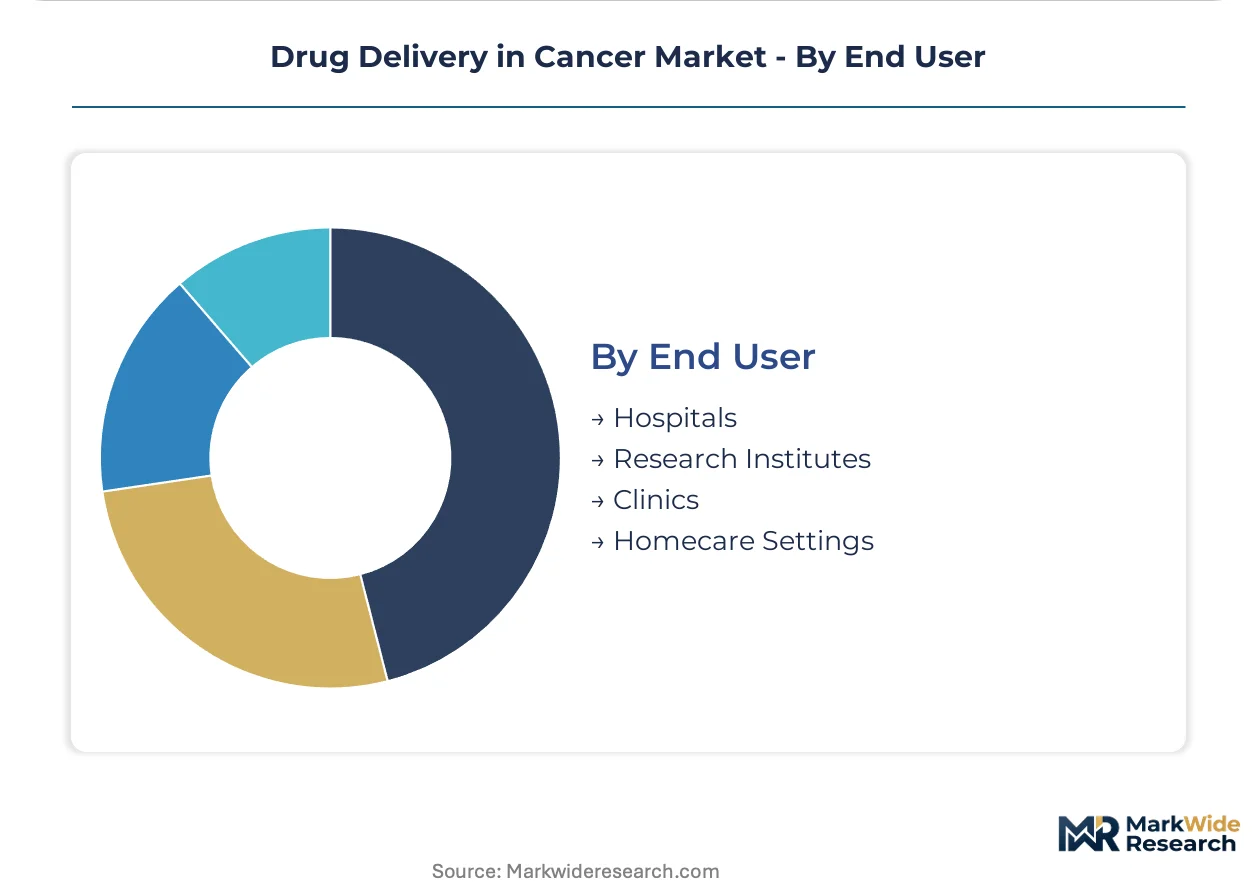
- Hospitals:Integrated delivery networks in the United States consolidate purchasing for liposomal and nanoparticle therapies. Infusion center capacity constraints limit throughput growth.
- Homecare Settings:Subcutaneous and wearable formats reduce nursing labor intensity. Japan's Ministry of Health expands reimbursement for ambulatory oncology administration.
- Clinics:Independent oncology practices depend on group purchasing organizations for novel delivery platform access. Prior authorization requirements delay patient starts.
- Research Institutes:Academic medical centers in Boston, Basel, and Singapore anchor first-in-human trials for RNA interference and gene therapy platforms.
Hospitals hold the largest share; homecare settings are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States tertiary centers concentrate on nanoparticle infusion protocols, while Japan prioritizes homecare-compatible formats for its aging demographic, and European markets navigate stricter biocompatibility testing regimes.
United States
Integrated delivery networks at MD Anderson, Memorial Sloan Kettering, and Mayo Clinic anchor demand for liposomal doxorubicin and nanoparticle albumin-bound paclitaxel. FDA breakthrough therapy designation compresses review timelines for novel delivery mechanisms, accelerating market entry for RNA interference platforms. Boston's Longwood Medical Area and Research Triangle Park in North Carolina cluster contract manufacturing for viral vectors and lipid nanoparticles.
Germany
University hospitals in Heidelberg and Munich pilot microneedle patches for EGFR inhibitor administration in lung cancer protocols. EMA's MDR framework imposes extended biocompatibility validation on implantable drug-eluting devices, elongating CE marking timelines. The Rhine-Main biotech corridor concentrates formulation development for controlled-release polymeric matrices serving hormone-sensitive tumor applications.
Japan
Ministry of Health reimbursement expansion for ambulatory oncology administration drives demand for subcutaneous and wearable delivery formats. PMDA reviews prioritize quality-by-design documentation for nanomaterial manufacturing processes. The Kansai region around Osaka anchors pilot production of dissolvable microneedle arrays for patient-administered biologic therapy.
China
NMPA's priority review pathway for innovative oncology delivery systems accelerates domestic liposomal drug approvals. Provincial hospital procurement in Jiangsu and Zhejiang provinces concentrates volume for nanoparticle-based taxane formulations. The Suzhou BioBAY industrial park clusters contract development and manufacturing organizations serving both domestic and export markets.
Switzerland
Basel's pharmaceutical corridor anchors early-phase adoption for targeted delivery biologics and antibody-drug conjugates. Swissmedic maintains alignment with EMA standards while offering streamlined review for products with prior FDA or EMA authorization. The Lake Geneva region concentrates specialized manufacturing for polymeric nanoparticles requiring aseptic processing capabilities.
Drug Delivery in Cancer Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with large-cap biopharmaceutical incumbents leveraging manufacturing scale against emerging nanotechnology developers focused on payload engineering. The market structure rewards backward integration into lipid supply chains and captive production of specialized excipients. Three archetypes dominate: diversified pharmaceutical conglomerates with infusion infrastructure partnerships, pure-play nanotechnology developers advancing RNA platforms, and contract manufacturing organizations capturing value from capacity constraints. Competitive intensity centers on formulary placement at tertiary cancer centers and strategic partnerships with hospital purchasing networks.
Among the diversified pharmaceutical tier, Pfizer Inc., Novartis AG, and Amgen Inc. exemplify contrasting strategic positions. Pfizer occupies a scale-driven position anchored in North American hospital network supply agreements. Novartis represents the controlled-release platform archetype with integration into existing chemotherapy infusion infrastructure. Amgen sits within the targeted delivery biologics segment, commanding premium formulary placement through antibody-drug conjugate specialization. These three entities collectively illustrate how manufacturing scale, regulatory navigation capability, and clinical evidence generation differentiate competitive positioning in nanoparticle-based oncology therapy.
| Leading Market Players |
|---|
| Amgen Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Merck KGaA |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Novartis AG |
| AstraZeneca |
| Bristol-Myers Squibb Company |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough therapy designation and EMA's MDR framework gate both supply qualification and price differentiation, as manufacturers must absorb extended validation costs to access premium reimbursement tiers at United States tertiary cancer centers while European implantable platforms face elongated CE marking timelines that compress margin structures.
Pricing Analysis
Long-term offtake agreements dominate liposomal drug procurement between North American hospital networks and contract manufacturing organizations, while spot purchasing persists for novel RNA interference platforms lacking established J-code reimbursement. Price differentiation rests on FDA approval tier and cold-chain infrastructure requirements, with premium formulary placement commanding significant brand premiums over biosimilar entrants. Cost compression in the standard tier intensifies as group purchasing organizations consolidate oncology clinic buying power. Independent infusion sites exhibit highest price sensitivity; integrated delivery networks at academic medical centers demonstrate lowest sensitivity due to bundled reimbursement structures.
Supply Chain Analysis
Specialized phospholipid supply from Germany and Belgium anchors liposomal drug production, while East Asian contract manufacturers concentrate microneedle array fabrication for transdermal oncology applications. Raw material dependencies include medical-grade phospholipids, polymeric excipients, and lipid nanoparticle formulations requiring aseptic processing capabilities. Single-source vulnerability concentrates in viral vector manufacturing facilities located in North Carolina and Belgium. Distribution feeds from captive production sites through hospital procurement committees and group purchasing organizations, with cold-chain logistics constraining geographic reach for RNA-based therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware in this market, as infusion infrastructure partnerships and patient monitoring subscriptions for wearable delivery formats outpace growth in standalone drug-device sales.
For Market Incumbents: Fortify backward integration into lipid supply chains and captive excipient production to defend against emerging nanotechnology specialists capturing RNA platform share. Prioritize certification investment for EU AI Act compliance on predictive dosing algorithms embedded in smart delivery devices, as regulatory navigation capability separates integrated leaders from specialist tier competitors facing formulary exclusion. For New Entrants and Emerging Players: Lead with patient-administered microneedle formats for Japan's expanding homecare reimbursement eligibility, the most penetrable geography for ambulatory oncology administration. Target white-space in subcutaneous biologic delivery for chronic lymphoma management, where nursing labor intensity reduction drives procurement committee interest. Pursue strategic partnerships with hospital purchasing networks rather than direct formulary challenges against established liposomal incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across RNA interference manufacturing as specialized aseptic processing capabilities and cold-chain infrastructure requirements escalate facility construction costs. Long-term viability favors acquisition targets with demonstrated regulatory approval in multiple jurisdictions and existing J-code reimbursement history. Monitor PMDA quality-by-design documentation precedents as the signal indicating which nanomaterial manufacturing processes will achieve streamlined market access.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for nanoparticle platforms entering late-stage oncology trials. |
| Manufacturing Scale-Up | Captive lipid nanoparticle production at Boston and Research Triangle Park facilities reduces supply vulnerability during capacity constraints. |
| Hospital System Partnership | Integrated delivery network agreements at MD Anderson and Memorial Sloan Kettering anchor formulary placement for novel delivery mechanisms. |
| Reimbursement Strategy | J-code establishment prior to launch determines procurement committee prioritization over prior authorization-dependent alternatives. |
| Software Companion Development | EU AI Act-compliant predictive dosing algorithms embedded in smart pumps differentiate controlled-release platforms at European university hospitals. |
Methodological Framework
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary fieldwork captured manufacturing scale constraints, reimbursement negotiation dynamics, and adoption timelines for novel delivery formats. Secondary validation drew from SEC 10-K disclosures, CMS Medicare data, and GPO contract databases. Bottom-up patient-flow modeling and top-down market sizing triangulated volume estimates across the analysis window.
Variance-decomposition across technology segments, therapy areas, and end-user channels informed the analytical framework, with administration route and regional regulatory cluster as additional modeled dimensions. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated infusion center capacity expansion plans, cold-chain infrastructure buildout, and evolving pharmacovigilance obligations for nanomaterial-based therapies.
Forecasts assume regulatory continuity in FDA breakthrough therapy pathways and EMA MDR implementation timelines; material policy shifts would require re-modeling. Specific risks include nanotoxicology expertise scarcity straining post-market surveillance capacity, and RNA stability limitations constraining distribution reach. Practitioners should keep alternative scenarios live as EU AI Act enforcement precedents and PMDA quality-by-design documentation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market