
 Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market | 2026-2036
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market Insights
The gap between manual cryopreservation workflows and automated closed-system manufacturing is narrowing as cell therapy developers scale toward commercial production. Thermo Fisher Scientific leverages its end-to-end bioproduction portfolio to anchor automated thaw performance testing across North American and European manufacturing sites. Cytiva competes through its specialized cryochain solutions that integrate temperature monitoring with process analytical technology. Sartorius differentiates via microfluidic platform investments that reduce sample volume requirements during viability assessment.
Cell Therapy Cryopreservation and Thaw Performance Test Platforms comprise instrument systems, consumable kits, and integrated software that measure post-thaw cell viability, recovery rate, and functional potency following controlled-rate freezing and warming protocols. These platforms typically operate within a temperature range of -196°C to 37°C, utilizing programmed thermal profiles and real-time analytics to ensure critical quality attributes meet release specifications for clinical cell products. Automated Systems dominate current procurement among commercial-stage biopharmaceutical developers seeking to minimize operator-dependent variability. CAR-T Cell Manufacturing represents the fastest-growing application segment as autologous therapy programs expand into multi-site production networks. Flow Cytometry technology leads analytical verification due to its established regulatory acceptance for identity and potency assays.
FDA cell therapy guidance and EMA ATMP frameworks mandate validated cryopreservation processes with documented thaw performance, directly elevating demand for standardized test platforms. ISO 20387 biobanking standards and USP <1046> cell and gene therapy product guidelines further constrain acceptable viability thresholds, forcing platform vendors to demonstrate measurement traceability. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA regarding post-thaw potency assay requirements, as divergence in acceptance criteria would fragment platform specifications and complicate multi-jurisdictional manufacturing strategies.
Market Dynamics
Automated closed-system manufacturing is compressing the gap between manual cryopreservation workflows and commercial-scale cell therapy production, forcing platform vendors to integrate process analytical technology with real-time thermal profiling.
Growth Catalysts
- FDA Cell Therapy Guidance:Mandated validated cryopreservation processes with documented thaw performance elevate demand for standardized test platforms across United States biopharmaceutical manufacturing sites.
- CAR-T Cell Manufacturing:Expansion of autologous therapy programs into multi-site production networks accelerates procurement of automated systems that minimize operator-dependent variability.
- ISO 20387 Biobanking Standards:Constrained acceptable viability thresholds force platform vendors to demonstrate measurement traceability, tightening quality specifications for clinical cell product release.
Market Restraints
- Liquid Nitrogen Supply Concentration:Regional supply bottlenecks for cryogenic cooling agents create operational vulnerability for manufacturing sites dependent on consistent ultra-low temperature maintenance.
- Flow Cytometry Equipment Cost Structure:High capital expenditure requirements for analytical verification systems limit adoption among early-stage cell therapy developers with constrained funding profiles.
- EMA-FDA Harmonization Friction:Divergence in post-thaw potency assay acceptance criteria between regulatory jurisdictions fragments platform specifications and complicates multi-jurisdictional manufacturing strategies.
Strategic Opportunities
- Microfluidic Platform Convergence:Integration of microfluidic technologies with viability assessment protocols reduces sample volume requirements, opening addressable market segments with limited cell material availability.
- Software-Defined Thermal Profiling:Cloud-based analytics platforms enable remote monitoring and predictive maintenance, creating subscription revenue streams beyond instrument hardware sales.
- Allogeneic Therapy Manufacturing:Emerging demand from off-the-shelf cell therapy programs requires scalable cryopreservation validation at batch volumes exceeding autologous production scales.
Industry Challenges
- GMP Compliance Talent Scarcity:Shortage of personnel qualified in current good manufacturing practice for cell and gene therapy products delays facility qualification and platform validation timelines.
- Legacy System Integration Complexity:Manufacturing execution system interoperability with existing bioproduction infrastructure requires customized software bridging, extending deployment cycles and elevating implementation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market |
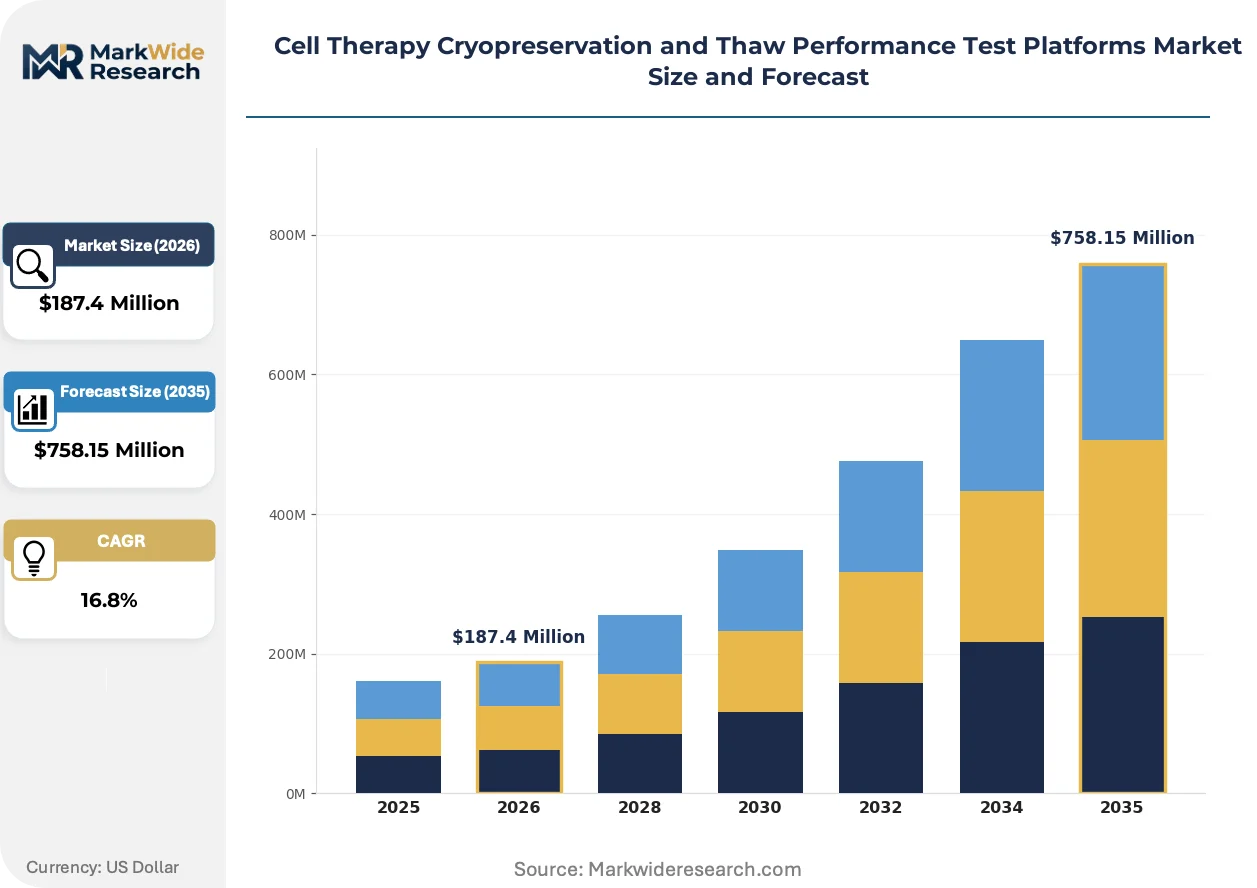
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Kits, Semi-Automated Devices, Cryogenic Vials, Temperature Monitors Application: Stem Cell Processing, CAR-T Cell Manufacturing, Gene Therapy Validation, Immunotherapy Analysis, Cell Line Development Technology: Flow Cytometry, Microscopy Imaging, Digital PCR, Microfluidic Platforms, Spectroscopy End User: Biopharmaceutical Developers, Contract Manufacturing Organizations, Research Institutions, Clinical Development Labs, Quality Control Units |
| Companies Covered | Thermo Fisher Scientific, BioLife Solutions, Cytiva, Sartorius, Merck KGaA, GE HealthCare, Beckman Coulter Life Sciences, ChemoMetec, PHC Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market Trends and Innovations
Process analytical technology is embedding real-time quality verification directly into cryopreservation workflows, collapsing the latency between manufacturing execution and release decision-making. Platform vendors now compete on data architecture rather than thermal hardware alone.
Closed-system automated thawing instrumentation is digitizing the transition from manual water bath protocols to controlled-rate warming devices with integrated viability feedback loops. Commercial-stage biopharmaceutical developers in the United States and Germany are standardizing on these platforms for multi-site CAR-T production networks. The technology is digitizing compliance documentation, compressing batch release timelines from days to hours.
EMA ATMP frameworks and FDA cell therapy guidance are converging on potency assay requirements for post-thaw functional verification, though residual divergence in acceptance criteria persists. This regulatory alignment pressure forces platform vendors to design instruments capable of supporting multiple jurisdictional validation protocols simultaneously. Contract development and manufacturing organizations across Switzerland and the Netherlands are investing in dual-compliant systems to serve transatlantic sponsor portfolios.
Service unbundling is separating instrument hardware procurement from validation and ongoing analytical support, enabling smaller developers to access enterprise-grade platforms through operating expenditure models rather than capital purchase. Contract research organizations in Massachusetts and California are capturing this demand through managed service offerings that include platform access, qualified operator staffing, and regulatory documentation support. The shift is most visible among Series B-funded cell therapy companies prioritizing cash runway preservation over asset ownership.
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market Segmentation
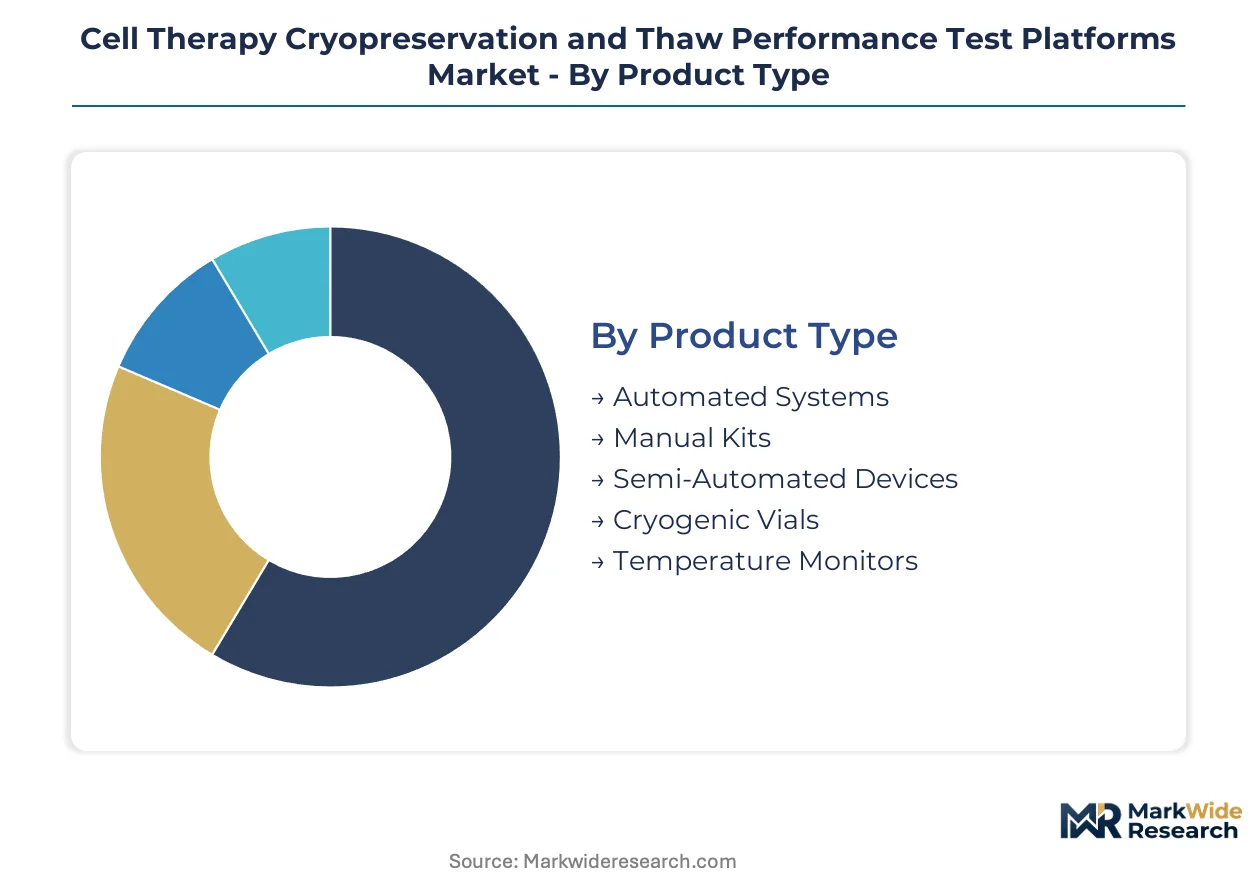
Segmentation in cryopreservation test platforms reveals divergent service intensity profiles across product tiers. Automated systems demand continuous calibration support and software maintenance contracts, while manual kits require minimal post-sale engagement beyond consumable replenishment.
Product Type:
After-sales-service intensity varies dramatically across product tiers, with automated platforms generating recurring revenue streams through validation support and predictive maintenance programs.
- Automated Systems:Closed-system architectures integrate controlled-rate freezing with real-time thermal profiling and process analytical technology. CAR-T cell manufacturing sites in the United States biopharmaceutical corridor prioritize these platforms to minimize operator-dependent variability and accelerate batch release timelines.
- Manual Kits:Basic consumable packages require minimal capital investment and suit early-stage developers with constrained funding profiles. Research institutions and academic laboratories represent the primary procurement base, though scaling manufacturers rapidly outgrow these workflows.
- Semi-Automated Devices:Bridge solutions offering partial automation with retained operator intervention points.
- Cryogenic Vials:Standardized storage containers with validated thermal performance specifications.
- Temperature Monitors:Data logging instruments for cryochain integrity verification during transport and storage.
Automated Systems hold the largest share; momentum sits with Semi-Automated Devices as mid-stage developers transition from manual workflows.
Application:
Application segmentation maps directly to regulatory complexity tiers, with commercial cell therapy manufacturing demanding the most intensive validation documentation and ongoing compliance support.
- CAR-T Cell Manufacturing:Autologous therapy production requires patient-specific cryopreservation validation with documented post-thaw viability and potency metrics. Multi-site production networks across Germany and Switzerland are standardizing on automated test platforms to ensure consistent release specifications.
- Stem Cell Processing:Allogeneic and autologous stem cell therapies impose stringent viability thresholds under ISO 20387 biobanking standards. Contract manufacturing organizations in the Netherlands are investing in dual-compliant systems to serve transatlantic sponsor portfolios.
- Gene Therapy Validation:Viral vector and plasmid cryopreservation testing with specialized thermal profiles.
- Immunotherapy Analysis:Tumor-infiltrating lymphocyte and NK cell thaw performance verification.
- Cell Line Development:Master cell bank characterization and stability testing protocols.
CAR-T Cell Manufacturing commands the dominant position; Gene Therapy Validation is climbing the fastest as viral vector programs advance toward commercial scale.
Technology:
Technology selection determines capital intensity and regulatory acceptance, with established analytical methods commanding premium pricing against emerging microfluidic alternatives.
- Flow Cytometry:Multi-parameter cell analysis with established FDA and EMA regulatory acceptance for identity and potency assays. Commercial-stage biopharmaceutical developers standardize on these systems despite high capital expenditure requirements.
- Microfluidic Platforms:Miniaturized viability assessment reducing sample volume requirements during precious cell material testing. Series B-funded companies in Massachusetts are accessing these platforms through managed service offerings to preserve cash runway.
- Microscopy Imaging:Morphological assessment and confluence measurement for adherent cell types.
- Digital PCR:Nucleic acid-based quantification for vector copy number and residual DNA detection.
- Spectroscopy:Non-invasive metabolic activity monitoring through NADH fluorescence or Raman signatures.
Flow Cytometry retains the installed base leadership; Microfluidic Platforms are gaining share fastest among developers with limited cell material availability.
End User:
End user segmentation reflects divergent procurement authority and validation burden, with commercial manufacturers internalizing compliance while outsourced partners absorb regulatory documentation complexity.
- Biopharmaceutical Developers:Integrated manufacturing organizations building captive cryopreservation validation capabilities. Thermo Fisher Scientific and Cytiva compete directly for multi-year platform procurement contracts at these accounts.
- Contract Manufacturing Organizations:CDMOs across Switzerland and California are capturing demand through service unbundling—offering platform access, qualified operator staffing, and regulatory documentation support without capital purchase requirements.
- Research Institutions:Academic laboratories with constrained budgets prioritizing manual kit workflows.
- Clinical Development Labs:Phase-appropriate testing facilities supporting investigator-sponsored trials.
- Quality Control Units:Embedded analytical groups within larger manufacturing organizations.
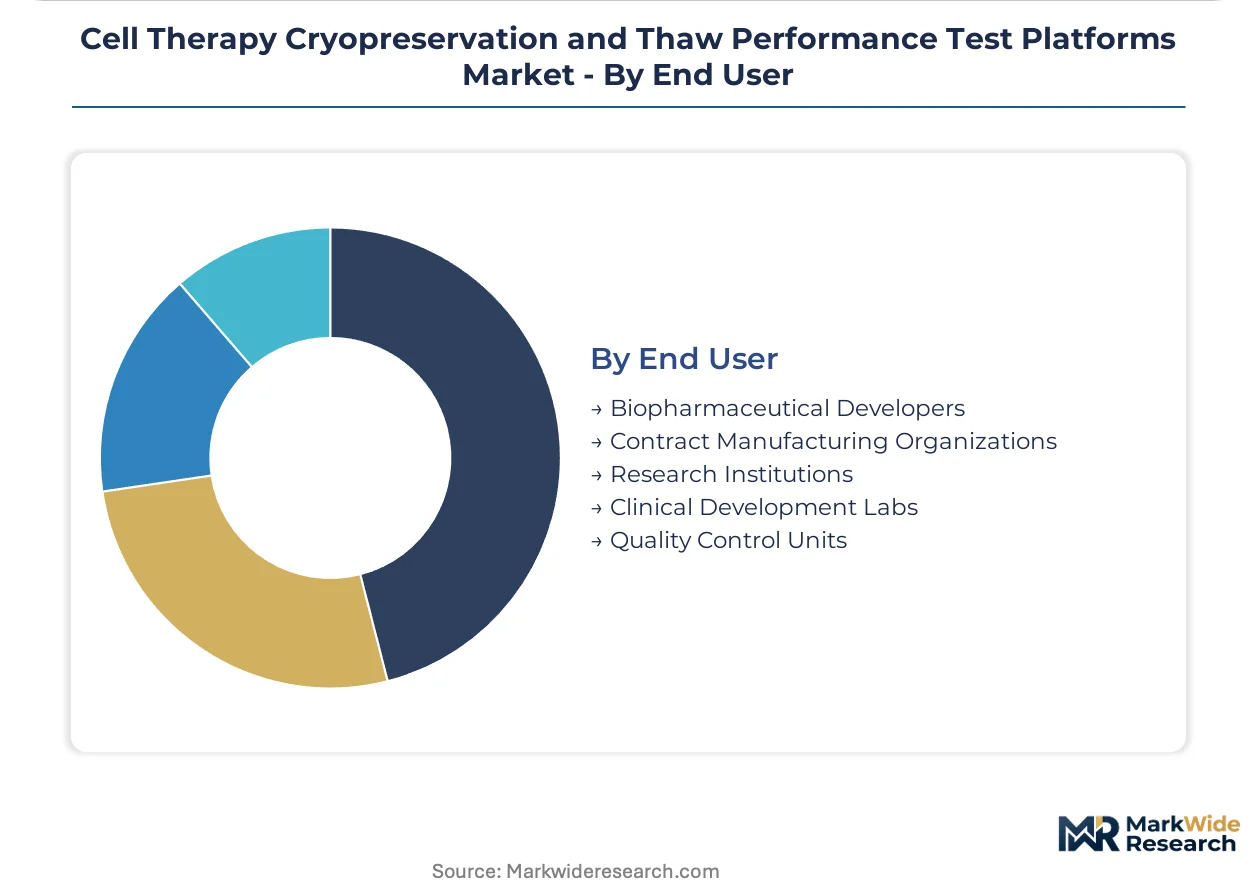
Biopharmaceutical Developers represent the largest addressable spend; Contract Manufacturing Organizations are expanding most quickly as outsourcing trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision thermal instrumentation to United States biopharmaceutical manufacturing corridors, establishing a transatlantic trade flow that channels European engineering into North American cell therapy production networks.
United States
FDA cell therapy guidance mandates validated cryopreservation processes with documented thaw performance, elevating procurement of automated test platforms. The Inflation Reduction Act accelerates domestic biomanufacturing capacity investments. The Greater Boston and San Francisco Bay Area clusters host multi-site CAR-T production networks standardizing on closed-system architectures.
Germany
EMA ATMP frameworks impose stringent post-thaw potency verification requirements for commercial cell product release. The country's national pharmaceutical regulator enforces ISO 20387 biobanking standards across manufacturing sites. The Rhine-Main and Munich biotech corridors concentrate CDMO investments in dual-compliant systems serving transatlantic sponsor portfolios.
Switzerland
Swissmedic oversight of advanced therapy medicinal products drives demand for measurement traceability in cryopreservation validation. Federal incentives for precision medicine manufacturing anchor platform vendor competition. The Basel and Zurich regions host contract development organizations capturing demand through service unbundling models.
Netherlands
Leiden and Amsterdam bioclusters expand allogeneic therapy manufacturing requiring scalable cryopreservation validation at batch volumes exceeding autologous scales. The country's national pharmaceutical regulator aligns with EMA frameworks while maintaining distinct documentation requirements. Rotterdam logistics hubs integrate temperature monitoring with cryochain integrity verification for European distribution.
United Kingdom
Medicines and Healthcare products Regulatory Agency cell and gene therapy guidance shapes post-Brexit validation protocols for domestic manufacturing. The Golden Triangle cluster between London, Oxford, and Cambridge concentrates early-stage developer demand for microfluidic platform access through managed service offerings. MHRA divergence from EMA acceptance criteria complicates multi-jurisdictional platform specifications.
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market Competitive Landscape
On the supply side, the industry is consolidating around integrated bioproduction portfolios that bundle thermal hardware with process analytical technology and regulatory documentation support. Three strategic archetypes dominate: diversified life science conglomerates with end-to-end platform ecosystems, specialized cryochain solution providers with temperature monitoring integration, and precision instrumentation specialists with microfluidic miniaturization capabilities. Competitive moves center on strategic partnerships with contract manufacturing organizations and technology licensing agreements that embed vendor platforms into multi-site production networks.
Within the diversified conglomerate tier, Thermo Fisher Scientific anchors automated thaw performance testing across North American and European manufacturing sites through its bioproduction portfolio breadth. Cytiva occupies a position among specialized cryochain solution providers, integrating temperature monitoring with process analytical technology for commercial-stage developers. Sartorius exemplifies the precision instrumentation archetype, with microfluidic platform investments reducing sample volume requirements during viability assessment for developers with constrained cell material availability.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| BioLife Solutions |
| Cytiva |
| Sartorius |
| Merck KGaA |
| GE HealthCare |
| Beckman Coulter Life Sciences |
| ChemoMetec |
| PHC Holdings |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in United States biopharmaceutical manufacturing corridors compresses pricing power for automated cryopreservation platforms while elevating buyer negotiation leverage. This utilization dynamic forces suppliers to bundle validation services and predictive maintenance contracts to defend margin structures.
Pricing Analysis
Next-generation microfluidic platforms command substantial premiums over flow cytometry systems and manual kit alternatives. Pricing stratifies across premium, standard, and economy tiers based on regulatory certification grade and after-sales service bundling intensity. Cost compression in semi-automated devices intensifies as mid-stage developers prioritize capital efficiency over full automation. Research institutions exhibit highest price sensitivity, while commercial-stage biopharmaceutical developers prioritize measurement traceability and regulatory acceptance over acquisition cost.
Supply Chain Analysis
Export control regimes restricting precision thermal instrumentation flows from Germany constrain supply elasticity for automated freezing systems. Manufacturing concentrates in Germany, the United States, and Switzerland, drawing from specialized sensor components, cryogenic-grade stainless steel, and proprietary thermal transfer fluids. Single-source vulnerability around liquid nitrogen distribution infrastructure elevates operational risk for multi-site CAR-T production networks. Distribution runs through direct vendor relationships with biopharmaceutical developers and CDMO service contracts rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. FDA and EMA validation documentation requirements create switching costs that lock in platform choices across multi-year manufacturing campaigns.
For Market Incumbents: Pre-empt emerging microfluidic specialists by acquiring precision instrumentation capabilities before next-generation platforms achieve regulatory acceptance. Anchor multi-site production networks through embedded process analytical technology that raises replacement costs. Defend against service unbundling trends by integrating cloud-based analytics platforms that generate recurring subscription revenue beyond hardware sales.
For New Entrants and Emerging Players: Pursue white-space opportunities in allogeneic therapy manufacturing where batch scale requirements exceed current platform specifications. Target Netherlands and Swiss CDMO clusters seeking dual-compliant systems for transatlantic sponsor portfolios. Establish beachheads through managed service offerings that preserve cash runway for Series B-funded developers.
For Investors and Strategic Acquirers: Capital is best deployed toward precision instrumentation specialists with microfluidic miniaturization capabilities and established regulatory documentation libraries. Long-term viability hinges on platform vendors' capacity to serve both autologous and allogeneic therapy manufacturing scales. Watch for EMA-FDA harmonization signals on post-thaw potency assay acceptance criteria as inflection indicators for platform specification consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Platform Integration | Reduces sample volume requirements for developers with constrained cell material availability. |
| Cloud-Based Analytics Development | Enables remote monitoring and predictive maintenance for multi-site CAR-T production networks. |
| Dual-Compliant System Certification | Positions CDMOs to serve transatlantic sponsor portfolios under converging FDA and EMA frameworks. |
| Allogeneic Therapy Manufacturing Scale-Up | Addresses emerging demand for batch volumes exceeding autologous production scales. |
| Service Unbundling Model Launch | Captures Series B-funded developers prioritizing operating expenditure models over capital purchase. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with cell therapy manufacturing executives, regulatory affairs specialists, CDMO operations directors, and bioprocess engineers; and secondary validation through FDA guidance documents, EMA ATMP framework publications, ISO 20387 biobanking standards, and United States biopharmaceutical facility investment disclosures. Bottom-up and top-down triangulation cross-checked platform procurement volumes against manufacturing capacity expansion announcements.
Forecast inputs considered product type segmentation across automated systems, manual kits, and semi-automated devices; application segmentation spanning CAR-T cell manufacturing, stem cell processing, and gene therapy validation; technology segmentation comparing flow cytometry, microfluidic platforms, and emerging analytical methods; and end user segmentation distinguishing biopharmaceutical developers from contract manufacturing organizations. CAGRs were derived from regression analysis of historical procurement patterns and projected manufacturing capacity buildouts across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical venture funding cycles and liquid nitrogen supply stability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and manufacturing automation adoption curves. Material shifts in FDA-EMA potency assay divergence or cryogenic cooling agent supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market