
 Adipose Derived Stem Cell Therapy Market | 2026-2036
Adipose Derived Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Adipose Derived Stem Cell Therapy Market Outlook
Bioreactor manufacturing capacity in South Korea is restructuring supply dynamics for stromal vascular fraction isolation. Cytori Therapeutics leverages proprietary Celution systems to anchor processing workflows across Japanese and European clinics. Mesoblast Ltd. competes through allogeneic off-the-shelf platforms, while Thermo Fisher Scientific controls upstream reagent and media supply chains that feed laboratory-scale expansion protocols.
Adipose derived stem cell therapy deploys mesenchymal stromal cells harvested from lipoaspirate tissue through enzymatic or mechanical dissociation, typically yielding 500,000 to 2 million nucleated cells per gram of processed fat for immunomodulation and tissue repair applications. Autologous preparations dominate current clinical volume due to lower immunogenicity risk, though cryopreserved allogeneic formats are gaining traction in orthopedic and cardiology applications where point-of-care processing proves impractical. Delivery mode selection bifurcates sharply: intra-articular injection captures margin pools in osteoarthritis protocols, while surgical implantation commands premium positioning in complex soft-tissue reconstruction.
The FDA regulates adipose-derived cell products under 21 CFR 1271 human cells and tissues criteria, with enforcement discretion narrowing for minimally manipulated applications, while the EMA's CAT committee imposes centralized ATMP assessments that delay European market entry. Japan's PMDA operates under the Act on Regenerative Medicine Safety, creating a conditional approval pathway that accelerates commercialization for qualified cell therapy facilities. Stakeholders must monitor evolving jurisdictional definitions of minimal manipulation, as regulatory reclassification would abruptly reshape permissible clinic-laboratory business models and capital deployment priorities.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation compresses clinical trial timelines for cell-based treatments, while bioreactor manufacturing capacity in South Korea restructures supply dynamics for stromal vascular fraction isolation. Orthopedic clinics in the United States are expanding sports medicine protocols, creating concentrated demand pull for point-of-care processing systems.
Growth Catalysts
- Regulatory Acceleration:The FDA's regenerative medicine advanced therapy designation fast-tracks approval pathways for qualified cell therapy facilities, reducing commercialization timelines.
- Orthopedic Demand Concentration:Sports medicine protocols at United States orthopedic clinics drive procedural volume expansion for autologous intra-articular injections.
- Enzymatic Dissociation:Advanced enzymatic processing methods yield 500,000 to 2 million nucleated cells per gram of lipoaspirate tissue, improving therapeutic potency consistency.
Market Restraints
- Supply Concentration Risk:Bioreactor manufacturing clusters in South Korea create geographic vulnerability for stromal vascular fraction isolation equipment.
- Regulatory Friction:The EMA's CAT committee imposes centralized ATMP assessments that delay European market entry for minimally manipulated products.
- Technical Limitation:Cryopreservation protocols for allogeneic formats introduce cell viability degradation that constrains shelf-life extension.
Strategic Opportunities
- Japan Infrastructure:METI funding supports adipose-derived cell banking infrastructure, creating captive supply networks for qualified therapy facilities.
- Cardiology Applications:Allogeneic formats gain traction in cardiology where point-of-care processing proves impractical for acute intervention timelines.
- Technology Convergence:Integration of automated Celution processing systems with surgical implantation workflows compresses operating room turnaround times.
Industry Challenges
- Talent Scarcity:Shortage of trained cell processing technicians constrains laboratory-scale expansion protocol throughput at clinic-laboratory facilities.
- Capex Intensity:Bioreactor manufacturing equipment and cleanroom infrastructure require substantial capital deployment that limits mid-tier facility entry.
- Standardization Delays:Absence of harmonized potency assays across jurisdictions creates batch release variability for cryopreserved allogeneic products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adipose Derived Stem Cell Therapy Market |
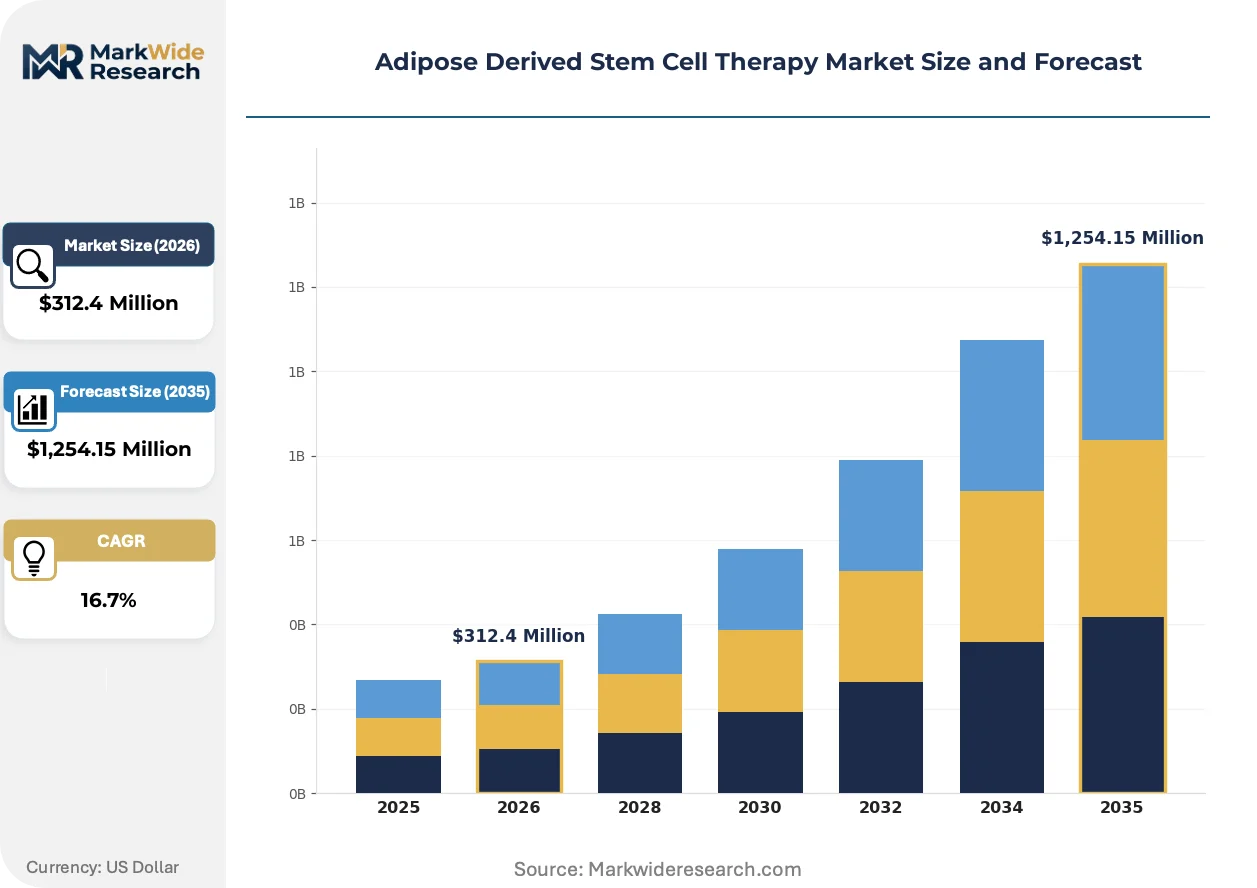
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,254.15 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allogeneic, Autologous, Cryopreserved, Fresh Application: Orthopedics, Cardiology, Neurology, Cosmetic Surgery Delivery Mode: Intravenous, Local Injection, Intra-articular, Surgical End User: Hospitals, Research Institutes, Clinics, Laboratories |
| Companies Covered | Cytori Therapeutics, Mesoblast Ltd., Tissue Genesis, BioRestorative Therapies, Celltex Therapeutics Corporation, Antria, Intrexon Corporation, Pluristem Therapeutics, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adipose Derived Stem Cell Therapy Market Strategic Shifts
Processing automation and regulatory pathway differentiation are compressing the gap between laboratory-scale expansion and clinical deployment. These shifts reconfigure competitive positioning around manufacturing scale rather than proprietary cell sourcing.
Automated Celution systems are automating stromal vascular fraction isolation workflows across Japanese and European clinics. Orthopedic surgical centers adopt these platforms at accelerated pace to reduce technician labor intensity. The technology is automating batch-to-batch consistency controls that previously required manual oversight, compressing quality assurance timelines.
The PMDA operates under Japan's Act on Regenerative Medicine Safety, creating conditional approval pathways that accelerate commercialization for qualified cell therapy facilities. This regulatory architecture enables earlier revenue generation contingent on post-market surveillance commitments. Japanese orthopedic and cardiology segments respond by front-loading manufacturing capacity ahead of full approval.
Intra-articular injection procurement bifurcates sharply from surgical implantation as buyers unbundle service contracts from device supply. Orthopedic clinics in the United States negotiate direct reagent sourcing agreements that displace bundled processing services. This pattern concentrates most visibly in high-volume sports medicine centers where procedure volume justifies in-house laboratory investment.
Adipose Derived Stem Cell Therapy Market Segmentation
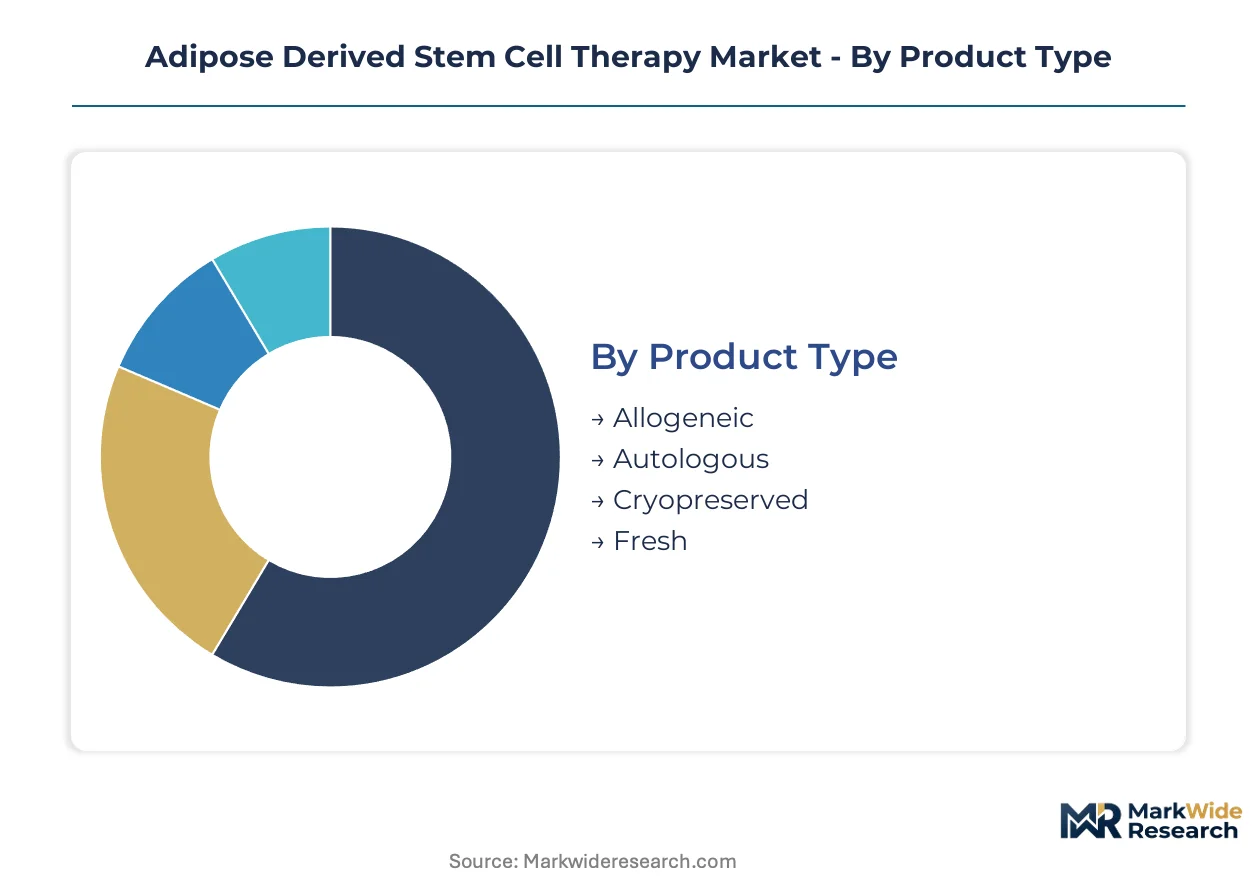
Adipose derived stem cell therapy segments fracture across preparation methodology, clinical application, and care setting. Procurement patterns diverge sharply between autologous point-of-care processing and centralized allogeneic manufacturing.
Product Type:
Buyers differentiate by immunogenicity tolerance, shelf-life requirements, and processing infrastructure investment.
- Autologous:Patient-specific preparations eliminate rejection risk through lipoaspirate harvest and same-day processing. Orthopedic clinics in the United States deploy these formats for sports medicine protocols where regulatory enforcement discretion permits minimally manipulated workflows.
- Allogeneic:Off-the-shelf cryopreserved products enable acute intervention timelines impractical for autologous harvest. Cardiology applications in Japan leverage METI-funded cell banking infrastructure to secure standardized donor pools.
- Cryopreserved:Extended shelf-life formats trade viability degradation for logistical flexibility in multi-site hospital networks.
- Fresh:Immediate-use preparations maximize cell viability for surgical implantation workflows requiring operating room turnaround compression.
Volume sits with autologous formats; growth tilts toward allogeneic platforms.
Application:
Revenue concentration tracks procedure reimbursement rates and regulatory pathway clarity.
- Orthopedics:Intra-articular injection protocols for osteoarthritis drive procedural volume through United States sports medicine centers. The FDA's regenerative medicine advanced therapy designation accelerates clinic-laboratory business model expansion in this segment.
- Cardiology:Acute myocardial infarction interventions demand allogeneic formats with validated potency assays. Japanese facilities front-load manufacturing capacity under PMDA conditional approval frameworks.
- Neurology:Blood-brain barrier penetration challenges constrain delivery mode selection to intravenous or intrathecal routes.
- Cosmetic Surgery:Aesthetic applications face narrower reimbursement coverage, concentrating demand in private-pay clinic networks.
Procedure volume clusters in orthopedics; margin expansion concentrates in cardiology.
Delivery Mode:
Site-of-care capabilities and anatomical target dictate equipment and technician requirements.
- Intra-articular:Image-guided injection systems dominate osteoarthritis treatment with ultrasound or fluoroscopy assistance. United States orthopedic clinics negotiate direct reagent sourcing to displace bundled processing services.
- Surgical:Open implantation commands premium positioning in complex soft-tissue reconstruction requiring operating room integration with automated Celution systems.
- Intravenous:Systemic delivery routes suit immunomodulation protocols with lower anatomical precision demands.
- Local Injection:Subcutaneous or intramuscular administration supports cosmetic and peripheral vascular applications.
Intra-articular captures outpatient volume; surgical commands inpatient margin pools.
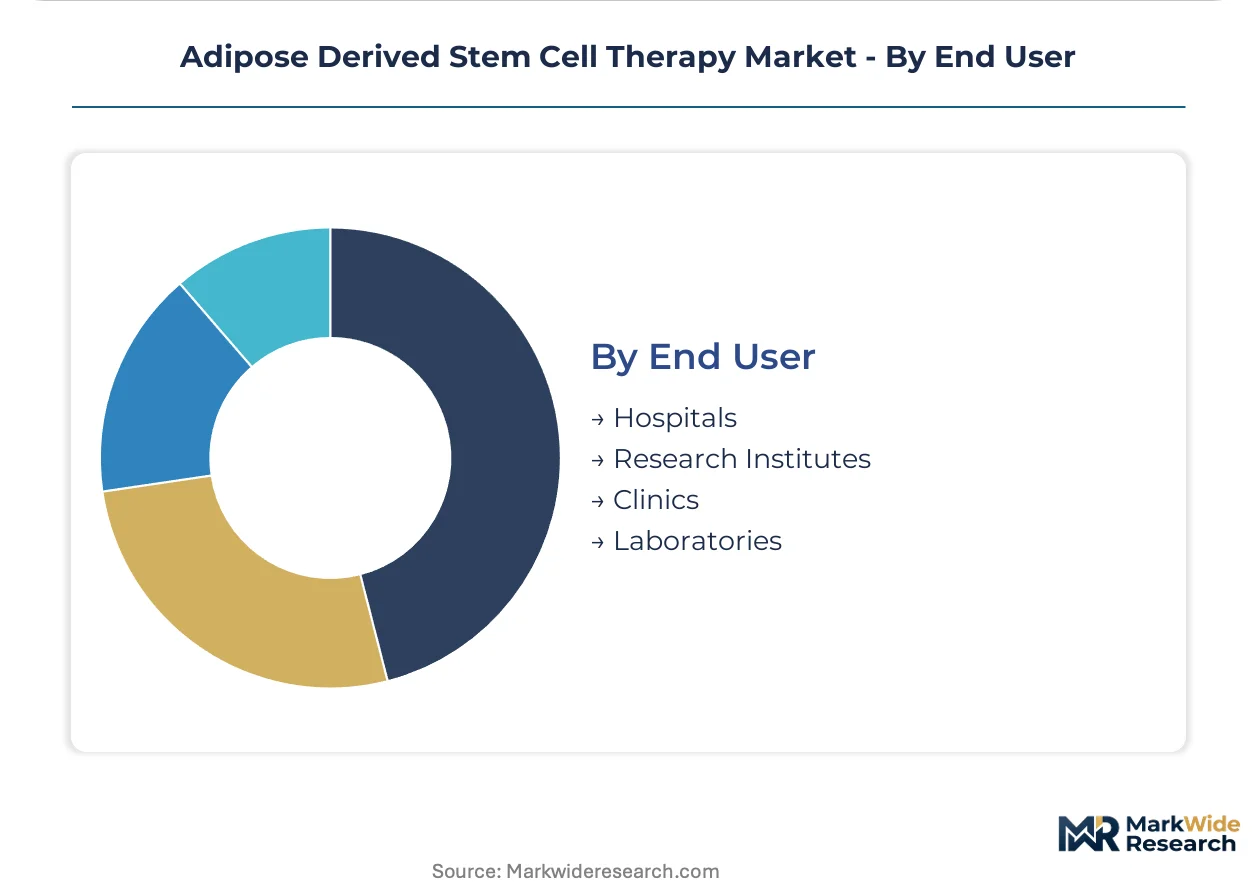
End User:
Capital intensity and regulatory licensing create tiered market access barriers.
- Clinics:Ambulatory surgical centers and orthopedic specialty practices drive point-of-care processing adoption. United States sports medicine protocols expand procurement of in-house laboratory equipment.
- Hospitals:Integrated health systems leverage centralized bioreactor capacity for allogeneic product distribution across multiple sites.
- Research Institutes:Academic medical centers conduct early-phase trials under FDA investigational new drug protocols.
- Laboratories:Contract processing facilities serve mid-tier clinics lacking cleanroom infrastructure or trained technician pools.
Clinics lead procedure count; hospitals anchor allogeneic volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lipoaspirate tissue sourcing clusters in United States metropolitan surgical centers, Japanese regenerative medicine hubs, and South Korean bioreactor manufacturing zones. Regulatory pathway differentiation across these geographies fragments commercialization timelines and capital deployment patterns.
United States
Orthopedic clinics in Texas and Florida drive procedural volume through sports medicine protocol expansion. The FDA's regenerative medicine advanced therapy designation compresses clinical trial timelines for qualified cell therapy facilities. Boston and San Diego anchor biotechnology clusters where Celution system deployments concentrate.
Japan
METI funding supports adipose-derived cell banking infrastructure that enables standardized donor pool development. The PMDA operates under the Act on Regenerative Medicine Safety, creating conditional approval pathways that accelerate commercialization. Tokyo and Osaka metropolitan areas host qualified therapy facilities front-loading manufacturing capacity.
South Korea
Bioreactor manufacturing capacity for stromal vascular fraction isolation equipment restructures regional supply dynamics. The MFDS regulates cell therapy products under advanced biopharmaceutical frameworks that align with international standards. Seoul Capital Area clusters cleanroom infrastructure serving export markets.
Germany
Academic medical centers in Bavaria and Baden-Württemberg conduct early-phase trials under EMA investigational protocols. The EMA's CAT committee imposes centralized ATMP assessments that delay market entry for minimally manipulated products. Frankfurt Rhine-Main biotech corridor attracts contract processing facility investment.
United Kingdom
Private-pay clinic networks in London concentrate demand for cosmetic surgery applications with narrower reimbursement coverage. The MHRA operates post-Brexit regulatory frameworks that diverge from EMA centralized procedures. Cambridge life sciences cluster supports laboratory-scale expansion protocol development.
Adipose Derived Stem Cell Therapy Market Competitive Environment
Global majors compete with regional champions across processing technology and regulatory pathway access. The vendor base organizes around three tiers: integrated bioreactor manufacturers, specialized cell therapy developers, and upstream reagent suppliers. Two dominant competitive moves define current positioning: strategic partnerships between device manufacturers and clinic networks, and geographic expansion into Japanese conditional approval markets.
Within the integrated processing systems tier, Cytori Therapeutics and Thermo Fisher Scientific occupy anchor positions. Cytori Therapeutics exemplifies the proprietary device archetype through Celution system deployments. Thermo Fisher Scientific represents upstream supply chain control over laboratory-scale expansion protocols. Mesoblast Ltd. sits within the allogeneic off-the-shelf platform segment.
| Leading Market Players |
|---|
| Cytori Therapeutics |
| Mesoblast Ltd. |
| Tissue Genesis |
| BioRestorative Therapies |
| Celltex Therapeutics Corporation |
| Antria |
| Intrexon Corporation |
| Pluristem Therapeutics |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Enzymatic processing reagent costs flow from South Korean bioreactor manufacturers through three pricing tiers: bundled Celution system contracts at premium positioning, direct reagent sourcing for high-volume United States orthopedic clinics, and economy-grade mechanical dissociation kits for price-constrained ambulatory centers.
Pricing Analysis
Service bundling separates premium-tier surgical implantation packages from unbundled intra-articular injection procurement at United States sports medicine centers. Three-tier pricing structure across premium, standard, and economy levels tracks processing automation intensity, with FDA regenerative medicine advanced therapy designation status commanding brand premiums. Price erosion runs through economy mechanical dissociation formats as South Korean equipment imports compress capital recovery timelines. Hospital systems demonstrate lowest price sensitivity due to centralized bioreactor infrastructure, while independent cosmetic surgery clinics operate at highest sensitivity with narrow reimbursement coverage.
Supply Chain Analysis
Trained cell processing technician scarcity in South Korea and Japan constrains bioreactor manufacturing throughput for stromal vascular fraction isolation equipment. Geographic supply concentration clusters in South Korea for automated processing systems, the United States for lipoaspirate tissue sourcing, and Japan for METI-funded cell banking infrastructure. Raw material dependencies center on collagenase enzymes, clinical-grade culture media, and cryopreservation dimethyl sulfoxide stocks. Single-source vulnerability sits with proprietary Celution consumable cartridges. Distribution runs through direct device manufacturer partnerships with qualified therapy facilities, supplemented by contract processing laboratories serving mid-tier clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated Celution processing systems are displacing manual stromal vascular fraction isolation workflows, compressing technician labor requirements and reshaping capital deployment patterns across clinic-laboratory facilities.
For Market Incumbents: Anchor manufacturing scale advantages through backward integration into collagenase enzyme supply chains, defending against emerging mechanical dissociation entrants. Expand bioreactor capacity in South Korea's Seoul Capital Area to capture export demand from Japanese conditional approval markets. Prioritize technician training program certification investments that lock in switching costs at United States orthopedic clinic networks. For New Entrants and Emerging Players: FDA regenerative medicine advanced therapy designation in the United States opens a window for specialized contract processing facilities serving mid-tier clinics lacking cleanroom infrastructure. Target cosmetic surgery applications in United Kingdom private-pay networks where reimbursement constraints limit incumbent bundling power. Pursue white-label reagent sourcing agreements with high-volume sports medicine centers seeking to displace bundled service contracts. For Investors and Strategic Acquirers: PMDA conditional approval pathway activations in Japan are the leading indicator that manufacturing capacity front-loading will accelerate revenue generation timelines for qualified facilities. Long-term viability favors integrated platform developers with proprietary device-consumable ecosystems over pure-play cell banking operations. Monitor METI funding commitment renewals as the inflection signal for Japanese infrastructure investment sustainability. Target acquisition archetypes: automated processing system specialists with regulatory pathway expertise in multiple jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses clinical trial timelines for cell-based treatments. |
| Manufacturing Scale-Up | South Korean bioreactor capacity expansion restructures stromal vascular fraction isolation supply dynamics. |
| Strategic Partnership | Celution system deployments with Japanese qualified therapy facilities accelerate conditional approval market entry. |
| Backward Integration | Upstream control over collagenase enzyme supply chains defends margin position against mechanical dissociation substitutes. |
| Geographic Expansion | United States sports medicine protocol expansion drives point-of-care processing system adoption in Texas and Florida. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cell processing technicians, orthopedic clinic laboratory directors, regulatory affairs specialists at device manufacturers, and hospital procurement managers. Secondary validation drew from FDA 510(k) submissions, PMDA conditional approval notices, METI funding disbursement records, and South Korean MFDS biopharmaceutical framework updates. Bottom-up procedure volume estimates triangulated against top-down market sizing from equipment installation databases.
Segmentation granularity modeled preparation methodology at the autologous-allogeneic-cryopreserved-fresh level, application at orthopedic-cardiology-neurology-cosmetic resolution, and delivery mode through intra-articular-surgical-intravenous-local injection taxonomy. Geographic clusters tracked United States metropolitan surgical centers, Japanese regenerative medicine hubs, and South Korean bioreactor manufacturing zones. CAGRs derived from equipment shipment trajectories, procedure reimbursement rate evolution, and regulatory pathway timeline compression factors across the projection horizon.
Caveats apply where PMDA conditional approval pathway modifications, FDA enforcement discretion narrowing on minimal manipulation, or METI funding discontinuation could materially shift the outlook. Forecasts reflect assumptions regarding technician training pipeline expansion and cryopreservation viability protocol standardization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market